
 Middle East and Africa Facility Management Market | 2026-2036
Middle East and Africa Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Facility Management Market Foresight
A shortage of certified FM engineers and bilingual technical supervisors is redrawing competitive boundaries across the Middle East and Africa. Sodexo leverages its integrated service platforms to anchor large healthcare and education contracts in North Africa. CBRE competes through technology-led asset management, while EFS Facilities Services Group specializes in hard FM delivery across the UAE's commercial tower stock.
Facility management encompasses the operational coordination of built environments through planned maintenance, energy systems oversight, and occupant services management, typically governed by SLA frameworks measuring uptime, response times, and energy consumption per square meter. Its primary purpose is preserving asset value while ensuring regulatory compliance and occupant productivity. Hard maintenance and security services dominate current contract value, while IoT Solutions and Building Automation represent the fastest-expanding technology categories as owners prioritize predictive asset management. Energy Management applications are maturing in the UAE and Saudi Arabia, where green building mandates intensify.
Saudi Arabia's Saudi Building Code and the UAE's Estidama Pearl Rating System shape FM procurement by embedding energy and water efficiency benchmarks into lease and operations contracts. South Africa's National Building Regulations and Egypt's new construction quality frameworks add compliance layers for cross-border operators. Stakeholders must decide whether to build in-house digital capabilities or partner with specialized PropTech vendors as regulatory thresholds tighten.
Market Dynamics
Energy code enforcement across the Gulf Cooperation Council is compressing contract renewal cycles as landlords scramble to retrofit aging commercial stock before compliance deadlines hit. This regulatory pressure is redrawing vendor selection criteria toward technology-enabled operators.
Growth Catalysts
- Net-zero building mandates:Saudi Arabia's Saudi Building Code and the UAE's Estidama Pearl Rating System embed energy efficiency benchmarks into lease contracts, forcing asset owners to upgrade FM procurement standards.
- Healthcare expansion:Hospital construction pipelines across Saudi Arabia and the UAE are generating multi-year outsourced FM contracts with stringent SLA frameworks.
- Smart building automation:IoT-enabled predictive maintenance platforms are penetrating commercial tower portfolios as landlords seek operational cost compression.
Market Restraints
- Certified engineer scarcity:The shortage of bilingual technical supervisors and FM engineers with regional certification limits contract scalability for mid-tier operators.
- Hard FM equipment import dependency:HVAC and building automation hardware concentrates in European and East Asian supply bases, exposing operators to currency volatility and extended lead times.
- Cross-border licensing friction:Egypt's new construction quality frameworks and South Africa's National Building Regulations create compliance layering costs for multi-country operators.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya's commercial real estate sectors lack integrated FM platforms, presenting first-mover advantages for technology-capable entrants.
- Energy management specialization:Green building mandates in the UAE and Saudi Arabia are maturing demand for dedicated energy optimization services separate from general maintenance contracts.
- PropTech partnership models:FM operators can avoid in-house digital development costs by aligning with specialized building analytics vendors as regulatory thresholds tighten.
Industry Challenges
- Technical workforce gaps:Recruitment pipelines for certified FM engineers and bilingual supervisors lag contract growth, forcing wage inflation and project delays.
- Legacy system integration:Retrofitting IoT sensors and automation platforms into 1990s-era building infrastructure requires costly custom engineering and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Facility Management Market |
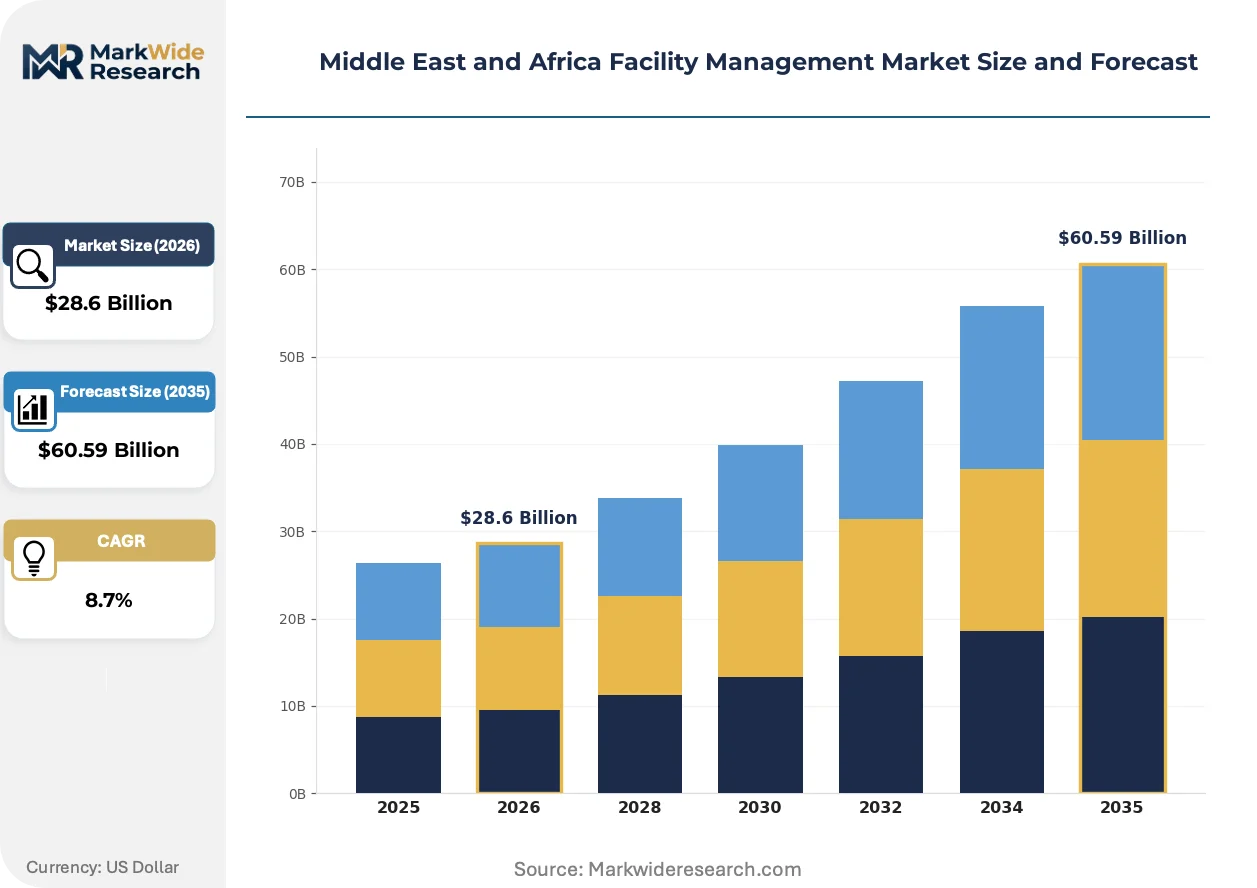
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Commercial, Residential, Industrial, Educational Technology: IoT Solutions, Building Automation, Energy Management, CMMS Application: Health Facilities, Office Spaces, Retail Outlets, Government Buildings |
| Companies Covered | Sodexo, Inc., CBRE, EFS Facilities Services Group, Al Yamama Group, ISS, Emrill Services LLC, G4S, EMCOR Facilities Services, Farnek Services LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Facility Management Market Shifts & Advancements
Digital infrastructure is penetrating FM service delivery faster than workforce adaptation can match, creating a capability gap that rewards early technology adopters. Three shifts are compressing traditional operating models.
Predictive maintenance algorithms leveraging equipment sensor data are supplanting scheduled preventive maintenance in premium commercial portfolios. Large landlords in Dubai and Riyadh are piloting these platforms to reduce HVAC downtime. The shift is compressing margins for traditional time-and-materials contractors unable to demonstrate uptime guarantees.
The UAE's Estidama Pearl Rating System and Saudi Arabia's Saudi Building Code are tightening water and energy efficiency benchmarks annually. Asset managers now embed these metrics into FM SLA frameworks with penalty clauses. Commercial tower operators in Abu Dhabi and Jeddah are responding by splitting energy management into specialized subcontracts.
Hospital and university procurement teams are unbundling integrated FM contracts into discrete hard services, soft services, and energy management lots. This fragmentation favors niche specialists over full-service operators. The pattern is most visible in Saudi Arabia's healthcare expansion, where Sodexo and EFS compete for separated security and maintenance lots rather than bundled awards.
Middle East and Africa Facility Management Market Segmentation
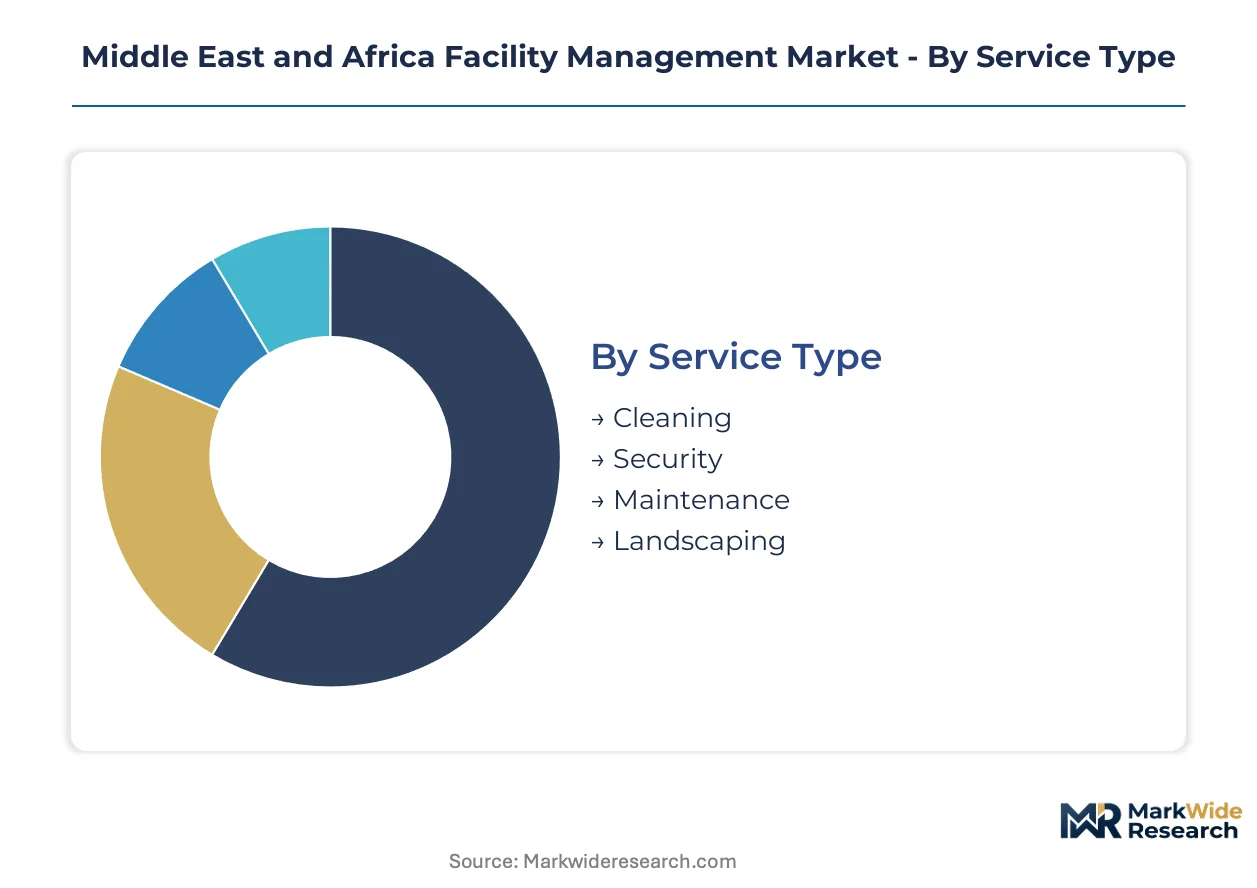
Facility management procurement across the Middle East and Africa fragments along service intensity, asset complexity, and regulatory exposure. Contract structures vary sharply between hard FM disciplines governed by Saudi Building Code mandates and soft services driven by occupant experience metrics.
Service Type:
Saudi Arabia's energy code enforcement and the UAE's Estidama Pearl Rating System impose distinct compliance burdens across service categories, reshaping vendor qualification requirements.
- Cleaning:Specialized healthcare sanitation protocols dominate contract value in Saudi hospital expansions, with HEPA filtration and infection control certification now mandatory for intensive care facilities. Dubai's commercial tower operators bundle cleaning with indoor air quality monitoring to meet WELL Building standards.
- Security:Biometric access control and integrated surveillance systems anchor multi-year contracts at UAE government complexes and Saudi Aramco facilities. Bilingual supervisor scarcity limits scalability for mid-tier operators pursuing these high-margin engagements.
- Maintenance:Hard FM delivery concentrates in Dubai's commercial stock and Riyadh's healthcare infrastructure, with HVAC and electrical systems commanding premium pricing due to European equipment import dependency.
- Landscaping:Water-efficient irrigation mandates under UAE and Saudi green building codes drive demand for xeriscaping and smart soil moisture systems at premium residential compounds.
Maintenance handles the majority of throughput; Security is expanding most quickly on share.
End User:
Cost tier differentiation separates trophy asset operators from volume-driven residential managers across the Gulf Cooperation Council corridor.
- Commercial:Dubai International Financial Centre and Riyadh King Abdullah Financial District towers demand integrated hard and soft FM with IoT-enabled SLA dashboards. Predictive maintenance clauses now standard in Class A lease agreements.
- Healthcare:Saudi Arabia's hospital construction pipeline generates outsourced FM contracts with 99.9% uptime guarantees and specialized medical gas system maintenance. Jeddah and Riyadh health clusters concentrate demand.
- Residential:Gated compounds in Abu Dhabi and Jeddah prioritize concierge-integrated FM, with energy management subcontracts splitting from general maintenance as Estidama enforcement tightens.
- Industrial:Saudi petrochemical zones and UAE free trade areas require hazardous material handling certification and 24/7 emergency response capabilities.
Commercial absorbs the largest contract volume; Healthcare climbs the fastest as Saudi Vision 2030 execution accelerates.
Technology:
Application maturity varies sharply between predictive platforms piloted in Dubai commercial stock and legacy CMMS deployments dominating African markets.
- IoT Solutions:Sensor networks for HVAC and lighting optimization penetrate Abu Dhabi and Riyadh premium portfolios. Equipment downtime prediction algorithms compress operating margins for traditional time-and-materials contractors.
- Building Automation:Integrated BMS platforms anchor FM procurement at UAE government buildings and Saudi healthcare facilities, with commissioning complexity delaying retrofit timelines in 1990s-era infrastructure.
- Energy Management:Dedicated subcontracts split from general maintenance as Saudi Building Code and Estidama benchmarks tighten annually, with penalty clauses now embedded in commercial tower SLAs.
- CMMS:Work order digitization lags in North African and sub-Saharan markets where paper-based preventive maintenance schedules still dominate mid-tier commercial stock.
Building Automation captures the dominant technology spend; Energy Management is gaining share fastest as regulatory thresholds escalate.
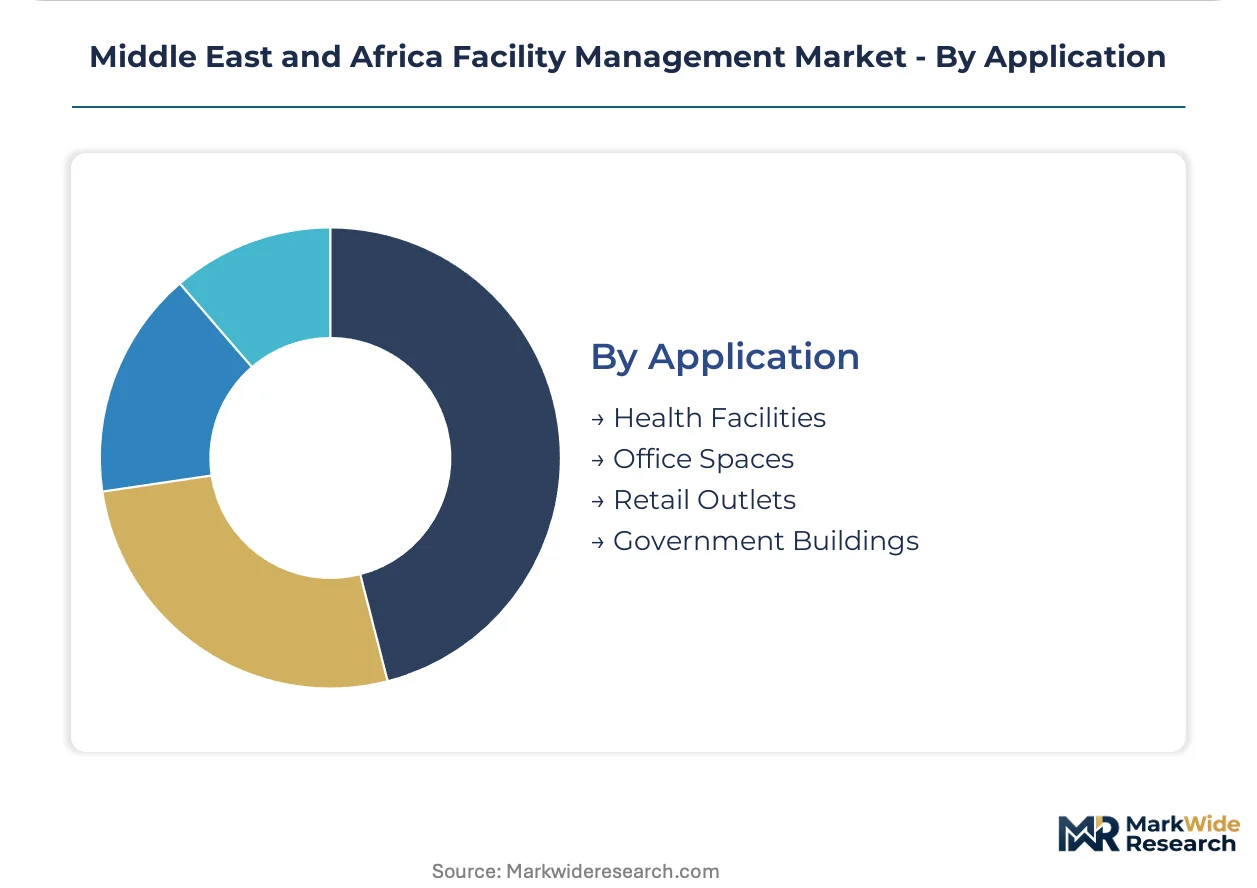
Application:
Geographic concentration within the Gulf Cooperation Council defines deployment patterns, with health and government segments commanding premium pricing due to compliance intensity.
- Health Facilities:Saudi Arabia's hospital expansion and UAE medical city developments drive multi-year integrated FM contracts with stringent infection control and medical equipment maintenance SLAs.
- Office Spaces:Dubai and Riyadh commercial towers unbundle services into discrete hard FM, soft FM, and energy management lots, favoring niche specialists over full-service operators.
- Retail Outlets:Mall operators in Abu Dhabi and Jeddah prioritize customer-facing cleanliness and HVAC reliability during peak summer loads, with shorter contract cycles than commercial office portfolios.
- Government Buildings:UAE federal and Saudi ministry facilities demand security-cleared personnel and compliance with national procurement frameworks, creating barriers for non-GCC operators.
Office Spaces generate the broadest contract base; Health Facilities show the steepest expansion trajectory as Saudi healthcare infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP and SFDA enforcement across the UAE and Saudi Arabia anchor regulatory frameworks reshaping FM procurement standards. Energy code compliance deadlines compress contract renewal cycles as landlords retrofit aging commercial stock. Healthcare infrastructure expansion concentrates demand in Gulf Cooperation Council urban corridors.
United Arab Emirates
Abu Dhabi's Estidama Pearl Rating System mandates annual energy efficiency benchmarks in commercial tower SLAs. Dubai International Financial Centre landlords pilot predictive maintenance platforms to meet uptime guarantees. Federal procurement frameworks at UAE government complexes favor security-cleared operators with integrated hard and soft FM capabilities.
Saudi Arabia
Riyadh's hospital construction pipeline generates multi-year outsourced contracts with 99.9% uptime requirements. The Saudi Building Code embeds water and energy metrics into lease agreements, forcing asset owners toward specialized energy management subcontracts. Jeddah health clusters concentrate medical gas system maintenance demand.
South Africa
National Building Regulations create compliance layering costs for cross-border FM operators entering industrial zones. Johannesburg commercial stock retains legacy CMMS deployments, delaying IoT sensor retrofit timelines. Cape Town's premium residential compounds drive demand for water-efficient irrigation systems under municipal conservation mandates.
Egypt
New construction quality frameworks impose certification requirements on foreign operators pursuing Cairo healthcare and education contracts. Alexandria's port logistics facilities require hazardous material handling capabilities. Government procurement centralization favors established regional players with Arabic-language technical supervision.
Nigeria
Lagos commercial real estate lacks integrated FM platforms, presenting first-mover positioning for technology-capable entrants. Power infrastructure instability drives demand for dedicated energy management services separate from general maintenance. Abuja government complexes prioritize security-cleared personnel with bilingual supervisory capacity.
Middle East and Africa Facility Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier fragmented by service intensity and geographic licensing. Tier-one operators anchor multi-year healthcare and government contracts through compliance-heavy SLAs. Mid-tier players concentrate in single-service maintenance or security lots. Competitive positioning hinges on technology partnerships for predictive platforms and recruitment pipelines for certified bilingual engineers.
Among French-origin integrated service providers, Sodexo anchors large healthcare and education contracts in North Africa through bundled soft and hard FM delivery. CBRE represents the technology-led asset management archetype, competing via building analytics integration. EFS Facilities Services Group exemplifies the hard FM specialist model focused on UAE commercial tower portfolios. These three occupy distinct positioning vectors without direct overlap in contract pursuit.
| Leading Market Players |
|---|
| Sodexo, Inc. |
| CBRE |
| EFS Facilities Services Group |
| Al Yamama Group |
| ISS |
| Emrill Services LLC |
| G4S |
| EMCOR Facilities Services |
| Farnek Services LLC |
| Others |
Supply & Pricing Matrix
The UAE's Estidama Pearl Rating System and Saudi Arabia's Saudi Building Code gate both vendor qualification and contract pricing simultaneously, as compliance certification separates premium-tier operators from price-competitive mid-market bidders across the Gulf Cooperation Council corridor.
Pricing Analysis
Contract spreads between Dubai's Class A commercial towers and Cairo's mid-tier office stock exceed threefold, with Saudi hospital FM engagements commanding premium positioning due to 99.9% uptime SLAs and medical gas system specialization. Three-tier pricing structure across premium, standard, and economy levels tracks certification density, bilingual supervisor ratios, and technology platform integration. Cost compression in the standard tier intensifies because European HVAC equipment import dependency exposes operators to currency volatility. Government and healthcare buyers demonstrate lowest price sensitivity, while Nigerian commercial landlords remain highly cost-conscious.
Supply Chain Analysis
Strategic stockpiling of critical HVAC and building automation hardware dominates procurement strategy among UAE and Saudi operators facing extended European and East Asian lead times. Manufacturing concentrates in Germany, Japan, and China for BMS controllers, variable refrigerant flow systems, and IoT sensor networks. Component dependencies rest on semiconductor chips for automation platforms, copper refrigerant lines, and specialized medical gas piping. Single-source vulnerability runs through German-engineered chiller systems. Distribution feeds from manufacturer-direct relationships with large FM operators, bypassing regional distributors for major healthcare and government contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa facility management market represents early-cycle expansion, with smart building automation penetration still below saturation across African commercial corridors and Saudi healthcare infrastructure scaling rapidly under Vision 2030 execution.
For Market Incumbents: Compound technology differentiation through predictive maintenance platform partnerships with specialized PropTech vendors, insulating contract renewal rates against emerging pure-play technology entrants. Deepen backward integration into energy management service lines as Saudi Building Code and Estidama enforcement splits these subcontracts from general maintenance awards. Prioritize recruitment pipeline investments for bilingual certified engineers, as workforce scarcity threatens margin compression across multi-year healthcare engagements. For New Entrants and Emerging Players: Differentiate on energy optimization specialization targeting Nigeria and Kenya's underpenetrated commercial real estate sectors, where integrated FM platforms remain nascent and first-mover positioning is achievable. Prioritize Lagos and Abuja office towers with dedicated power infrastructure services addressing grid instability pain points. Pursue PropTech partnership routes rather than in-house digital development to accelerate market entry without capital-heavy platform buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap hard FM specialists holding concentrated UAE commercial tower portfolios but lacking technology integration capabilities. Five-to-ten year viability hinges on successful digital transformation execution rather than geographic expansion alone. Target acquisition archetypes include Saudi-certified maintenance operators with healthcare sector exposure and established government relationships. Watch predictive maintenance SLA penetration rates in Dubai International Financial Centre and Riyadh King Abdullah Financial District as inflection indicators for technology-enabled competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| PropTech Platform Partnership | Accelerates predictive maintenance deployment without in-house R&D burden at EFS and Farnek. |
| Bilingual Engineer Recruitment Pipeline | Resolves certified supervisor scarcity constraining Sodexo's North Africa healthcare contract scalability. |
| Energy Management Subcontract Specialization | Captures value from Estidama and Saudi Building Code unbundling trends in Abu Dhabi and Riyadh towers. |
| Healthcare FM Certification Investment | Meets SFDA and MOHAP infection control mandates for Saudi hospital expansion pipelines. |
| African Market First-Mover Positioning | Secures integrated FM platform adoption ahead of technology-capable competitor entry in Lagos and Nairobi. |
Research Methodology
The analysis maps hard FM, soft FM, energy management, and technology-enabled service sub-sectors, each validated through facility directors, procurement officers at healthcare systems, commercial property asset managers, and building automation engineers. Primary interviews with UAE and Saudi FM operators, Egyptian construction quality inspectors, and South African industrial zone managers combined with secondary validation against MOHAP enforcement guidelines, Saudi Building Code documentation, Estidama Pearl Rating System technical manuals, and trade customs data for HVAC equipment imports. Bottom-up contract value aggregation and top-down market sizing triangulated outputs across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regional construction pipeline disclosures, healthcare infrastructure budget allocations, and commercial real estate transaction databases. Segmentation dimensions modeled encompass service type intensity, end-user regulatory exposure, technology application maturity, and geographic compliance framework clustering. CAGRs derived from weighted average contract renewal trajectories, equipment replacement cycles, and regulatory deadline compression effects. Forecast inputs incorporated hospital construction completion schedules and green building mandate enforcement timelines without year-specific pinning.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council infrastructure investment levels or accelerated African commercial real estate formalization would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, equipment import lead time stability, and certified workforce pipeline development. Revision becomes warranted when smart building automation penetration rates in premium commercial portfolios cross thresholds indicating technology-enabled competitive displacement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Bulgaria Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Finland Facility Management Market