
 Argentina Facility Management Market | 2026-2036
Argentina Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Facility Management Market Outlook
Integrated service-level specifications are redrawing competitive boundaries in Argentina's facility management sector. CBRE Group, Inc. leverages its international platform to anchor premium corporate office contracts in Buenos Aires. ISS Facility Services Argentina S.A. competes through specialized cleaning and security protocols for healthcare and educational clients. Sodexo Argentina S.A. differentiates via food-service-integrated facility solutions that extend beyond conventional maintenance scopes.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, catering) to ensure operational continuity of built environments, typically governed by SLA response-time thresholds of 2-4 hours for critical systems and 24-48 hours for routine maintenance. Maintenance and cleaning services dominate current revenue pools due to mandatory compliance requirements across Argentina's commercial building stock, while IoT Solutions and Building Automation Systems represent the fastest-expanding technology dimension as property managers deploy sensor networks for predictive equipment monitoring. Energy Management Systems command premium pricing tiers where utility cost reduction justifies capital outlay.
Argentina's national building code enforcement and municipal energy efficiency ordinances in Buenos Aires and Rosario shape compliance-driven service procurement, with the Secretaría de Energía mandating consumption audits for public buildings above 500 square meters. The Superintendencia de Riesgos del Trabajo (SRT) imposes occupational safety standards that elevate liability costs for in-house facility operations, accelerating outsourced contract migration. Stakeholders must monitor regulatory harmonization between provincial building codes and federal energy efficiency frameworks to anticipate compliance cost trajectories.
Market Dynamics
Argentina's facility management sector is compressing toward integrated service delivery as Buenos Aires municipal energy audits and SRT occupational safety mandates force property owners to consolidate vendor relationships under single accountability frameworks.
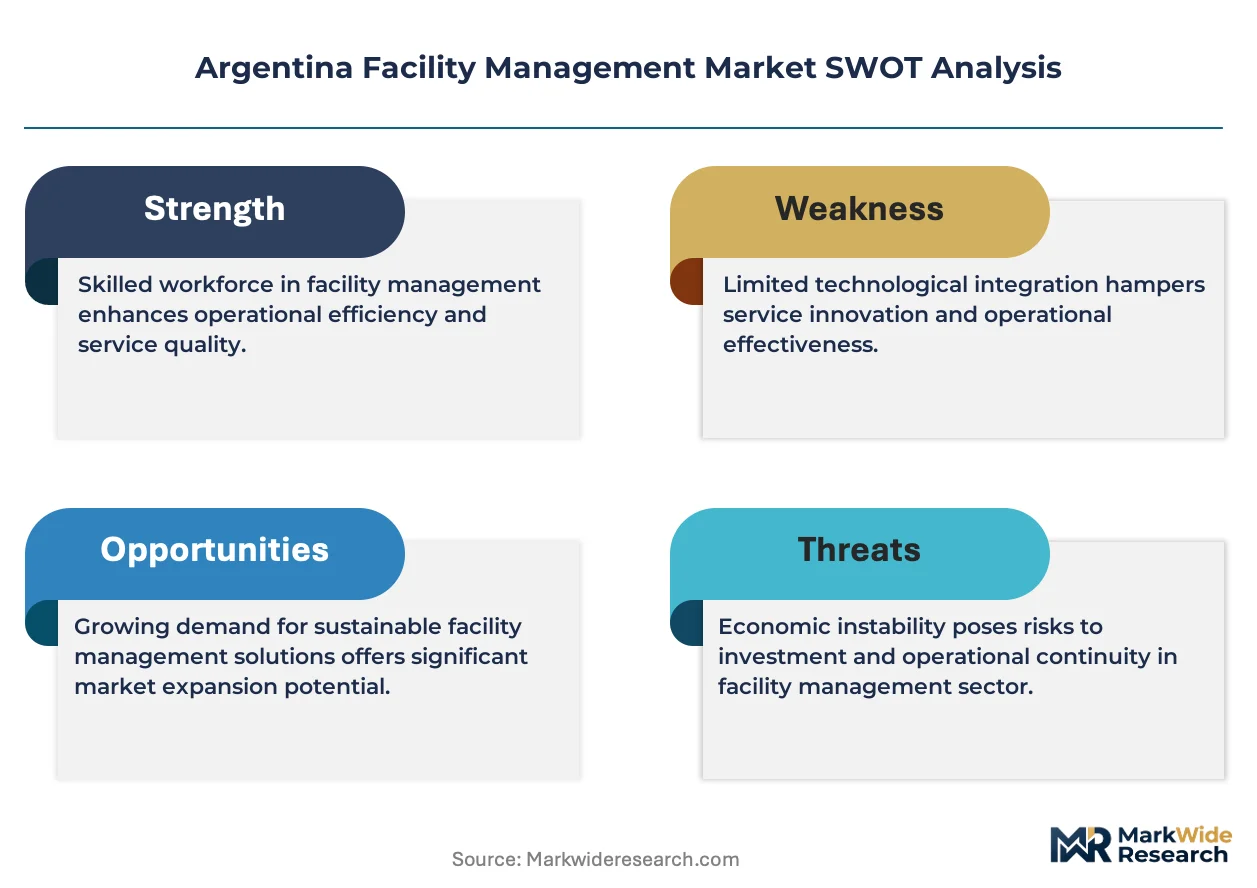
Growth Catalysts
- Buenos Aires Energy Efficiency Ordinance:Mandatory consumption audits for public buildings above 500 square meters are generating systematic retrofit procurement cycles.
- Healthcare infrastructure expansion:Specialized cleaning and security protocols for hospitals and clinics are extending contract scopes beyond conventional maintenance.
- Predictive maintenance platforms:IoT sensor networks for equipment monitoring are reducing unplanned downtime in aging commercial building stock.
Market Restraints
- Imported component dependency:Building automation hardware and specialized MEP equipment face currency volatility and import licensing delays.
- Provincial regulatory fragmentation:Divergent building code enforcement between Buenos Aires, Córdoba, and Rosario jurisdictions inflates compliance overhead.
- Skilled technician scarcity:Certification requirements for HVAC and electrical systems exceed available trained workforce supply in secondary cities.
Strategic Opportunities
- Rosario industrial corridor:Manufacturing and logistics facilities remain underpenetrated by integrated facility service providers relative to Buenos Aires saturation.
- Food-service convergence:Catering-integrated facility solutions extend contract value beyond hard and soft maintenance boundaries.
- Federal energy efficiency harmonization:Anticipated alignment between provincial codes and Secretaría de Energía frameworks will standardize procurement specifications.
Industry Challenges
- Legacy system integration:Aging mechanical infrastructure in Buenos Aires commercial stock requires bespoke sensor retrofitting rather than plug-and-play automation deployment.
- SLA response-time staffing:SRT-mandated occupational safety protocols elevate liability insurance costs and constrain 24-hour coverage availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Facility Management Market |
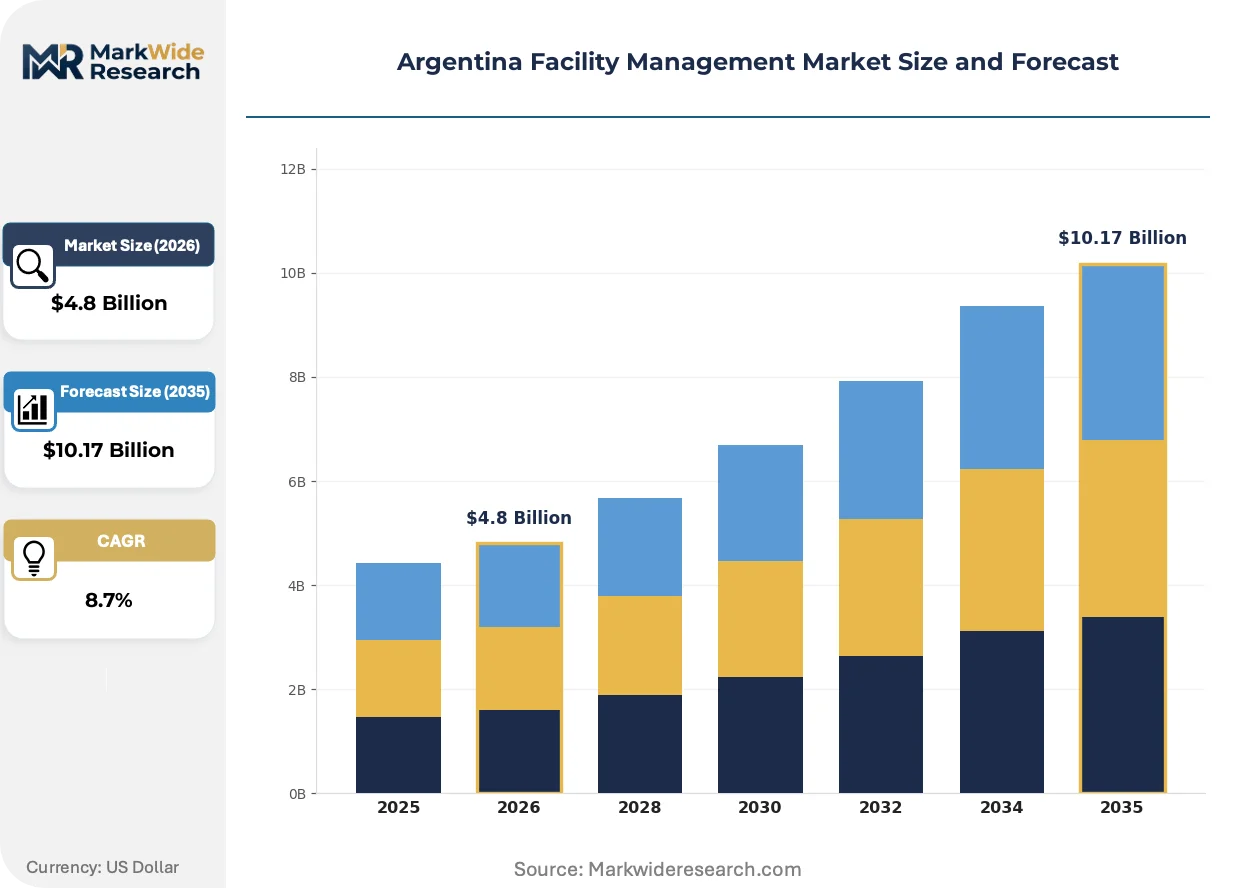
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Space Management End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Outlets Deployment Type: Onsite, Remote, Hybrid, Cloud-based Technology: IoT Solutions, Asset Management Software, Energy Management Systems, Building Automation Systems |
| Companies Covered | CBRE Group, Inc., ISS Facility Services Argentina S.A., Cushman & Wakefield Argentina, Sodexo Argentina S.A., Grupo EULEN Argentina S.A., Facility Service S.A., Plural Facility Management Services S.A., Facility Argentina S.R.L., Johnson Controls Argentina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Facility Management Market Strategic Shifts
Digital instrumentation is penetrating Argentina's building stock at accelerating velocity as property managers seek operational visibility without full infrastructure replacement.
Wireless sensor networks for predictive equipment monitoring are miniaturizing installation footprints and cost structures. Corporate office portfolios in Buenos Aires are piloting battery-powered vibration and temperature sensors on chillers and pumps. This technology is miniaturizing the capital barrier to entry for predictive maintenance, enabling mid-size property managers to access capabilities previously reserved to premium Class A assets.
Buenos Aires municipal energy efficiency ordinances are tightening audit frequency and disclosure requirements for commercial buildings above 500 square meters. Property managers must now submit verified consumption data to municipal authorities annually. Healthcare and educational facilities face the steepest compliance cost trajectories as they operate extended hours across dispersed building footprints.
Consolidated vendor relationships are displacing fragmented service procurement across Argentina's corporate real estate sector. Single-source integrated contracts covering hard services, soft services, and energy management are replacing siloed maintenance agreements. This concentration is most visible in Córdoba's expanding office market, where international tenant requirements are importing global facility management standards.
Argentina Facility Management Market Segmentation
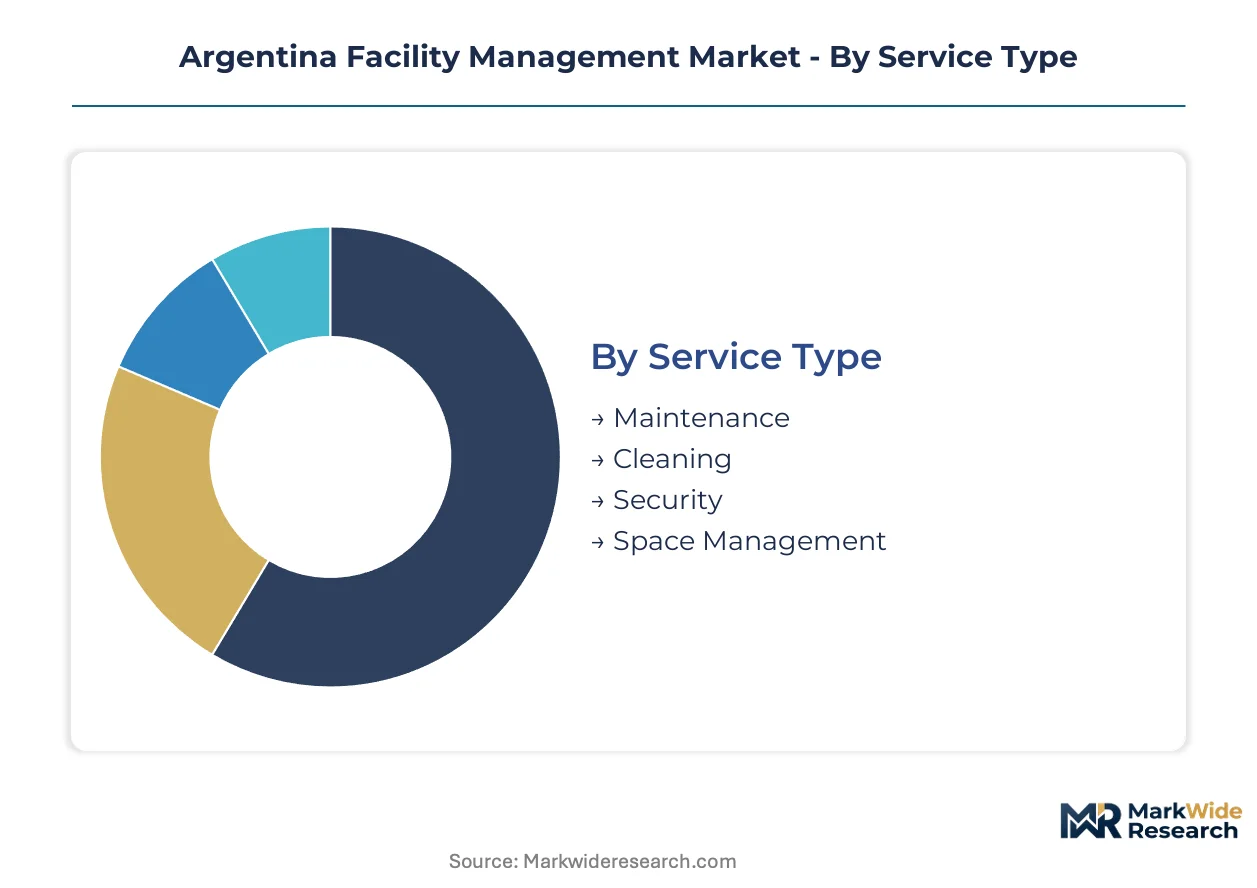
Argentina's facility management market fragments across service delivery modes, end-use verticals, and technology integration levels. Each segmentation dimension reveals distinct procurement patterns shaped by Buenos Aires regulatory density versus secondary city infrastructure maturity.
Service Type:
Geographic concentration varies sharply across service categories, with maintenance and cleaning contracts clustering in Buenos Aires corporate portfolios while security services penetrate provincial healthcare and educational facilities more evenly.
- Maintenance:Hard services encompassing mechanical, electrical, and plumbing systems governed by SRT-mandated response-time thresholds. Buenos Aires Class A office towers drive premium contract value as aging infrastructure in the metropolitan corridor requires systematic HVAC and electrical modernization to meet Secretaría de Energía consumption audit standards.
- Cleaning:Soft services spanning routine janitorial through specialized healthcare sanitation protocols. Córdoba's expanding educational and medical campus footprint is accelerating demand for infection-control-certified cleaning crews as provincial healthcare infrastructure scales.
- Security:Personnel-based and technology-augmented guarding services for commercial and institutional assets. Rosario's industrial corridor generates steady demand for perimeter security and access control integration at manufacturing and logistics facilities.
- Space Management:Workplace optimization and occupancy planning services. Corporate office portfolio rationalization in Buenos Aires is elevating space utilization analytics as hybrid work patterns persist.
Maintenance commands the established base. The steepest expansion runs through specialized cleaning protocols for healthcare compliance.
End User:
Customer-type segmentation reveals divergent procurement sophistication, with international corporate tenants importing integrated service specifications while public sector institutions navigate fragmented municipal contracting frameworks.
- Corporate Offices:Premium Class A and B commercial buildings in Buenos Aires and Córdoba. International tenant requirements are consolidating vendor relationships under single-source accountability frameworks covering hard services, soft services, and energy management.
- Healthcare Facilities:Hospitals, clinics, and diagnostic centers requiring specialized cleaning, security, and maintenance protocols. Extended operating hours and dispersed building footprints across provincial cities elevate compliance cost trajectories.
- Educational Institutions:Universities, schools, and research campuses. Public sector procurement cycles in Buenos Aires and Rosario are lengthening contract award timelines despite steady facility modernization budgets.
- Retail Outlets:Shopping centers, big-box stores, and high-street commercial premises. Foot traffic volatility and seasonal demand patterns favor flexible staffing models over fixed-cost in-house operations.
Corporate offices concentrate vendor consolidation momentum. Healthcare facilities are climbing the fastest on compliance-driven contract scope expansion.
Deployment Type:
Technology-enabled delivery models are gaining share fastest where property managers seek operational visibility without full infrastructure replacement, particularly in mid-size commercial assets previously excluded from premium automation tiers.
- Onsite:Traditional embedded facility teams with physical presence at client properties. Buenos Aires municipal energy audit mandates are sustaining demand for onsite technical staff capable of immediate response to consumption anomaly investigations.
- Remote:Centralized monitoring and dispatch operations leveraging digital connectivity. Currency volatility and skilled technician scarcity in secondary cities are accelerating remote service adoption for routine diagnostics.
- Hybrid:Blended models combining periodic onsite presence with remote oversight. This configuration dominates mid-market commercial assets seeking SLA compliance without premium staffing costs.
- Cloud-based:Fully digitized service delivery through software platforms and IoT integration. Battery-powered wireless sensor networks are miniaturizing capital barriers for predictive maintenance in aging Buenos Aires building stock.
Onsite deployment retains the revenue base. Cloud-based delivery is expanding most quickly through sensor miniaturization and reduced capital thresholds.
Technology:
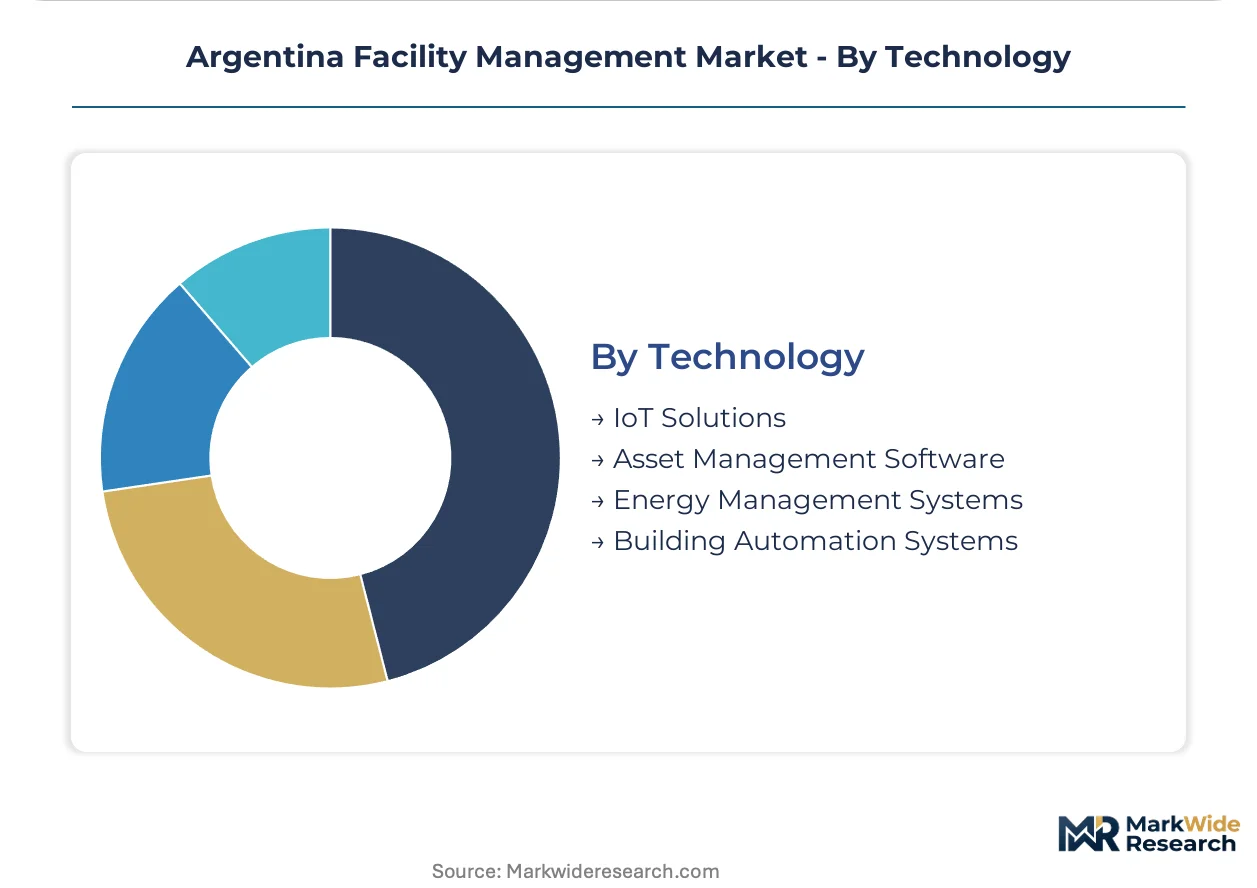
Technology segmentation stratifies by integration depth, with point solutions dominating current procurement while platform convergence defines competitive differentiation.
- IoT Solutions:Wireless sensor networks for equipment condition monitoring and environmental tracking. Vibration and temperature sensors on chillers and pumps are reducing unplanned downtime in aging commercial infrastructure.
- Asset Management Software:Computerized maintenance management systems for work order tracking and lifecycle planning. Córdoba's expanding office market is importing global CMMS standards through international tenant requirements.
- Energy Management Systems:Utility consumption monitoring and optimization platforms. Premium pricing tiers apply where verifiable cost reduction justifies capital outlay against Secretaría de Energía audit mandates.
- Building Automation Systems:Integrated control of mechanical, electrical, and environmental systems. Legacy system integration challenges in Buenos Aires commercial stock require bespoke retrofitting rather than plug-and-play deployment.
Asset management software commands the installed base. IoT solutions are gaining share fastest through wireless miniaturization and reduced installation footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's facility management sector exhibits pronounced import dependency for building automation hardware and specialized MEP components, creating currency exposure that shapes regional procurement patterns across South American markets.
Buenos Aires Metropolitan Corridor
Corporate office portfolios in Puerto Madero and Catalinas Norte are expanding outsourced maintenance contracts under international tenant specifications. The Secretaría de Energía mandates consumption audits for public buildings above 500 square meters, accelerating energy management system procurement. Class A towers in Retiro and Belgrano are deploying wireless sensor networks for predictive equipment monitoring on aging chillers and pumps.
Córdoba Province
Educational and healthcare campus expansion is driving specialized cleaning and security protocol demand across the provincial capital. The Superintendencia de Riesgos del Trabajo imposes occupational safety standards that elevate liability costs for in-house operations. Nueva Córdoba's medical district is consolidating vendor relationships under single-source accountability frameworks.
Rosario Industrial Corridor
Manufacturing and logistics facilities remain underpenetrated by integrated facility service providers relative to Buenos Aires saturation. Municipal energy efficiency ordinances mirror Buenos Aires disclosure requirements for commercial buildings above 500 square meters. The port district and surrounding industrial parks generate steady demand for perimeter security and access control integration.
Mendoza Wine Region
Tourism and hospitality infrastructure requires seasonal facility staffing models rather than fixed-cost in-house operations. Provincial building code enforcement lags federal energy efficiency frameworks, creating compliance anticipation uncertainty. Luján de Cuyo's hotel and conference center clusters are piloting hybrid deployment models combining periodic onsite presence with remote oversight.
Argentina Facility Management Market Competitive Environment
Listed leaders compete with private specialists across service integration depth, compressing the vendor landscape toward consolidated accountability frameworks. International platforms anchor premium corporate office contracts through single-source specifications covering hard services, soft services, and energy management. Three archetypes dominate: global real estate service conglomerates with integrated facility arms, specialized cleaning and security operators with healthcare certifications, and food-service-integrated providers extending beyond conventional maintenance scopes. Competitive moves concentrate on vendor consolidation through long-term integrated contracts and technology licensing partnerships for predictive maintenance platforms.
Within the international platform tier, CBRE Group, Inc. and Cushman & Wakefield Argentina occupy positions as listed real estate service providers with facility management capabilities. ISS Facility Services Argentina S.A. and Sodexo Argentina S.A. exemplify the specialized service archetype, with the former representing cleaning and security specialists and the latter anchoring food-service-integrated solutions. These four entities collectively represent the competitive poles around which provincial and local operators position for secondary market penetration.
| Leading Market Players |
|---|
| CBRE Group, Inc. |
| ISS Facility Services Argentina S.A. |
| Cushman & Wakefield Argentina |
| Sodexo Argentina S.A. |
| Grupo EULEN Argentina S.A. |
| Facility Service S.A. |
| Plural Facility Management Services S.A. |
| Facility Argentina S.R.L. |
| Johnson Controls Argentina |
| Others |
Value Chain & Pricing Dynamics
The Superintendencia de Riesgos del Trabajo certification regime gates both supplier qualification and price differentiation simultaneously. SRT-mandated occupational safety protocols create tiered compliance costs that separate certified facility operators from uncertified competitors. Corporate office tenants in Buenos Aires and Córdoba pay premiums for SRT-compliant integrated contracts covering hard services, soft services, and energy management under single accountability frameworks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term pricing structures across Argentina's facility management sector. Three-tier pricing structure across premium, standard, and economy levels separates Class A corporate towers with IoT-enabled predictive maintenance from mid-market assets with hybrid deployment and budget properties with basic onsite staffing. Price differentiation hinges on certification grade and geographic delivery cost, with Buenos Aires metropolitan corridor commanding premiums against secondary city discounts. Cost compression in the economy tier is intensifying because skilled technician scarcity elevates wage pressure while currency volatility inflates imported automation component costs. Retail outlet operators exhibit highest price sensitivity due to foot traffic volatility, while healthcare facilities show lowest sensitivity given mandatory infection-control compliance requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate domestic staffing and soft services procurement, while strategic stockpiling prevails for imported building automation hardware facing currency volatility and import licensing delays. Hardware supply concentrates in China, Germany, and the United States for HVAC controls, sensor networks, and energy management systems. Raw material dependencies span copper wiring, refrigerants, and lithium-ion battery cells for wireless sensor deployment. Single-source vulnerability runs through specialized MEP equipment where Buenos Aires property managers lack domestic alternatives. Distribution runs through direct vendor relationships with international platform providers and regional specialist networks serving provincial healthcare and educational facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's facility management sector presents a defensive-moat story anchored in regulatory entrenchment. SRT certification requirements and municipal energy audit mandates create switching costs that protect incumbent positions against price-based competition.
For Market Incumbents: Shield market position through backward integration into predictive maintenance technology licensing and captive supply of certified technician training programs. Consolidate vendor relationships in Córdoba's expanding medical district before international competitors establish footprint. Margin pressure from currency-exposed hardware imports demands accelerated remote service platform deployment to reduce onsite staffing intensity.
For New Entrants and Emerging Players: Rosario's industrial corridor under-service for integrated facility solutions presents the most penetrable white-space target. Manufacturing and logistics facilities currently rely on fragmented security and maintenance contracts without energy management integration. Target food-service convergence as entry wedge, extending catering contracts into hard services scope under single-source specifications. Municipal energy efficiency ordinance harmonization creates procurement standardization tailwind for standardized service offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based deployment sub-segments as wireless sensor miniaturization reduces infrastructure replacement requirements. Long-term viability over the mid-term projection horizon favors platform-enabled operators with recurring revenue streams over project-dependent construction affiliates. Acquisition target archetype: mid-market hybrid deployment specialists with healthcare certification and established Rosario industrial relationships. Signal to watch is federal-provincial regulatory harmonization progress, with accelerated consolidation likely upon standardized procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Platform Convergence | Single-source contracts covering hard services, soft services, and energy management reduce vendor fragmentation for Buenos Aires corporate tenants. |
| Predictive Maintenance Technology Licensing | IoT sensor networks for equipment monitoring enable mid-market property managers to access capabilities previously reserved to Class A assets. |
| Healthcare Certification Investment | Infection-control-certified cleaning crews command premium pricing as Córdoba's medical district scales provincial healthcare infrastructure. |
| Remote Service Platform Expansion | Centralized monitoring reduces skilled technician dependency in secondary cities facing workforce supply constraints. |
| Rosario Industrial Corridor Penetration | Manufacturing and logistics facilities remain underpenetrated relative to Buenos Aires saturation, creating white-space opportunity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, municipal energy audit disclosures, and industry association reports. Facility management executives, property portfolio directors, SRT compliance officers, and municipal energy planning officials provided operational perspective across Buenos Aires, Córdoba, and Rosario. Secondary validation drew from Secretaría de Energía consumption audit databases, Superintendencia de Riesgos del Trabajo certification registries, and commercial real estate leasing transaction records. Bottom-up service contract value aggregation triangulates against top-down building stock modernization spend estimates.
Segmentation dimensions modeled span service type, end-user vertical, deployment configuration, and technology integration level across the projection horizon. Hard services, soft services, and energy management systems represent core service categories, while corporate offices, healthcare facilities, educational institutions, and retail outlets define end-user demand clusters. CAGRs derive from fitted growth curves against historical contract award velocity and regulatory mandate implementation timelines. Forecast inputs incorporate SRT enforcement intensity trajectories and municipal energy audit expansion schedules.
Underlying assumptions cover regulatory harmonization progress, currency volatility bands, and skilled workforce supply elasticity, with deviation risk concentrated in import licensing disruption and provincial code fragmentation persistence. Revision becomes warranted when federal-provincial regulatory alignment crosses implementation thresholds or hardware import dependency shifts toward domestic sourcing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Cold Storage Warehouse Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Switzerland Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Austria Facility Management Market