
 Philippines Facility Management Market | 2026-2036
Philippines Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Facility Management Market Analytics
Service procurement channels in Philippine facility management is tilting toward integrated bundled contracts rather than fragmented single-service awards. CBRE Philippines leverages its international property platform to anchor premium commercial portfolios in Makati and Bonifacio Global City. Kontrac Facilities Management Services Inc. competes through specialized industrial maintenance contracts tied to Philippine Economic Zone Authority (PEZA) locators. Santos Knight Frank Inc. differentiates via landlord representation combined with technical facilities oversight.
Facility management encompasses the professional coordination of building systems, infrastructure, and support services to ensure operational continuity, occupant safety, and asset longevity across commercial, industrial, and institutional properties. Technical scope spans HVAC calibration, electrical load balancing, fire suppression testing, and integrated workplace management systems governed by Philippine National Standards for building performance. Maintenance Services commands the largest revenue pool due to mandatory preventive schedules under DPWH guidelines, while Energy Management Systems within the Technology segment shows the fastest structural ascent as power costs in the Philippines rank among Asia's highest. Cleaning Services remains mature with thin margins, though compliance with Department of Health sanitation protocols for Healthcare Facilities creates premium pricing pockets.
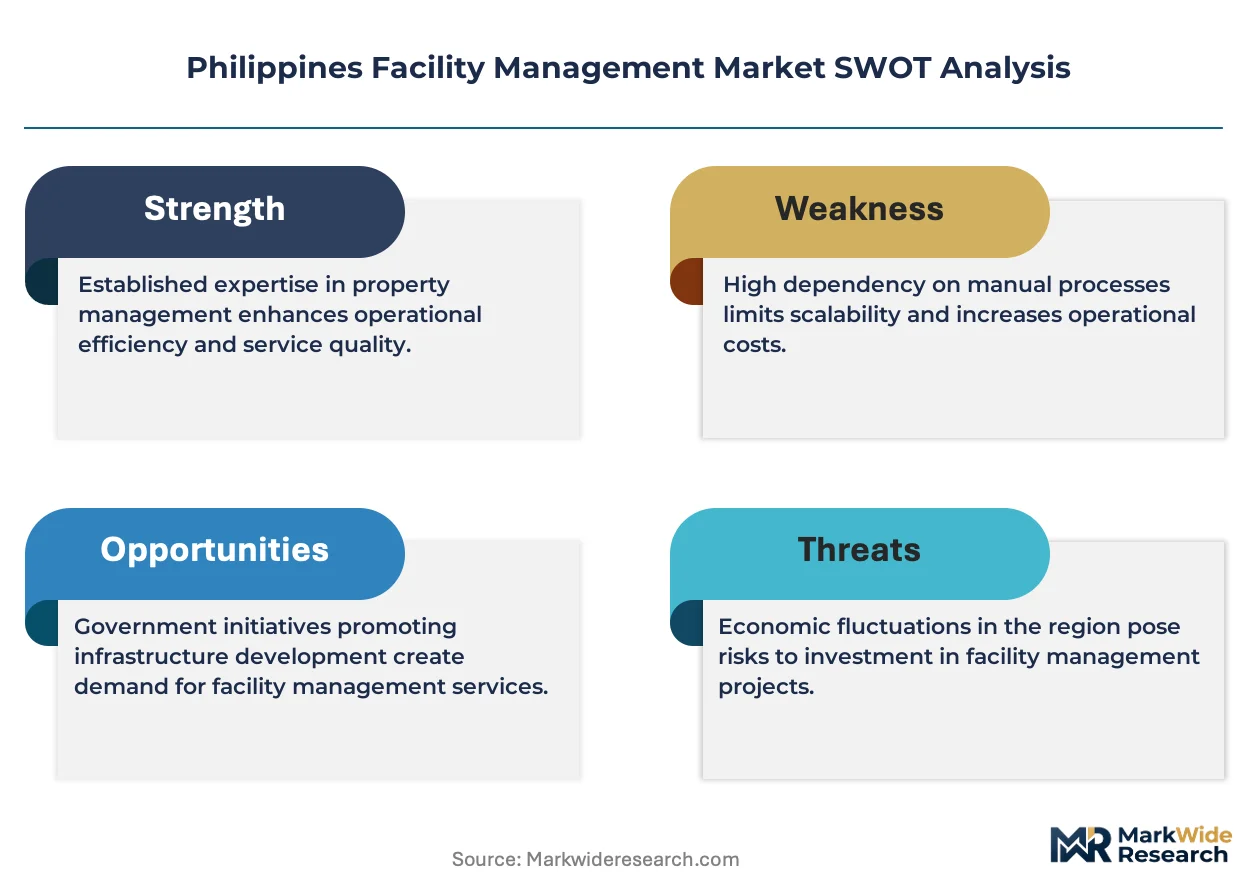
The Department of Public Works and Highways (DPWH) enforces National Building Code compliance audits that directly expand third-party facilities assessment demand, while the Department of Energy (DOE) mandates consumption benchmarking for government buildings above specific floor thresholds. Bureau of Fire Protection (BFP) inspection tightening since updated fire safety regulations now requires certified facility managers on staff for high-occupancy structures. Stakeholders must weigh capital deployment toward smart building platforms against the persistent constraint of fragmented provincial service networks outside Luzon's core corridor.
Market Dynamics
Integrated workplace management platforms are compressing service delivery timelines across Philippine commercial portfolios, forcing facility operators to consolidate previously fragmented maintenance contracts under single-source accountability structures.
Growth Catalysts
- Healthcare Facilities modernization:The Department of Public Works and Highways mandates stricter building codes for public hospital infrastructure, accelerating compliance-driven service contracts nationwide.
- PEZA industrial zones:Philippine Economic Zone Authority locators require specialized industrial maintenance, creating captive demand for technical facilities oversight within export-processing enclaves.
- Smart building convergence:Internet of Things sensor networks and cloud-based asset management systems are enabling predictive maintenance models that reduce unplanned downtime in Metro Manila commercial towers.
Market Restraints
- Power cost volatility:Philippine electricity rates rank among Asia's highest, squeezing operating margins for energy-intensive HVAC and mechanical maintenance operations.
- Provincial service fragmentation:Technical talent and certified facility managers concentrate in Luzon's core corridor, leaving Visayas and Mindanao with thin qualified vendor networks.
- Fire safety compliance friction:Bureau of Fire Protection tightened inspection protocols now require certified facility managers on staff, creating credential scarcity for high-occupancy structures.
Strategic Opportunities
- Cebu City commercial expansion:Emerging business districts outside Metro Manila present underpenetrated demand for integrated bundled contracts as regional office stock modernizes.
- Energy Management Systems:Department of Energy consumption benchmarking mandates for government buildings above specific floor thresholds create regulatory tailwind for technology deployment.
- Healthcare sanitation premium:Department of Health protocols for hospital-grade cleaning create pricing differentiation pockets within otherwise commoditized janitorial services.
Industry Challenges
- Certified technician scarcity:Bureau of Fire Protection and DPWH credential requirements outpace vocational training pipeline output, extending hiring timelines for technical roles.
- Legacy system integration:Older Metro Manila commercial buildings require costly retrofitting to accommodate integrated workplace management platforms, delaying smart building adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Facility Management Market |
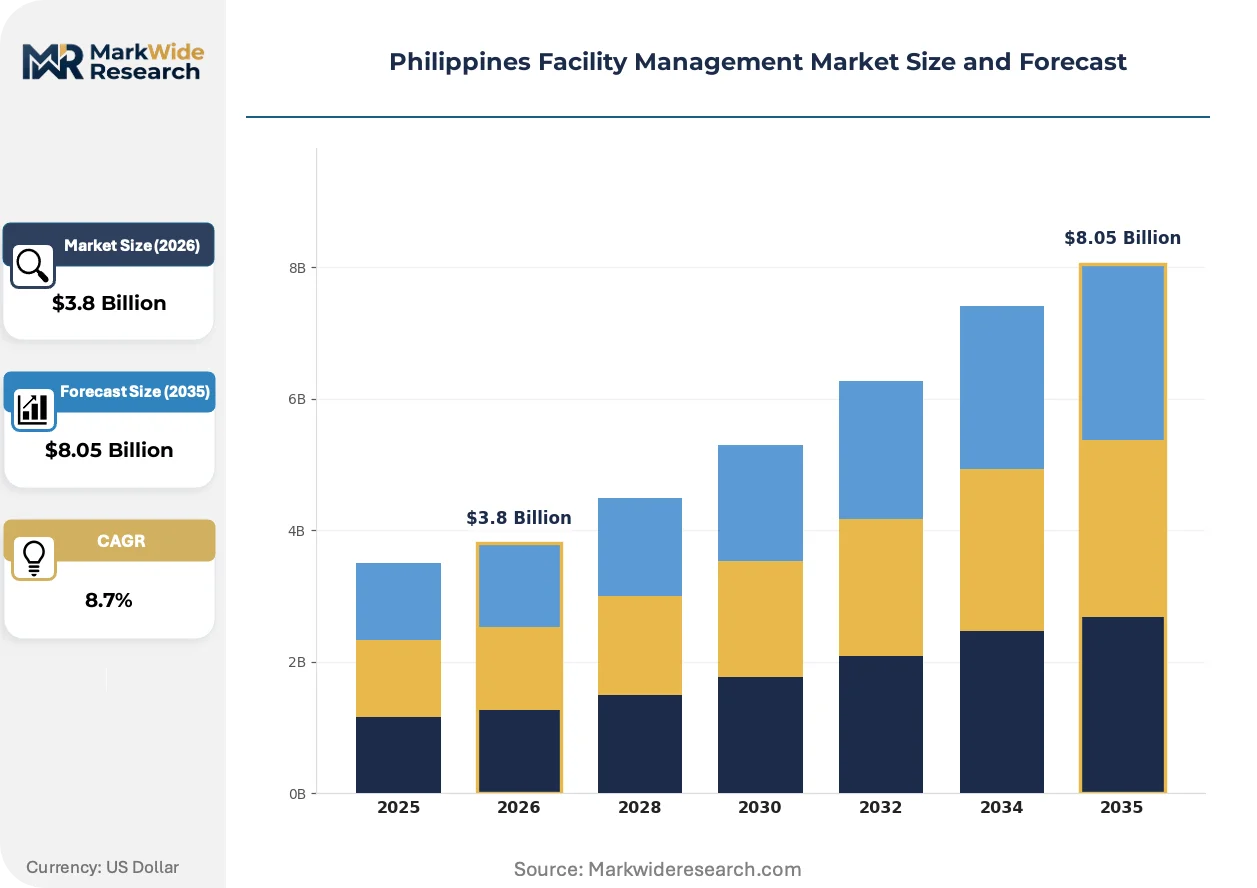
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, Landscaping Services End User: Commercial Buildings, Residential Complexes, Educational Institutions, Healthcare Facilities Technology: IoT Solutions, Automation Tools, Energy Management Systems, Building Management Software Application: Facility Operations, Cost Reduction, Compliance Management, Quality Assurance |
| Companies Covered | SGS Philippines Inc., Century Properties Management Inc., CBRE Philippines, Kontrac Facilities Management Services Inc., Mansion Maintenance Co. Inc., Servicio Filipino Inc., Santos Knight Frank Inc., Jones Lang LaSalle Inc., Meralco Industrial Engineering Services Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Facility Management Market Evolving Landscape
Digital twin technology and artificial intelligence-driven predictive analytics are reconfiguring how Philippine facility operators prioritize capital expenditure and manage asset lifecycle decisions across multi-site portfolios.
Integrated Workplace Management Systems are hybridizing building automation with real-time occupancy analytics, enabling dynamic HVAC and lighting adjustments based on actual space utilization rather than fixed schedules. Large-scale commercial developers in Makati and Bonifacio Global City are deploying these platforms to compress energy expenditure and extend mechanical equipment lifecycles. The convergence is compressing demand for standalone point solutions while elevating vendor technical certification requirements.
Department of Energy consumption benchmarking mandates for government buildings above specific floor thresholds are forcing public sector facility managers to adopt sub-metering and performance tracking systems. This regulatory pressure is creating procurement preference for vendors with demonstrated energy audit capabilities and DOE-compliant reporting infrastructure. State universities and regional hospital networks represent the most affected segments, with procurement specifications now embedding energy performance guarantees.
Building owners are consolidating previously fragmented single-service awards into integrated bundled contracts that span maintenance, cleaning, security, and technical oversight. This procurement compression is displacing specialized janitorial and security subcontractors in favor of single-source facility management providers with multi-disciplinary capabilities. The shift is most visible in Metro Manila premium commercial towers, where landlord representation firms now bundle technical facilities oversight with property management services.
Philippines Facility Management Market Segmentation
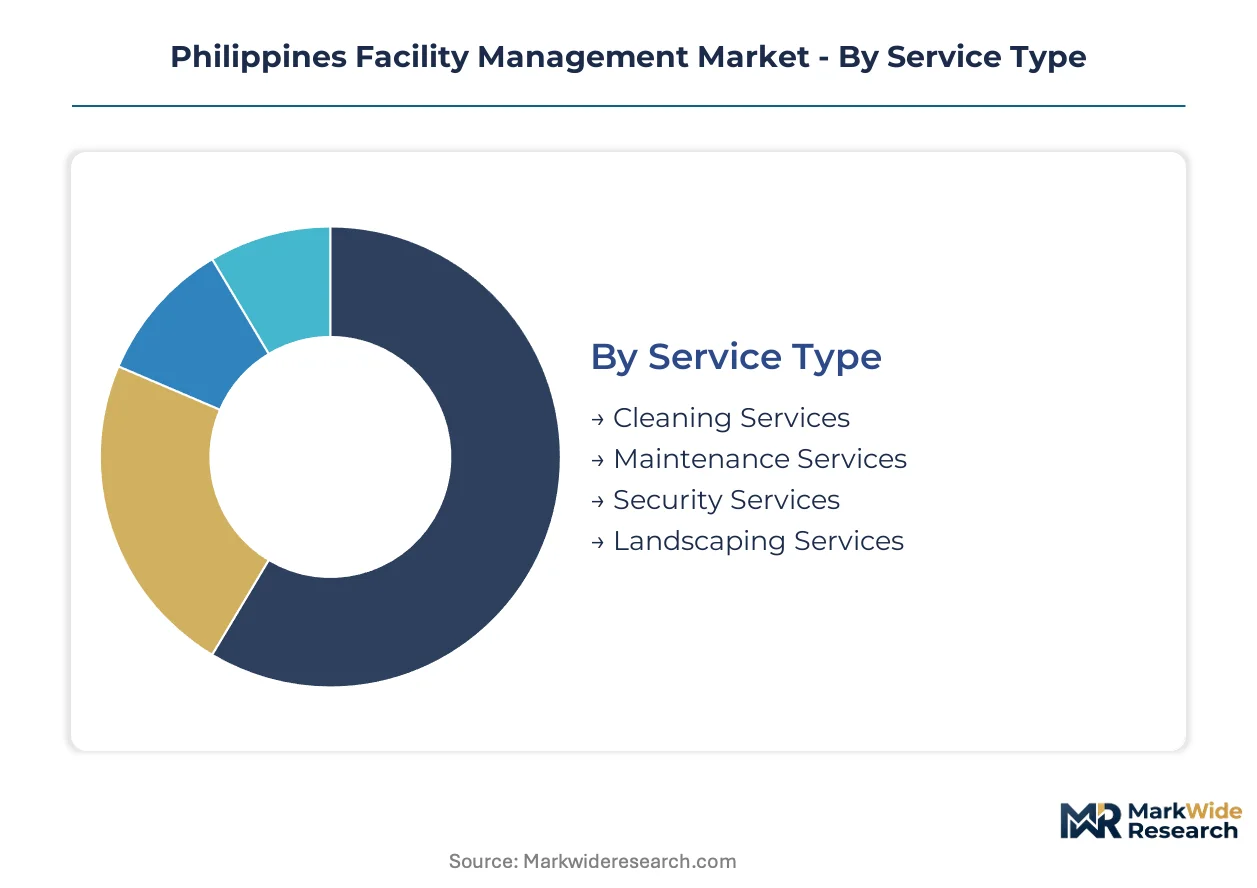
Philippine facility procurement patterns diverge sharply across service maturity and technology readiness. Segmentation reveals where bundled contracts compress vendor margins versus where specialized premiums persist.
Service Type:
Mature maintenance disciplines dominate contract value, while emerging technology-enabled services reshape competitive positioning.
- Maintenance Services:Encompasses HVAC calibration, electrical load balancing, fire suppression testing, and mechanical systems oversight under DPWH-mandated preventive schedules. Demand concentrates in Metro Manila commercial towers and PEZA industrial zones where uptime guarantees drive premium pricing.
- Cleaning Services:Covers janitorial operations, waste management, and sanitation protocols including Department of Health hospital-grade compliance. Healthcare Facilities in Cebu City and Davao create pricing differentiation pockets within otherwise commoditized municipal contracts.
- Security Services:Personnel-based access control and surveillance coordination for commercial and institutional properties.
- Landscaping Services:Grounds maintenance and green space management for corporate campuses and residential developments.
Maintenance Services handles the majority of throughput; Energy Management Systems integration is expanding most quickly within bundled contracts.
End User:
Customer concentration tilts toward institutional anchor tenants with compliance mandates rather than discretionary spenders.
- Healthcare Facilities:Public hospital infrastructure upgrades under DPWH stricter building codes generate compliance-driven service contracts nationwide. Department of Health sanitation protocols create mandatory procurement specifications that specialized vendors exploit.
- Commercial Buildings:Makati and Bonifacio Global City premium towers demand integrated workplace management bundling maintenance, cleaning, and technical oversight under single-source accountability.
- Educational Institutions:State universities face Department of Energy consumption benchmarking mandates forcing sub-metering and performance tracking procurement.
- Residential Complexes:Mid-market condominiums and gated communities with fragmented management associations.
Healthcare Facilities anchors regulatory tailwinds; Commercial Buildings drives technology adoption fastest.
Technology:
Cost tier stratification separates enterprise-grade platforms from point solutions facing consolidation pressure.
- Energy Management Systems:Sub-metering infrastructure and consumption analytics platforms enabling predictive load balancing. Government buildings above specific floor thresholds face DOE mandatory benchmarking, creating procurement preference for audit-capable vendors.
- IoT Solutions:Sensor networks for real-time occupancy analytics and dynamic HVAC adjustments. Large-scale developers in Cebu City emerging districts deploy these to compress energy expenditure against Asia's highest power rates.
- Building Management Software:Cloud-based asset lifecycle platforms for multi-site portfolio coordination.
- Automation Tools:Robotic cleaning and mechanical system controllers reducing labor dependency.
Energy Management Systems captures regulatory premiums; IoT Solutions climbs the fastest on deployment timelines.
Application:
Volume concentration sits with operational continuity mandates rather than discretionary efficiency projects.
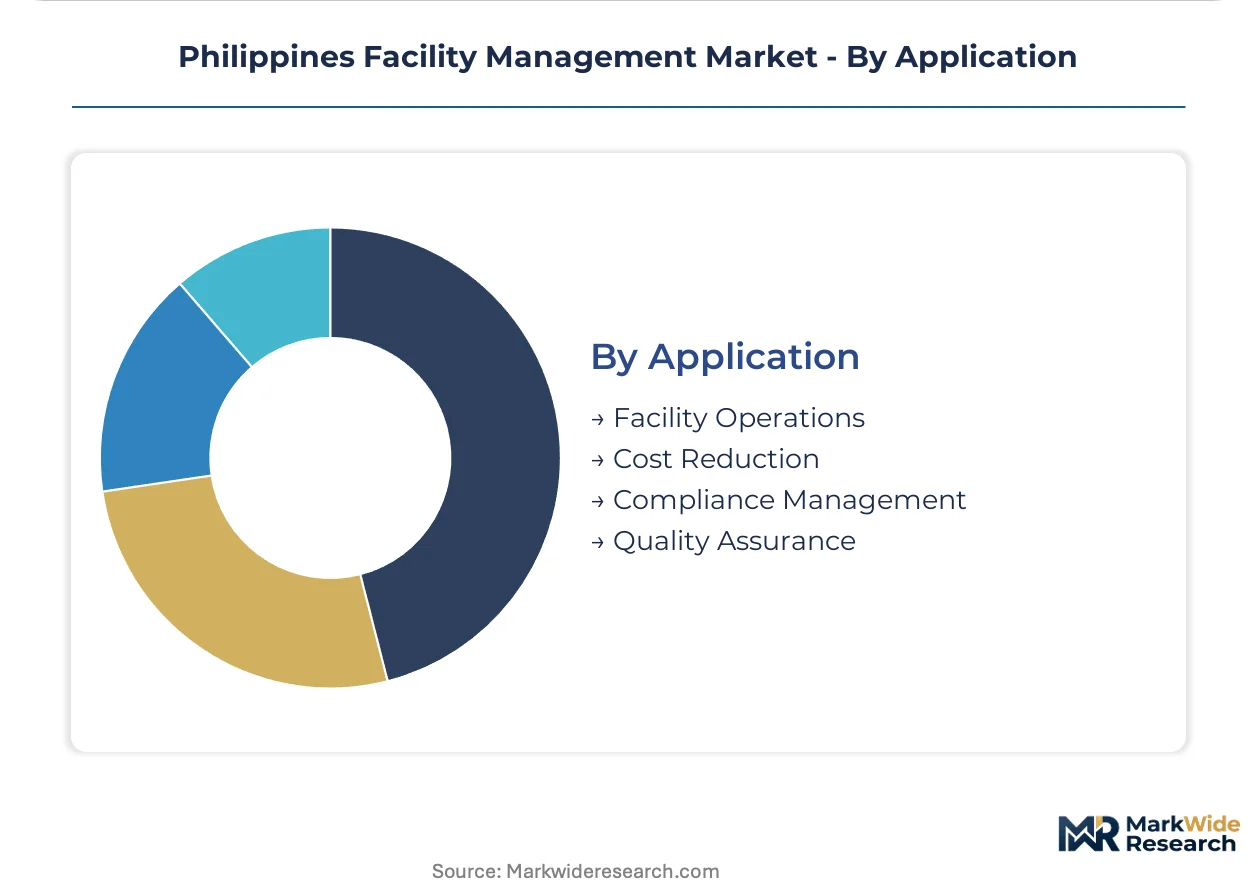
- Facility Operations:Core building systems coordination ensuring occupant safety and asset longevity across commercial, industrial, and institutional properties. Metro Manila premium portfolios demand 24/7 technical oversight with certified facility managers on staff per Bureau of Fire Protection requirements.
- Compliance Management:DPWH building code audits, BFP fire safety inspections, and DOE consumption reporting. Credential scarcity for certified technicians extends hiring timelines and inflates contract pricing.
- Cost Reduction:Energy expenditure compression and preventive maintenance scheduling.
- Quality Assurance:Performance benchmarking and service level enforcement.
Facility Operations handles the majority of contract volume; Compliance Management gains share fastest on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Subic-Clark corridor's logistics spine and the Cebu-Mactan international gateway anchor facility management demand across Philippine archipelagic geography. Metro Manila's premium commercial towers concentrate integrated service procurement, while emerging provincial business districts reshape vendor deployment patterns.
Metro Manila
DPWH-mandated building code audits for public hospital infrastructure generate compliance-driven service contracts across Quezon City and Caloocan medical districts. The Bureau of Fire Protection's certified facility manager requirements tighten staffing protocols for Makati and Bonifacio Global City high-occupancy towers. Integrated workplace management platforms compress multi-service procurement timelines across Ortigas and Taguig central business districts.
Cebu City
Department of Health sanitation protocols for hospital-grade cleaning create pricing premiums in emerging Cebu commercial zones outside Metro Manila. The Philippine Economic Zone Authority's Mactan export-processing enclave demands specialized industrial maintenance for electronics manufacturing locators. Regional office stock modernization in Cebu IT Park and Cebu Business Park tilts procurement toward bundled facility contracts.
Davao Region
Mindanao's largest metropolitan area attracts facility management vendors seeking geographic diversification beyond Luzon's saturated corridor. The Department of Energy's consumption benchmarking mandates extend to government buildings in Davao del Sur above specified floor thresholds. Limited certified technician availability extends hiring timelines for DPWH-compliant preventive maintenance schedules.
Central Luzon
Clark Freeport Zone and Subic Bay Metropolitan Authority industrial parks require captive technical facilities oversight for PEZA-registered manufacturing operations. The North Luzon Expressway logistics corridor supports distribution center maintenance demand across Pampanga and Tarlac warehousing clusters. Provincial service network fragmentation constrains same-day response capabilities for mechanical systems failures.
Western Visayas
Iloilo City's emerging business district presents underpenetrated demand for integrated bundled contracts as regional office construction accelerates. The Department of Public Works and Highways' stricter building code enforcement reaches provincial hospital infrastructure in Bacolod and Iloilo. Thin qualified vendor networks delay compliance audit completion timelines outside core urban centers.
Philippines Facility Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in maintenance and cleaning disciplines. The Philippine facility management market structures around three archetypes: international property consultancies bundling landlord representation with technical oversight, domestic industrial maintenance specialists serving PEZA locators, and integrated workplace management platform vendors compressing multi-service procurement. Competitive moves concentrate on geographic expansion into Cebu and Davao corridors, plus portfolio diversification into healthcare sanitation compliance.
Among international property consultancies, CBRE Philippines and Jones Lang LaSalle Inc. exemplify the bundled-service archetype combining landlord representation with technical facilities oversight. Kontrac Facilities Management Services Inc. occupies a position within the industrial maintenance specialist tier serving export-processing zone locators. Santos Knight Frank Inc. represents the hybrid model integrating property management with certified facility manager staffing for Bureau of Fire Protection compliance.
| Leading Market Players |
|---|
| SGS Philippines Inc. |
| Century Properties Management Inc. |
| CBRE Philippines |
| Kontrac Facilities Management Services Inc. |
| Mansion Maintenance Co. Inc. |
| Servicio Filipino Inc. |
| Santos Knight Frank Inc. |
| Jones Lang LaSalle Inc. |
| Meralco Industrial Engineering Services Corporation |
| Others |
Value Network & Pricing Analysis
Regulatory credential scarcity for Bureau of Fire Protection certified facility managers compresses both pricing tier spreads and supply chain configuration, forcing vendors to absorb training costs or pass premiums to buyers while concentrating qualified talent networks in Luzon's core corridor.
Pricing Analysis
Volume-discount tiering structures separate bundled integrated workplace management contracts from fragmented single-service awards. Pricing stratifies across premium, standard, and economy tiers based on certification grade compliance and geographic delivery cost. Cost compression in the standard tier is intensifying because provincial service fragmentation extends response timelines. Healthcare Facilities represent the least price-sensitive segment due to mandatory Department of Health sanitation protocols, while mid-market Residential Complexes exhibit highest sensitivity.
Supply Chain Analysis
Extended payment terms from Philippine Economic Zone Authority locators anchor supplier financing arrangements for industrial maintenance specialists. Equipment and technology inputs draw from Japan, South Korea, and Singapore. Single-source vulnerability concentrates in IoT sensor networks and cloud-based asset management platforms. Distribution runs through direct vendor-client contracting for premium commercial portfolios, with subcontractor cascades penetrating provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated workplace management platforms are reconfiguring the Philippines facility management market toward ecosystem economics, where interoperability between building automation and real-time occupancy analytics determines vendor survival.
For Market Incumbents: Build switching-cost moats through embedded energy performance guarantees tied to Department of Energy benchmarking mandates. Consolidate fragmented provincial service networks via acquisition of certified technician training pipelines. The threat of smart building platform vendors displacing standalone maintenance contracts demands backward integration into IoT deployment capabilities. For New Entrants and Emerging Players: Pursue white-space capture in Cebu City emerging commercial districts where regional office stock modernization outpaces qualified vendor supply. Target Davao Region government buildings facing DOE consumption mandates with sub-metering and audit capabilities. Lead with regulatory compliance expertise rather than price competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated specialists over fragmented single-service providers. Long-term viability hinges on proprietary technician certification pipelines and multi-site portfolio management software. Watch for Bureau of Fire Protection credential requirement expansion as the inflection signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines building automation with real-time occupancy analytics for Metro Manila premium towers. |
| Certification Pipeline Investment | Builds captive Bureau of Fire Protection and DPWH credential capacity ahead of regulatory tightening. |
| Geographic Expansion | Establishes qualified service networks in Cebu and Davao corridors beyond Luzon's saturated core. |
| Energy Audit Capability Acquisition | Captures Department of Energy-mandated benchmarking procurement preference in government buildings. |
| Healthcare Sanitation Specialization | Exploits Department of Health protocol premiums within commoditized cleaning services. |
Research Methodology
The analysis maps maintenance services, cleaning services, security services, and technology-enabled solutions, each validated through facility directors, property managers, procurement officers at PEZA locators, and certified facility managers. Primary interviews with building owners and technical oversight leads combined with secondary validation from DPWH building code filings, DOE consumption benchmarking reports, Bureau of Fire Protection inspection protocols, and Philippine Economic Zone Authority locator directories. Bottom-up contract value aggregation and top-down market sizing triangulate segment estimates.
Assumptions held DPWH regulatory enforcement timelines and PEZA zone expansion plans within observed patterns while varying smart building platform adoption rates and provincial service network development. The forecast framework spans service type, end user, technology, and application dimensions across the analysis window. CAGRs derive from segment-level growth trajectory blending and technology penetration curve modeling. Industry-specific inputs include electricity rate volatility assumptions and certified technician pipeline output estimates.
The forecast holds incumbent behavior within observed patterns; aggressive platform acquisition moves by international property consultancies would shift outcomes. Macroeconomic deviation, regulatory enforcement acceleration, or smart building technology cost disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Lithuania Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Vietnam Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Belgium Facility Management Market
Facility Management
Italy Facility Management Services Market