
 Calcitriol Capsules Market | 2026-2036
Calcitriol Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Calcitriol Capsules Market Insights
Fixed-dose combination bundling with phosphate binders is pivoting how nephrologists prescribe calcitriol therapy, reducing pill burden for dialysis patients. Pfizer leverages its hospital formulary relationships to sustain institutional channel dominance. Teva Pharmaceuticals anchors its position through generic calcitriol portfolios that compete aggressively on price. Sun Pharmaceutical Industries Ltd. differentiates via vertically integrated active pharmaceutical ingredient production that controls cost structures.
Calcitriol capsules contain the hormonally active form of vitamin D, chemically designated 1,25-dihydroxycholecalciferol, typically formulated at 0.25 microgram or 0.5 microgram strengths for oral administration to correct calcium metabolism disorders. The compound functions primarily as a calcium-regulating agent in patients with impaired renal activation of endogenous vitamin D. Softgel formulations lead the product type landscape due to enhanced bioavailability of lipophilic calcitriol in oil-based matrices, while hard capsules occupy the value-conscious generic tier where margin pools remain thinner. The kidney disease therapy area dominates absolute prescription volume given calcitriol's established role in managing secondary hyperparathyroidism among hemodialysis populations, though osteoporosis applications in predialysis chronic kidney disease represent the fastest-expanding clinical segment.
The US FDA enforces bioequivalence standards under ANDA pathways that determine which generic calcitriol manufacturers gain market access, while the EMA's centralized marketing authorization process governs European commercialization through the European Medicines Agency. India's CDSCO mandates local clinical trial bridging data for imported calcitriol formulations, shaping how multinational firms structure regulatory submissions. Stakeholders must monitor evolving pharmacovigilance requirements for hypercalcemia risk labeling as regulators tighten post-market surveillance on vitamin D analogs.
Market Dynamics
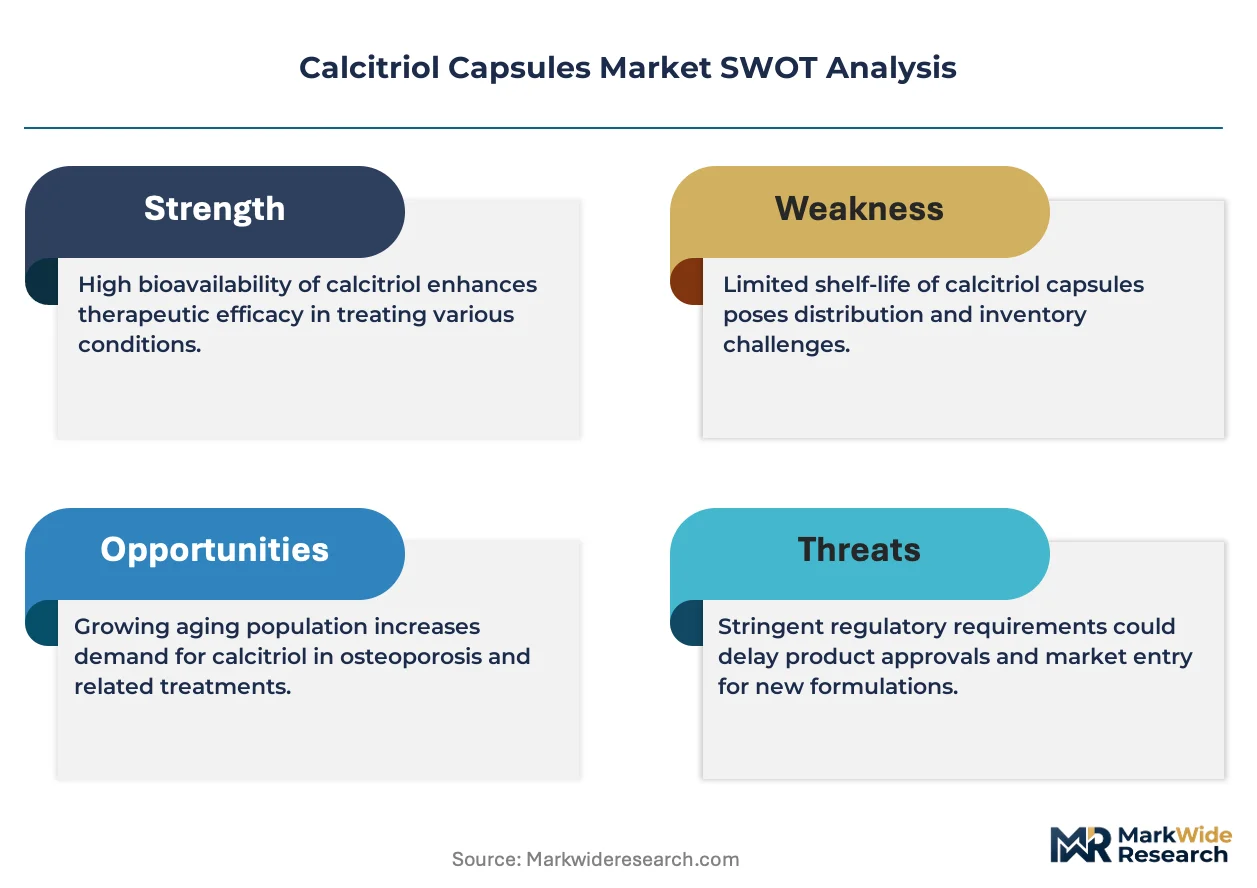
FDA bioequivalence requirements for generic calcitriol ANDAs are forcing manufacturers to invest heavily in dissolution testing and pharmacokinetic studies, compressing margins for mid-tier producers while elevating compliance costs across the formulation landscape.
Growth Catalysts
- Secondary hyperparathyroidism protocols:Dialysis centers in the United States are expanding calcitriol prescriptions as nephrology societies tighten PTH management guidelines, pulling volume through institutional channels.
- Medicare reimbursement structures:Active vitamin D therapy coverage under Medicare Part B sustains patient access and reduces out-of-pocket friction for chronic kidney disease populations.
- Softgel bioavailability advantages:Oil-based matrix formulations enhance lipophilic calcitriol absorption, driving preference among clinicians managing malabsorption in dialysis patients.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in India and China, exposing finished dose manufacturers to geopolitical friction and import inspection backlogs.
- Hypercalcemia liability exposure:Narrow therapeutic index of calcitriol elevates litigation risk and pharmacovigilance costs for sponsors maintaining post-market surveillance systems.
- Paricalcitol substitution pressure:Synthetic vitamin D analogs with improved side-effect profiles displace calcitriol in some dialysis protocols, particularly among integrated delivery networks.
Strategic Opportunities
- Predialysis osteoporosis expansion:Chronic kidney disease stages 3-4 represent underpenetrated calcitriol prescribing relative to dialysis populations, with endocrinology practices expanding off-label utilization.
- Fixed-dose phosphate binder bundling:Co-formulation with sevelamer or lanthanum carbonate reduces pill burden and creates pharmacy benefit manager negotiation leverage.
- Indian CDSCO local trial pathway:Bridging study requirements for imported formulations create first-mover advantages for sponsors establishing domestic manufacturing or licensing partnerships.
Industry Challenges
- ANDA bioequivalence timeline compression:FDA dissolution profile matching requirements extend development cycles for generic sponsors, delaying market entry and elevating capital-at-risk.
- Specialized nephrology sales force maintenance:Targeting dialysis centers and nephrology clinics demands dedicated clinical liaisons with CKD-MBD expertise, inflating fixed cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcitriol Capsules Market |
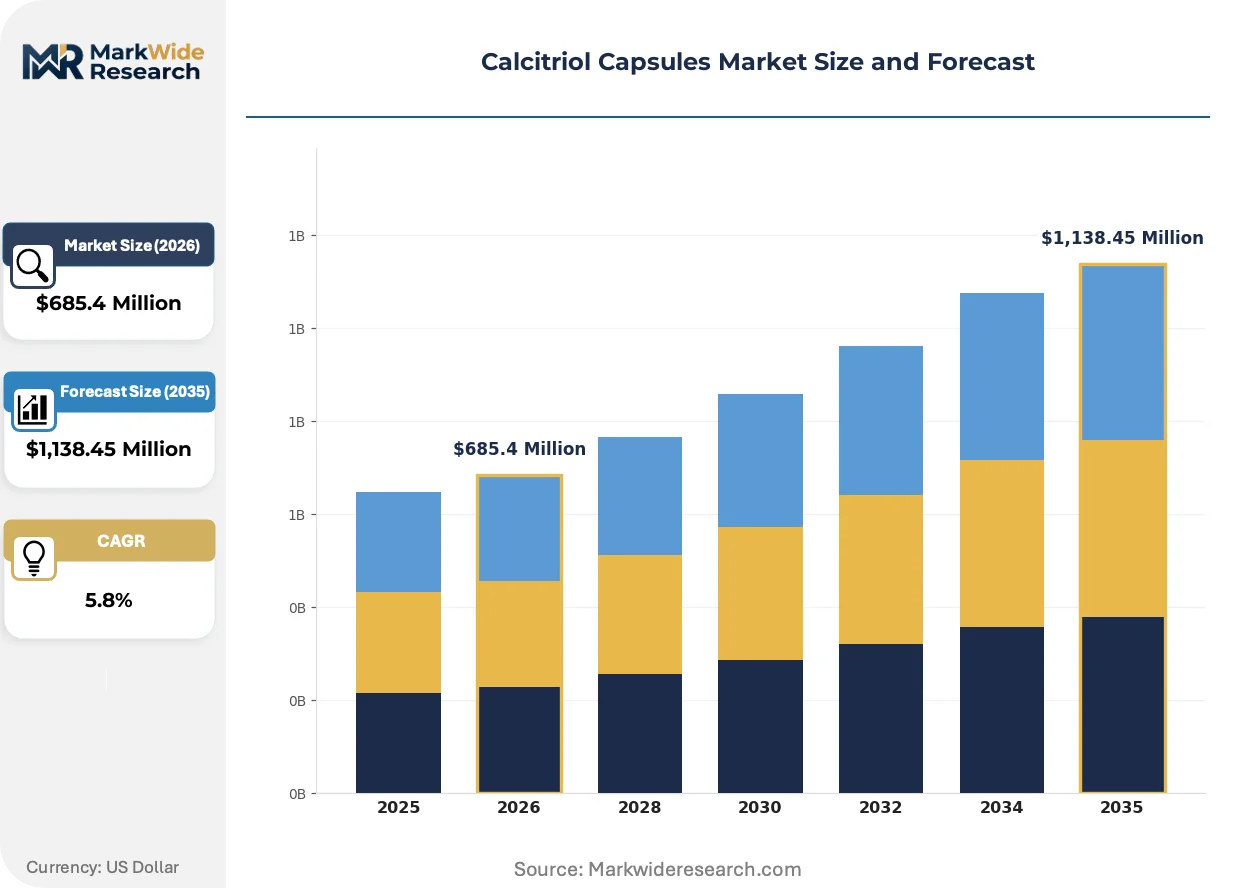
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgel, Hard capsule, Oral solution, Powder End User: Hospitals, Clinics, Pharmacies, Homecare Therapy Area: Kidney Disease, Osteoporosis, Psoriasis, Nutritional Deficiency Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | GlaxoSmithKline plc, Pfizer, Teva Pharmaceuticals, Sun Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd, Abbott, Cadila Pharmaceuticals, Cardinal Health, Strides Pharma Science Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcitriol Capsules Market Trends and Innovations
Formulation science and regulatory science are converging to reshape calcitriol product development, with bioequivalence methodology and patient-centric delivery formats commanding disproportionate R&D investment relative to molecular innovation.
Nanostructured lipid carriers are integrating into calcitriol softgel development to enhance lymphatic absorption and reduce first-pass metabolism variability. Nephrology-focused contract manufacturers are adopting these platforms to differentiate against commodity generic offerings. The technology is integrating quality-by-design principles that compress batch failure rates and accelerate ANDA submission timelines.
EMA's tightened pharmacovigilance requirements for vitamin D analogs are mandating real-world evidence collection through patient registries and electronic health record mining. Marketing authorization holders must now submit periodic safety update reports with hypercalcemia signal detection algorithms. European nephrology clinics are responding by standardizing PTH and calcium monitoring protocols to preempt regulatory scrutiny.
Integrated delivery networks in the United States are consolidating calcitriol purchasing through specialty pharmacy carve-outs, displacing traditional wholesale distribution for dialysis center supply. Pharmacy benefit managers are deploying therapeutic substitution protocols that favor contracted manufacturers. This concentration is most visible in Medicare Advantage populations where vertical integration between payers and dialysis providers compresses formulary access points.
Calcitriol Capsules Market Segmentation
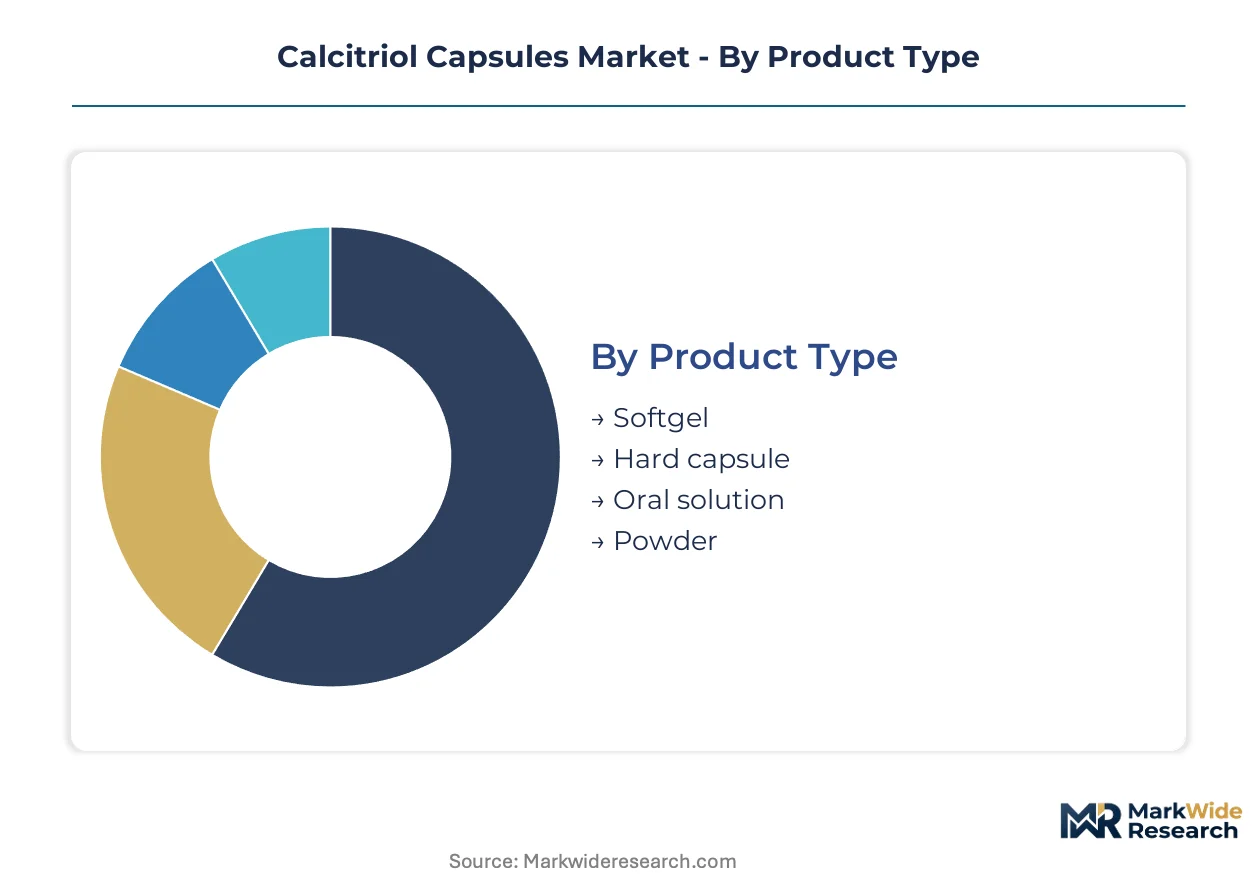
Calcitriol capsule formulations diverge sharply across delivery technologies, patient settings, and reimbursement pathways. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that determine manufacturer strategic positioning.
Product Type:
Oil-based matrices and solid oral technologies define the formulation landscape, with bioavailability performance separating premium from commodity tiers.
- Softgel:Lipophilic calcitriol dissolves in oil-based gel matrices that enhance absorption in patients with malabsorption syndromes common to advanced chronic kidney disease. Dialysis centers in the United States favor these formulations for hemodialysis populations where gastrointestinal function is compromised.
- Hard capsule:Powder-filled gelatin shells deliver crystalline calcitriol at lower unit cost, anchoring the generic tier where Medicare Part B reimbursement compression forces price competition. Indian API manufacturers supply the bulk of active ingredient for these formulations.
- Oral solution:Liquid formulations enable dose titration in pediatric populations and patients with dysphagia, though stability requirements limit shelf life.
- Powder:Bulk active pharmaceutical ingredient for institutional compounding occupies niche demand in research settings and specialized nephrology practices.
Mature deployment sits with Softgel. Newer deployment is concentrated in Hard capsule.
End User:
Institutional procurement power and patient acuity levels create divergent margin and compliance requirements across the care continuum.
- Hospitals:Inpatient nephrology services manage acute hypercalcemia episodes and initiate calcitriol therapy for newly diagnosed secondary hyperparathyroidism. Formulary committees negotiate sole-source contracts with manufacturers holding FDA-approved ANDAs.
- Clinics:Outpatient dialysis centers generate recurring prescription volume through standing orders tied to monthly PTH monitoring protocols. Bundled payment models under Medicare constrain per-dose reimbursement rates.
- Pharmacies:Retail dispensing captures predialysis chronic kidney disease patients managed by community nephrologists and endocrinologists.
- Homecare:Specialty pharmacy distribution serves peritoneal dialysis patients administering calcitriol outside institutional settings.
Volume concentrates in Clinics. Value capture is shifting toward Homecare.
Therapy Area:
Clinical indication drives dosing intensity, monitoring frequency, and competitive substitution risk from alternative vitamin D analogs.
- Kidney Disease:Secondary hyperparathyroidism management in dialysis-dependent populations consumes the majority of calcitriol prescriptions. KDIGO guideline adherence by nephrology societies sustains protocol-driven demand in the United States.
- Osteoporosis:Predialysis chronic kidney disease stages 3-4 represent expanding off-label utilization as endocrinology practices address mineral bone disorder before dialysis initiation.
- Psoriasis:Topical calcitriol competes with systemic capsules for moderate plaque disease, though oral bioavailability concerns limit dermatology adoption.
- Nutritional Deficiency:Hypoparathyroidism and malabsorption syndromes generate low-volume, high-compliance prescriptions in specialized endocrinology practices.
Established protocols dominate Kidney Disease. Prescription expansion is climbing the fastest in Osteoporosis.
Distribution Channel:
Channel configuration determines manufacturer touchpoint economics and data capture capabilities for pharmacovigilance obligations.
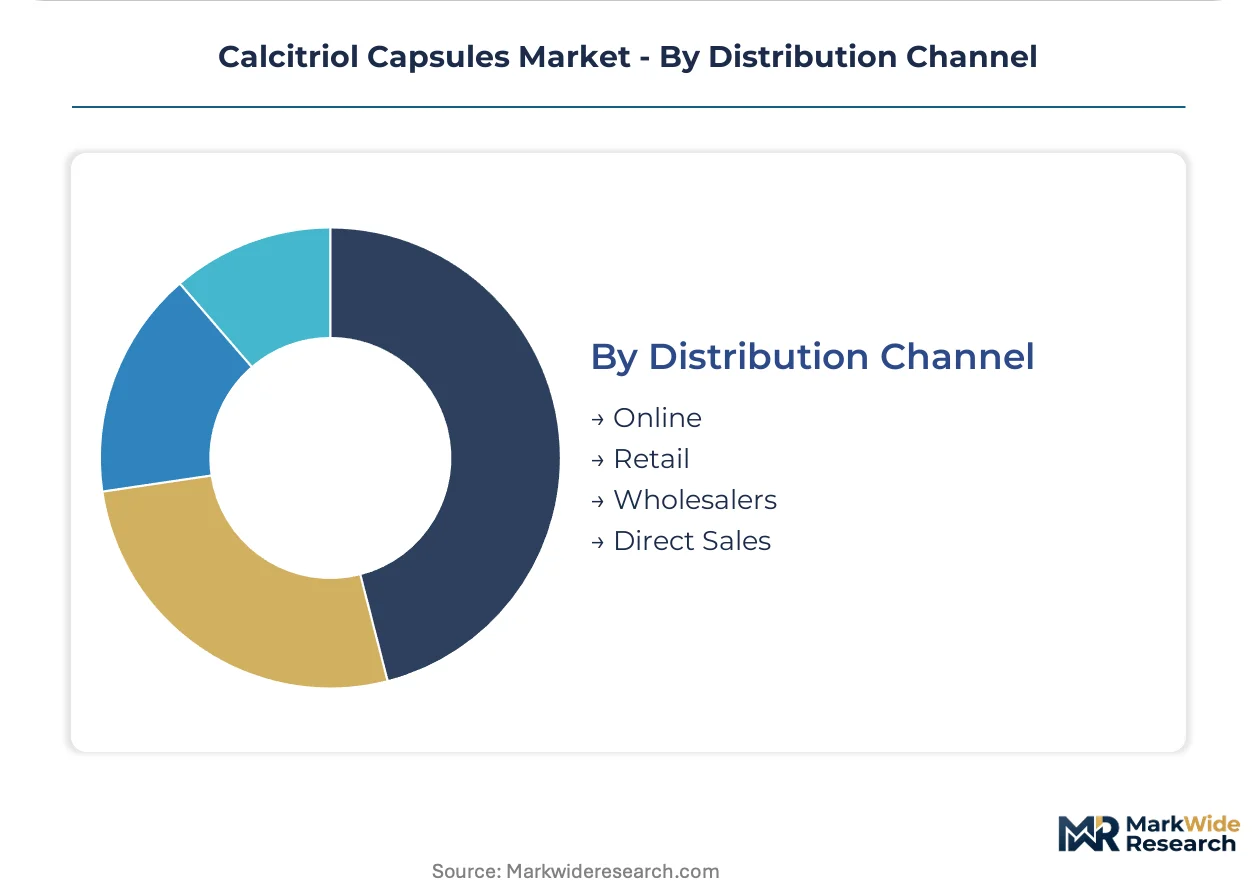
- Online:Telehealth-integrated specialty pharmacies serve Medicare Advantage populations with home delivery and automated refill management.
- Retail:Chain pharmacies process 30-day fills for commercially insured predialysis patients with standard benefit designs.
- Wholesalers:Institutional purchasing through distributors like McKesson and AmerisourceBergen supplies dialysis center networks with 340B pricing access.
- Direct Sales:Manufacturer field forces negotiate sole-source agreements with integrated delivery networks controlling multiple dialysis facilities.
Contract penetration is deepest in Wholesalers. Channel development is accelerating in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Telangana concentrate Indian pharmaceutical manufacturing, while FDA-registered facilities in New Jersey and Puerto Rico anchor North American supply. Medicare reimbursement structures and EMA centralized authorizations create divergent commercial pathways across major demand centers.
United States
Dialysis center networks in Texas and Florida drive institutional procurement volume for secondary hyperparathyroidism protocols. FDA bioequivalence requirements under ANDA pathways compress generic entry timelines and elevate compliance investments. New Jersey hosts Pfizer's hospital formulary negotiation headquarters, shaping Medicare Part B contracting strategies.
Germany
Integrated delivery networks in Bavaria and North Rhine-Westphalia consolidate calcitriol purchasing through specialty pharmacy carve-outs. EMA pharmacovigilance mandates for vitamin D analogs require real-world evidence collection through nephrology registries. Heidelberg and Mannheim clusters house contract manufacturing organizations serving EMA centralized marketing authorizations.
India
CDSCO bridging study requirements for imported formulations reshape how multinational sponsors structure regulatory submissions. Active pharmaceutical ingredient production concentrates in Hyderabad and Ahmedabad, supplying crystalline calcitriol for global generic formulation. Sun Pharmaceutical Industries Ltd. leverages vertically integrated API production from its Gujarat facilities.
Japan
PMDA post-market surveillance requirements for narrow therapeutic index drugs elevate pharmacovigilance costs for vitamin D analog sponsors. Dialysis-dependent populations in Osaka and Tokyo metropolitan areas sustain protocol-driven prescribing through nephrology society guidelines. Kansai region manufacturers supply oil-based softgel formulations optimized for malabsorption populations.
Brazil
ANVISA registration pathways for imported calcitriol formulations create extended review timelines for foreign sponsors. São Paulo state dialysis networks expand secondary hyperparathyroidism management protocols, pulling volume through institutional channels. Local manufacturing partnerships in Rio de Janeiro and Minas Gerais reduce import dependency for finished dose supply.
Calcitriol Capsules Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the calcitriol capsule landscape, creating a tiered structure where hospital formulary relationships determine institutional access. Pfizer leverages its diversified pharmaceutical portfolio to sustain sole-source agreements with integrated delivery networks. Teva Pharmaceuticals anchors the generic tier through aggressive price positioning. Strategic moves concentrate on ANDA bioequivalence investments and fixed-dose combination bundling with phosphate binders.
Within the diversified multinational tier, Pfizer and GlaxoSmithKline plc exemplify hospital-centric commercial models that prioritize formulary committee negotiations over retail pharmacy volume. Teva Pharmaceuticals occupies a distinct position as a generic-focused specialist competing on price-accessibility for Medicare Part B reimbursement. Sun Pharmaceutical Industries Ltd. represents the vertically integrated Indian manufacturer archetype, controlling cost structures through captive API supply from domestic facilities.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer |
| Teva Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Cadila Pharmaceuticals |
| Cardinal Health |
| Strides Pharma Science Limited |
| Others |
Pricing and Supply Chain Analysis
Captive API production in Indian pharmaceutical zones anchors both cost structures and pricing power for finished dose manufacturers serving Medicare Part B reimbursement channels. This backward integration choice insulates margin positions against import inspection volatility while compressing price competition in the generic hard capsule tier.
Pricing Analysis
Short lead-time premiums for softgel formulations serving dialysis centers with standing monthly orders separate from spot inventory discounts in the retail pharmacy channel. Three-tier pricing structure across premium softgel, standard hard capsule, and economy generic levels reflects bioavailability performance and ANDA bioequivalence certification status. Pricing pressure stems from Medicare Part B reimbursement compression forcing manufacturers toward volume-based contracting. Dialysis center procurement committees exhibit highest price sensitivity, while hospital formulary directors prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Gujarat and Telangana feed hub-and-spoke patterns into FDA-registered facilities in New Jersey and Puerto Rico for North American finished dose supply. Active pharmaceutical ingredient production draws from India and China, with crystalline calcitriol feedstock resting on import inspection clearance timelines. Single-source vulnerability concentrates in Hyderabad API clusters subject to CDSCO export certification delays. Distribution runs through institutional purchasing cooperatives serving integrated dialysis networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcitriol capsules market functions as a vertical-integration race where control over active pharmaceutical ingredient supply determines who captures Medicare Part B contract volume. Players are pursuing backward integration into Indian API manufacturing as the decisive upstream lever.
For Market Incumbents: Anticipate paricalcitol substitution pressure from integrated delivery networks by securing sole-source formulary agreements with hospital systems before generic calcitriol ANDA approvals multiply. Defend market position through fixed-dose phosphate binder bundling that raises competitor switching costs. Prioritize CDSCO local trial pathway investments to preempt emerging Indian manufacturers from gaining first-mover bridging study advantages. For New Entrants and Emerging Players: Predialysis osteoporosis patients managed by community endocrinologists represent an underserved buyer archetype with lower formulary control intensity than dialysis centers. Target this white-space segment through telehealth-integrated specialty pharmacy partnerships that bypass traditional institutional procurement. Penetration accelerates fastest in Medicare Advantage populations where vertical integration between payers and nephrology practices creates carve-out opportunities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking hospital formulary access. Long-term viability hinges on ANDA bioequivalence completion timelines and phosphate binder co-formulation capabilities. Watch for FDA dissolution profile guidance revisions as the critical inflection signal that reshapes generic entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Phosphate Binder Co-Formulation | Bundling with sevelamer reduces pill burden and strengthens PBM negotiation leverage. |
| CDSCO Local Trial Bridging Study | Domestic clinical data requirements create regulatory moats against imported formulation competitors. |
| Nanostructured Lipid Carrier Softgel Development | Enhanced lymphatic absorption differentiates against commodity generic offerings in dialysis populations. |
| Medicare Part B Contracting Scale-Up | Institutional volume commitments secure recurring revenue through bundled payment models. |
| EMA Pharmacovigilance Registry Investment | Real-world evidence collection preempts regulatory scrutiny on hypercalcemia risk labeling. |
Research Methodology
FDA ANDA filings, EMA centralized marketing authorization records, and CMS Medicare Part B claims data formed the secondary backbone for market sizing and competitive positioning. Primary interviews with nephrology formulary directors, dialysis center procurement managers, CDSCO regulatory affairs leads, and API manufacturing executives validated secondary findings. Bottom-up prescription volume triangulation against top-down reimbursement expenditure analysis anchored forecast confidence.
Bottom-up modeling of prescription volumes by therapy area, product type, and distribution channel converged with top-down Medicare expenditure trajectory analysis across the projection horizon. Segmentation dimensions included dosage form technology, patient disease stage, institutional versus retail channel mix, and regional regulatory cluster. CAGRs derived from polynomial trend fitting to historical prescription audit data, with calcitriol-to-paricalcitol substitution rates and KDIGO guideline revision timing as key sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA bioequivalence guidance shifts and Indian API export policy changes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market