
 Vutrisiran Market | 2026-2036
Vutrisiran Market Size, Share, and Industry Trends Forecast 2026-2036
Vutrisiran Market Outlook
Outcome-based financing and pay-for-performance agreements between insurers and RNA therapy developers are reshaping how manufacturers fund clinical programs and commercial launches. Alnylam Pharmaceuticals leverages its end-to-end siRNA manufacturing infrastructure to control supply security and pricing power. Ionis Pharmaceuticals anchors its competitive position through deep expertise in antisense chemistry and strategic partnerships with large-cap biopharma. Pfizer Inc. extends its reach into rare disease RNA therapeutics through licensing arrangements and distribution scale.
Vutrisiran is a chemically modified, double-stranded small interfering RNA (siRNA) conjugated to N-acetylgalactosamine (GalNAc) ligands, enabling targeted hepatocyte uptake and silencing of transthyretin (TTR) gene expression to reduce amyloid deposition. The subcutaneous delivery mode dominates clinical preference due to reduced infusion center burden and patient convenience compared to intravenous alternatives. Hereditary transthyretin amyloidosis represents the leading indication segment, while cardiac amyloidosis applications are expanding fastest as screening protocols improve and cardiologist awareness broadens.
The FDA's accelerated approval and orphan drug designations shape development economics by granting market exclusivity and tax incentives, while the EMA's PRIME eligibility streamlines European access for innovative RNA therapies. The EU's CSRD and evolving pharmaceutical disclosure requirements are pressing manufacturers to document environmental and social governance across their supply chains. Stakeholders must monitor how CMS and European health technology assessment bodies calibrate value-based pricing for single-administration gene-silencing drugs against chronic infusion alternatives.
Market Dynamics
RNA therapeutic manufacturing is consolidating around captive GalNAc-siRNA conjugation capacity, with specialty infusion networks competing to secure preferential supply allocation from Alnylam's end-to-end production infrastructure.
Growth Catalysts
- Orphan drug exclusivity:The FDA's seven-year market exclusivity provisions for hereditary transthyretin amyloidosis indications protect pricing power and accelerate clinical investment timelines.
- Subcutaneous delivery preference:Hepatology clinics and home infusion services are expanding subcutaneous administration capacity, reducing dependence on hospital-based intravenous infrastructure.
- Cardiac amyloidosis screening:Mayo Clinic and Cleveland Clinic protocols are driving diagnostic volume through technetium pyrophosphate scintigraphy adoption.
Market Restraints
- GalNAc ligand supply concentration:Three contract manufacturers control N-acetylgalactosamine production, creating single-source vulnerability for siRNA conjugation.
- Reimbursement fragmentation:Medicare Part B versus Part D classification disputes delay patient access across US commercial and government payers.
- Patent thicket complexity:Alnylam's foundational siRNA delivery patents constrain second-mover freedom-to-operate for rival GalNAc conjugate programs.
Strategic Opportunities
- Wild-type ATTR cardiac expansion:The HELIOS-B trial readout positions vutrisiran for sporadic amyloidosis, a population tenfold larger than hereditary cases.
- EMA PRIME eligibility:European Medicines Agency priority medicines status compresses regulatory review timelines and accelerates national reimbursement negotiations.
- Home administration models:Self-injection training programs and remote monitoring platforms enable outpatient revenue capture outside infusion center fee structures.
Industry Challenges
- siRNA manufacturing talent scarcity:Synthetic chemists with oligonucleotide purification expertise command premium compensation, constraining capacity expansion timelines.
- Cold chain integrity:Temperature excursions during GalNAc-siRNA distribution degrade potency, requiring validated thermal packaging investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vutrisiran Market |
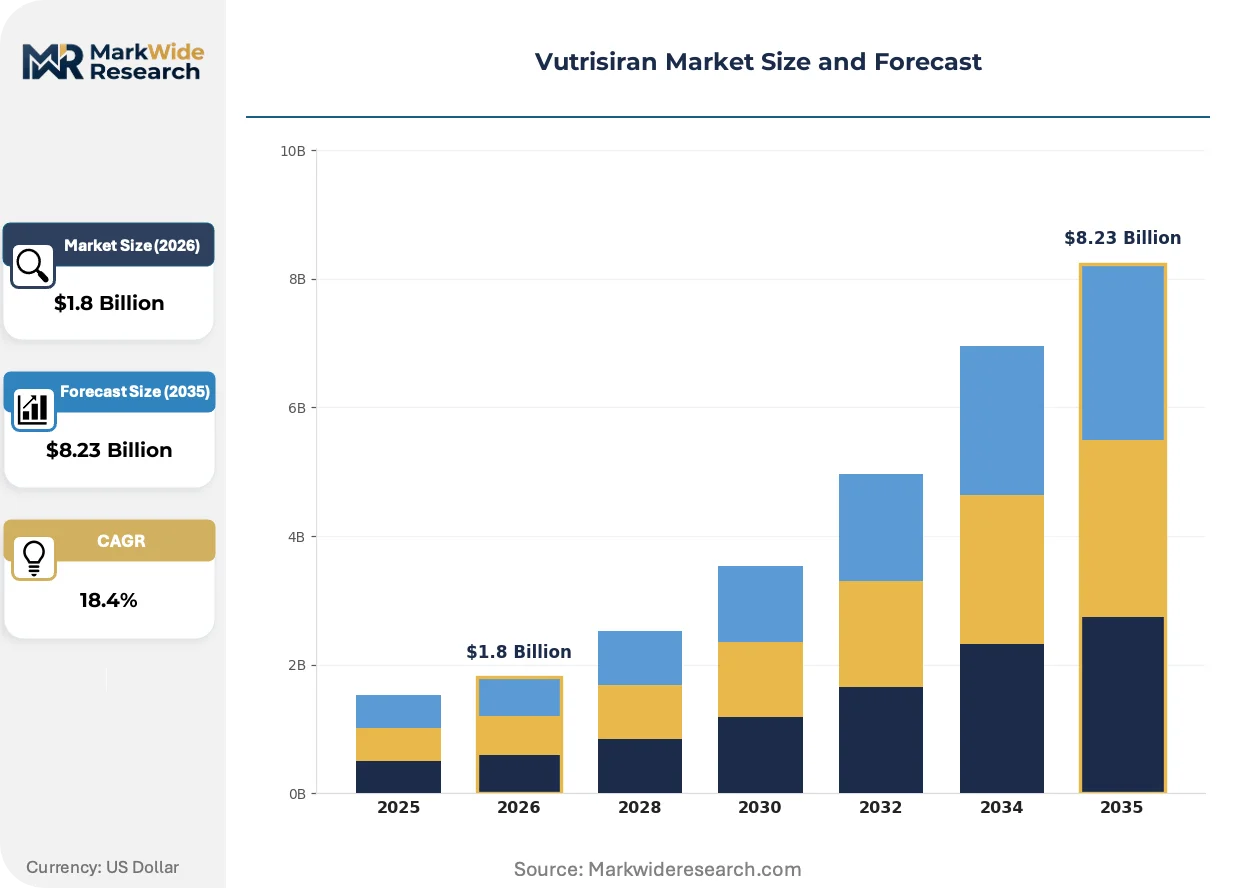
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Oral Tablet, Infusion, Capsule Indication: Hereditary Transthyretin Amyloidosis, Cardiac Amyloidosis, Peripheral Neuropathy, Protein Misfolding Diseases Delivery Mode: Subcutaneous, Intravenous, Oral, Transdermal End User: Hospitals, Specialty Clinics, Research Institutions, Home Care |
| Companies Covered | Ultragenyx Pharmaceutical, Teva Pharmaceuticals, Alnylam Pharmaceuticals, Inc., Ionis Pharmaceuticals, Sanofi, AstraZeneca, Merck & Co., Inc., Regeneron Pharmaceuticals, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vutrisiran Market Strategic Shifts
RNA therapeutic development is pivoting from rare disease proof-of-concept toward common disease scalability, with delivery chemistry and manufacturing process innovations compressing dose volumes and administration frequencies.
Next-generation GalNAc-siRNA conjugates are hybridizing multivalent ligand architectures with enhanced endosomal escape mechanisms. Hepatology and cardiology practices in the United States are adopting these constructs for monthly and quarterly dosing regimens. The technology is hybridizing chronic disease management models previously reserved for small-molecule oral therapies.
The FDA's accelerated approval pathway for amyloidosis therapies is conditioning confirmatory trial design on surrogate endpoint validation. Manufacturers must complete post-marketing cardiovascular outcome studies to maintain labeling. Cardiac amyloidosis indications face the steepest evidentiary requirements, with sponsors investing in registry infrastructure to satisfy the agency's confirmatory evidence standards.
Specialty pharmacy distribution is displacing buy-and-bill oncology models for RNA therapeutics. Accredo and CVS Specialty are capturing patient management through risk-sharing agreements with payers. This channel migration is most advanced in Massachusetts and California, where integrated delivery networks have consolidated infusion access under specialty pharmacy formularies.
Vutrisiran Market Segmentation
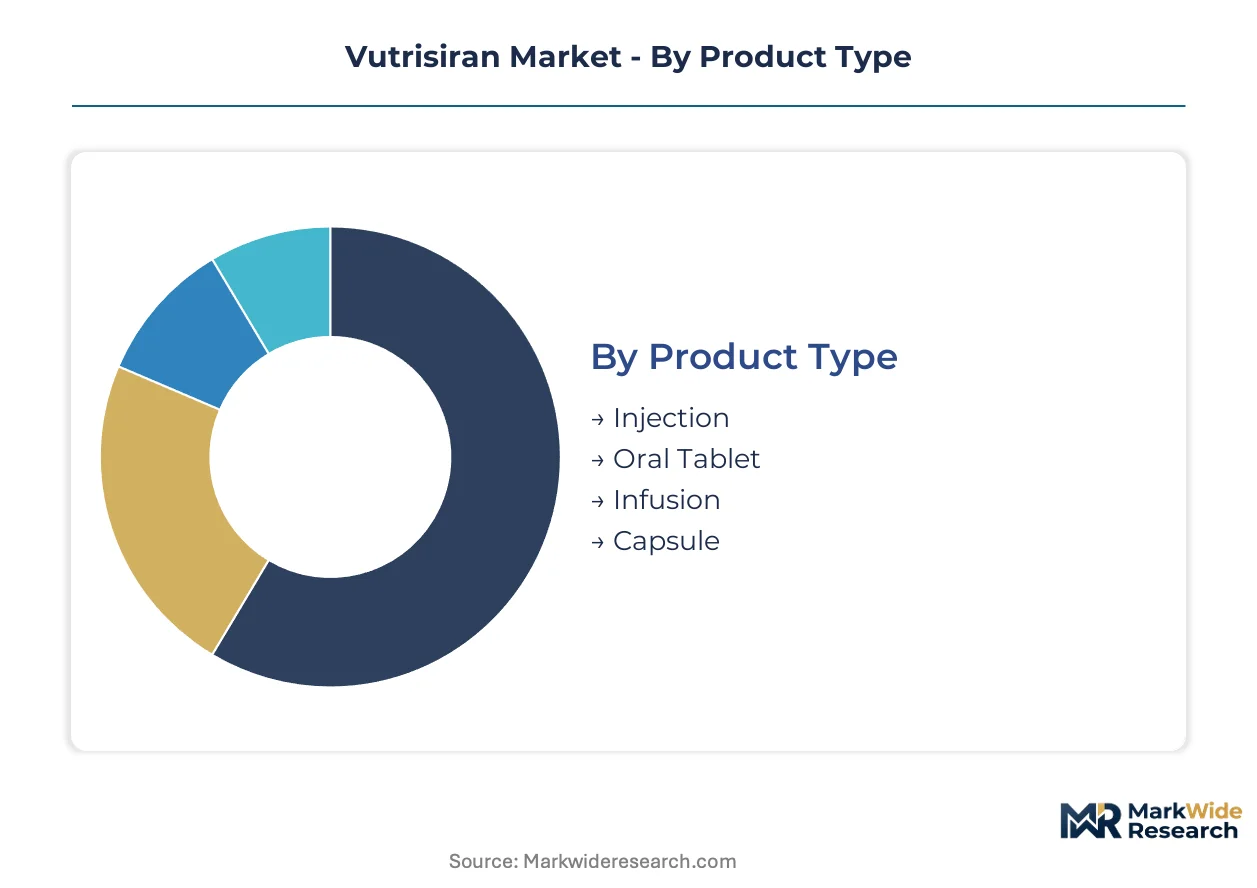
RNA therapeutic segmentation reveals how administration economics, disease biology, and care setting infrastructure interact to determine commercial viability. Each dimension carries distinct margin profiles and capacity constraints that reshape competitive positioning across the value chain.
Product Type:
Cycle times vary dramatically — subcutaneous injection formulations turn inventory fastest due to simplified cold chain requirements, while intravenous infusion products tie up working capital through complex compounding protocols.
- Injection:Pre-filled syringe and autoinjector formats dominate vutrisiran commercialization. Hepatology clinics in the United States prefer subcutaneous injection for its reduced nursing burden and faster patient throughput.
- Infusion:Intravenous administration requires hospital-based infrastructure with extended chair time. Mayo Clinic and Cleveland Clinic amyloidosis centers maintain dedicated infusion suites for patients with needle aversion or complex comorbidities.
- Oral Tablet:Small-molecule TTR stabilizers compete alongside siRNA therapies in oral formats. Bioavailability challenges limit oral RNA therapeutic development despite patient preference.
- Capsule:Encapsulated lipid nanoparticle formulations remain experimental for hepatocyte-targeted gene silencing. Early-phase sponsors explore capsule delivery to bypass injection requirements entirely.
Injection dominates installed base. Infusion is where expansion concentrates for cardiac amyloidosis patients requiring concomitant cardiovascular monitoring.
Indication:
Cost tier stratification separates ultra-rare hereditary indications from larger cardiac populations, with reimbursement intensity scaling inversely to addressable patient volume.
- Hereditary Transthyretin Amyloidosis:Germline TTR mutations drive progressive polyneuropathy and cardiomyopathy. The FDA granted vutrisiran accelerated approval based on surrogate neurological endpoints, with confirmatory cardiovascular outcome trials ongoing.
- Cardiac Amyloidosis:Wild-type ATTR deposits infiltrate myocardium in aging populations. Technetium pyrophosphate scintigraphy screening at US academic medical centers is expanding diagnostic capture faster than hereditary testing.
- Peripheral Neuropathy:TTR amyloid deposition damages autonomic and sensory nerves. Neurology practices coordinate with cardiology for systemic staging.
- Protein Misfolding Diseases:Broader amyloidosis category includes AL and AA subtypes with distinct therapeutic pathways. Vutrisiran mechanism specificity limits cross-indication application.
Hereditary Transthyretin Amyloidosis anchors revenue concentration. Cardiac Amyloidosis is climbing the fastest as screening protocols mature.
Delivery Mode:
Patient type determines channel economics — self-administered subcutaneous dosing shifts reimbursement from facility fees toward pharmacy benefit structures.
- Subcutaneous:Monthly or quarterly self-injection with remote monitoring support. Home infusion services and specialty pharmacies capture margin through patient training programs.
- Intravenous:Hospital outpatient department administration under Medicare Part B. Buy-and-bill oncology models persist for cardiac monitoring requirements.
- Oral:TTR stabilizers like tafamidis compete via oral bioavailability. siRNA oral delivery remains preclinical due to gastrointestinal nuclease degradation.
- Transdermal:Microneedle patch technologies under investigation for painless siRNA administration. No commercial products yet approved.
Subcutaneous administration commands patient preference. Intravenous retains share where cardiac telemetry is required.
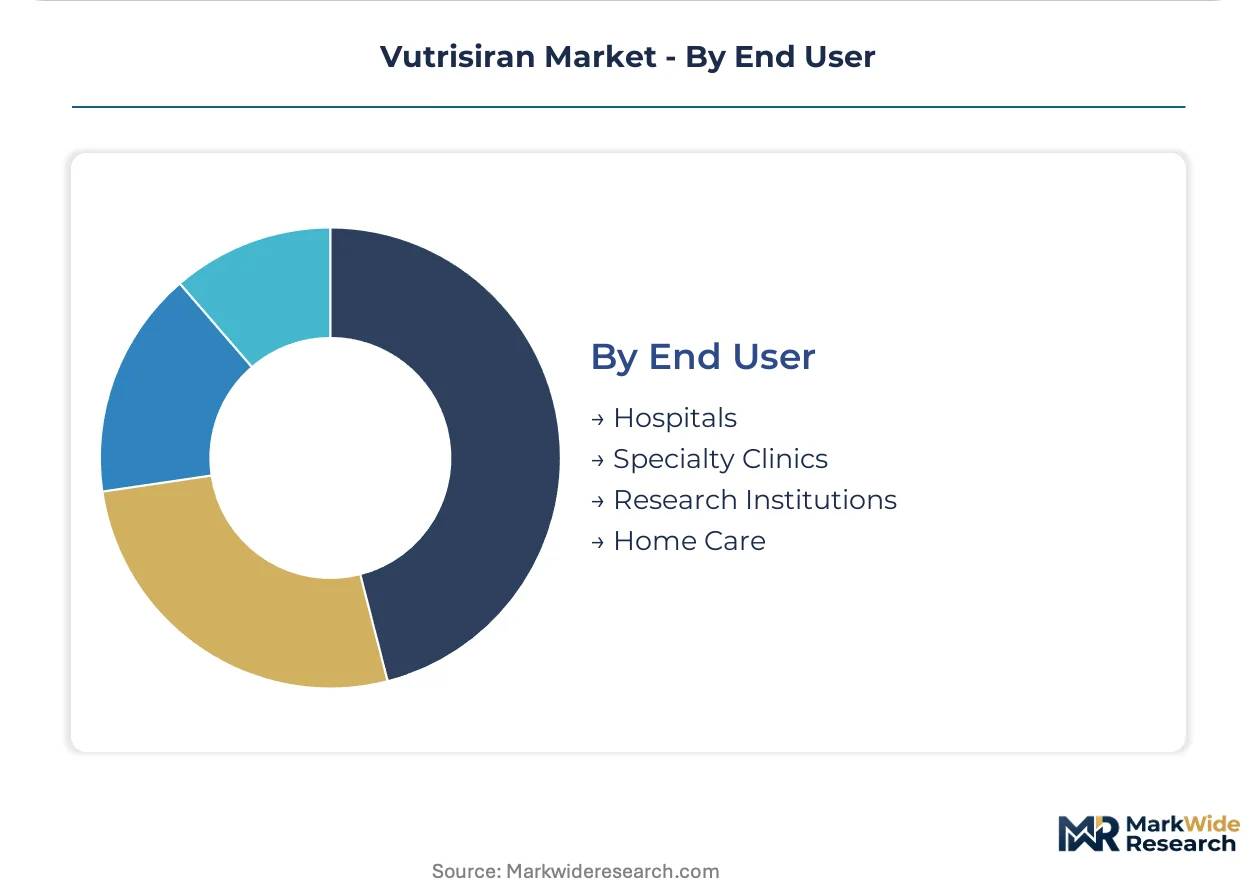
End User:
Supply concentration favors integrated delivery networks with captive specialty pharmacy relationships and amyloidosis diagnostic expertise.
- Specialty Clinics:Dedicated amyloidosis centers at Massachusetts General and Stanford coordinate genetic counseling, neurology, and cardiology. These sites command preferential allocation from Alnylam's limited distribution network.
- Hospitals:Academic medical centers with cardiac catheterization labs manage wild-type ATTR patients requiring invasive hemodynamic assessment. CMS reimbursement rates for hospital outpatient infusion exceed specialty clinic fee schedules.
- Home Care:Visiting nurse services administer subcutaneous vutrisiran with telehealth oversight. Risk-sharing agreements between payers and home health agencies are expanding in California and Florida.
- Research Institutions:NIH-funded amyloidosis centers conduct natural history studies and registry enrollment. These sites generate real-world evidence supporting label expansion.
Specialty Clinics dominate installed base. Home Care is gaining share fastest as self-administration protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in RNA therapeutics skew heavily toward import dependence outside the United States, with manufacturing concentration in North American and European hubs creating asymmetric access patterns across patient populations.
United States
Massachusetts General and Stanford amyloidosis centers drive diagnostic volume through technetium pyrophosphate scintigraphy protocols. FDA orphan drug exclusivity provisions grant seven-year market protection for hereditary transthyretin amyloidosis indications. Alnylam's Cambridge manufacturing complex controls captive GalNAc-siRNA conjugation capacity serving domestic specialty clinic networks.
Germany
University hospitals in Munich and Heidelberg coordinate European reference networks for ATTR cardiomyopathy staging. EMA PRIME eligibility compresses regulatory review timelines for innovative RNA therapies entering German reimbursement negotiations. Baden-Württemberg's pharmaceutical cluster hosts contract oligonucleotide manufacturers supplying conjugation chemistry to siRNA developers.
Japan
PMDA's sakigake designation accelerates priority review for amyloidosis therapies addressing unmet neurological indications. Tokyo and Osaka academic medical centers maintain dedicated amyloidosis registries generating real-world evidence for label expansion. METI's healthcare export promotion program supports Japanese pharmaceutical partnerships with US RNA therapy developers.
United Kingdom
NHS England's specialized commissioning frameworks concentrate vutrisiran access through designated amyloidosis centers in London and Manchester. The MHRA's reliance procedure post-Brexit maintains alignment with EMA scientific opinions while enabling independent UK marketing authorizations. Cambridge's biotechnology corridor hosts siRNA delivery chemistry research programs feeding into clinical-stage pipelines.
Switzerland
University Hospital Zurich operates as a referral hub for cardiac amyloidosis patients across Alpine regions lacking local diagnostic capacity. Swissmedic's expedited access pathways for orphan medicines compress time-to-reimbursement for high-cost RNA therapies. Basel's pharmaceutical research cluster maintains oligonucleotide synthesis expertise serving European siRNA developers.
Vutrisiran Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in conjugation chemistry and GalNAc ligand supply. The vutrisiran competitive structure concentrates around end-to-end siRNA developers with captive manufacturing, with second movers constrained by patent thickets and delivery chemistry expertise gaps. Three archetypes dominate: integrated RNA therapy platforms, antisense chemistry specialists, and large-cap biopharma licensing partners. Capacity expansion and strategic patent licensing constitute the primary competitive moves reshaping positioning.
Among integrated platform developers, Alnylam Pharmaceuticals, Inc. anchors the GalNAc-siRNA conjugation tier with end-to-end production infrastructure. Ionis Pharmaceuticals occupies a position within antisense chemistry specialization, while Pfizer Inc. represents large-cap biopharma entry through distribution scale and rare disease licensing arrangements. These three exemplify the archetype segmentation governing competitive dynamics in hepatocyte-targeted gene silencing.
| Leading Market Players |
|---|
| Ultragenyx Pharmaceutical |
| Teva Pharmaceuticals |
| Alnylam Pharmaceuticals, Inc. |
| Ionis Pharmaceuticals |
| Sanofi |
| AstraZeneca |
| Merck & Co., Inc. |
| Regeneron Pharmaceuticals |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive GalNAc-siRNA conjugation capacity utilization at Alnylam's Massachusetts manufacturing complex shapes both supplier pricing discipline and buyer procurement posture across the RNA therapeutic value chain. Full-load operation at this single-source facility tightens spot-market availability for rival developers while reinforcing premium pricing for contracted volume allocations.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures where reimbursement outcomes determine contract terms between specialty pharmacies and RNA therapy developers. Price differentiation stems from FDA orphan drug exclusivity tiers and volume scale through integrated delivery network commitments. Pricing pressure intensifies in cardiac amyloidosis indications as confirmatory trial costs compound with expanded patient screening investments. Academic medical centers exhibit lowest price sensitivity due to bundled research funding, while community hepatology clinics face acute margin compression from Medicare Part B versus Part D classification disputes.
Supply Chain Analysis
Upstream N-acetylgalactosamine ligand production draws from contract manufacturers concentrated in Germany, Switzerland, and the United States, with Baden-Württemberg's pharmaceutical cluster hosting critical oligonucleotide synthesis expertise. Raw material dependencies center on phosphoramidite chemistries, high-purity solvents, and specialized chromatography resins. Single-source vulnerability pervades the GalNAc conjugation tier where three manufacturers control essential hepatocyte-targeting ligand supply. Distribution runs through specialty pharmacy networks led by Accredo and CVS Specialty, displacing traditional buy-and-bill oncology models with risk-sharing arrangements that consolidate patient management under pharmacy benefit structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring-revenue conversion is highest among patient support and remote monitoring services, where home administration training programs and telehealth oversight platforms expand faster than drug product sales alone. This service-attach layer captures margin outside infusion center fee structures while deepening prescriber loyalty.
For Market Incumbents: Build regulatory exclusivity moats through accelerated approval pathway mastery and confirmatory trial infrastructure that rivals cannot replicate. Secure captive GalNAc-siRNA manufacturing capacity in Massachusetts or Basel to defend against second-mover entrants constrained by patent thickets. Expand backward integration into oligonucleotide synthesis to reduce dependence on German and Swiss contract manufacturers facing talent scarcity. For New Entrants and Emerging Players: Build out wild-type ATTR cardiac amyloidosis positioning ahead of HELIOS-B trial readouts, where diagnostic screening expansion outpaces hereditary testing penetration. Target community hepatology clinics in Florida and California underserved by Alnylam's limited distribution network. Pursue licensing arrangements with large-cap biopharma to access specialty pharmacy distribution scale without captive infrastructure investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform developers with end-to-end manufacturing and companion diagnostic capabilities. Long-term viability favors integrated RNA therapy specialists over antisense chemistry component suppliers facing patent cliff exposure. Watch FDA confirmatory trial completion rates as the primary inflection signal for label expansion sustainability and reimbursement durability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive GalNAc-siRNA conjugation capacity at Alnylam's Cambridge complex secures supply security against contract manufacturer concentration. |
| Regulatory Approval Pathway | FDA accelerated approval and orphan drug designations compress development timelines while granting seven-year market exclusivity for hereditary ATTR. |
| Pipeline Diversification | Wild-type ATTR cardiac expansion through HELIOS-B positions vutrisiran for a population tenfold larger than hereditary indications. |
| Strategic Partnership | Specialty pharmacy risk-sharing agreements with Accredo and CVS Specialty consolidate patient management under pharmacy benefit structures. |
| Licensing Agreement | Large-cap biopharma distribution partnerships extend reach into rare disease RNA therapeutics without captive manufacturing investment. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at major payers, and hospital procurement managers specializing in amyloidosis therapeutics. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov registries, and CMS Medicare reimbursement databases. Bottom-up patient volume estimates across hereditary and wild-type ATTR segments were triangulated against top-down RNA therapeutic market assessments.
Calibration across the projection horizon employed multi-dimensional segmentation modeling by treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from patient epidemiology projections, diagnostic screening adoption curves, and reimbursement intensity assumptions. Forecast inputs incorporated technetium pyrophosphate scintigraphy protocol expansion at Mayo Clinic and Cleveland Clinic, alongside EMA PRIME eligibility timelines for European market entry.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by antisense chemistry specialists or sudden regulatory pathway modifications would shift outcomes materially. Cross-checking against FDA confirmatory trial completion benchmarks and national amyloidosis registry enrollment rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
PAP and Paracetamol Market