
 Germany X by Wire Systems Market | 2026-2036
Germany X by Wire Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Germany X by Wire Systems Market Foresight
Electromechanical actuator architectures with redundant signal paths is reshaping how chassis control systems are engineered and validated for production. ZF Friedrichshafen AG leverages its integrated mechatronics portfolio to anchor development of complete steer-by-wire modules for European OEM platforms. Robert Bosch GmbH sustains heavy R&D investment in sensor fusion layers that bridge brake-by-wire and steering domains. Continental AG dominates the electrohydraulic braking segment through captive semiconductor sourcing and in-house ASIC fabrication.
X by wire systems replace mechanical linkages with electronic control units, actuators, and multiplexed data buses that transmit driver intent via digital signals with sub-100-millisecond latency; these architectures eliminate hydraulic fluids and mechanical columns to reduce vehicle weight while enabling software-defined chassis tuning for autonomous operation. Steering control modules command the largest margin pool among product types due to their safety-critical redundancy requirements and patent-protected torque-feedback algorithms. Sensor fusion technology is displacing single-sensor electromechanical systems in premium applications where lidar and camera inputs must reconcile with driver steering commands in real time.
The KBA enforces UN ECE R79 and R13-H type approvals that mandate fallback modes for steering and braking failures, compelling suppliers to certify dual-channel ECU architectures. Germany's implementation of the EU AI Act through BSI conformity assessments will impose additional algorithmic transparency requirements on autonomous steering functions. OEM manufacturers and Tier-1 suppliers must monitor how KBA interprets AI Act risk classifications for Level 3+ steering automation, as this determines whether existing validation protocols satisfy emerging compliance thresholds or demand expanded field-testing regimes.
Market Dynamics
German OEMs are accelerating steer-by-wire adoption in premium passenger vehicles as the EU AI Act and KBA type-approval requirements tighten functional safety standards for autonomous-capable systems. This regulatory convergence is forcing suppliers to redesign validation protocols and redundant ECU architectures from the ground up.
Growth Catalysts
- EU AI Act implementation:The BSI conformity assessment framework mandates algorithmic transparency for Level 3+ steering automation, creating compliance-driven replacement cycles for legacy chassis control modules.
- Baden-Württemberg supplier corridor concentration:Stuttgart's mechatronics ecosystem provides captive access to precision actuator manufacturing and embedded software talent pools.
- Electromechanical actuator architectures:Redundant signal path designs enable software-defined chassis tuning that eliminates hydraulic maintenance and reduces vehicle weight.
Market Restraints
- Semiconductor supply concentration:ASIC fabrication for safety-critical ECUs depends on a limited foundry base, exposing Tier-1 suppliers to allocation volatility.
- UN ECE R79 certification complexity:Dual-channel fallback mode requirements extend validation timelines and inflate development budgets for steer-by-wire platforms.
- Mechanical linkage residual demand:Commercial vehicle segments continue specifying hydraulic steering for extreme-duty cycles, constraining electromechanical penetration.
Strategic Opportunities
- Sensor fusion convergence:Lidar and camera input reconciliation with driver steering commands creates premium-tier differentiation for autonomous-capable chassis systems.
- North Rhine-Westphalia logistics corridor:Heavy-duty fleet operators in the Ruhr industrial zone present untapped demand for brake-by-wire retrofit programs.
- CSRD disclosure mandates:Sustainability reporting requirements favor suppliers with transparent semiconductor sourcing and circular actuator design.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates at established suppliers, constraining new entrant scaling.
- Legacy platform integration friction:Retrofitting x-by-wire modules onto existing vehicle architectures demands custom mechanical adapters and extended calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany X by Wire Systems Market |
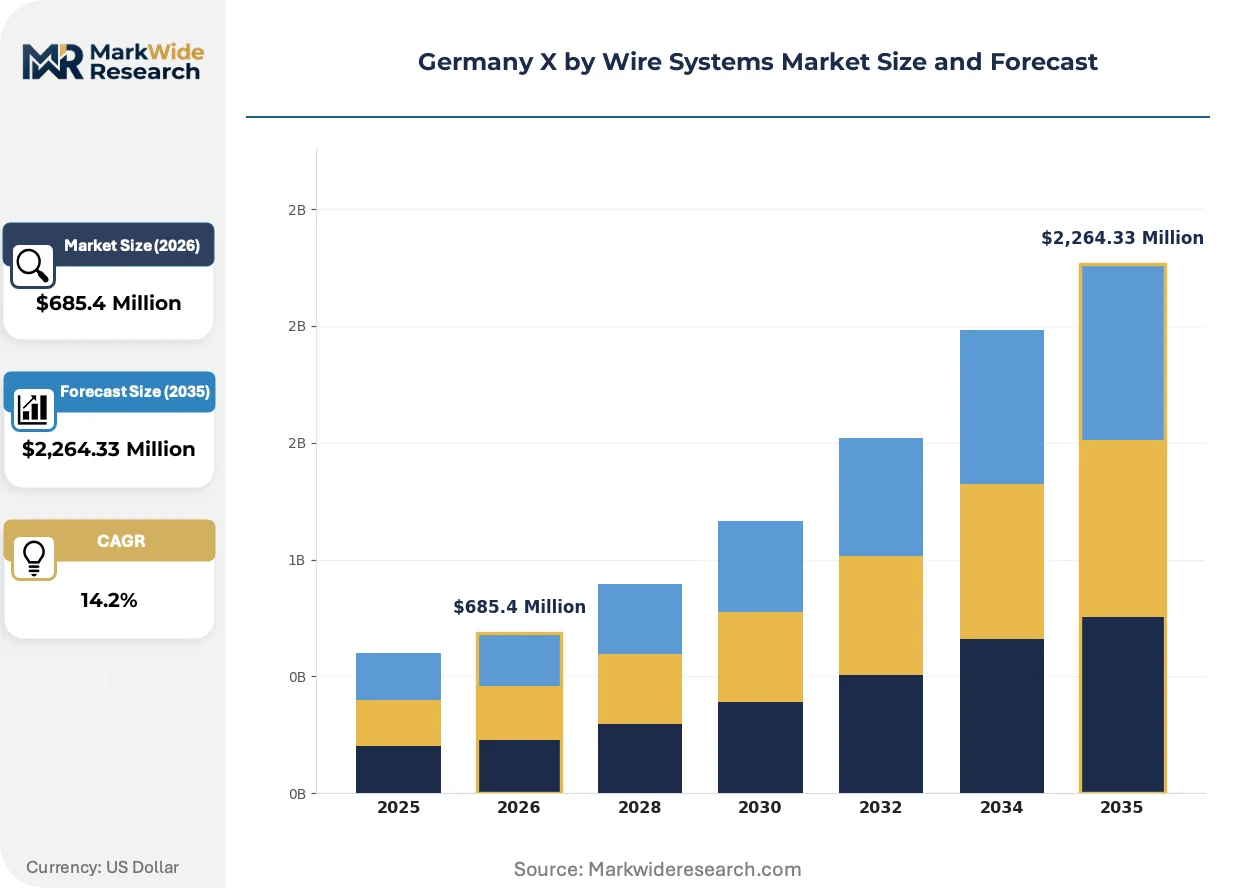
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steering Control, Braking Control, Throttle Control, Parking Assistance, Transmission Control Technology: Electromechanical, Hydraulic, Electrohydraulic, Digital Control, Sensor Fusion Application: Passenger Vehicles, Commercial Transport, Agricultural Equipment, Construction Machinery, Emergency Vehicles End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Diagnostic Service Providers |
| Companies Covered | ZF Friedrichshafen AG, Robert Bosch GmbH, Continental AG, Nissan Motor Corporation, Nexteer Automotive, Infineon Technologies, JTEKT Corporation, Schaeffler AG, Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany X by Wire Systems Market Shifts & Advancements
Electromechanical architectures are actively displacing hydraulic and mechanical linkages across German OEM platforms. Three convergent developments are compressing development cycles and redefining competitive differentiation in chassis control systems.
Redundant torque-feedback algorithms are rendering obsolete single-channel electromechanical steering modules that lack real-time sensor fusion capabilities. Premium passenger vehicle platforms in Baden-Württemberg are adopting these architectures at accelerated validation paces. The technology is rendering obsolete conventional hardware-in-the-loop testing regimes that cannot simulate multimodal sensor reconciliation.
KBA enforcement of UN ECE R79 and R13-H type approvals now mandates documented fallback modes for steering and braking failures. This regulatory pressure compels suppliers to certify dual-channel ECU architectures with independent power domains. Level 3+ automation programs face the steepest compliance burden as KBA interprets AI Act risk classifications for algorithmic steering functions.
Fleet procurement patterns in commercial vehicle segments are compressing supplier qualification cycles from 36 months to 18 months. Large logistics operators in Bavaria and Lower Saxony are unbundling after-sales service contracts from hardware supply agreements. This behavioral shift is most visible among long-haul freight carriers seeking outcome-based chassis availability guarantees rather than component warranties.
Germany X by Wire Systems Market Segmentation
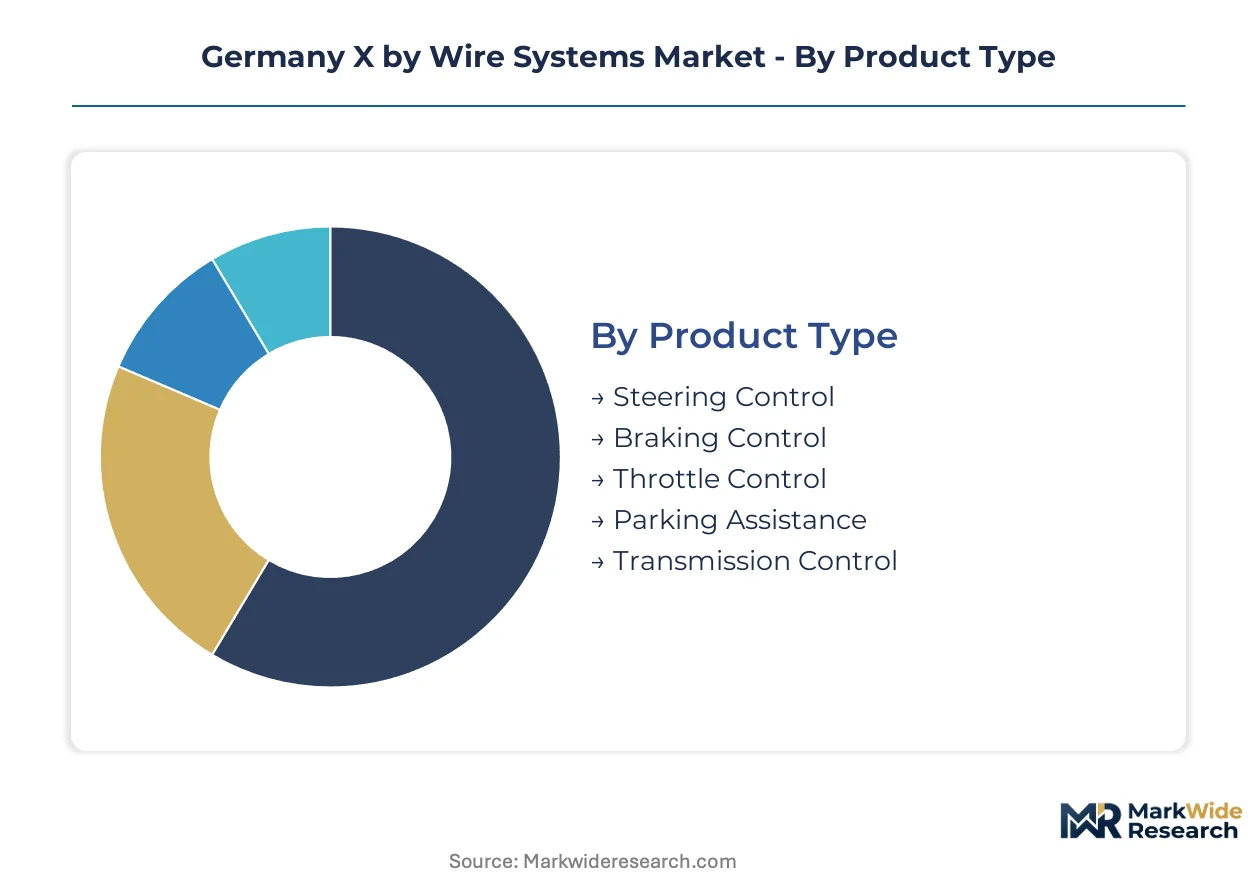
X-by-wire architectures fragment across five distinct product categories, each governed by divergent replacement cycles and certification burdens. Understanding velocity differentials between steering modules and transmission controllers shapes supplier capacity planning and R&D allocation decisions.
Product Type:
Steering control modules command the longest validation timelines due to ASIL-D functional safety requirements, while parking assistance systems turn over fastest as software-defined feature sets iterate quarterly.
- Steering Control:Torque-feedback actuators with redundant signal paths eliminate mechanical columns for autonomous-capable platforms. Premium passenger vehicle programs in Baden-Württemberg concentrate procurement for steer-by-wire modules as KBA tightens UN ECE R79 certification timelines.
- Braking Control:Electrohydraulic and fully electromechanical architectures displace hydraulic circuits through weight reduction and regenerative energy recovery integration. Commercial transport fleets in Bavaria are retrofitting brake-by-wire systems to meet CSRD-linked sustainability reporting mandates.
- Throttle Control:Drive-by-wire electronic throttle bodies with position sensor redundancy.
- Parking Assistance:Automated steering actuation for perpendicular and parallel maneuvering.
- Transmission Control:Shift-by-wire actuators replacing mechanical linkages in multi-speed gearboxes.
Steering control dominates installed base value. Parking assistance is where expansion concentrates.
Technology:
Cost tiers stratify sharply between legacy hydraulic systems and sensor-fusion platforms requiring lidar-camera reconciliation.
- Electromechanical:Direct electric actuation with brushless motors and Hall-effect position sensing eliminates fluid maintenance. OEM manufacturers specify these architectures for new passenger vehicle platforms to reduce assembly complexity and enable over-the-air calibration updates.
- Sensor Fusion:Multi-modal input reconciliation combining lidar, camera, and driver intent signals demands specialized ECU architectures. Premium autonomous programs are concentrating demand here as KBA interprets EU AI Act algorithmic transparency requirements for Level 3+ steering functions.
- Hydraulic:Conventional fluid-power actuation for extreme-duty commercial applications.
- Electrohydraulic:Hybrid architectures retaining hydraulic power with electronic valve control.
- Digital Control:Multiplexed data bus architectures with deterministic latency guarantees.
Electromechanical systems anchor volume production. Sensor fusion commands the steepest expansion trajectory.
Application:
Passenger vehicle segments absorb the majority of electromechanical actuator supply, while commercial transport and off-road equipment retain hydraulic specifications for durability cycles.
- Passenger Vehicles:Premium and luxury platforms drive steer-by-wire adoption with redundant torque-feedback algorithms. Stuttgart-based OEMs are accelerating validation paces for autonomous-capable chassis systems ahead of EU AI Act implementation.
- Commercial Transport:Long-haul freight and urban delivery fleets in North Rhine-Westphalia are unbundling hardware supply from outcome-based service contracts. This procurement shift favors brake-by-wire retrofit programs with availability guarantees rather than component warranties.
- Agricultural Equipment:Autonomous tractor platforms with GPS-guided steering actuation.
- Construction Machinery:Electrohydraulic control for excavator and loader implement management.
- Emergency Vehicles:Specialized brake-by-wire systems for pursuit and rescue vehicle dynamics.
Passenger vehicles dominate current installed base. Commercial transport is gaining share fastest.
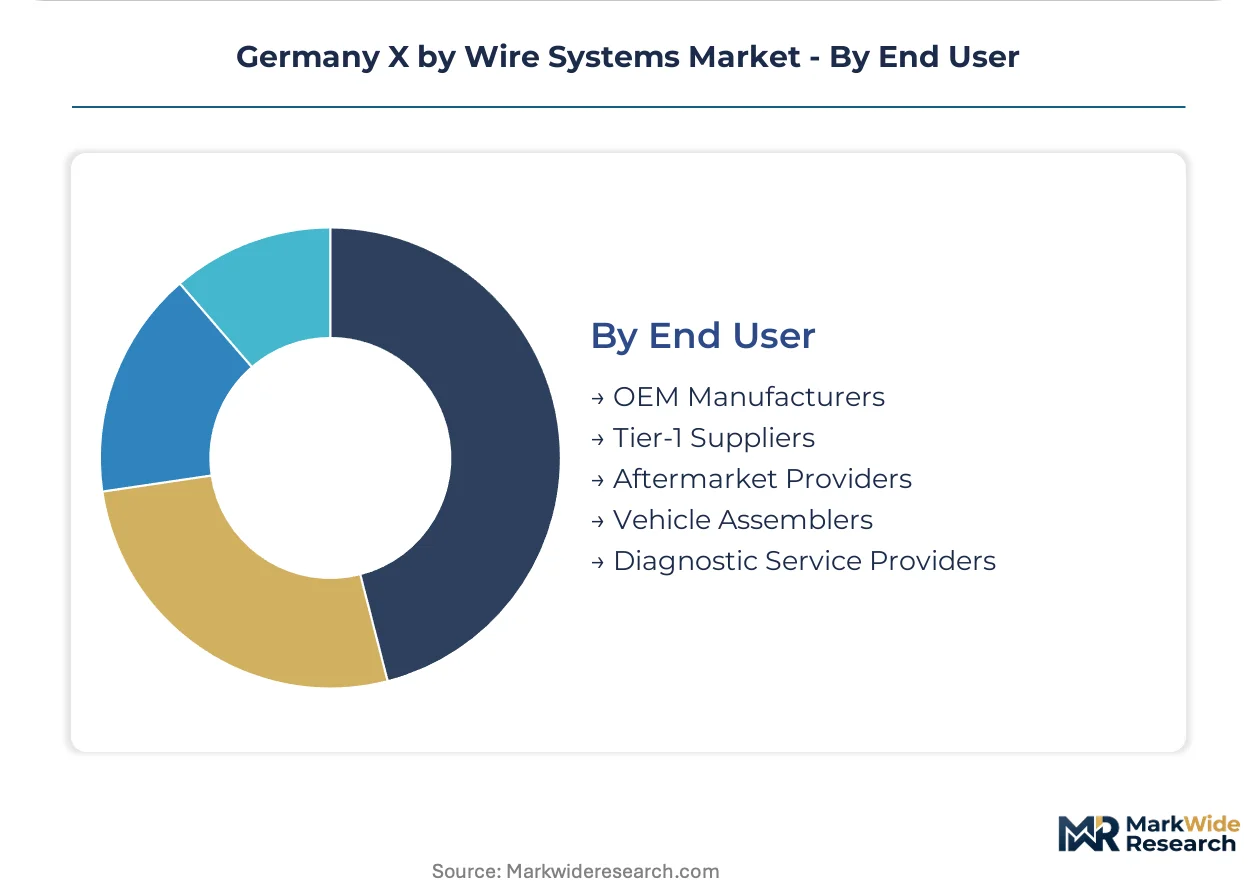
End User:
Supply concentration diverges between captive OEM development programs and fragmented aftermarket service networks.
- OEM Manufacturers:In-house chassis control development for proprietary vehicle platforms with custom ECU architectures. These programs concentrate in Baden-Württemberg and Bavaria, leveraging proximity to precision actuator manufacturing clusters.
- Tier-1 Suppliers:Modular system integration for multiple OEM platforms with standardized validation protocols. Functional safety engineer scarcity at this tier constrains scaling for new steer-by-wire entrants seeking ISO 26262 ASIL-D certification.
- Aftermarket Providers:Retrofit kit distribution for legacy vehicle brake and steering upgrades.
- Vehicle Assemblers:Contract manufacturing operations integrating supplied x-by-wire modules.
- Diagnostic Service Providers:Specialized calibration and fault-code resolution for electronic chassis systems.
OEM manufacturers control platform specification. Tier-1 suppliers are where competitive positioning shifts most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's X-by-wire systems trade flows reveal a pronounced export surplus in precision electromechanical actuators, with domestic absorption concentrated in southwestern automotive clusters and northern logistics corridors importing retrofit brake systems for commercial fleets.
Baden-Württemberg
Stuttgart's mechatronics ecosystem anchors steer-by-wire development for premium passenger platforms. KBA type-approval enforcement under UN ECE R79 compresses validation timelines for dual-channel ECU architectures. The region's supplier corridor around Böblingen and Sindelfingen concentrates redundant torque-feedback algorithm development.
Bavaria
Munich-based OEMs accelerate sensor-fusion integration for Level 3+ autonomous steering functions. BSI conformity assessments for EU AI Act algorithmic transparency requirements reshape procurement specifications for chassis control modules. Ingolstadt's manufacturing belt hosts captive semiconductor sourcing programs for safety-critical ASIC fabrication.
North Rhine-Westphalia
Ruhr industrial zone logistics operators drive brake-by-wire retrofit demand for heavy-duty fleet sustainability compliance. CSRD disclosure mandates favor suppliers with transparent actuator sourcing and circular design credentials. Düsseldorf-Cologne corridor procurement offices unbundle hardware supply from outcome-based chassis availability contracts.
Lower Saxony
Commercial vehicle manufacturers in Wolfsburg and Hanover retain hydraulic steering specifications for extreme-duty cycles while testing electromechanical alternatives. UN ECE R13-H braking certification requirements extend development budgets for dual-channel fallback architectures. Brunswick's research institutes collaborate on ISO 26262 ASIL-D functional safety engineer training programs.
Hesse
Frankfurt's financial and logistics hub channels aftermarket diagnostic service demand for electronic chassis calibration. The state's central location supports distribution networks reaching eastern European assembly plants. Darmstadt's technical universities supply embedded software talent pools for multiplexed data bus architecture development.
Germany X by Wire Systems Market Competitive Landscape
On the supply side, the industry is tiered between integrated mechatronics conglomerates and specialized actuator fabricators. Three strategic archetypes dominate: vertically integrated chassis module suppliers, captive semiconductor-ECU integrators, and regional brake-steering specialists. Competitive positioning hinges on M&A activity consolidating sensor fusion capabilities and strategic partnerships securing foundry allocation for safety-critical ASIC production.
Within the integrated tier, ZF Friedrichshafen AG, Robert Bosch GmbH, and Continental AG occupy anchor positions representing distinct engineering philosophies. ZF exemplifies complete steer-by-wire module development through proximity to Stuttgart OEM platforms. Bosch anchors sensor fusion convergence across braking and steering domains. Continental represents electrohydraulic braking segmentation through in-house semiconductor fabrication control.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Continental AG |
| Nissan Motor Corporation |
| Nexteer Automotive |
| Infineon Technologies |
| JTEKT Corporation |
| Schaeffler AG |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for safety-critical ASICs feeds directly into margin capture at Tier-1 module integrators serving Stuttgart-based OEM platforms. KBA certification timelines for UN ECE R79 dual-channel architectures compress supplier pricing power while amplifying procurement premiums for pre-validated redundant ECU designs.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure with volume-scale and certification-grade differentiation. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and non-safety-critical economy levels separates premium steer-by-wire modules from standard brake-by-wire units. Cost compression in electromechanical actuator tiers is intensifying because captive semiconductor sourcing programs at Continental and Bosch constrain independent foundry allocation. Fleet procurement offices in North Rhine-Westphalia exhibit highest price sensitivity due to unbundled hardware-service contracts, while Munich-based premium OEMs remain least sensitive given autonomous-capable platform roadmaps.
Supply Chain Analysis
EU dual-use technology export controls on advanced lidar sensor arrays and high-precision torque-feedback algorithms limit cross-border flows to non-EU automotive assemblers. Geographic supply concentration centers on Germany for ECU module integration, Taiwan for safety-critical ASIC fabrication, and South Korea for brushless motor actuators. Raw material dependencies include rare-earth magnets for motor assemblies, silicon carbide substrates for power electronics, and specialized epoxy resins for ECU encapsulation. Single-source vulnerability at the 7nm automotive semiconductor node poses structural risk. Distribution runs through captive OEM supply chains in Baden-Württemberg and modular Tier-1 supplier networks serving multiple platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German X-by-wire systems sit in early-cycle expansion as EU AI Act implementation forces Level 3+ automation compliance-driven replacement cycles across legacy chassis control architectures.
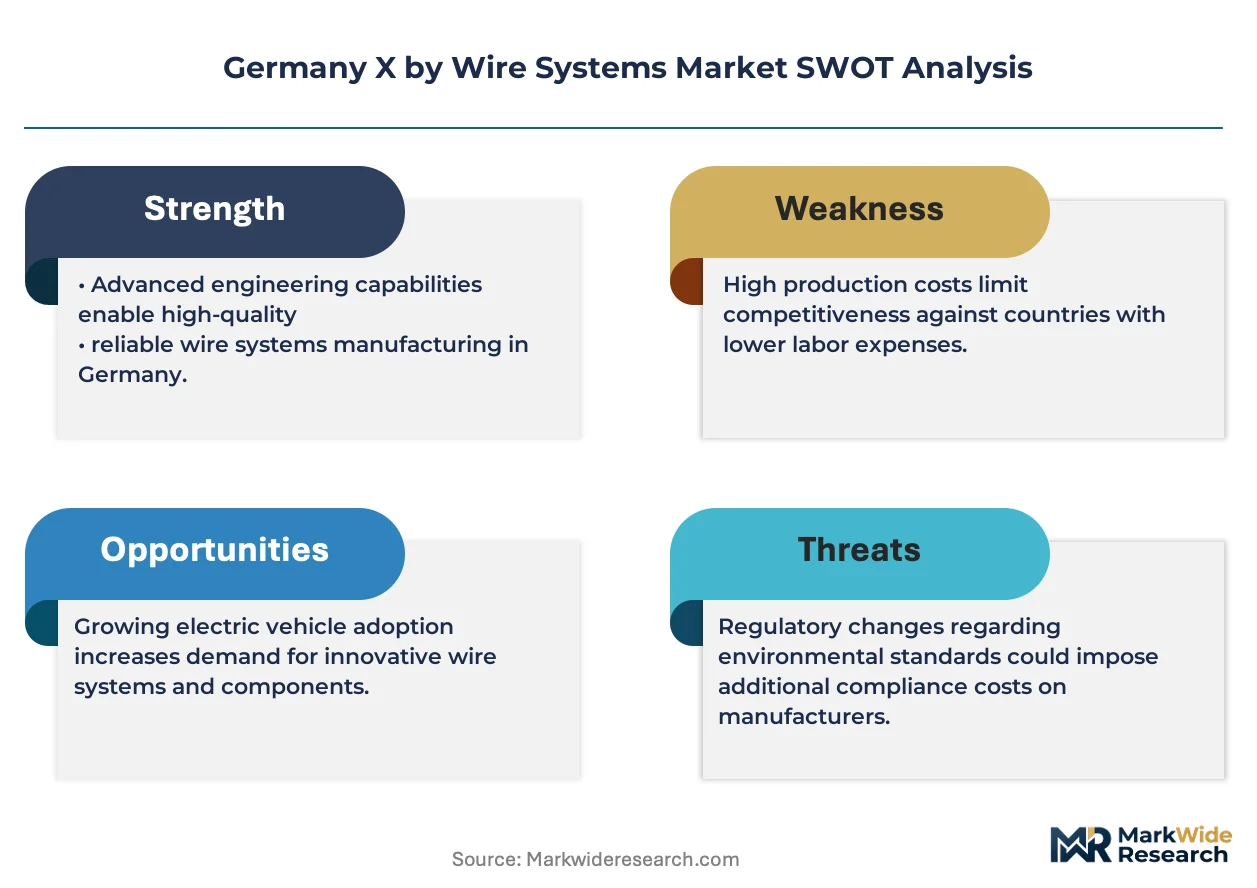
For Market Incumbents: Harden dual-channel ECU validation protocols against emerging BSI conformity assessment timelines for algorithmic transparency. Deepen backward integration into captive semiconductor sourcing to defend margin position against foundry allocation volatility. Consolidate sensor fusion capabilities through targeted acquisition of lidar-camera reconciliation specialists before KBA finalizes AI Act risk classifications for autonomous steering functions.
For New Entrants and Emerging Players: Establish a beachhead in brake-by-wire retrofit programs for North Rhine-Westphalia heavy-duty logistics fleets seeking CSRD-linked sustainability compliance. Target commercial transport procurement offices that have unbundled hardware supply from outcome-based availability guarantees. Pursue ISO 26262 ASIL-D certification partnerships with Brunswick research institutes to bypass functional safety engineer scarcity constraints.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-fusion platform development as lidar-camera-ECU integration demands expand R&D burn rates. Long-term viability favors vertically integrated module suppliers with in-house ASIC fabrication control and Stuttgart OEM platform relationships. Watch KBA interpretation of EU AI Act risk classifications for Level 3+ steering automation as the inflection signal determining whether existing validation protocols satisfy compliance thresholds or demand expanded field-testing regimes.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Multi-modal lidar-camera reconciliation enables Level 3+ autonomous steering compliance under KBA AI Act assessments. |
| Captive ASIC Fabrication Investment | In-house semiconductor sourcing insulates Continental and Bosch from Taiwan foundry allocation volatility. |
| Brake-by-Wire Retrofit Program Launch | Ruhr logistics fleet procurement unbundling creates aftermarket entry for sustainability-linked chassis upgrades. |
| ISO 26262 ASIL-D Certification Partnership | Brunswick institute collaborations address functional safety engineer scarcity constraining new entrant scaling. |
| EU AI Act Compliance Roadmap | BSI conformity assessment preparation determines whether existing validation protocols require expanded field-testing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of KBA type-approval documentation, UN ECE regulatory filings, and EU AI Act implementation guidance. Primary interviews engaged chassis control engineering directors at Stuttgart OEMs, Tier-1 supplier procurement heads, functional safety certification specialists, and fleet operations managers across Bavaria and North Rhine-Westphalia. Secondary sources included vehicle production databases, IHS Markit registration data, semiconductor trade flow records, and ASIL-D certification registries. Bottom-up unit economics triangulate against top-down OEM platform deployment schedules.
Forecast inputs span vehicle class segmentation across premium passenger and commercial transport categories, propulsion architecture differentiation between battery-electric and hybrid platforms, content-per-vehicle trajectories for steer-by-wire versus brake-by-wire modules, and regional production cluster concentration in Baden-Württemberg and Bavaria. CAGRs derive from installed base turnover modeling against KBA certification timeline compression. Industry-specific inputs include UN ECE R79 validation pace assumptions and EU AI Act implementation sequencing across BSI conformity assessments.
Stress conditions across semiconductor foundry allocation volatility, KBA regulatory timeline acceleration, and commercial fleet procurement contract unbundling were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on autonomous-capable platform deployment rates and functional safety engineer supply constraints. Material shifts in KBA interpretation of AI Act risk classifications for Level 3+ steering automation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market