
 Stepper Motors Market | 2026-2036
Stepper Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Stepper Motors Market Intelligence
The provision of integrated motion control solutions is reshaping competitive positioning away from simple component sales. Nidec Corporation leverages its extensive manufacturing scale to offer a broad portfolio of motor technologies. Siemens AG integrates stepper motors into its larger industrial automation and digitalization platforms. Parker Hannifin Corporation specializes in high-performance systems for demanding aerospace and medical applications, focusing on precision and reliability.
A stepper motor is a brushless DC electric motor that rotates in precise, discrete increments. Its position can be controlled accurately without a feedback mechanism, relying on digital pulses to command movement through a specific step angle. Hybrid stepper motors command the largest market share, offering a superior balance of torque, speed, and resolution for a wide range of uses. Demand from robotics and semiconductor equipment applications is accelerating, prioritizing motors with high accuracy and low vibration characteristics.
Compliance with standards like Europe's RoHS directive and CE marking is essential for market access, governing material use and electromagnetic compatibility. In China, GB standards dictate performance and safety requirements for industrial motors. Global manufacturers often adhere to ISO 9001 for quality management systems. Future product development will need to reconcile demands for higher torque and speed with emerging energy efficiency regulations across key industrial markets.
Market Dynamics
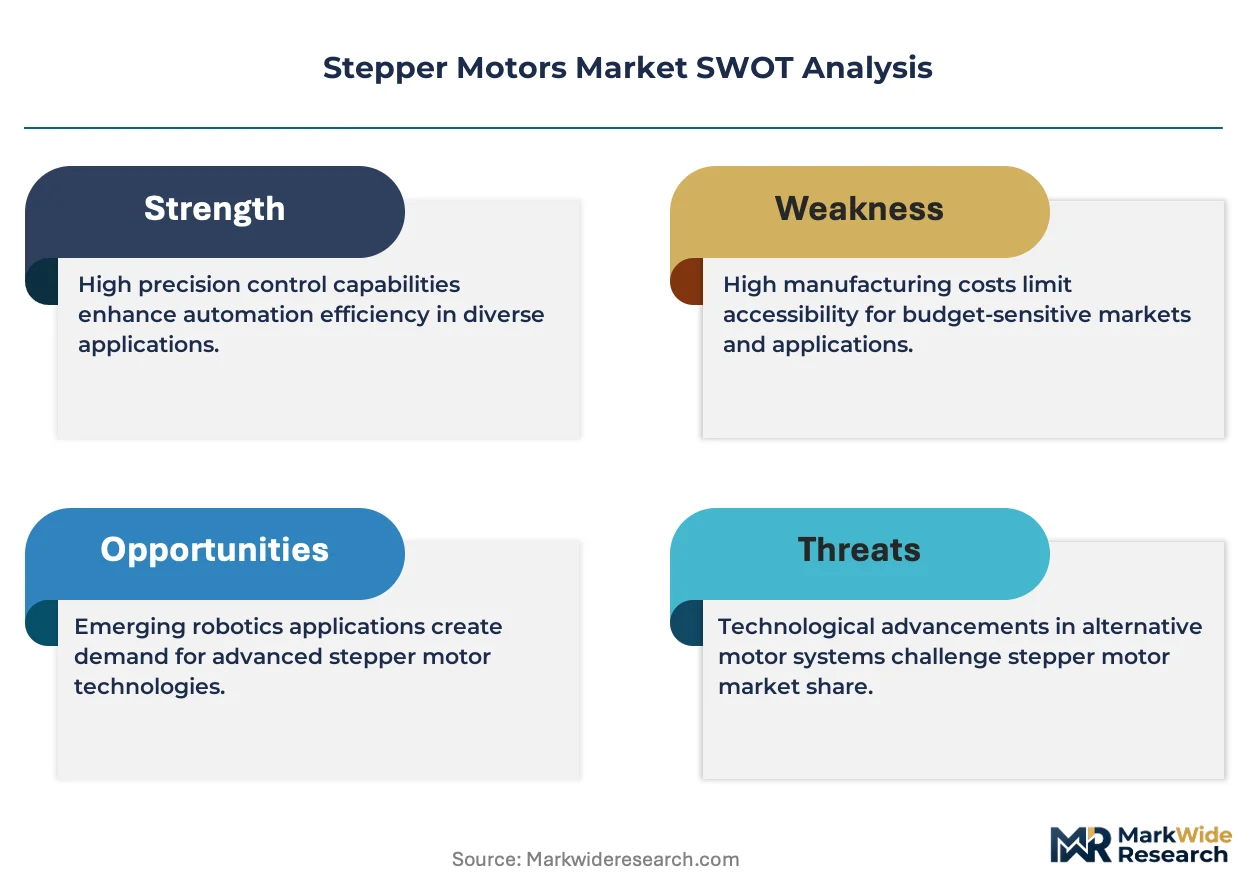
The central force shaping the stepper motor market is the dual demand for extreme precision and miniaturization, driven primarily by the semiconductor and medical device industries. This pressure compels innovation in motor design and control electronics to achieve finer resolution and lower vibration in increasingly compact form factors.
Growth Catalysts
- Hybrid Motor Technology:The superior balance of torque, speed, and step resolution offered by hybrid stepper motors drives their adoption in demanding applications like industrial robotics and 3D printing, where performance is critical.
- Semiconductor Expansion:Construction of new semiconductor fabrication plants, particularly in Taiwan, South Korea, and the United States, creates sustained demand for precision motion control systems in wafer handling and lithography equipment.
- Automation in Life Sciences:The push for automated laboratory equipment for diagnostics and drug discovery accelerates the need for small, accurate stepper motors in liquid handlers, sample analyzers, and robotic microscopes.
Market Restraints
- Input Cost Volatility:The market is sensitive to price fluctuations of rare-earth magnets, such as neodymium, which are critical components for high-torque motors and are subject to supply chain disruptions.
- Technical Limitations:Inherent issues like resonance at certain speeds and the potential for lost steps in open-loop systems can limit use in applications requiring the highest levels of dynamic performance and guaranteed positioning.
- Servo Motor Substitution:In applications where very high speeds, dynamic torque control, and absolute position feedback are non-negotiable, advanced servo motors present a significant substitution threat despite their higher cost.
Strategic Opportunities
- Integrated Smart Motors:Combining the motor, drive, and controller into a single, networkable unit creates opportunities in Industry 4.0 applications, simplifying machine design and enabling distributed control architectures.
- Medical Device Miniaturization:The development of smaller, more precise stepper motors for portable and implantable medical devices, such as infusion pumps and surgical tools, represents a high-value growth frontier.
- Energy Efficiency Mandates:Emerging energy efficiency standards for industrial equipment, such as those within the EU Green Deal, create an opportunity for optimized stepper systems that reduce power consumption.
Industry Challenges
- System Integration Complexity:Successfully integrating stepper motors into complex automation systems with various software platforms and communication protocols requires a high level of specialized engineering talent.
- Global Compliance Burden:Manufacturers face significant overhead in navigating and adhering to a patchwork of international regulations, including Europe's RoHS and CE marking and China's GB standards for safety.
- Motion Control Skill Gap:A shortage of engineers with expertise in both mechanical systems and digital control programming hinders optimal system design, implementation, and troubleshooting for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stepper Motors Market |
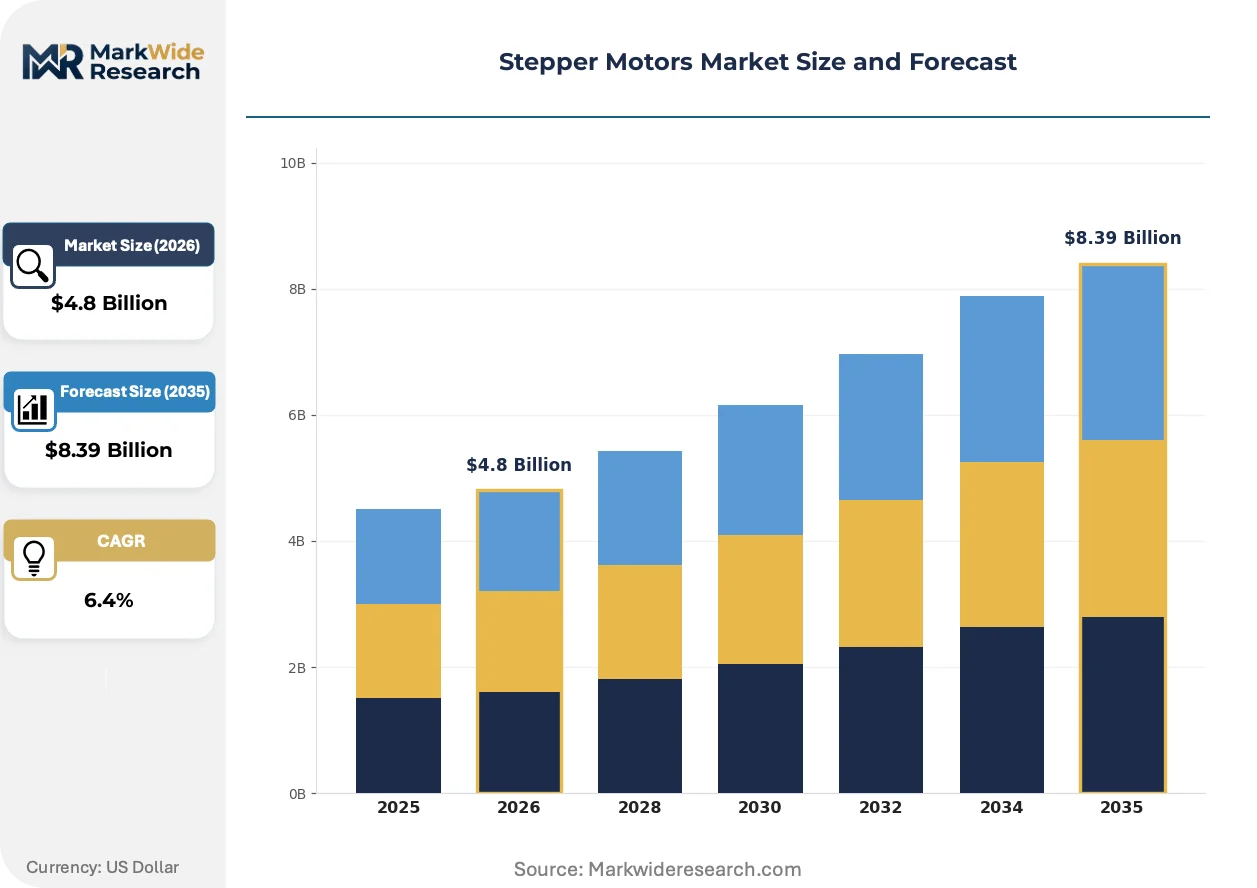
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Permanent Magnet, Hybrid, Variable Reluctance, Optical, Others Technology: Microstepping, Full Step, Half Step, Wave Drive, Bipolar, Unipolar Application: Robotics, Semiconductor Equipment, Automation Systems, Textile Machinery, Printing Equipment End User Industry: Aerospace, Consumer Electronics, Packaging, Medical Devices, Renewable Energy |
| Companies Covered | Sanyo Denki, Moons' Industries, Nidec Corporation, Parker Hannifin Corporation, Siemens AG, Oriental Motor, Applied Motion Products, Nanotec Electronic, Trinamic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stepper Motors Market Strategic Shifts & Innovations
The evolution from selling discrete components to providing intelligent, networked motion control systems is the dominant market trend. This shift prioritizes system-level performance, connectivity, and ease of integration over the specifications of the motor alone, altering both product development and go-to-market strategies.
Integrated stepper motors, which combine the motor, drive, and controller into a single compact unit, are gaining traction. End-users in automated packaging and laboratory automation are adopting these systems to simplify machine design, reduce wiring complexity, and shrink machine footprints. This integration is digitizing the motion control architecture, moving intelligence from centralized cabinets to the machine's periphery.
Europe's RoHS directive, which restricts hazardous substances in electrical equipment, continues to influence global manufacturing practices. The regulation forces motor producers to re-engineer components and qualify supply chains for compliant materials, impacting design and cost. The electronics and medical device sectors are most affected, requiring extensive documentation and certified components to maintain access in the EU.
Equipment manufacturers are increasingly sourcing complete motion control sub-assemblies rather than procuring individual motor components. This change in buying behavior often bypasses traditional component distributors in favor of direct partnerships with specialized system integrators or motor manufacturers. This is most prominent in the semiconductor and medical device industries, where system-level performance and reliability are paramount.
Stepper Motors Market Segmentation
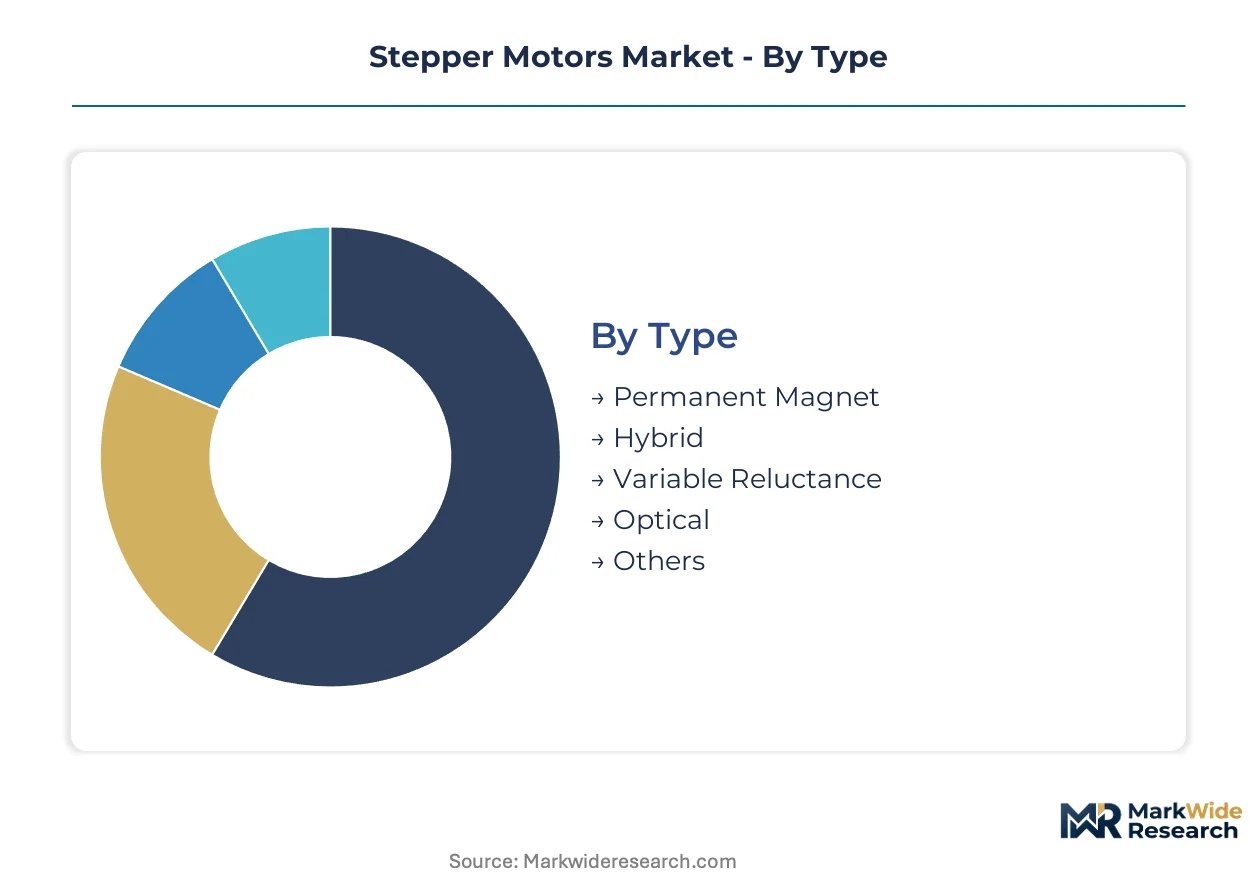
The segmentation of the stepper motors market illuminates distinct demand patterns and technological requirements across various end-use sectors. Understanding these segments is crucial for manufacturers to tailor product development and strategic market entry. This analysis details how different motor types, technologies, applications, and industries shape overall market dynamics.
Type:
The after-sales service intensity for stepper motors varies significantly across different motor types, influencing long-term operational costs and maintenance strategies for industrial users.
- Hybrid:These motors combine features of permanent magnet and variable reluctance types, offering superior torque, speed, and resolution. Robotics and semiconductor equipment demand these for critical performance.
- Permanent Magnet:Simpler construction and lower cost characterize these motors, suitable for moderate precision. They find widespread use in consumer electronics and simpler automation systems.
- Variable Reluctance:Simple design, high-speed, and lower torque/resolution, these motors suit less demanding industrial settings.
- Optical:Specialized for extremely high precision and fine angular resolution, critical for advanced scientific instruments and metrology.
- Others:Encompassing niche and emerging motor types, this segment caters to highly specialized industrial applications with unique performance.
By volume, Hybrid stepper motors lead. By growth pace, Optical stepper motors are ahead.
Technology:
Cost tiers for stepper motor technologies reflect the complexity of control and precision required, directly impacting overall system expenditure for integrators.
- Microstepping:This technology divides each full step into smaller microsteps, significantly increasing resolution and reducing vibration. Essential for semiconductor and medical device automation.
- Full Step:Each pulse moves the motor one full step, offering simplicity and cost-effectiveness. Prevalent in general automation and consumer electronics applications.
- Half Step:Offers twice the resolution of full step, balancing precision with control simplicity in various industrial uses.
- Wave Drive:Energizing one coil at a time, this method offers smooth movement and reduced torque for quiet operations.
- Bipolar:Uses two windings for higher torque, requiring a more complex driver circuit for robust industrial machinery.
- Unipolar:Uses a single winding with a center tap, allowing simpler driver design but offering lower torque.
The market structure favors Microstepping due to its superior precision, while Bipolar configurations address high torque requirements.
Application:
The intensity of application demands for stepper motors varies widely, dictating specific performance characteristics and integration challenges for equipment manufacturers.
- Robotics:Requires high precision, repeatability, and compact size for articulated arms and grippers in industrial and collaborative robots. Critical for automated manufacturing processes.
- Semiconductor Equipment:Demands extremely fine resolution and low vibration for wafer handling, lithography, and inspection tools. Concentrated in advanced manufacturing hubs like Taiwan.
- Automation Systems:Integrates stepper motors for various control tasks like positioning and material handling, supporting diverse industrial processes.
- Textile Machinery:Uses stepper motors for precise thread tension, needle positioning, and fabric movement, ensuring consistent quality.
- Printing Equipment:Relies on stepper motors for accurate paper feeding and print head positioning, supporting high-resolution output.
Specific end-use requirements for Semiconductor Equipment shape its demand profile, while Automation Systems represent a broad base of industrial adoption.
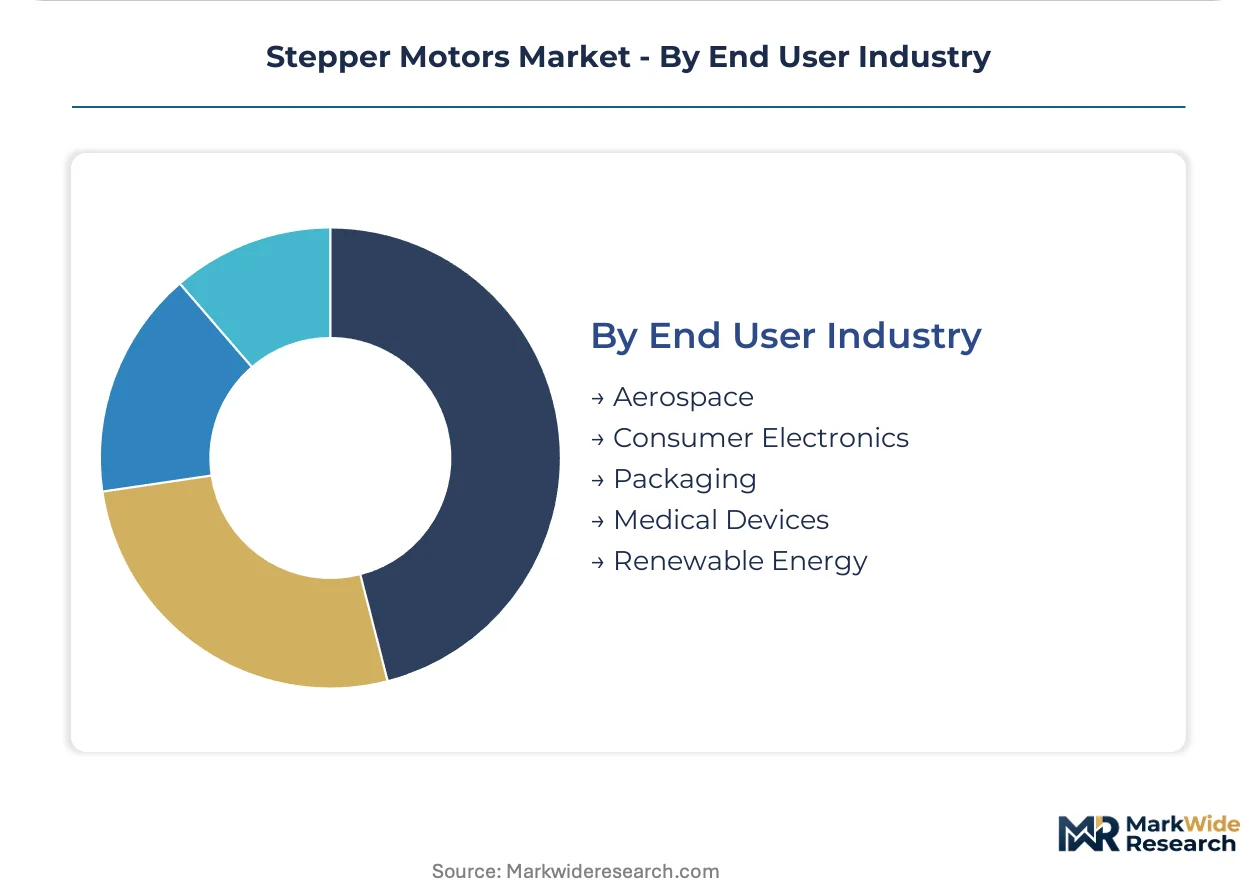
End User Industry:
Customer types across end-user industries exhibit distinct purchasing behaviors and regulatory compliance needs for stepper motor solutions.
- Medical Devices:Requires miniature, precise, and reliable motors for diagnostic equipment, surgical tools, and implantable pumps. This sector necessitates stringent compliance like ISO 13485.
- Aerospace:Demands high reliability, resistance to extreme conditions, and precision for flight control surfaces and instrumentation. Often involves custom engineering and rigorous certification.
- Consumer Electronics:Uses stepper motors for optical drives, printers, and camera focusing, prioritizing cost-effectiveness and compact form factors.
- Packaging:Employs stepper motors for accurate material feeding, cutting, and sealing in automated lines, supporting high-speed operations.
- Renewable Energy:Integrates stepper motors for precise solar panel tracking and wind turbine pitch control, optimizing energy capture efficiency.
The segment of Medical Devices commands premium pricing due to its stringent demands, whereas Consumer Electronics focuses on volume efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for stepper motors varies significantly, with consumer electronics applications exhibiting high price sensitivity, while the semiconductor and medical device sectors prioritize precision and reliability over cost. This bifurcation influences regional investment and manufacturing strategies. The global landscape reflects these diverse requirements for motion control solutions.
United States
Demand for advanced stepper motors in the United States stems from its robust aerospace and medical device industries. The FDA's stringent regulations for medical devices necessitate highly reliable and precise motor components. Silicon Valley and Boston's biotech corridor concentrate research and manufacturing for these sophisticated applications.
Germany
Germany's industrial automation sector drives significant demand for high-performance stepper motors, particularly in machine tools and robotics. Compliance with CE marking and the EU Green Deal mandates energy-efficient and compliant motor designs. Bavaria and Baden-Württemberg host major industrial engineering hubs, fostering innovation in motion control.
Taiwan
Semiconductor equipment manufacturing fuels Taiwan's demand for ultra-precision stepper motors for wafer fabrication. The government's investment in advanced chip production, supported by initiatives like the "5+2 Industrial Innovation Plan," strengthens this sector. Hsinchu Science Park remains a global center for semiconductor foundries and related equipment suppliers.
South Korea
South Korea's advanced electronics and robotics industries require stepper motors with superior accuracy and low vibration characteristics. The Ministry of Trade, Industry and Energy (MOTIE) supports R&D in smart factory technologies, including advanced motion control. Gyeonggi Province's technology clusters are central to the development and production of these sophisticated systems.
China
Rapid expansion in industrial automation and 3D printing applications drives China's substantial demand for stepper motors. GB standards for industrial motors ensure performance and safety requirements across diverse manufacturing sectors. The Yangtze River Delta and Pearl River Delta regions are key manufacturing bases for both stepper motor production and consumption.
Stepper Motors Market Key Industry Players
Vertically integrated specialists and component suppliers split the market for stepper motors, reflecting diverse customer requirements. The competitive landscape features a tiered structure, with a few large global players offering broad portfolios and numerous niche manufacturers focusing on specific applications. Strategic archetypes include automation platform providers, precision component manufacturers, and cost-optimized volume producers. Dominant competitive moves involve portfolio diversification and strategic partnerships to offer integrated solutions.
Companies offering integrated motion control solutions are reshaping competitive positioning, moving away from simple component sales. Nidec Corporation, a Japanese multinational, represents a global leader leveraging extensive manufacturing scale to offer a broad portfolio of motor technologies across various applications. Siemens AG, a German industrial technology company, exemplifies players integrating stepper motors into larger industrial automation and digitalization platforms, focusing on system-level performance. Additionally, Moons' Industries, a prominent Chinese manufacturer, occupies a strong position among dedicated motion control specialists, providing a range of stepper motor solutions for diverse industrial and consumer electronics segments. These firms collectively demonstrate the market's emphasis on both specialized component excellence and integrated system capability.
| Leading Market Players |
|---|
| Sanyo Denki |
| Moons' Industries |
| Nidec Corporation |
| Parker Hannifin Corporation |
| Siemens AG |
| Oriental Motor |
| Applied Motion Products |
| Nanotec Electronic |
| Trinamic |
Cost & Logistics Intelligence
Hsinchu Science Park's concentrated semiconductor manufacturing capacity significantly influences downstream pricing for ultra-precision stepper motors. This regional supply concentration creates a distinct pricing power for specialized component manufacturers serving advanced fabrication facilities.
Pricing Analysis
After-sales service contracts represent a critical revenue tier, driving long-term customer value beyond initial motor sales. The dominant pricing model is project-based, with significant customization affecting final costs. Price differentiation stems from precision grade and certification level, particularly for medical device and aerospace applications. Pricing softness reflects intense competition in general industrial automation segments. Consumer electronics applications exhibit the highest price sensitivity, while semiconductor equipment buyers prioritize performance over cost.
Supply Chain Analysis
Export controls on advanced manufacturing technologies could limit the flow of high-end stepper motor components. The supply chain draws from specific countries like China, Japan, and Germany for critical raw materials and finished components. Rare-earth magnets, such as neodymium, represent a significant raw material dependency, introducing commodity price volatility. Single-source vulnerability for specialized control electronics poses a structural risk. Downstream distribution typically runs through direct sales channels for complex systems and specialized distributors for individual motor components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stepper motors market is experiencing high-growth disruption, driven by the increasing demand for miniaturization and precision in semiconductor manufacturing.
For Market Incumbents: Entrench core market share by investing heavily in R&D for next-generation hybrid stepper motors with integrated control. Develop enhanced low-vibration capabilities to counter the threat from advanced servo motor substitution in dynamic applications. Leverage existing manufacturing scale to achieve cost efficiencies and expand presence in emerging industrial automation hubs. Prioritize certification investments to meet stringent regulatory requirements across medical and aerospace sectors.
For New Entrants and Emerging Players: Underpenetration in portable medical device applications offers a significant white-space opportunity. Focus on developing compact, energy-efficient stepper motors for automated laboratory equipment and surgical tools. Target regions with nascent but growing industrial automation sectors, such as Southeast Asia, with cost-effective, high-resolution solutions. A go-to-market angle centered on simplified integration and comprehensive technical support can attract small and medium-sized equipment manufacturers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component manufacturers with strong intellectual property in microstepping and hybrid motor designs. Focus on companies demonstrating robust R&D pipelines for integrated smart motors and advanced materials. The long-term viability of precision motion control solutions remains strong, driven by persistent automation trends. A key signal to watch is the adoption rate of Industry 4.0 platforms in discrete manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Smart Motors | Simplifies machine design and enables distributed control architectures for Industry 4.0 applications. |
| Expand Hybrid Motor Production | Addresses growing demand from robotics and semiconductor equipment for superior performance. |
| Invest in Advanced Material R&D | Reduces reliance on volatile rare-earth magnets and enhances motor efficiency. |
| Strengthen Medical Device Certifications | Ensures market access and commands premium pricing in a highly regulated, high-value sector. |
| Form Strategic Partnerships with Integrators | Offers complete motion control sub-assemblies, bypassing traditional component distribution channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive market perspective. Primary interviews included R&D directors, procurement managers, and plant engineers from semiconductor, medical device, and industrial automation firms. Secondary validation drew from technical specifications, regulatory filings (e.g., EU RoHS directives), and industry association reports. A multi-pronged approach ensured triangulation across diverse data points, employing both bottom-up and top-down estimation techniques.
The calibration approach involved a detailed analysis of historical market performance and future growth drivers across the modeling period. Segmentation dimensions modeled included motor type, technology, application, and end-user industry, alongside regional manufacturing capacities. Compound annual growth rates were derived through correlation with macroeconomic indicators and sector-specific capital expenditure trends. Forecast inputs specifically considered new semiconductor fabrication plant investments and medical device miniaturization trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or major technological shifts would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and raw material supply. Material shifts in global trade policies or critical component availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market