
 Printed Electronics in Healthcare Market | 2026-2036
Printed Electronics in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Electronics in Healthcare Market Insights
Homecare settings is reorganizing demand patterns as aging populations and remote patient monitoring programs shift purchasing authority from hospital supply chains to direct-to-consumer channels and outpatient service providers. Jabil Inc. leverages its healthcare manufacturing infrastructure to anchor large-scale production of flexible diagnostic substrates. DuPont de Nemours, Inc. sustains materials leadership through advanced conductive ink portfolios optimized for biocompatible applications. Medtronic plc competes by integrating printed electronic layers into minimally invasive device platforms, extending its therapeutic device ecosystem into conformable form factors.
Printed electronics in healthcare encompasses the additive manufacturing of functional electronic components—conductive traces, sensors, and power elements—onto flexible substrates such as polyethylene terephthalate or biodegradable polymers using processes operating below 150°C to preserve sensitive biological layers, primarily serving diagnostic, monitoring, and therapeutic applications where conformability and disposability outweigh traditional silicon performance. Inkjet printing dominates prototyping and customized low-volume outputs where digital patterning enables rapid design iteration without photomask costs, while screen printing anchors high-throughput manufacturing of standardized electrode configurations for glucose test strips and ECG patches. Gravure printing occupies the emerging middle ground for medium-run pharmaceutical packaging with embedded authentication and temperature-tracking circuitry, though equipment capital requirements constrain its penetration outside established converters.
The FDA governs printed electronics deployed in diagnostics and drug delivery through its combination product and medical device pathways, requiring biocompatibility testing under ISO 10993 and electrical safety validation that extends development cycles but creates compliance moats for qualified suppliers. EMA's Medical Device Regulation imposes parallel conformity assessment obligations across European markets, with notified bodies scrutinizing substrate degradation profiles and ink leachables for implantable or long-wear applications. Stakeholders must monitor convergence between pharmaceutical packaging serialization mandates and printed sensor traceability standards, as regulatory overlap between device and drug authorities reshapes vendor qualification requirements and contract manufacturing organization selection criteria.
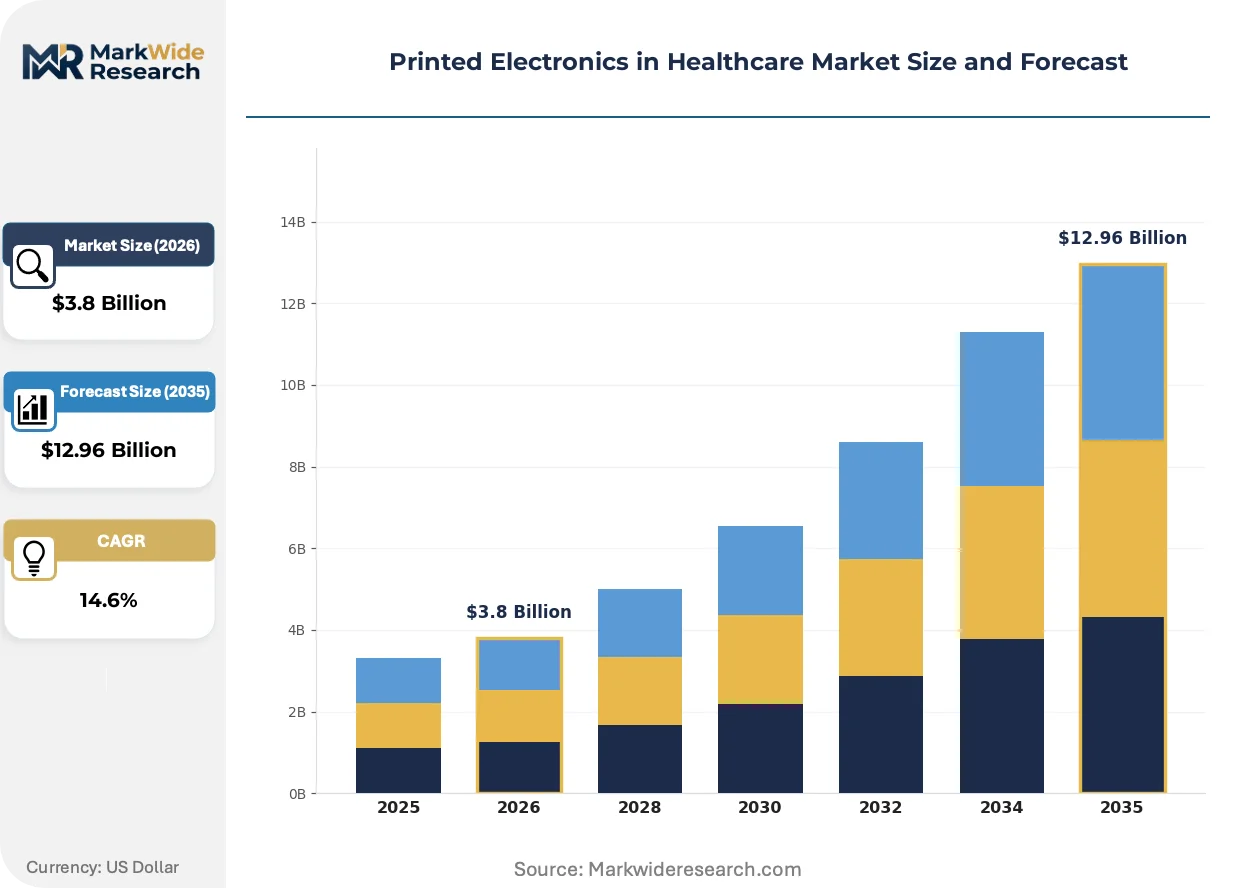
Market Dynamics
Roll-to-roll manufacturing scale-up in German industrial clusters is compressing unit economics for flexible diagnostic substrates while FDA combination product pathways reshape validation requirements for printed therapeutic platforms.
Growth Catalysts
- ISO 10993 biocompatibility frameworks:Standardized testing protocols reduce regulatory uncertainty for substrate-ink interactions, accelerating supplier qualification cycles for medical device integrators.
- Point-of-care diagnostic demand:Hospital procurement teams prioritize disposable biosensor formats that eliminate sterilization overhead and enable decentralized testing workflows.
- Fraunhofer applied research networks:Germany's institute-industry partnerships transfer roll-to-roll process knowledge directly to contract manufacturers, shortening pilot-to-production timelines.
Market Restraints
- Silver nanoparticle ink cost volatility:Conductive ink formulations depend on precious metal feedstocks with exchange-traded price exposure, compressing margins for high-volume electrode manufacturers.
- Gravure equipment capital intensity:Medium-run pharmaceutical packaging converters face 18-24 month payback periods for embedded sensor integration, limiting adoption outside established European converters.
- EMA MDR conformity assessment friction:Notified body scrutiny of substrate degradation profiles extends development cycles for implantable or long-wear applications beyond 36 months.
Strategic Opportunities
- Homecare channel expansion:Aging populations and remote patient monitoring programs shift purchasing authority from hospital supply chains to direct-to-consumer platforms and outpatient service providers.
- Pharmaceutical packaging serialization convergence:EU Falsified Medicines Directive mandates for track-and-trace create regulatory overlap with printed sensor traceability standards, opening embedded authentication contracts.
- Inkjet-flexography hybrid workflows:Digital patterning for customized low-volume outputs converges with high-throughput screen printing for standardized configurations, enabling mass personalization at glucose test strip scale.
Industry Challenges
- Cross-functional talent scarcity:Printed electronics development requires simultaneous mastery of polymer chemistry, additive manufacturing, and medical device regulatory science, creating recruitment bottlenecks.
- Biocompatibility-electrical safety dual certification:ISO 10993 testing sequences must synchronize with IEC 60601 electrical validation, forcing parallel rather than sequential development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Electronics in Healthcare Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Displays, Antennas, Batteries End User: Hospitals, Clinics, Laboratories, Homecare Technology: Inkjet Printing, Screen Printing, Gravure Printing, 3D Printing Application: Diagnostics, Monitoring, Therapeutics, Drug Delivery |
| Companies Covered | Jabil Inc., Flex Ltd., DuPont de Nemours, Inc., Abbott Laboratories, Medtronic plc, GE Healthcare, Nissha Co., Ltd., E Ink Holdings Inc., GSI Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Electronics in Healthcare Market Trends and Innovations
Functional material deposition below 150°C is unlocking biological-electronic interfaces previously incompatible with silicon processing, while regulatory convergence between drug and device authorities restructures vendor qualification hierarchies.
Biodegradable polymer substrates are bifurcating the implantable sensor segment between transient electronics that dissolve post-therapy and long-wear platforms requiring multi-year stability. Cardiac monitoring patch manufacturers in the Netherlands and Switzerland are piloting polylactic acid-based substrates for 30-day wearables. This material shift is bifurcating supply chains into disposable diagnostic and durable therapeutic tracks with incompatible substrate specifications.
EMA's Medical Device Regulation is tightening notified body scrutiny of ink leachables for skin-contact applications beyond 72 hours. Manufacturers now face mandatory migration testing for plasticizers and residual solvents previously exempt under withdrawn directives. German and French contract manufacturers are responding by qualifying medical-grade ink portfolios with pre-submitted toxicity dossiers.
Direct-to-consumer distribution is displacing traditional hospital supply chain procurement for continuous glucose monitoring patches and fertility tracking sensors. Outpatient service providers and pharmacy chains in the United Kingdom and Australia are building dedicated printed electronics procurement functions. This channel rotation concentrates volume with platform intermediaries rather than end-user institutions, compressing supplier margin structures.
Printed Electronics in Healthcare Market Segmentation
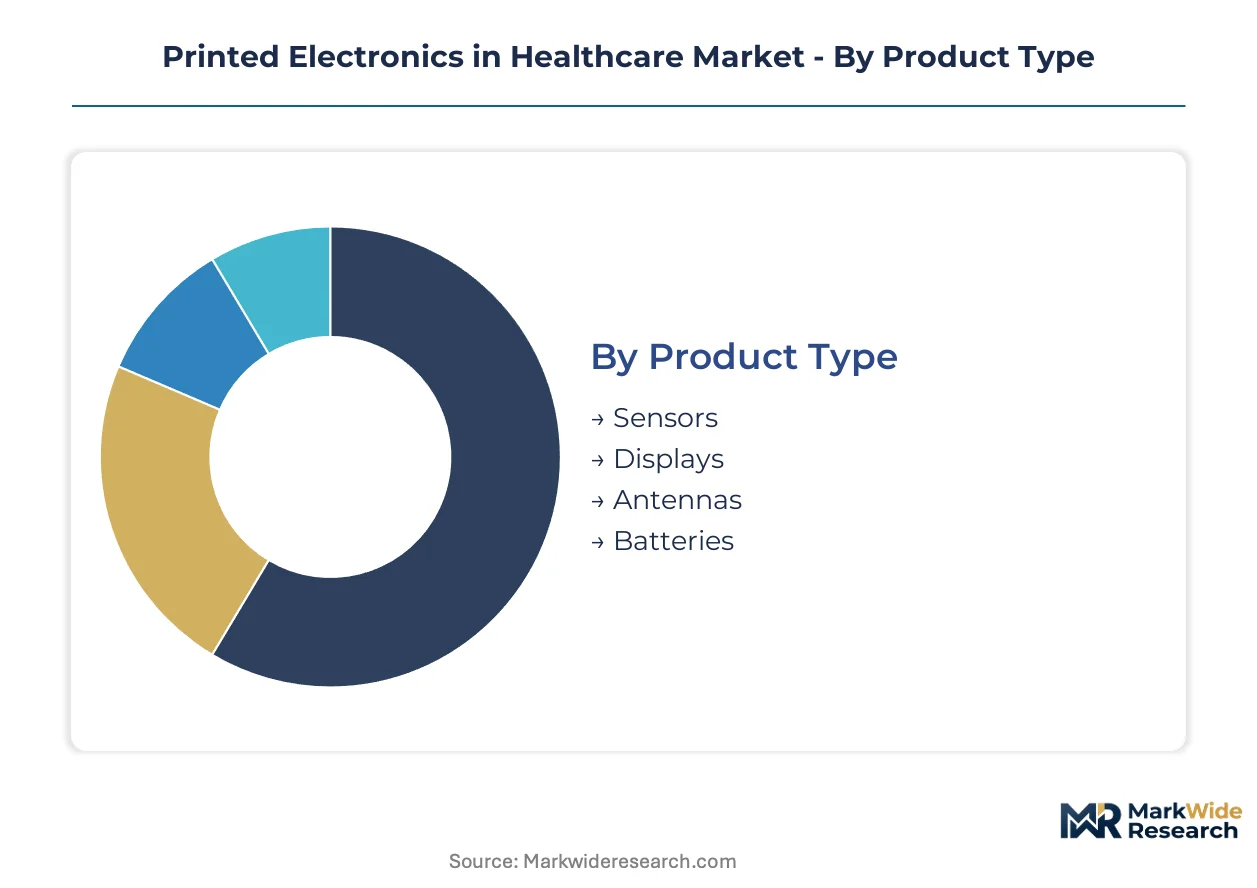
Segmentation in printed electronics healthcare markets exposes divergent supply chain configurations across product types and end-user channels. Each dimension carries distinct regulatory pathways, manufacturing scale requirements, and geographic demand concentrations that reshape vendor prioritization.
Product Type:
Sensors dominate export-led manufacturing from German industrial clusters, while displays and batteries concentrate in domestic hospital procurement channels.
- Sensors:Glucose test strips and ECG electrodes employ silver nanoparticle conductive traces on polyethylene terephthalate substrates. Hospital procurement teams in Germany and the United States drive volume for disposable biosensor formats that eliminate sterilization overhead.
- Displays:Electrophoretic and electrochromic screens for patient-facing diagnostic readouts integrate with flexible substrates below 150°C processing thresholds. Demand clusters in Netherlands and Swiss cardiac monitoring patch manufacturers piloting polylactic acid-based substrates for 30-day wearables.
- Antennas:Near-field communication coils for pharmaceutical packaging authentication.
- Batteries:Printed zinc-manganese and solid-state lithium cells for low-power therapeutic patches.
Sensors hold the largest share; momentum sits with displays as homecare channel expansion accelerates patient-facing interface requirements.
End User:
Customer type determines pricing tier and regulatory pathway, with hospital procurement demanding certified supply chains and homecare channels prioritizing direct-to-consumer logistics.
- Hospitals:Centralized procurement of disposable diagnostic substrates with ISO 10993 biocompatibility dossiers pre-submitted to notified bodies. German and French contract manufacturers anchor supply for sterile electrode configurations.
- Homecare:Continuous glucose monitoring patches and fertility tracking sensors distributed through pharmacy chains in the United Kingdom and Australia. Outpatient service providers build dedicated printed electronics procurement functions outside traditional hospital supply chains.
- Clinics:Point-of-care diagnostic workflows requiring rapid-turnover biosensor inventory.
- Laboratories:Customized low-volume sensor arrays for research and clinical trial applications.
Hospitals command the largest share; homecare exhibits the steepest expansion trajectory as aging populations shift purchasing authority to direct-to-consumer platforms.
Technology:
Manufacturing process selection maps directly to volume scale and customization requirements, with capital intensity creating divergent geographic concentration patterns.
- Inkjet Printing:Digital patterning enables rapid design iteration without photomask costs for customized low-volume outputs. Prototyping demand concentrates in Netherlands and Swiss pilot facilities for cardiac monitoring applications.
- Screen Printing:High-throughput manufacturing of standardized electrode configurations for glucose test strips. German Fraunhofer institute-industry partnerships transfer roll-to-roll process knowledge to contract manufacturers.
- Gravure Printing:Medium-run pharmaceutical packaging with embedded authentication and temperature-tracking circuitry. Equipment capital requirements constrain adoption outside established European converters.
- 3D Printing:Stereolithography and material jetting for complex multi-layer therapeutic device geometries.
Screen printing holds the largest share; inkjet printing gains share fastest as mass personalization requirements intensify across glucose test strip scale production.
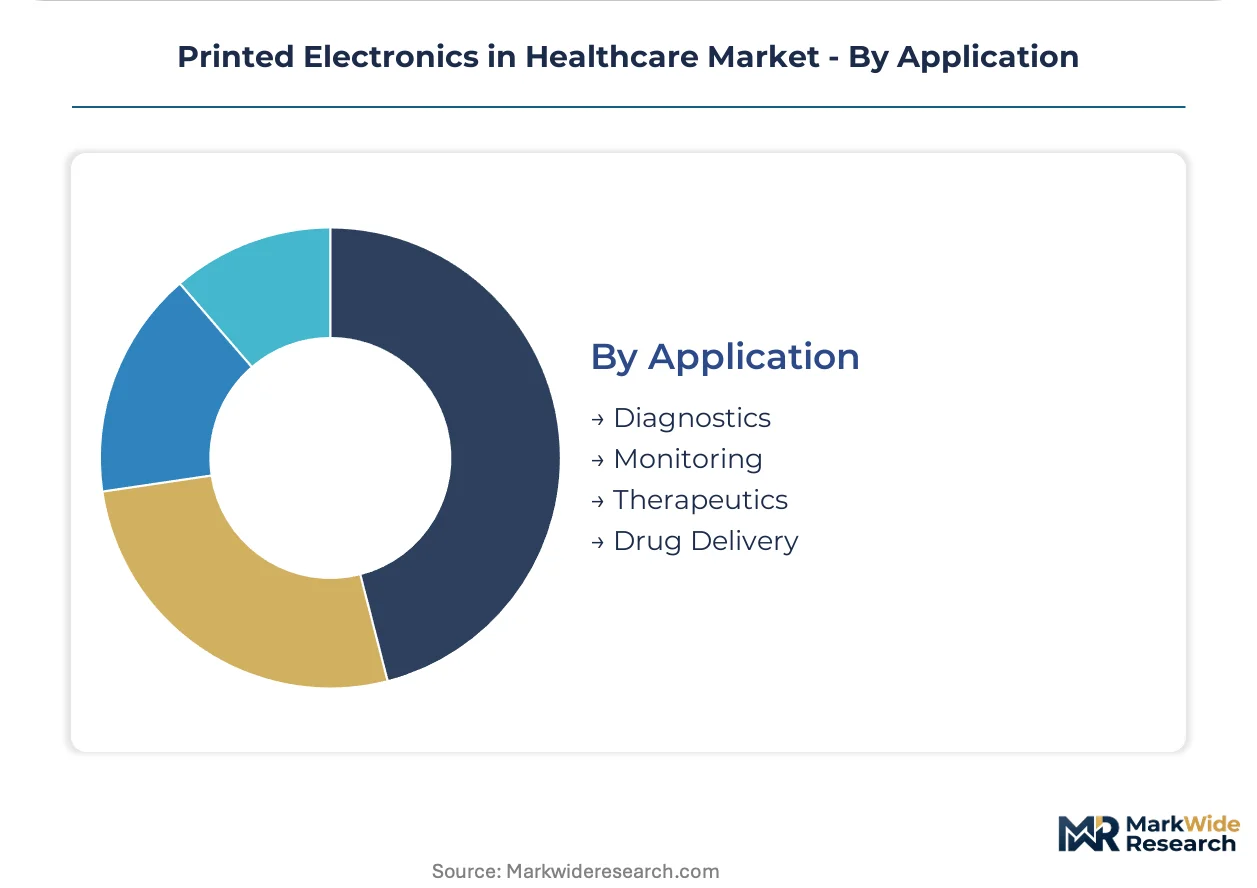
Application:
Functional use case determines substrate specification and wear duration, bifurcating supply chains between transient and durable platforms.
- Diagnostics:Disposable biosensors for decentralized testing workflows. FDA combination product pathways accelerate validation timelines for printed therapeutic platforms in United States hospital procurement.
- Monitoring:Cardiac patches and continuous glucose monitors requiring multi-day to multi-week wear. EMA MDR notified body scrutiny of substrate degradation profiles extends development cycles for long-wear applications.
- Therapeutics:Transdermal drug delivery patches with integrated electronic actuation.
- Drug Delivery:Smart pharmaceutical packaging with printed temperature sensors and authentication circuits.
Diagnostics holds the largest share; monitoring climbs the fastest as remote patient monitoring programs expand in United Kingdom and Australian outpatient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract manufacturers export flexible diagnostic substrates to United States hospital procurement networks, while Swiss and Dutch pilot facilities supply cardiac monitoring prototypes to United Kingdom and Australian outpatient channels.
United States
FDA combination product pathways accelerate validation timelines for printed therapeutic platforms entering hospital supply chains. Hospital procurement teams prioritize disposable biosensor formats that eliminate sterilization overhead. Boston and Minneapolis medical device clusters anchor applied research in minimally invasive platforms with conformable electronic layers.
Germany
Fraunhofer institute-industry partnerships transfer roll-to-roll process knowledge directly to contract manufacturers in Baden-Württemberg and Bavaria. EMA MDR notified body scrutiny of substrate degradation profiles extends development cycles for implantable applications. Munich and Stuttgart industrial clusters compress unit economics for flexible diagnostic substrates through scaled manufacturing.
United Kingdom
Outpatient service providers and pharmacy chains build dedicated printed electronics procurement functions outside traditional hospital supply chains. EU Falsified Medicines Directive mandates for track-and-trace create regulatory overlap with printed sensor traceability standards. London and Cambridge clusters pilot direct-to-consumer distribution for continuous glucose monitoring patches.
Australia
Remote patient monitoring programs shift purchasing authority from hospital supply chains to direct-to-consumer platforms. TGA conformity assessment requirements parallel FDA biocompatibility frameworks for imported diagnostic substrates. Sydney and Melbourne healthcare distributors concentrate volume for fertility tracking sensors and pharmacy-chain distribution.
Switzerland
Swissmedic scrutiny of ink leachables for skin-contact applications beyond 72 hours mandates migration testing for plasticizers and residual solvents. Cardiac monitoring patch manufacturers pilot polylactic acid-based substrates for 30-day wearables. Basel and Zurich precision manufacturing clusters anchor pharmaceutical packaging with embedded authentication circuitry.
Printed Electronics in Healthcare Market Competitive Landscape
Player mix skews toward diversified healthcare conglomerates with captive device manufacturing infrastructure, supplemented by specialized materials suppliers and precision printing contractors. Market structure concentrates around three strategic archetypes: integrated device manufacturers leveraging in-house flexible substrate production, advanced materials suppliers commanding conductive ink portfolios, and contract manufacturers anchoring roll-to-roll scale. Dominant competitive moves include backward integration into substrate production and strategic partnerships between ink formulators and notified body-qualified converters.
Within the integrated device manufacturer tier, Medtronic plc and Abbott Laboratories exemplify archetypes extending therapeutic device ecosystems into conformable form factors. DuPont de Nemours, Inc. occupies a position among materials specialists optimizing conductive portfolios for biocompatible applications. Jabil Inc. anchors the contract manufacturing vector, leveraging healthcare infrastructure for large-scale flexible diagnostic substrate production.
| Leading Market Players |
|---|
| Jabil Inc. |
| Flex Ltd. |
| DuPont de Nemours, Inc. |
| Abbott Laboratories |
| Medtronic plc |
| GE Healthcare |
| Nissha Co., Ltd. |
| E Ink Holdings Inc. |
| GSI Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
ISO 10993 biocompatibility certification tiers gate both supplier qualification and price differentiation simultaneously, with notified body dossiers separating medical-grade ink portfolios from commodity conductive formulations and compressing margin structures for uncertified converters.
Pricing Analysis
Screen-printed glucose test strips occupy the prior-generation cost floor while inkjet-flexography hybrid workflows command next-generation premiums for mass-personalized outputs. Pricing stratifies across premium, standard, and economy tiers based on ISO 10993 certification grade and volume scale, with hospital procurement teams exhibiting lowest price sensitivity due to sterilization overhead elimination and homecare channels facing compression from direct-to-consumer platform intermediaries. Cost compression in silver nanoparticle ink feedstocks is intensifying because exchange-traded precious metal volatility squeezes high-volume electrode manufacturers.
Supply Chain Analysis
Strategic stockpiling of silver nanoparticle inks dominates inventory strategy over just-in-time approaches due to commodity price volatility exposure. Supply concentrates in Germany for roll-to-roll flexible substrates, the United States for FDA-validated therapeutic platforms, and Switzerland for pharmaceutical packaging with embedded authentication circuitry. Raw material dependencies draw from silver bullion markets, polyethylene terephthalate film suppliers, and medical-grade polymer resin producers. Single-source vulnerability in Fraunhofer-affiliated contract manufacturing clusters creates concentration risk. Distribution runs through hospital procurement networks, pharmacy chain direct-to-consumer platforms, and outpatient service provider dedicated procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including calibration subscriptions and regulatory compliance monitoring are expanding faster than hardware unit sales as hospital procurement teams outsource biocompatibility dossier maintenance.
For Market Incumbents: Shield market position by deepening backward integration into medical-grade substrate production and accelerating CE marking pathway investments ahead of EMA MDR notified body queue congestion. Ink leachable migration testing mandates from Swissmedic and ANSM threaten margin structures for skin-contact applications beyond 72 hours. For New Entrants and Emerging Players: Anchor in the homecare channel expansion trajectory where direct-to-consumer platforms and pharmacy chains in the United Kingdom and Australia lack established printed electronics procurement functions. Fertility tracking sensors and continuous glucose monitoring patches represent the most penetrable white-space segment. Pursue inkjet-flexography hybrid workflow partnerships with German Fraunhofer network contract manufacturers to bypass capital-intensive gravure equipment barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across inkjet-printed customized diagnostic outputs as digital patterning eliminates photomask costs and compresses pilot-to-production timelines. Five-to-ten year viability favors acquisition targets with pre-submitted ISO 10993 toxicity dossiers and notified body-qualified converter relationships. The signal to watch is FDA combination product pathway backlog clearance rates as validation timeline acceleration indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR notified body scrutiny of substrate degradation profiles extends development cycles beyond 36 months for implantable applications. |
| Hospital System Partnership | German and French contract manufacturers anchor supply for sterile electrode configurations with pre-submitted biocompatibility dossiers. |
| Software Companion Development | Patient-facing diagnostic readouts for cardiac monitoring patches require electrophoretic display integration below 150°C processing thresholds. |
| Reimbursement Strategy | Remote patient monitoring program eligibility criteria in United Kingdom and Australian outpatient channels determine volume concentration. |
| FDA Submission | Combination product pathway acceleration for printed therapeutic platforms entering United States hospital procurement networks. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration through structured primary interviews combined with secondary validation against FDA 510(k) filings, EMA medical device registration databases, hospital procurement contract repositories, and ISO 10993 testing laboratory accreditation records. Bottom-up sensor unit demand modeling and top-down healthcare expenditure allocation triangulation anchored value estimates.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, end-user channel, manufacturing technology, and application function with wear duration specifications. CAGRs were derived from annualized growth rate interpolation across the projection horizon. Industry-specific forecast inputs incorporated roll-to-roll manufacturing scale-up timelines and FDA combination product pathway validation velocity assumptions.
Material uncertainties — silver nanoparticle ink price volatility, EMA MDR notified body capacity constraints, and FDA guidance evolution on printed therapeutic devices — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained Fraunhofer institute-industry partnership technology transfer rates and homecare channel procurement function maturation. Revision becomes warranted when silver exchange-traded price volatility crosses threshold levels triggering margin compression responses from high-volume electrode manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Patellar Implant Market
Medical Devices
South Korea ECG Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Respiratory Devices Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Global Joint Replacement Device Market