
 Neurosurgery Software Market | 2026-2036
Neurosurgery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Neurosurgery Software Market Foresight
North American health systems are fragmenting their vendor portfolios across specialized neurosurgery software modules rather than consolidating on single platforms. Medtronic leverages its installed base of spinal navigation hardware to extend software subscription attach rates. Brainlab sustains R&D intensity in radiation oncology-neurosurgery convergence. Stryker Corporation anchors its position through deep integration with surgical instrument workflows.
Neurosurgery software encompasses digital platforms that process medical imaging data, reconstruct three-dimensional anatomical models with sub-millimeter spatial resolution, and guide instrument trajectories during cranial or spinal procedures. Imaging software and surgical planning tools dominate current revenue, while artificial intelligence and machine learning segments capture the fastest expansion as hospitals seek automated tumor segmentation and predictive outcome modeling. Cloud-based deployment is displacing on-premise installations in ambulatory surgical centers seeking lower capital burdens.
FDA premarket notification requirements and HIPAA data security frameworks shape product architecture and market access timelines for vendors targeting United States providers. The EU AI Act and MDR conformity assessments impose additional validation burdens on machine learning-enabled navigation systems sold in Europe. Stakeholders must monitor how regulatory divergence between jurisdictions affects development roadmaps and commercial prioritization.
Market Dynamics
Machine learning-enabled surgical navigation is compressing FDA premarket clearance timelines while fragmenting hospital vendor portfolios across specialized software modules rather than consolidated platforms.
Growth Catalysts
- FDA 510(k) pathway acceleration:Machine learning-enabled navigation tools now secure premarket clearance faster than traditional hardware-dependent systems, compressing vendor commercialization cycles for United States hospitals.
- German university hospital procurement:University hospitals in Germany anchor adoption of intraoperative imaging integration, creating concentrated demand clusters that validate platform scalability for European expansion.
- Cloud deployment in ambulatory centers:Ambulatory surgical centers are displacing on-premise installations with cloud-based platforms to reduce capital burdens and accelerate software refresh cycles.
Market Restraints
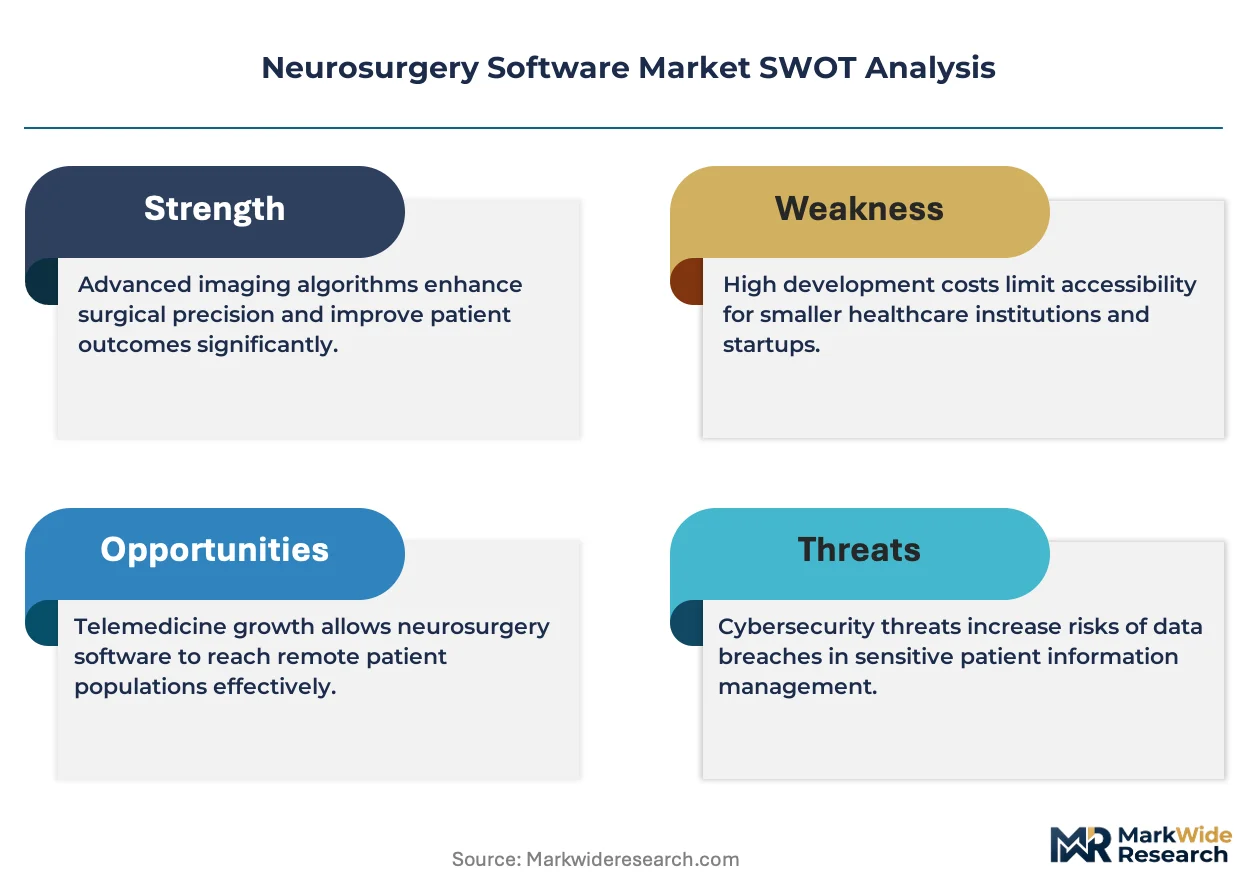
- EU MDR conformity assessment costs:Machine learning-enabled navigation systems face extended validation timelines and elevated documentation burdens under EU MDR and EU AI Act dual frameworks, raising European market entry costs.
- HIPAA data security architecture requirements:United States providers demand hardened data security frameworks that extend product development cycles and constrain cloud architecture choices for vendors.
- Input concentration in imaging modalities:Software platforms remain tethered to MRI and CT scanner ecosystems controlled by concentrated medical imaging equipment manufacturers, limiting independent pricing power.
Strategic Opportunities
- AI-radiation oncology convergence:Radiation oncology-neurosurgery workflow integration represents underexploited white space where automated tumor segmentation bridges treatment planning and surgical execution.
- India's hospital digitization mandate:India's PLI scheme for medical device manufacturing and hospital digitization initiatives create regulatory tailwinds for software vendors establishing localized cloud infrastructure.
- Predictive outcome modeling:Machine learning platforms that forecast post-surgical complications and recovery trajectories command premium positioning in value-based reimbursement environments.
Industry Challenges
- Neurosurgeon-digital interface training:Sub-millimeter navigation accuracy demands specialized training in 3D anatomical model interpretation, creating bottlenecks in adoption velocity across health systems.
- Legacy PACS integration complexity:Surgical planning platforms must interface with heterogeneous picture archiving and communication systems that lack standardized APIs, extending implementation timelines.
- Cross-border data residency compliance:Cloud-based deployments face conflicting data localization requirements between HIPAA, GDPR, and emerging national health data frameworks, complicating multi-tenant architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurosurgery Software Market |
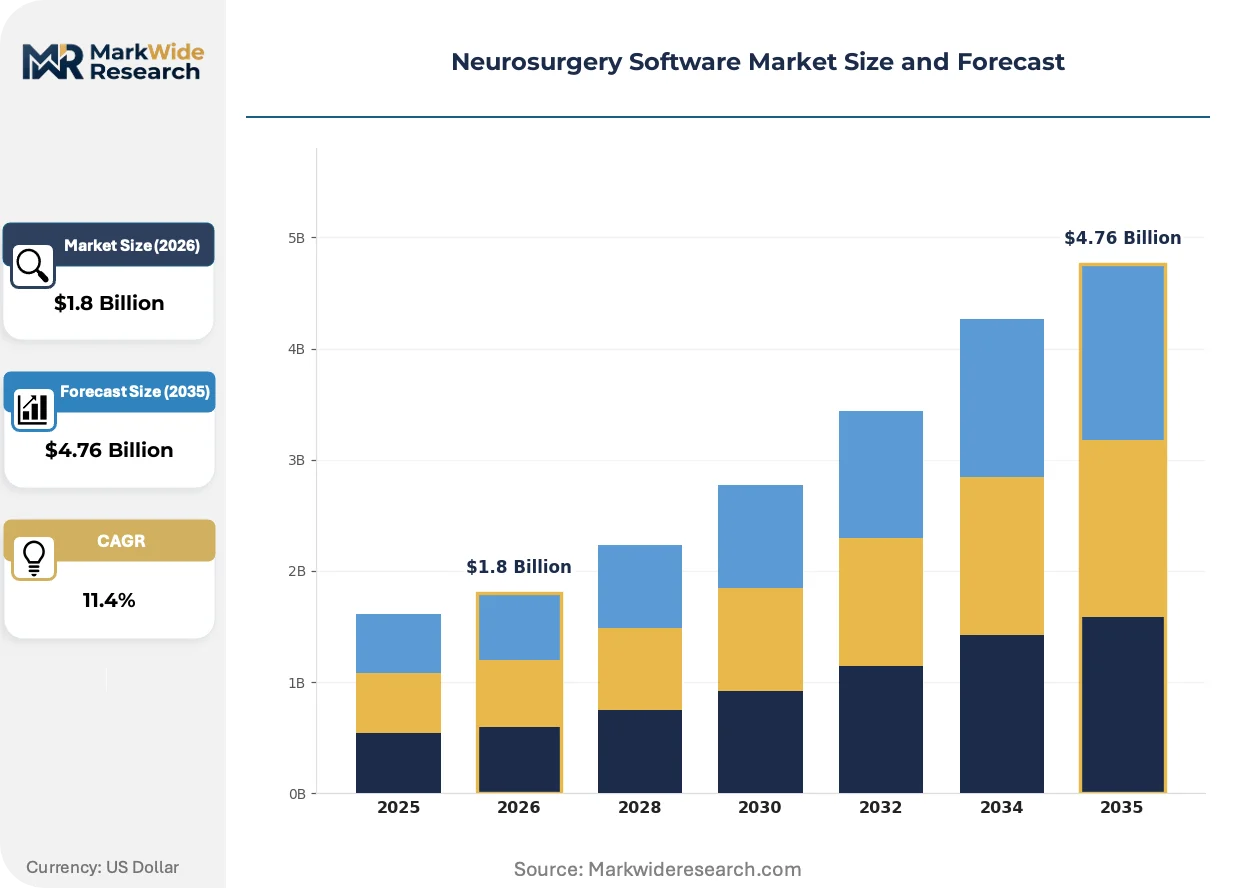
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Software, Surgical Planning Tools, Navigation Systems, Patient Management Software End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Medical Clinics Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Applications Technology: Artificial Intelligence, Machine Learning, 3D Visualization, Virtual Reality |
| Companies Covered | Medtronic, Brainlab, Stryker Corporation, Siemens Healthineers, GE Healthcare, Philips Healthcare, Zimmer Biomet, Elekta AB, Intuitive Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurosurgery Software Market Shifts & Advancements
Artificial intelligence is restructuring how neurosurgical plans are generated, validated, and executed, with automation penetrating previously manual segmentation and trajectory calculation workflows.
Federated learning architectures are rendering obsolete centralized model training approaches that required pooling patient data across institutions. Academic medical centers in the United States and Germany are deploying edge-computing nodes that train algorithms locally while sharing only model updates, preserving HIPAA and GDPR compliance. This architecture is compressing the data governance overhead that previously stalled multi-site AI validation studies.
The EU AI Act's risk-classification framework for medical devices is forcing recalibration of machine learning product roadmaps for vendors targeting European sales. High-risk AI systems now face mandatory conformity assessments, post-market monitoring obligations, and human oversight requirements that extend beyond traditional MDR medical device obligations. Neurosurgery navigation platforms with autonomous trajectory suggestions fall under this classification, compelling architecture redesigns before 2026 enforcement deadlines.
Subscription pricing for software modules is displacing perpetual licensing in North American hospital procurement. Health systems now unbundle surgical planning, navigation, and post-operative analytics into separate annual contracts, enabling vendor switching and pressuring attach rates for integrated platforms. This fragmentation is most visible in California and Texas health systems, where specialized neurosurgery institutes negotiate module-specific service level agreements rather than enterprise-wide commitments.
Neurosurgery Software Market Segmentation
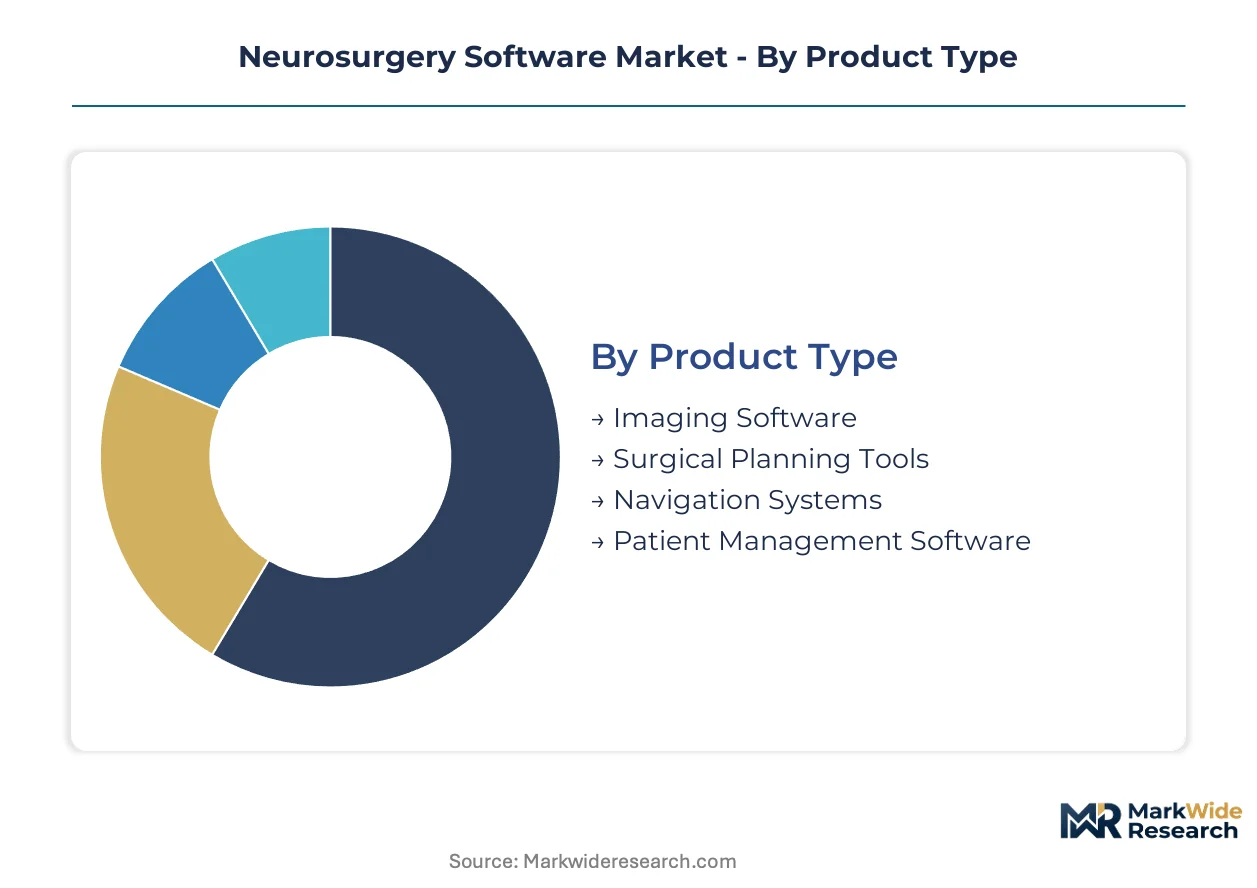
Neurosurgery software segmentation reveals how vendor portfolios fragment across specialized modules rather than consolidated platforms. Understanding these divisions exposes where procurement power concentrates and where technology transitions create displacement opportunities.
Product Type:
Mature imaging and navigation platforms anchor current revenue while AI-enhanced planning tools represent the emerging technology frontier reshaping competitive positioning.
- Imaging Software:Processes MRI and CT data to reconstruct three-dimensional anatomical models with sub-millimeter spatial resolution. Demand clusters in German university hospitals validating intraoperative imaging integration platforms for European expansion.
- Surgical Planning Tools:Digital platforms that calculate instrument trajectories and simulate cranial or spinal procedures pre-operatively. North American health systems are fragmenting procurement across specialized modules rather than consolidated enterprise licenses, compressing vendor attach rates.
- Navigation Systems:Real-time instrument tracking with optical or electromagnetic positioning.
- Patient Management Software:Post-operative analytics and recovery trajectory monitoring.
Imaging software handles the majority of throughput; surgical planning tools are climbing the fastest on share as AI penetration accelerates.
End User:
Customer type segmentation tracks capital intensity gradients from enterprise hospitals to lean ambulatory operators seeking subscription alternatives.
- Hospitals:Academic medical centers deploy federated learning architectures with edge-computing nodes that train algorithms locally while sharing model updates. FDA 510(k) pathway acceleration for machine learning-enabled navigation tools compresses procurement cycles for these institutions.
- Ambulatory Surgical Centers:Cloud-based platforms displace on-premise installations to reduce capital burdens and accelerate software refresh cycles. HIPAA data security architecture requirements constrain cloud architecture choices and extend vendor development timelines.
- Research Institutions:Federated learning validation studies and multi-site AI governance frameworks.
- Medical Clinics:Modular subscription pricing for discrete planning and analytics functions.
Hospitals command the dominant procurement volume; ambulatory surgical centers are gaining share fastest as cloud deployment displaces capital-intensive installations.
Deployment:
Architecture choices reflect tension between data sovereignty requirements and operational flexibility demands across provider types.
- On-Premise:Legacy installations in hospitals with hardened security frameworks and dedicated IT infrastructure. HIPAA compliance and legacy PACS integration complexity extend implementation timelines for vendors targeting United States providers.
- Cloud-Based:Multi-tenant platforms facing cross-border data residency conflicts between HIPAA, GDPR, and emerging national health data frameworks. Subscription pricing models enable vendor switching and pressure integrated platform attach rates in California and Texas health systems.
- Hybrid Solutions:Sensitive processing on-premise with analytics and storage in cloud environments.
- Mobile Applications:Surgeon-facing interfaces for remote plan review and intraoperative reference.
On-premise retains the installed base majority; cloud-based deployment shows the steepest expansion trajectory as ambulatory centers prioritize capital efficiency.
Technology:
Technology segmentation captures the automation penetration gradient from established visualization to predictive algorithmic platforms.
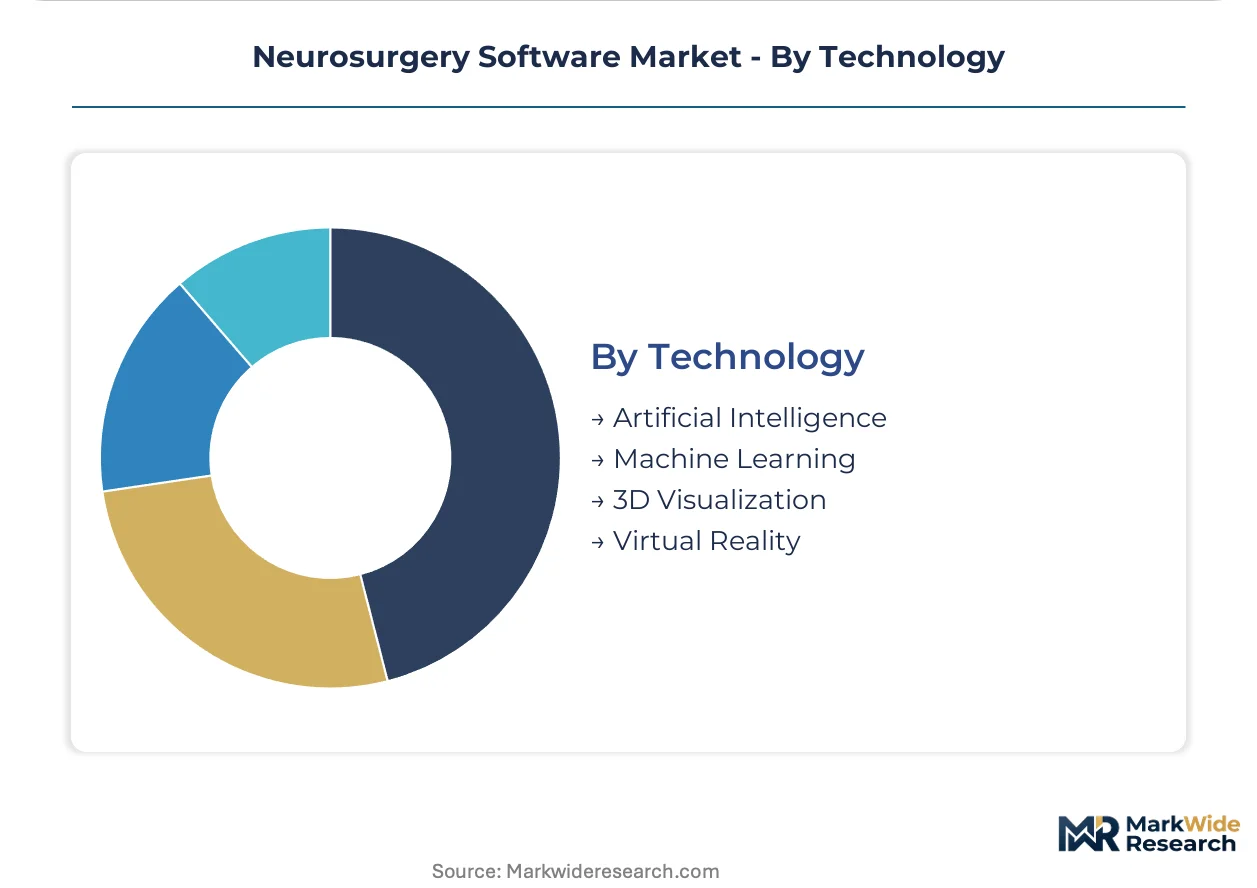
- Artificial Intelligence:Automated tumor segmentation and autonomous trajectory suggestion engines. EU AI Act risk-classification framework mandates conformity assessments and human oversight requirements extending beyond traditional MDR obligations for European market entry.
- Machine Learning:Predictive outcome modeling platforms forecasting post-surgical complications and recovery trajectories. These command premium positioning in value-based reimbursement environments and face compressed FDA premarket clearance timelines relative to hardware-dependent systems.
- 3D Visualization:Established anatomical model rendering and surgical simulation.
- Virtual Reality:Immersive pre-operative planning and neurosurgeon training environments.
3D visualization handles current procedural volume; machine learning platforms are expanding most quickly as reimbursement models reward predictive capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for neurosurgical applications clusters where academic medical centers, regulatory pathways, and imaging hardware ecosystems intersect. Vendors concentrate engineering resources near FDA clearance infrastructure in the United States, EU MDR validation networks in Germany, and emerging digitization mandates in India.
United States
Academic medical centers in Massachusetts and California deploy federated learning architectures with edge-computing nodes for algorithm training. FDA 510(k) pathway acceleration for machine learning-enabled navigation tools compresses commercialization cycles. The Boston-Cambridge corridor anchors validation studies for intraoperative imaging integration platforms.
Germany
University hospitals in Bavaria and North Rhine-Westphalia anchor procurement of intraoperative imaging integration systems. EU MDR and EU AI Act dual frameworks impose extended validation timelines for high-risk AI navigation platforms. The Heidelberg-Mannheim medical technology cluster validates platform scalability for European market entry.
India
Hospital digitization initiatives under the PLI scheme for medical device manufacturing create procurement tailwinds for cloud-based surgical planning platforms. CDSCO regulatory frameworks for software-as-medical-device are stabilizing. The Bangalore-Hyderabad corridor hosts localized cloud infrastructure development for ambulatory surgical center deployment.
Japan
PMDA premarket approval pathways for AI-enabled surgical navigation are streamlining relative to traditional hardware-dependent systems. METI funding for smart hospital infrastructure accelerates cloud migration in metropolitan medical centers. The Tokyo-Osaka corridor concentrates demand for predictive outcome modeling platforms in value-based reimbursement pilots.
United Kingdom
NHS England procurement frameworks for surgical planning software are fragmenting across specialized modules rather than consolidated enterprise licenses. MHRA recognition of FDA 510(k) clearances accelerates market access for United States-validated platforms. The Oxford-Cambridge-London triangle anchors federated learning governance studies for multi-site AI validation.
Neurosurgery Software Market Competitive Landscape
Diversified medical technology conglomerates and specialized surgical navigation software developers split the market between integrated platform strategies and modular best-of-breed offerings. The vendor landscape exhibits moderate consolidation, with three to five entities commanding disproportionate attach rates through hardware-software bundling. Two dominant strategic archetypes prevail: imaging equipment manufacturers extending software subscription models, and independent software vendors pursuing radiation oncology-neurosurgery convergence. Competitive dynamics center on M&A activity targeting AI segmentation capabilities and strategic partnerships with academic medical centers for federated learning validation.
Within the diversified medical technology tier, Medtronic leverages spinal navigation hardware installed bases to extend software subscription attach rates. Brainlab occupies a position exemplifying specialized surgical navigation software developers with sustained R&D intensity in radiation oncology-neurosurgery workflow integration. Stryker Corporation represents the surgical instrument workflow integration archetype, anchoring competitive positioning through deep interoperability with operative tool ecosystems.
| Leading Market Players |
|---|
| Medtronic |
| Brainlab |
| Stryker Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Zimmer Biomet |
| Elekta AB |
| Intuitive Surgical |
| Others |
Supply & Pricing Matrix
Medical imaging equipment manufacturers in Germany, Japan, and the United States control MRI and CT scanner ecosystems that tether software platforms to hardware procurement cycles, concentrating margin pools in bundled enterprise contracts rather than standalone software licenses.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure for neurosurgery software, with machine learning-enabled navigation tools commanding premium positioning over traditional hardware-dependent systems. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced platforms with predictive capabilities from basic imaging reconstruction modules. Cost compression in the standard tier is intensifying as cloud-based deployment reduces capital barriers for ambulatory surgical centers. Academic medical centers demonstrate the least price sensitivity due to research funding and federated learning validation requirements, while standalone clinics face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for optical tracking sensors and electromagnetic positioning arrays concentrates in Taiwan, South Korea, and select German industrial clusters. Software development draws from specialized imaging algorithm libraries, edge-computing hardware, and HIPAA-compliant cloud infrastructure. Single-source vulnerability persists in sub-millimeter precision sensor supply, where qualified vendors remain limited. Distribution runs through direct hospital system contracts and group purchasing organizations, with academic medical centers negotiating enterprise-wide platform access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurosurgery software is approaching a platform-economics inflection as federated learning architectures fragment data governance and enable modular vendor switching across specialized software modules.
For Market Incumbents: Pre-empt modular unbundling by deepening integration with surgical instrument workflows and securing exclusive intraoperative imaging partnerships. Subscription attach rates face erosion from specialized AI segmentation entrants. Vertical integration into edge-computing hardware for federated learning nodes preserves data governance control. For New Entrants and Emerging Players: Mid-market ambulatory surgical centers in India and Southeast Asia represent the most penetrable entry point for cloud-native surgical planning platforms. Radiation oncology-neurosurgery workflow convergence offers underexploited white space with lower incumbent saturation. Go-to-market through localized cloud infrastructure partnerships bypasses legacy PACS integration complexity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical navigation specialists seeking exit via strategic acquisition by imaging equipment conglomerates. Five-to-ten year viability hinges on AI Act compliance architecture and federated learning validation scale. Watch FDA 510(k) clearance velocity for machine learning platforms as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Federated learning node deployment compresses multi-site AI validation timelines for HIPAA compliance. |
| Strategic Partnership | University hospital alliances in Germany validate intraoperative imaging scalability for European expansion. |
| Acquisition of Specialist Firm | AI segmentation capabilities bridge radiation oncology and neurosurgery workflow convergence. |
| Geographic Expansion | Localized cloud infrastructure in India captures PLI scheme procurement tailwinds. |
| Product Launch | Predictive outcome modeling platforms command premium positioning in value-based reimbursement pilots. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity assessments, hospital procurement databases, and GPO contract disclosures. Interviews with neurosurgeons, biomedical engineers, hospital purchasing committees, and software integration specialists inform demand-side validation. Bottom-up modeling of vendor-reported installations and top-down triangulation against imaging equipment shipment data ensure cross-verification.
Forecast inputs span deployment architecture, end-user facility type, technology automation tier, and regional regulatory cluster across the analysis window. Segmentation dimensions include product module, customer capital intensity, cloud versus on-premise architecture, and AI risk classification under EU AI Act. CAGRs derive from installed base expansion rates and subscription pricing trajectory analysis, incorporating cloud migration velocity and ambulatory center digitization mandates.
Practitioners should monitor FDA 510(k) clearance velocity for machine learning platforms, EU AI Act enforcement calibration, and federated learning validation study publication rates for early signals. Forecasts reflect assumptions regarding regulatory pathway stability and cloud infrastructure localization feasibility. Quarterly review of hospital procurement database entries and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Epharmacy Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Healthcare Smart Card Reader Market