
 Healthy Care Coenzyme Q10 Market | 2026-2036
Healthy Care Coenzyme Q10 Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Care Coenzyme Q10 Market Insights
Japanese fermentation capacity is rebalancing toward pharmaceutical-grade CoQ10 output after years of nutraceutical dominance. Kaneka Corporation leverages its proprietary yeast-fermentation technology to sustain premium positioning in ubiquinol production. DSM Nutritional Products anchors European supply through its synthetic CoQ10 platform, while Kyowa Hakko U.S.A. competes on biotechnology-driven purity standards.
Healthy Care Coenzyme Q10 denotes a lipid-soluble quinone compound (C59H90O4) synthesized through microbial fermentation or chemical extraction, functioning primarily as a mitochondrial electron transporter and cellular energy catalyst. Softgels dominate product type revenue due to superior bioavailability in oil-based matrices, while powders gain traction in functional food fortification. The aging population end-user segment concentrates margin pools, though athletes represent the fastest-growing demand category for recovery-oriented formulations.
The FDA's dietary supplement Current Good Manufacturing Practices constrain manufacturing consistency requirements for U.S.-market CoQ10 products, while Japan's Ministry of Health, Labour and Welfare oversees pharmaceutical-grade CoQ10 as an approved cardioprotective agent. Stakeholders must monitor evolving pharmacopeial standards for ubiquinone-ubiquinol equivalence claims across multiple regulatory jurisdictions.
Market Dynamics
Japanese fermentation capacity rebalancing toward pharmaceutical-grade output is compressing nutraceutical supply availability and forcing procurement diversification across North American and European dietary supplement manufacturers.
Growth Catalysts
- Cardiovascular wellness prioritization:Aging demographics in Japan and the United States are expanding physician-recommended CoQ10 protocols for heart health maintenance, driving prescription-adjacent supplement demand.
- FDA New Dietary Ingredient pathway maturation:Streamlined notification procedures for novel ubiquinol delivery formats are accelerating product entry timelines for oil-matrix softgel innovations.
- Fermentation biotechnology advancement:Yeast-based production methods are achieving pharmaceutical-grade purity thresholds previously reserved for synthetic chemistry, enabling dual-use manufacturing flexibility.
Market Restraints
- Kaneka Corporation supply concentration:Proprietary ubiquinol fermentation technology remains captive to single-source Japanese production, creating procurement vulnerability for international formulators.
- Raw material input volatility:Pharmaceutical-grade yeast culture media and specialized lipid carriers face agricultural commodity price swings that compress contract manufacturing margins.
- Ubiquinone-ubiquinol bioequivalence uncertainty:Inconsistent pharmacopeial standards across FDA, EFSA, and Japan's MHLW jurisdictions complicate multi-region label claims and inventory positioning.
Strategic Opportunities
- Athletic recovery formulation white space:Exercise-induced oxidative stress management represents an underdeveloped application segment with premium pricing potential for mitochondrial support positioning.
- Functional food fortification expansion:Powder-format CoQ10 integration into dairy alternatives and sports nutrition bars opens mass-market channels beyond pharmacy retail dominance.
- European synthetic platform leverage:DSM Nutritional Products' chemical production infrastructure offers supply security advantages as Asian fermentation capacity pivots toward pharmaceutical grades.
Industry Challenges
- Dual-grade manufacturing complexity:Nutraceutical and pharmaceutical production lines require segregated equipment validation protocols that extend facility qualification timelines.
- Analytical method standardization gaps:HPLC assay variability between contract laboratories creates batch release disputes and inventory quarantine risks.
- Cross-jurisdiction equivalence documentation:Supporting ubiquinol content claims across FDA dietary supplement rules and Japan's approved drug specifications demands duplicative stability testing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Care Coenzyme Q10 Market |
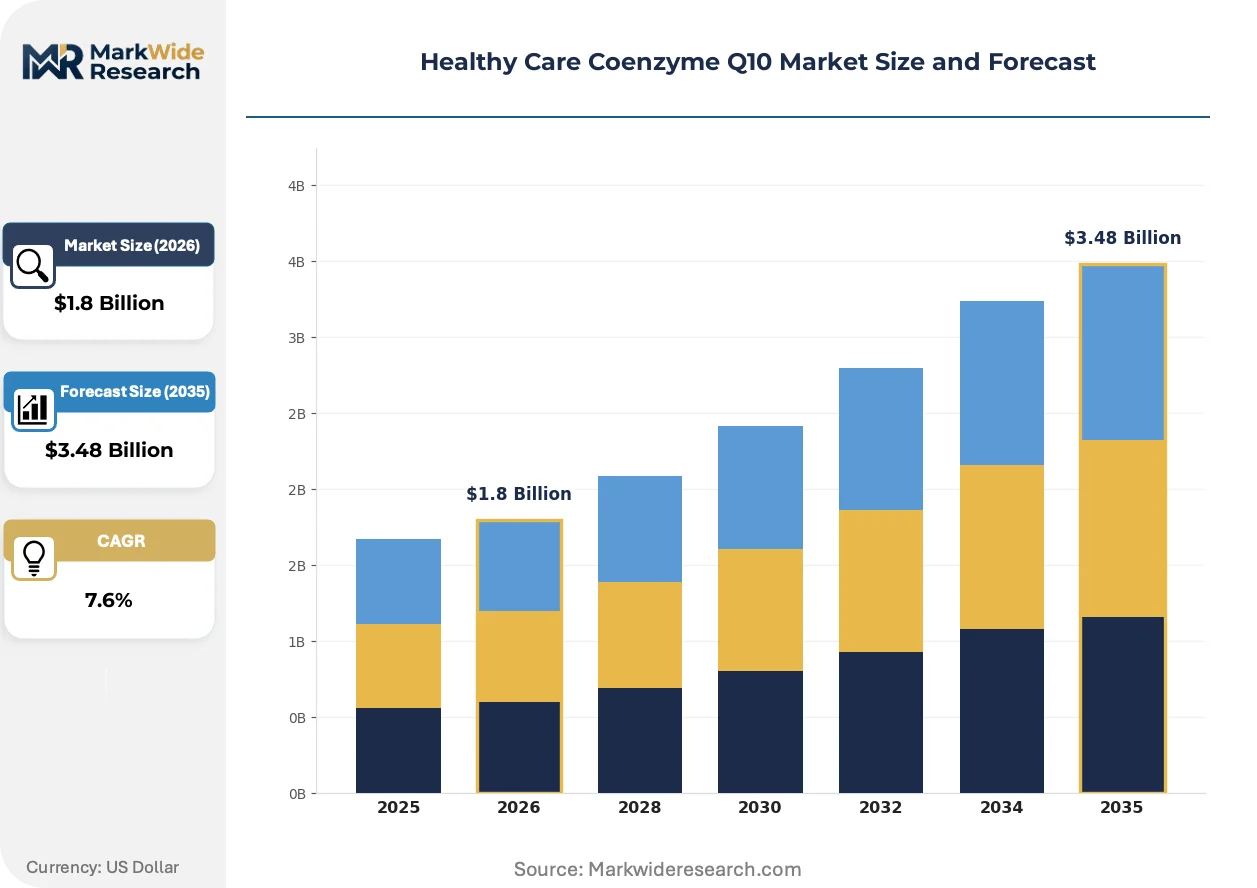
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Capsules, Powders, Liquid Application: Dietary Supplements, Functional Foods, Nutraceuticals, Pharmaceuticals End User: Health Enthusiasts, Athletes, Aging Population, General Consumers Distribution Channel: Retail Stores, Online Platforms, Pharmacies, Health Shops |
| Companies Covered | Kaneka Corporation, DSM Nutritional Products, Kyowa Hakko U.S.A., Gnosis, Nature's Bounty, PharmaEssentia Corporation, Hwail Pharmaceutical, Nisshin Seifun Group, ZMC-USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Care Coenzyme Q10 Market Trends and Innovations
Continuous processing technology and delivery format innovation are compressing traditional batch manufacturing timelines while regulatory convergence pressures force harmonization investments across multi-jurisdictional portfolios.
Self-emulsifying drug delivery systems (SEDDS) are automating the industrial-scale production of enhanced-bioavailability CoQ10 formulations. Softgel manufacturers in the United States are adopting these lipid-based carriers to achieve pharmacokinetic parity with ubiquinol at reduced raw material cost. The technology is automating quality control throughput and reducing batch-to-batch dissolution variability that previously required extensive manual testing intervention.
Japan's Ministry of Health, Labour and Welfare maintains pharmaceutical-grade CoQ10 as an approved cardioprotective agent with distinct manufacturing and labeling requirements from dietary supplements. This regulatory bifurcation is compelling Japanese producers to segregate production lines and maintain separate inventory pools for domestic pharmaceutical distribution versus export nutraceutical supply. European importers are responding by diversifying sourcing toward synthetic CoQ10 platforms to avoid supply priority conflicts.
Direct-to-consumer subscription models are displacing pharmacy retail as the primary acquisition channel for maintenance-dose CoQ10 regimens. Wellness-focused e-commerce platforms in North America are capturing recurring revenue through personalized dosing protocols based on self-reported cardiovascular risk factors. This shift is most visible among aging consumers seeking physician-adjacent guidance without clinical consultation friction.
Healthy Care Coenzyme Q10 Market Segmentation
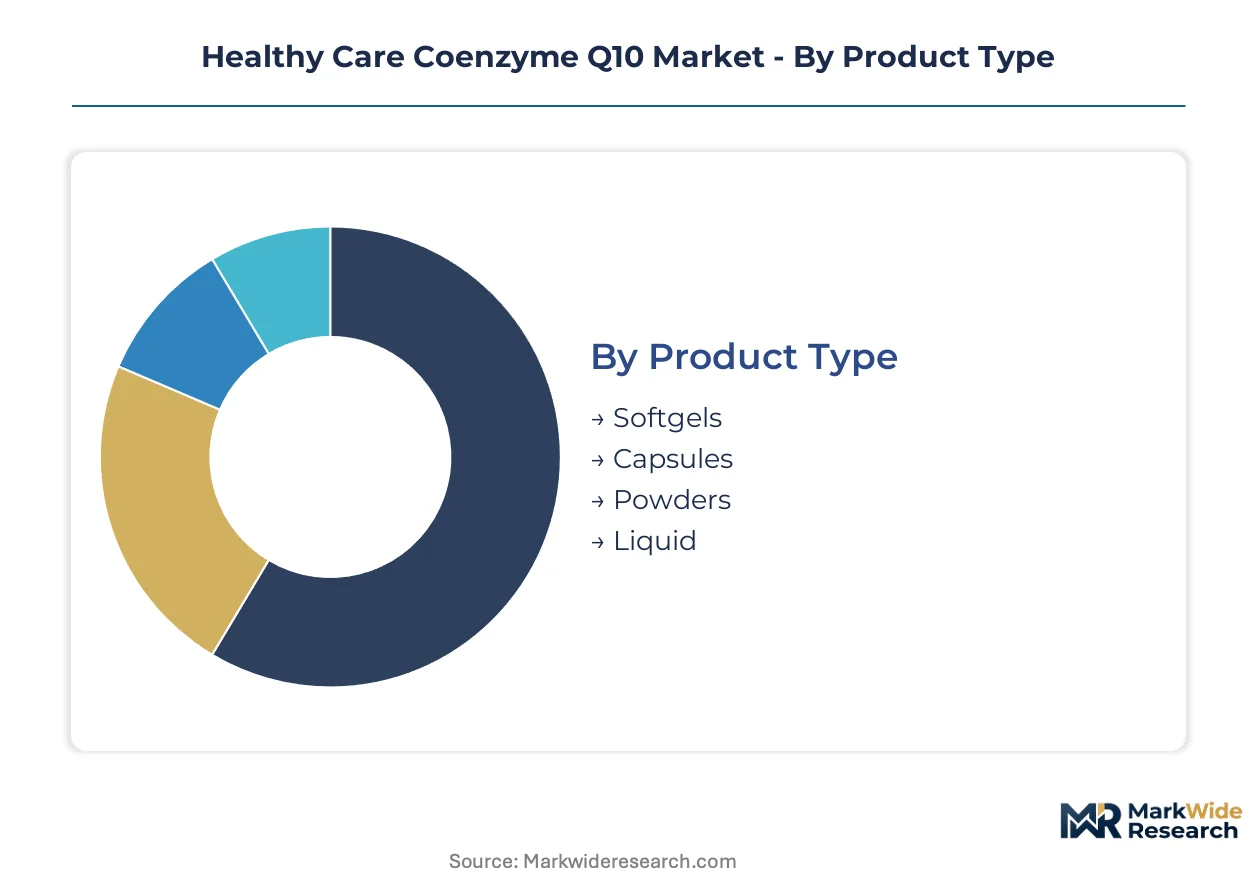
CoQ10 segmentation reveals how bioavailability requirements and regulatory pathways fragment commercial opportunity. Each dimension carries distinct certification burdens and margin profiles that shape manufacturer portfolio strategy.
Product Type:
Softgels demand FDA New Dietary Ingredient notifications for novel oil-matrix formats, while powders fall under conventional food additive thresholds in most jurisdictions. Liquid formulations trigger pharmaceutical-grade stability testing in Japan.
- Softgels:Oil-based matrices encapsulate CoQ10 in lipid carriers that enhance intestinal absorption. Demand concentrates in North American pharmacy retail chains where cardiologist-adjacent recommendations drive repeat purchases. The format commands premium positioning due to superior bioavailability data.
- Powders:Microencapsulated particles enable functional food fortification with controlled release properties. Sports nutrition manufacturers in the United States are integrating these into protein bars and dairy alternatives, though heat stability during processing constrains formulation flexibility.
- Capsules:Two-piece hard shells accommodate vegetarian excipient preferences but sacrifice absorption efficiency without lipid co-formulation.
- Liquid:Emulsion-based delivery suits pediatric and geriatric populations with swallowing difficulties, requiring preservative systems that complicate clean-label positioning.
Softgels sit at the top of the volume ranking, with powders climbing the fastest.
Application:
Cost tier stratification separates commodity nutraceutical supply from pharmaceutical-grade contracts with 3-5x raw material premiums.
- Dietary Supplements:Capsule and softgel formats dominate this mass-market tier with standardized ubiquinone content claims. Retail shelf positioning near cardiovascular health sections drives impulse purchases among aging consumers.
- Pharmaceuticals:Japan's Ministry of Health, Labour and Welfare maintains CoQ10 as an approved cardioprotective agent with batch-level purity documentation. Domestic fermentation capacity prioritizes this channel, forcing international nutraceutical buyers toward synthetic alternatives.
- Functional Foods:Powder integration into beverages and baked goods requires masking technologies to address CoQ10's inherent bitterness and oxidative degradation under thermal processing.
- Nutraceuticals:Positioned between supplements and pharmaceuticals, this segment demands clinical trial substantiation for mitochondrial support claims without full drug registration.
Dietary Supplements capture the largest volume share, with Pharmaceuticals expanding most quickly on regulatory approval tailwinds.
End User:
Customer type segmentation aligns dosing protocols with distinct purchasing behaviors and price sensitivity thresholds.
- Aging Population:Physician-adjacent recommendations drive maintenance-dose regimens with high adherence rates. Direct-to-consumer subscription models capture this cohort through personalized cardiovascular risk assessments.
- Athletes:Exercise-induced oxidative stress management represents premium positioning opportunity with recovery-oriented formulations. This segment shows steepest expansion trajectory as endurance sports participation rises.
- Health Enthusiasts:Early adopters of novel delivery formats including SEDDS-enhanced softgels, willing to pay bioavailability premiums.
- General Consumers:Price-driven purchasers responding to mass-market promotional activity with low brand loyalty and intermittent usage patterns.
Aging Population holds volume leadership, with Athletes gaining share fastest on performance-nutrition crossover appeal.
Distribution Channel:
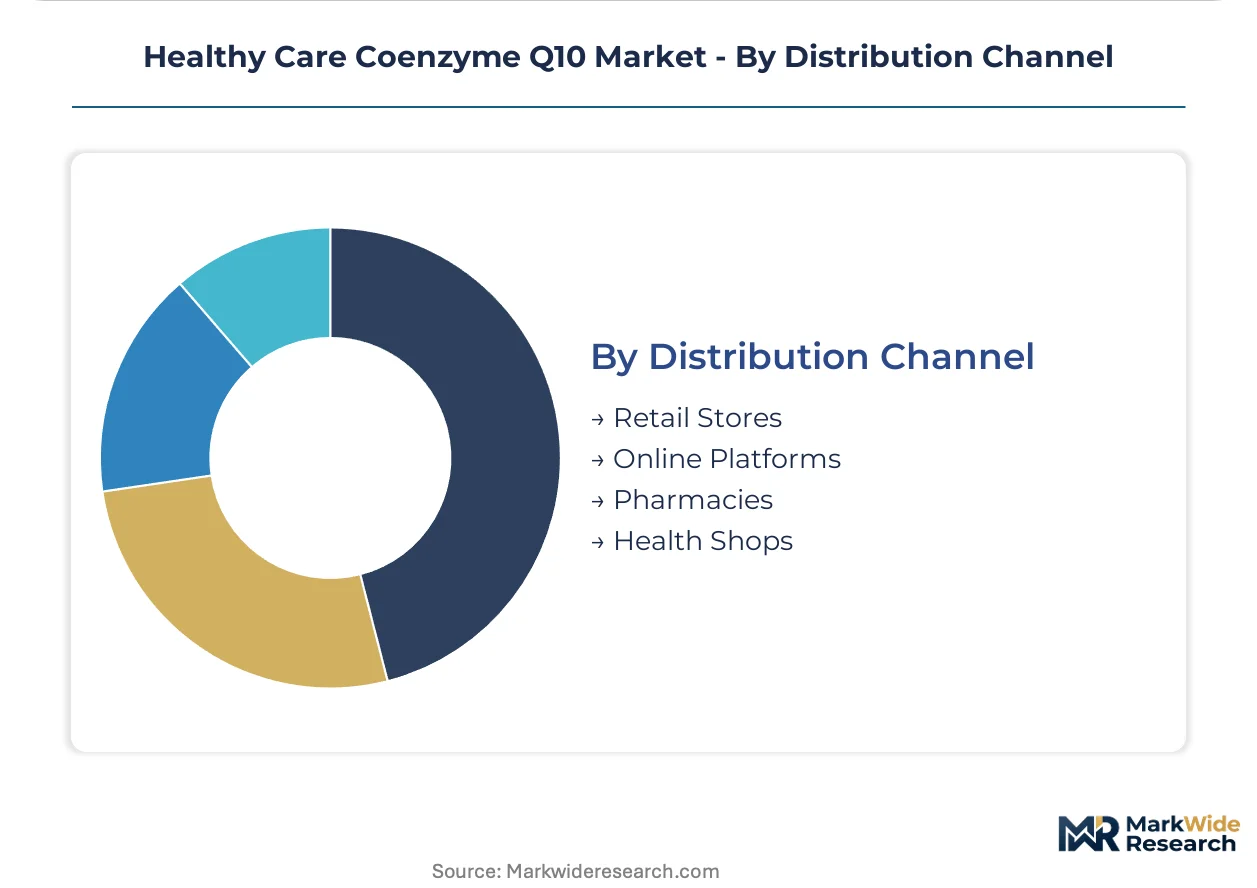
Channel maturity varies by geography, with pharmacy retail consolidating in North America while health shops dominate European positioning.
- Online Platforms:Subscription-based replenishment algorithms leverage self-reported health data to customize dosing protocols. Wellness-focused e-commerce in the United States is displacing traditional pharmacy acquisition for maintenance regimens.
- Pharmacies:Professional endorsement environment supports premium pricing for clinically positioned formulations. Chains require extensive documentation for shelf placement, extending supplier qualification timelines.
- Retail Stores:Mass-market penetration depends on trade spend and promotional calendar alignment with cardiovascular health awareness campaigns.
- Health Shops:Specialty retailers emphasize clean-label attributes and fermentation-derived sourcing narratives to differentiate from synthetic alternatives.
Pharmacies retain volume dominance, with Online Platforms ascending fastest on subscription model traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing CoQ10 production capacity as Japanese manufacturers absorb higher compliance costs for pharmaceutical-grade certification while North American and European buyers seek alternative supply origins to avoid premium pricing.
United States
FDA New Dietary Ingredient notifications for novel ubiquinol delivery formats are accelerating product entry timelines for domestic softgel manufacturers. The agency's Current Good Manufacturing Practices constrain manufacturing consistency requirements for CoQ10 products. Greater Boston anchors pharmaceutical-grade analytical testing capacity while California hosts formulation innovation clusters for SEDDS-enhanced bioavailability platforms.
Japan
The Ministry of Health, Labour and Welfare maintains pharmaceutical-grade CoQ10 as an approved cardioprotective agent with distinct manufacturing requirements from dietary supplements. This regulatory bifurcation compels domestic producers to segregate production lines for pharmaceutical versus nutraceutical output. Kanto/Tokyo fermentation facilities are rebalancing capacity toward pharmaceutical grades, compressing export nutraceutical availability.
Germany
EFSA guidance on ubiquinone-ubiquinol equivalence claims shapes multi-region label strategies for European formulators. REACH compliance obligations for synthetic CoQ10 precursor chemicals add regulatory overhead to chemical production platforms. Bavaria's specialty chemical corridor hosts DSM Nutritional Products' synthetic infrastructure, offering supply security as Asian fermentation pivots toward pharmaceutical grades.
China
NMPA oversight of imported CoQ10 raw materials creates documentation burdens for domestic dietary supplement manufacturers seeking pharmaceutical-grade inputs. The country's dual carbon goals are pressuring energy-intensive fermentation facilities to upgrade wastewater treatment and carbon capture systems. Zhejiang province concentrates contract manufacturing capacity for powder-format CoQ10 destined for functional food fortification.
Switzerland
Swissmedic's pharmaceutical-grade standards attract premium positioning for CoQ10 products targeting clinician-recommended channels. The country's neutrality in regulatory harmonization disputes positions it as a stability testing hub for multi-jurisdiction equivalence documentation. Basel anchors nutraceutical formulation R&D serving European pharmacy retail chains.
Healthy Care Coenzyme Q10 Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional food fortification and athletic recovery positioning to escape commodity pricing pressure. The market structures around fermentation-derived versus synthetic production platform differentiation, with capacity concentration in Japanese and European chemical manufacturing clusters. Three archetypes dominate: proprietary yeast-fermentation specialists, synthetic chemistry platforms, and biotechnology-driven purity standard competitors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure raw material supply amid pharmaceutical-grade demand diversion.
Within the fermentation-specialist tier, Kaneka Corporation and Kyowa Hakko U.S.A. exemplify proprietary biotechnology positioning, while DSM Nutritional Products anchors the synthetic chemistry platform archetype from its European base. These three entities represent divergent supply security strategies as international buyers respond to Japanese capacity rebalancing.
| Leading Market Players |
|---|
| Kaneka Corporation |
| DSM Nutritional Products |
| Kyowa Hakko U.S.A. |
| Gnosis |
| Nature's Bounty |
| PharmaEssentia Corporation |
| Hwail Pharmaceutical |
| Nisshin Seifun Group |
| ZMC-USA |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade procurement diversion from Japanese fermentation facilities is forcing North American and European dietary supplement manufacturers toward synthetic alternatives and elevating contract pricing for remaining nutraceutical supply. This supply rebalancing compresses margins for softgel formulators while creating arbitrage opportunities for DSM Nutritional Products' European chemical platform.
Pricing Analysis
Pharmacy retail markup layers absorb significant margin from manufacturer cost bases, with chain-level slotting fees and promotional spend requirements amplifying price differentiation between clinically positioned and mass-market tiers. Three-tier pricing structure across pharmaceutical-grade, premium nutraceutical, and economy softgel levels separates contract manufacturing quotes by purity certification and stability documentation depth. Pricing pressure stems from Kaneka Corporation's single-source ubiquinol concentration as buyers seek supply security premiums. Aging population segments show lowest price sensitivity due to physician-adjacent recommendation trust, while general consumers exhibit highest elasticity responding to promotional calendar timing.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore manage hub-and-spoke patterns for CoQ10 raw material flow, with temperature-controlled warehousing addressing lipid carrier stability requirements. Supply concentrates in Japan, the Netherlands, and the United States as pharmaceutical-grade fermentation and synthetic chemistry platforms anchor production. Raw material dependencies include pharmaceutical-grade yeast culture media, specialized lipid carriers for softgel matrices, and gelatin or vegetarian shell alternatives. Single-source vulnerability around Kaneka's proprietary ubiquinol technology creates procurement concentration risk for international formulators. Distribution runs through pharmacy retail chains in North America, direct-to-consumer subscription platforms, and health shop networks in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthy Care Coenzyme Q10 functions as a stable compounder anchored by irreversible aging demographics and chronic cardiovascular wellness prioritization across developed economies. Regulatory bifurcation between pharmaceutical and nutraceutical grades sustains margin tier separation.
For Market Incumbents: Deploy backward integration into pharmaceutical-grade yeast fermentation capacity to capture regulatory premium flows as Japanese supply diverts toward domestic drug channels. Secure long-term offtake agreements with DSM Nutritional Products' synthetic platform to hedge Kaneka concentration exposure. Invest in SEDDS-enhanced softgel R&D to maintain bioavailability positioning against emerging powder-format functional food competitors. For New Entrants and Emerging Players: Self-emulsifying drug delivery system technology offers white-space entry around athletic recovery formulations with premium mitochondrial support claims. Athletic end-user segments remain underpenetrated relative to aging population saturation, presenting fastest expansion trajectory for novel positioning. Direct-to-consumer subscription acquisition models bypass pharmacy retail gatekeeping and capture recurring revenue through personalized dosing protocols based on self-reported cardiovascular risk factors. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology-driven purity standard specialists possessing dual-grade manufacturing flexibility across pharmaceutical and nutraceutical certification tiers. Five-to-ten year viability hinges on regulatory harmonization progress across FDA, EFSA, and Japan's MHLW jurisdictions. Monitor pharmacopeial standard convergence signals as inflection indicator for multi-region label claim scalability and inventory pooling efficiency gains.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Fermentation Capacity Expansion | Captures MHLW-approved cardioprotective agent premiums as Japanese supply diverts domestically. |
| SEDDS-Enhanced Softgel Platform Development | Achieves pharmacokinetic parity with ubiquinol at reduced raw material input costs for mass-market positioning. |
| Synthetic CoQ10 Supply Agreement | Secures DSM Nutritional Products' European chemical infrastructure against Asian fermentation rebalancing. |
| Athletic Recovery Formulation Launch | Targets fastest-growing end-user segment with exercise-induced oxidative stress management claims. |
| Direct-to-Consumer Subscription Infrastructure | Displaces pharmacy retail dependency through personalized cardiovascular risk assessment algorithms. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with formulation scientists, dietary supplement procurement managers, pharmacy retail category buyers, and regulatory affairs specialists with secondary validation. FDA New Dietary Ingredient notification databases, Japan's MHLW approved drug specifications, EFSA guidance documents, and customs trade flow records provide triangulation anchors. Fermentation capacity utilization rates and pharmaceutical-grade purity certification databases supply production-side calibration points.
Historical trendline analysis across softgel, powder, capsule, and liquid format adoption patterns informs segmentation-level trajectory projection. Modeling incorporates product type, application tier, end-user demographic, and distribution channel dimensions throughout the forecast period. CAGRs derive from elasticity-adjusted demand curves calibrated against aging population growth rates and athletic participation expansion. Raw material input cost volatility indices and regulatory approval timeline distributions feed scenario-weighted output ranges.
The model holds under stable regulatory bifurcation between pharmaceutical and nutraceutical grades; deviation in pharmacopeial standard harmonization or fermentation capacity rebalancing velocity would shift supply security premiums and pricing tier separation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Hair Growth Supplement and Treatment Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Global 5-Hydroxytryptophan (5-HTP) Market