
 Neurology Services Market | 2026-2036
Neurology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Neurology Services Market Foresight
The EU Green Deal is restructuring neurology service procurement across European hospital networks, pushing providers toward lower-carbon diagnostic equipment and sustainable facility operations. Mayo Clinic Health System leverages its integrated care model to anchor multi-state neurology delivery. Cleveland Clinic competes through deep specialization in stroke and epilepsy protocols. Johns Hopkins University sustains research-to-clinical pipelines that differentiate its academic medical center offerings.
Neurology services encompass the clinical evaluation, diagnostic investigation, therapeutic intervention, and longitudinal management of disorders affecting the central and peripheral nervous systems, employing neuroimaging resolution thresholds below one millimeter and electrophysiological sampling rates exceeding 256 channels for precise localization of pathological activity. These services address stroke, epilepsy, neurodegenerative conditions, and chronic headache syndromes through multidisciplinary teams spanning neuroradiology, neurosurgery, and rehabilitation medicine. Diagnostic Testing commands substantial margin pools due to high capital intensity in MRI and CT infrastructure, while Telemedicine extends reach into underserved geographies with lower fixed-cost profiles. Rehabilitation services occupy mature positions in post-acute care, though Home Care segments are gaining traction as remote monitoring technologies advance.
The FDA governs neurotherapeutic device approvals and diagnostic algorithm validations, while HIPAA mandates data security protocols for patient records across all delivery settings. State-level certificate-of-need regulations constrain imaging capacity expansion in concentrated markets, shaping competitive dynamics. Stakeholders must monitor reimbursement policy evolution for remote neurology consultations and decide on capital allocation between centralized hub facilities and distributed telemedicine nodes.
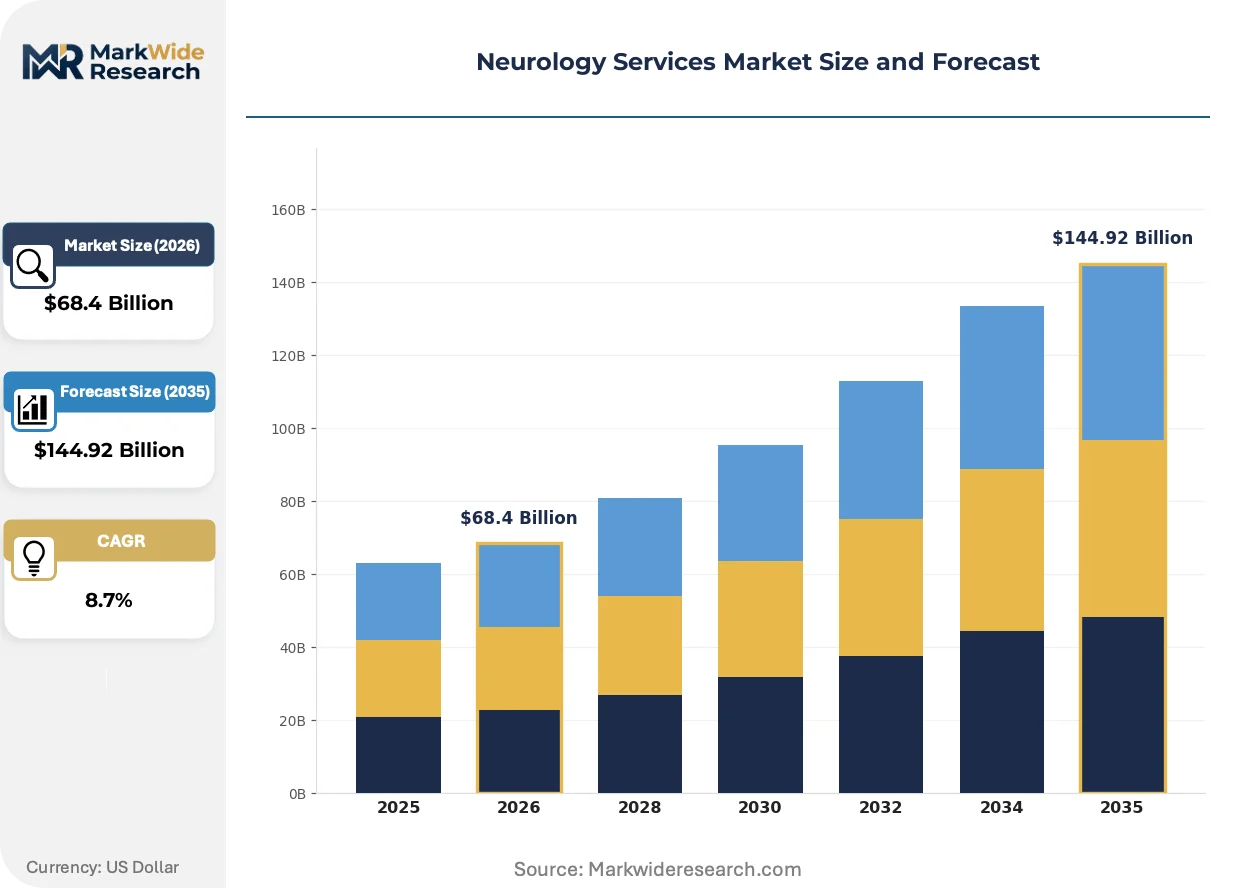
Market Dynamics
The FDA's accelerated approval pathways for neurotherapeutics are compressing clinical trial timelines and forcing hospital systems to restructure service capabilities around faster therapeutic integration. This regulatory velocity is reshaping capital allocation across diagnostic infrastructure and care delivery models.
Growth Catalysts
- Accelerated FDA Pathways:The FDA's breakthrough therapy and fast track designations for amyloid-targeting Alzheimer's treatments are pulling demand toward specialized infusion centers and biomarker testing protocols.
- Stroke Network Expansion:Hospital systems across the United States are building comprehensive stroke centers with 24/7 thrombectomy capabilities, driving investment in neurointerventional suites and mobile stroke units.
- Remote Monitoring Platforms:Wearable EEG and seizure detection devices are extending neurology service reach into rural geographies previously dependent on episodic specialist visits.
Market Restraints
- Certificate-of-Need Constraints:State-level CON regulations in New York, California, and Illinois block imaging capacity expansion in concentrated urban markets, protecting incumbent providers.
- Specialist Supply Bottlenecks:The four-year fellowship training pipeline for vascular neurologists creates persistent mismatch between stroke incidence and interventionist availability.
- MRI Gadolinium Cost Volatility:Supply concentration among Chinese rare earth processors exposes diagnostic centers to contrast agent price swings and procurement uncertainty.
Strategic Opportunities
- Home-Based Rehabilitation:FDA-cleared robotic exoskeletons and VR-based motor therapy platforms are opening post-stroke care segments outside traditional facility-based settings.
- EU Green Deal Procurement:European hospital networks are rewriting tender specifications to prioritize lower-carbon MRI systems and sustainable facility operations, creating differentiation for compliant vendors.
- AI-Assisted Triage:Machine learning algorithms for large vessel occlusion detection are converging with mobile CT imaging to compress door-to-needle intervals in emergency departments.
Industry Challenges
- Interoperability Fragmentation:Proprietary data formats from Siemens, GE, and Philips imaging platforms block seamless integration with Epic and Cerner EHR systems, forcing costly interface development.
- Neurointerventional Talent Wars:Academic medical centers compete aggressively for dual-trained neurosurgeons capable of both open and endovascular procedures, compressing compensation structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurology Services Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Diagnostic Testing, Rehabilitation, Surgical Treatment Technology: EEG, MRI, CT Scan, Telemedicine End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Therapy Area: Epilepsy, Stroke, Neurodegenerative Disorders, Headaches |
| Companies Covered | NewYork-Presbyterian Hospital, Mayo Clinic Health System, Cleveland Clinic, Johns Hopkins University, Northwestern Medicine, Sutter Health, Emory Healthcare, Barrow Neurological Institute, Harvard Medical School, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurology Services Market Shifts & Advancements
Neurology service delivery is fragmenting across physical and virtual channels as diagnostic resolution thresholds tighten and therapeutic modalities diversify. Three forces are actively restructuring competitive positioning.
High-field 7 Tesla MRI is expanding into clinical applications previously confined to research protocols, delivering sub-millimeter resolution for hippocampal volumetry and cortical layer imaging. Academic medical centers in Boston and Baltimore are deploying these systems for early Alzheimer's detection, compressing the timeline between research validation and reimbursed clinical use. The technology is expanding into community hospital networks as magnet reliability improves and siting requirements relax.
The EU AI Act's risk classification framework for medical devices is forcing neurology software developers to restructure algorithm validation protocols before CE marking. Diagnostic algorithms for stroke detection and seizure prediction now face mandatory post-market monitoring and bias auditing requirements. European hospital procurement committees are prioritizing MDR-compliant AI tools, displacing non-certified competitors from tender shortlists.
Episodic fee-for-service neurology consultations are yielding to longitudinal care contracts bundled across diagnosis, acute intervention, and rehabilitation phases. Medicare Advantage plans in Florida and Arizona are piloting these arrangements for Parkinson's and multiple sclerosis populations, shifting financial risk toward provider systems capable of managing total cost of care. The model is compressing specialist visit frequency while expanding remote monitoring and nurse navigator staffing.
Neurology Services Market Segmentation
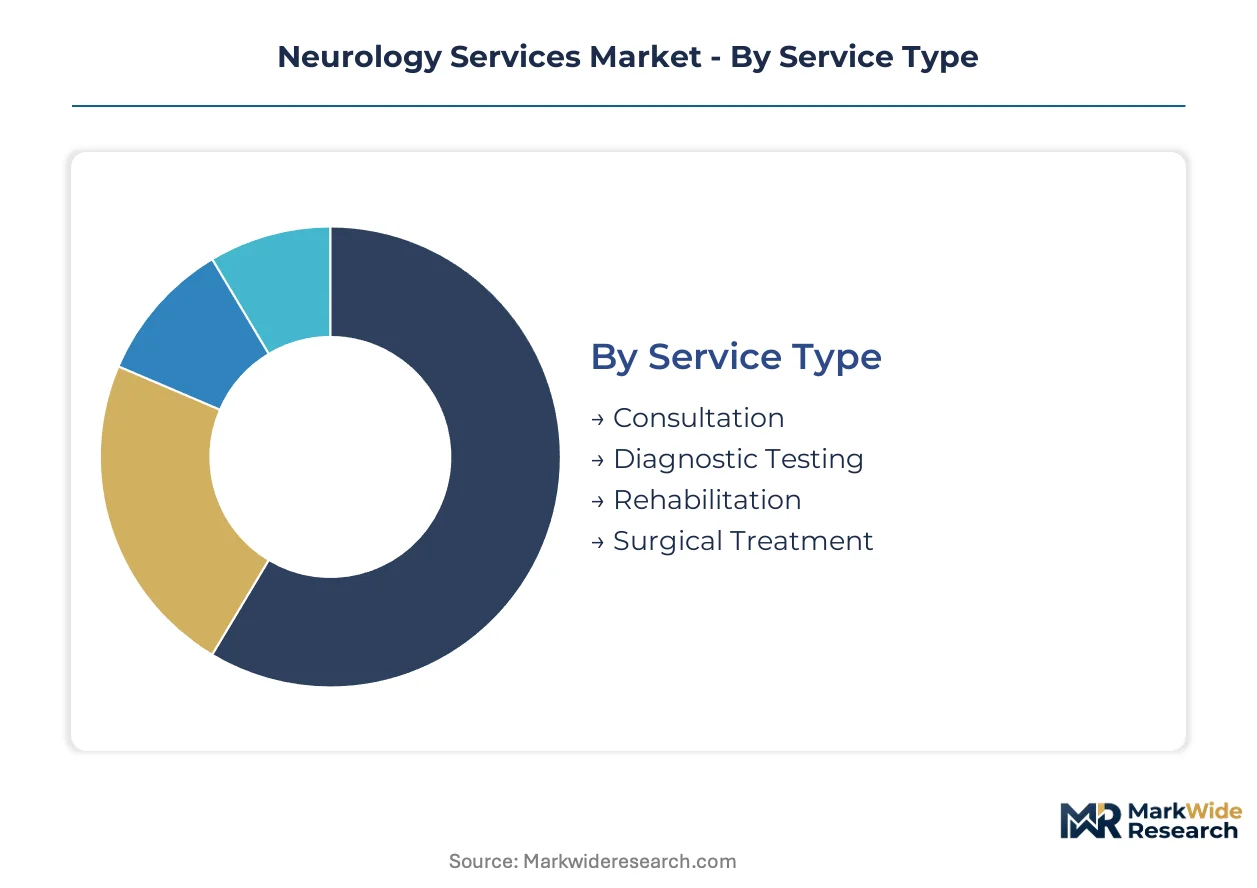
Neurology services fragment across distinct technical capabilities and care settings. Each segment carries unique capital intensity, reimbursement profiles, and competitive dynamics that shape provider strategy and patient access patterns.
Service Type:
Capital deployment and margin profiles vary sharply across service modalities, with reimbursement velocity and fixed-cost intensity driving buyer selection criteria.
- Consultation:Clinical assessment and longitudinal management delivered by board-certified neurologists. Demand clusters in academic medical centers and large integrated systems where complex case volumes justify subspecialist staffing. Medicare Advantage bundles are compressing visit frequency while expanding remote consultation platforms.
- Diagnostic Testing:Neuroimaging and electrophysiological evaluation employing MRI, CT, and EEG modalities. High capital intensity in magnet and scanner infrastructure creates barrier-to-entry moats around established hospital networks. CON regulations in concentrated urban markets protect incumbent imaging capacity.
- Rehabilitation:Post-acute motor, cognitive, and speech therapy following neurological injury. Skilled nursing facilities and inpatient rehabilitation hospitals capture Medicare fee-for-service episodes, though home-based platforms are eroding facility-based volume.
- Surgical Treatment:Open and endovascular interventions including thrombectomy, tumor resection, and deep brain stimulation. Dual-trained neurosurgeon scarcity concentrates these services at quaternary referral centers with 24/7 neurointerventional coverage.
Volume sits with Diagnostic Testing; growth tilts toward Consultation as telemedicine extends reach.
Technology:
Resolution thresholds and data throughput requirements determine equipment replacement cycles and vendor lock-in severity across diagnostic modalities.
- EEG:Electroencephalography capturing cortical electrical activity through scalp electrode arrays. Ambulatory and wearable form factors are displacing inpatient monitoring for epilepsy diagnosis, with AI-assisted spike detection reducing interpretation burden.
- MRI:Magnetic resonance imaging delivering sub-millimeter structural and functional neuroimaging. 7 Tesla systems are migrating from research protocols into clinical use for early Alzheimer's detection at academic centers in Boston and Baltimore.
- CT Scan:Computed tomography providing rapid hemorrhage and large vessel occlusion detection in emergency settings. Mobile stroke units equipped with portable CT compress door-to-needle intervals for thrombolysis candidates.
- Telemedicine:Remote consultation and monitoring platforms extending specialist access into underserved geographies. HIPAA-compliant video infrastructure and asynchronous store-and-forward imaging are replacing episodic rural outreach clinics.
Revenue concentrates in MRI; telemedicine platforms are climbing the fastest as reimbursement parity expands.
End User:
Site-of-care economics and regulatory licensing requirements shape competitive positioning across delivery settings.
- Hospitals:Inpatient and emergency neurology services anchored by comprehensive stroke centers and neurocritical care units. Thrombectomy capability and 24/7 neuroradiology coverage differentiate tiered stroke center designations.
- Clinics:Outpatient neurology offices handling chronic disease management and pre-surgical evaluation. Private practice consolidation into hospital-employed models is accelerating under value-based contract pressure.
- Rehabilitation Centers:Dedicated post-acute facilities for stroke, spinal cord, and traumatic brain injury recovery. Medicare reimbursement cuts to skilled nursing facilities are shifting volume toward inpatient rehabilitation hospitals.
- Home Care:Remote monitoring and visiting nurse services for stable chronic neurological conditions. FDA-cleared robotic exoskeletons and VR motor therapy platforms are opening new reimbursement categories outside facility walls.
Patient volume aggregates at Hospitals; Home Care segments are gaining share fastest as monitoring technologies mature.
Therapy Area:
Disease prevalence trajectories and therapeutic innovation pipelines determine service line investment priority across neurological conditions.
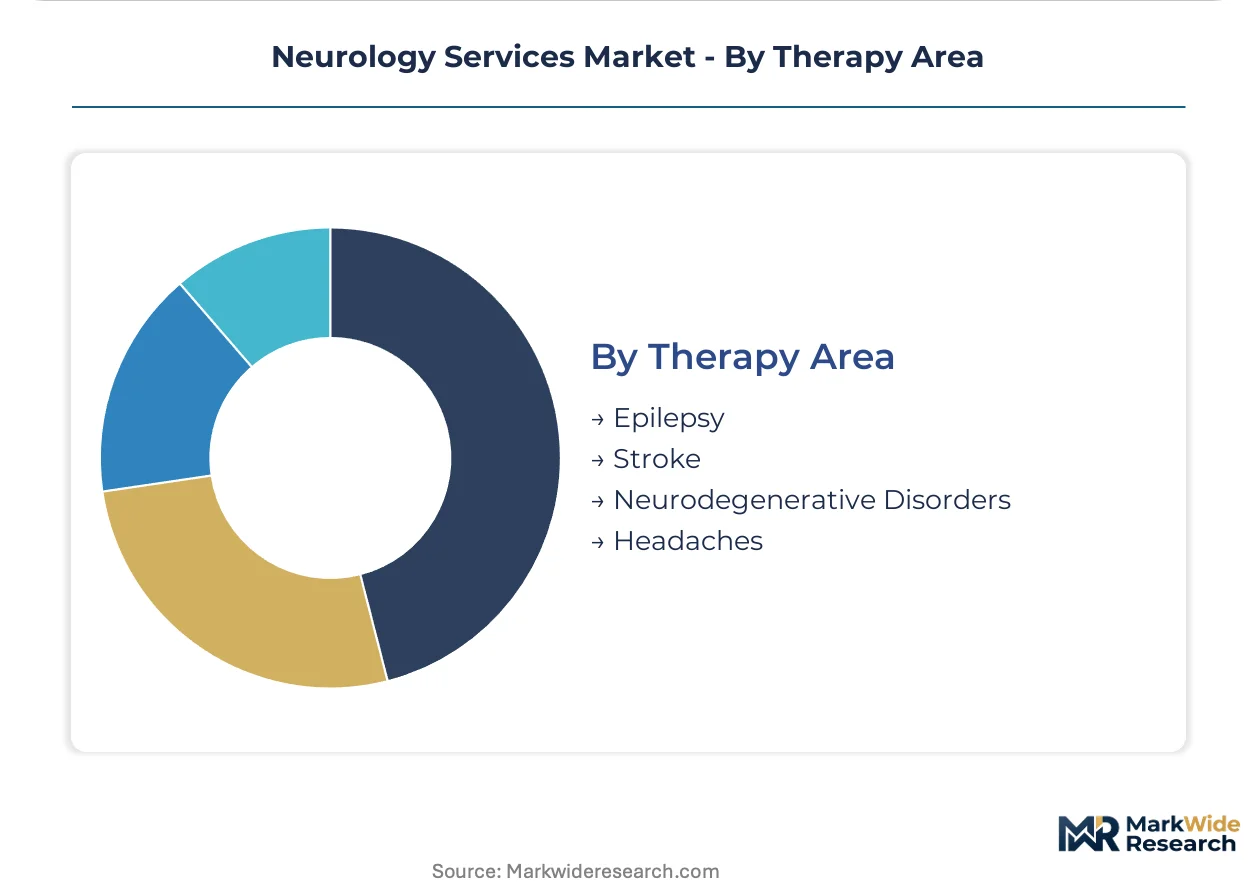
- Epilepsy:Seizure disorder management spanning medication optimization, surgical candidacy evaluation, and device implantation. Responsive neurostimulation and laser ablation are expanding intervention candidates beyond traditional resection.
- Stroke:Acute ischemic and hemorrhagic cerebrovascular event management with thrombectomy and neurocritical care. Networked stroke systems with mobile CT and helicopter transport are restructuring regional referral patterns.
- Neurodegenerative Disorders:Alzheimer's, Parkinson's, and ALS management combining symptomatic care and emerging disease-modifying therapy. FDA accelerated approval pathways for amyloid-targeting treatments are pulling demand toward specialized infusion centers.
- Headaches:Chronic migraine and cluster headache intervention including Botox injection, CGRP antagonist administration, and neuromodulation device trialing. Academic headache centers differentiate through multidisciplinary pain psychology integration.
Service volume concentrates in Stroke; Neurodegenerative Disorders show the steepest expansion trajectory as therapeutic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors neurology service innovation, with Massachusetts General Hospital and Brigham and Women's Hospital driving clinical trial density and 7 Tesla MRI deployment that shapes patterns replicated across developed healthcare systems.
United States
Aging demographics and stroke prevalence concentrate demand in the Southeast and Midwest, where hospital systems expand comprehensive stroke center networks. FDA accelerated approval pathways for amyloid-targeting Alzheimer's therapies pull investment toward specialized infusion centers and biomarker testing infrastructure. Mayo Clinic Health System leverages its integrated care model to anchor multi-state neurology delivery across Minnesota, Wisconsin, and Iowa.
Germany
Neurodegenerative disease burden and precision diagnostic adoption drive service expansion in Bavaria and Baden-Württemberg. The EU AI Act's risk classification framework forces algorithm validation restructuring before CE marking, displacing non-compliant diagnostic software from hospital procurement shortlists. Heidelberg University Hospital clusters advanced neuroimaging research with clinical translation in the Rhine-Neckar metropolitan region.
Japan
Super-aging population dynamics and Parkinson's disease prevalence create sustained demand for movement disorder specialists. METI funding for healthcare robotics accelerates FDA-cleared exoskeleton adoption in post-stroke rehabilitation protocols. The Keiyō industrial corridor between Tokyo and Chiba concentrates neuroimaging equipment manufacturing with adjacent clinical validation sites.
United Kingdom
NHS England's integrated care systems restructure neurology referral pathways toward centralized hub-and-spoke models. MHRA alignment with FDA breakthrough therapy designations compresses timelines for neurotherapeutic market entry. London's Queen Square and the Cambridge biomedical campus anchor academic-clinical pipelines for epilepsy and neurodegenerative therapeutics.
Australia
Rural geography and specialist distribution inequities drive telemedicine platform investment for remote consultation delivery. TGA streamlined approval pathways for software-based medical devices accelerate AI-assisted stroke detection deployment in emergency departments. Melbourne's Parkville biomedical precinct clusters neuroimaging research with commercial translation capabilities.
Neurology Services Market Competitive Landscape
The competitive structure tilts toward academic medical center dominance, with quaternary referral hospitals capturing complex case volume through fellowship-trained specialist concentration and research-to-clinical translation pipelines. Three archetypes define positioning: integrated multi-state health systems with captive neurology networks; standalone academic medical centers leveraging NIH funding density; and specialized neurological institutes built around single-disease deep expertise. Consolidation through hospital system employment of private neurology practices accelerates, while telemedicine partnerships extend geographic reach without fixed-capital deployment.
Among US-based academic medical centers, Mayo Clinic Health System, Cleveland Clinic, and Johns Hopkins University anchor distinct competitive positions. Mayo Clinic exemplifies the integrated-system archetype through its multi-state care delivery and standardized protocol replication. Cleveland Clinic occupies the specialized-institute position with concentrated stroke and epilepsy service depth. Johns Hopkins represents the research-intensive academic model, sustaining longitudinal pipelines from laboratory validation to reimbursed clinical application. These three institutions collectively illustrate how scale, specialization, and science translation differentiate positioning in a market where specialist scarcity and capital intensity create persistent barrier-to-entry moats.
| Leading Market Players |
|---|
| NewYork-Presbyterian Hospital |
| Mayo Clinic Health System |
| Cleveland Clinic |
| Johns Hopkins University |
| Northwestern Medicine |
| Sutter Health |
| Emory Healthcare |
| Barrow Neurological Institute |
| Harvard Medical School |
| Others |
Supply & Pricing Matrix
Hospital-employed neurology specialists rolled up through private-equity-backed practice acquisitions are tightening supply discipline and compressing fee schedules across diagnostic and consultation segments. This ownership concentration feeds directly into pricing power erosion for standalone clinics while reinforcing margin pools at integrated systems with captive referral networks.
Pricing Analysis
Value-based pricing anchored to episode-of-care outcomes is displacing fee-for-service neurology consultations in Medicare Advantage contracts across Florida and Arizona. Three-tier pricing structure across academic medical centers, community hospitals, and telemedicine platforms differentiates access speed and specialist credential depth. Cost compression in community hospital diagnostic testing is intensifying because CON-protected incumbents face ambulatory surgical center competition. Price sensitivity concentrates among uninsured and high-deductible plan populations in rural geographies, while academic medical centers command premium positioning through research-affiliated specialist density.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processors supplying gadolinium contrast agents for MRI neuroimaging. Magnet manufacturing draws from Germany, Japan, and the United States, while EEG electrode arrays source predominantly from Malaysia and Mexico. Tariff exposure on Chinese-processed rare earths creates procurement uncertainty for diagnostic centers dependent on stable contrast agent pricing. Distribution runs through GPO-negotiated contracts with hospital systems, though direct-to-hospital procurement is gaining traction as 7 Tesla MRI deployment accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurology services are consolidating into integrated health system employment as value-based contracts and specialist scarcity force independent practice exits. Certificate-of-need restrictions and imaging capital intensity protect incumbent positions while squeezing marginal competitors.
For Market Incumbents: Extend telemedicine platform reach into rural geographies previously served by episodic outreach clinics, capturing volume before standalone competitors achieve reimbursement parity. Deepen backward integration into remote monitoring device supply through FDA-cleared wearable EEG partnerships, locking in proprietary data streams that differentiate longitudinal care contracts. For New Entrants and Emerging Players: Telemedicine-as-a-service platforms offer the lowest-friction entry vector for neurology consultation delivery, bypassing magnet capital requirements that block diagnostic testing segments. Target home-based rehabilitation for post-stroke populations in states with favorable remote therapeutic monitoring reimbursement, leveraging FDA-cleared robotic exoskeleton distribution partnerships to bypass facility-based competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor hospital-employed neurology groups in Midwestern states with aging demographics and stroke belt prevalence, where Medicare Advantage penetration is accelerating value-based contract adoption. Watch FDA accelerated approval velocity for amyloid-targeting therapies as the inflection signal for specialized infusion center infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Expansion | Extends specialist reach into CON-constrained rural markets without imaging capital deployment. |
| 7 Tesla MRI Clinical Deployment | Positions academic centers for early Alzheimer's detection reimbursement at sub-millimeter resolution thresholds. |
| Home-Based Rehabilitation Partnership | Captures post-acute stroke volume outside facility walls through FDA-cleared robotic and VR platforms. |
| EU Green Deal Compliance Investment | Secures tender positioning in European hospital networks prioritizing lower-carbon diagnostic equipment. |
| AI-Assisted Triage Integration | Compresses door-to-needle intervals through machine learning convergence with mobile CT imaging. |
Research Methodology
Multi-period observation of stroke center designation trends, FDA neurotherapeutic approval pathways, and Medicare Advantage contract proliferation anchored the trend analysis, supplemented by interviews with vascular neurologists, neuroradiology department heads, hospital procurement managers, and GPO contracts specialists. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare claims data, state certificate-of-need databases, and hospital procurement records. Bottom-up service line revenue modeling and top-down health system expenditure analysis were triangulated against specialist supply estimates from ACGME fellowship match data.
Input-output matrices mapped neuroimaging procedure volumes, consultation encounter frequencies, and rehabilitation episode lengths against demographic prevalence projections and therapeutic pipeline maturation timelines across the analysis window. Segmentation dimensions included service type, technology modality, site-of-care setting, and disease-specific therapy area. CAGRs were derived from logistic diffusion curves fitted to technology adoption patterns and reimbursement policy phase-in schedules, with sensitivity testing around FDA approval velocity and CON regulatory stringency.
The model holds under stable Medicare reimbursement and CON regulatory frameworks; deviation in FDA accelerated approval withdrawal or state-level imaging deregulation would shift competitive positioning toward standalone diagnostic centers. Forecasts reflect documented assumptions about specialist training pipeline output and therapeutic commercialization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Bell Palsy Treatment Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Neuroprotection Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Italy Neurology Devices Market
Neurology
CNS Treatment and Therapy Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Netherlands Neurology Devices Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Nerve Repair Market
Neurology
Acute Repetitive Seizures Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Frontotemporal Disorders Treatment Market