
 Neuroprotection Market | 2026-2036
Neuroprotection Market Size, Share, and Industry Trends Forecast 2026-2036
Neuroprotection Market Outlook
Modular combination regimens pairing antioxidants with neurotrophic factors is expanding as a preferred configuration for acute stroke protocols. Novartis AG leverages its neuroscience pipeline depth to anchor European hospital adoption of bundled neuroprotective therapies. Biogen Inc. specializes in amyloid-targeting adjacencies that extend its platform into complementary neuroprotection mechanisms. Teva Pharmaceutical Industries Ltd. competes on generic neuroprotective accessibility across rehabilitation center channels in multiple geographies.
Neuroprotection encompasses pharmacological and biological interventions designed to prevent neuronal death, preserve synaptic integrity, and modulate inflammatory cascades following ischemic, traumatic, or degenerative insults to the central nervous system. These therapies typically operate through calcium channel modulation, free radical scavenging, or neurotrophic factor supplementation to maintain cellular homeostasis and reduce secondary injury propagation. Among product types, antioxidants occupy the mature volume base while neurotrophic factors capture concentrated margin pools due to manufacturing complexity and orphan indication pricing. The application landscape shows stroke and traumatic brain injury driving near-term utilization, with Alzheimer's Disease representing the longest-duration revenue horizon as disease-modifying trials mature.
FDA breakthrough therapy designations and EMA PRIME eligibility criteria are compressing clinical development timelines for neuroprotective candidates targeting Parkinson's Disease and amyotrophic lateral sclerosis. The EU MDR and FDA 21 CFR Part 312 standards govern investigational new drug applications and post-market surveillance, directly shaping trial design investments and market access negotiations for sponsors. Stakeholders must monitor biomarker qualification progress and payer evidence requirements for functional outcome measures as the threshold for reimbursement tightens across hospital and rehabilitation settings.
Market Dynamics
FDA breakthrough therapy designations and EMA PRIME eligibility criteria are compressing clinical development timelines for neuroprotective candidates, while hospital procurement committees increasingly bundle neuroprotective agents into acute stroke protocol formularies.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy and EMA PRIME designations compress Phase II-to-approval timelines for Parkinson's Disease and ALS candidates. Hospital pharmacy committees fast-track formulary inclusion for designated therapies.
- Aging Demographics:Germany, Japan, and the United States exhibit converging demand as neurology infrastructure expands to address stroke and traumatic brain injury patient volumes.
- Biomarker Qualification:CSF neurofilament light chain and plasma p-tau standards are hardening surrogate endpoints, enabling smaller trial designs and earlier go/no-go decisions.
Market Restraints
- Manufacturing Complexity:Neurotrophic factor production requires mammalian cell culture systems with 18-24 month capacity lead times, constraining supply elasticity for orphan indications.
- Reimbursement Threshold Hardening:CMS and Germany's G-BA demand functional outcome measures beyond mortality reduction, extending market access negotiations.
- Clinical Trial Failure Rates:Neurodegenerative disease-modifying trials exhibit high Phase III attrition, dampening private capital deployment into early-stage neuroprotection platforms.
Strategic Opportunities
- Rehabilitation Channel Expansion:Post-acute care facilities in the United States represent underpenetrated prescription volume for oral neuroprotective maintenance regimens.
- Modular Combination Protocols:Antioxidant-neurotrophic factor pairings enable premium positioning within bundled stroke care payments.
- Digital Biomarker Integration:Wearable motor function sensors and smartphone-based cognitive assessments create endpoint innovation opportunities for ambulatory neuroprotection trials.
Industry Challenges
- Specialized Investigator Recruitment:Qualified principal investigators for neurodegenerative trials concentrate at academic medical centers in Boston, Heidelberg, and Tokyo, creating site activation bottlenecks.
- Legacy EDC Integration:Electronic data capture systems at CROs require reconfiguration to capture digital biomarker streams, extending study startup timelines.
- Patent Thicket Navigation:Calcium channel modulator and free radical scavenger compound classes face dense prior art, complicating freedom-to-operate analyses for new molecular entities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuroprotection Market |
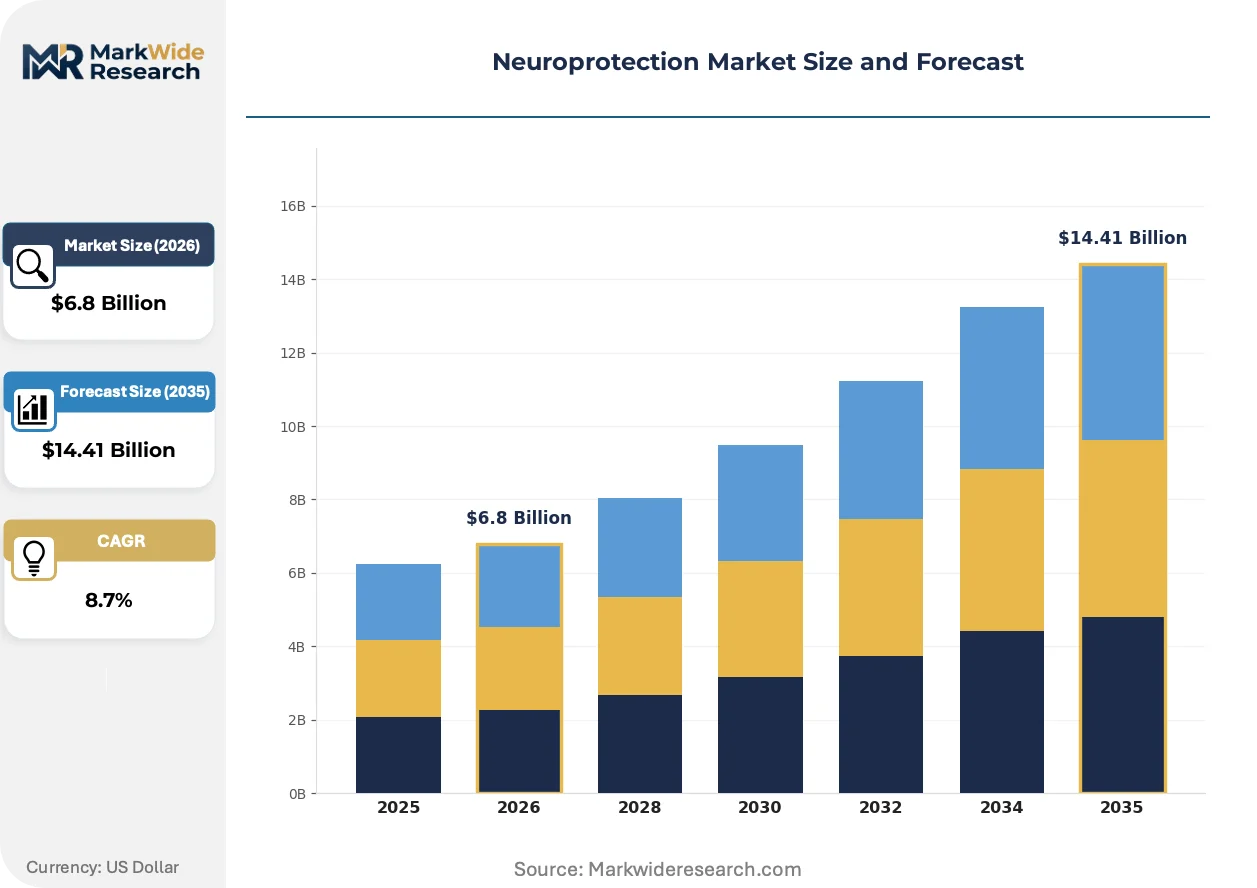
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Neurotrophic Factors, Calcium Channel Blockers, Omega-3 Fatty Acids Application: Alzheimer's Disease, Parkinson's Disease, Stroke, Traumatic Brain Injury End User: Hospitals, Research Institutes, Pharmaceutical Companies, Rehabilitation Centers Treatment Mode: Intravenous, Oral, Transdermal, Intra-arterial |
| Companies Covered | Novartis AG, Roche Holding AG, Biogen Inc., Pfizer Inc., AstraZeneca PLC, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Johnson & Johnson, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuroprotection Market Strategic Shifts
Neuroprotection development is pivoting from monotherapy paradigms toward combination regimens and digital endpoint integration, with regulatory science evolving in parallel to accommodate novel trial designs.
Point-of-care biomarker platforms are decentralizing stroke triage decisions by enabling rapid neurofilament light chain quantification in emergency departments. Neurology departments at academic medical centers in the United States and Germany are piloting these systems to compress treatment initiation windows. This capability is decentralizing protocol enrollment authority from centralized laboratories to bedside clinicians, reshaping site selection criteria for sponsors.
EMA's PRIME eligibility criteria and FDA's breakthrough therapy designation framework are compressing development timelines for amyotrophic lateral sclerosis and Parkinson's Disease candidates. Sponsors gain enhanced regulatory dialogue and rolling review access, reducing time-to-submission by 12-18 months in qualified programs. Neurodegenerative indications with validated biomarker strategies capture disproportionate designation rates, redirecting pipeline investment toward these categories.
Hospital pharmacy committees are consolidating neuroprotective procurement into bundled acute stroke protocol contracts, displacing standalone product purchasing. Integrated delivery networks in the United States and hospital chains in Germany negotiate multi-agent formularies with outcome guarantees. This concentration is visible most acutely in stroke centers with Level I trauma designation, where protocol standardization reduces clinical variation.
Neuroprotection Market Segmentation
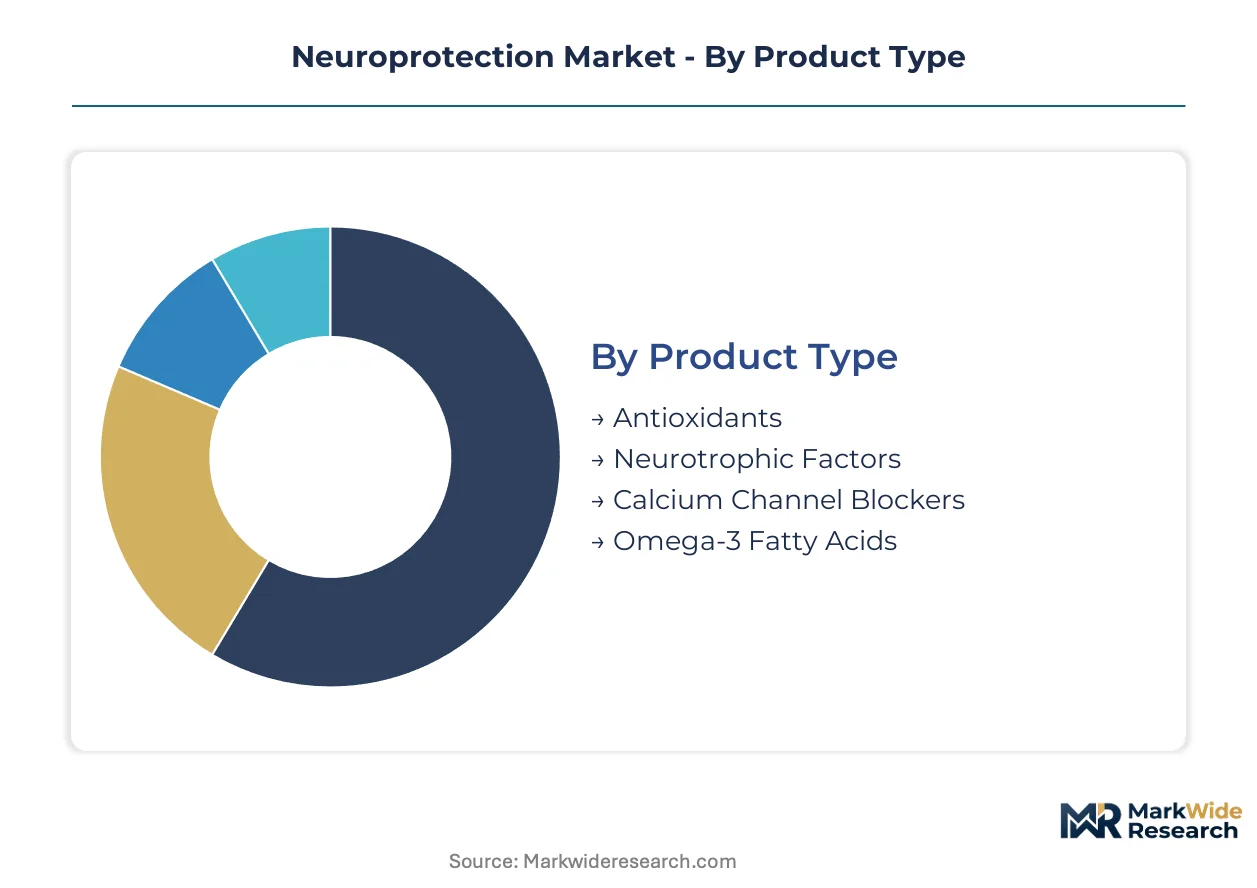
Neuroprotection market segmentation reveals divergent capital requirements and margin profiles across therapeutic modalities. Manufacturing intensity varies dramatically between small-molecule antioxidants and biologic neurotrophic factors, reshaping competitive entry barriers and partnership strategies.
Product Type:
Capital intensity peaks with mammalian cell culture requirements for biologics, while small-molecule synthesis offers faster capacity scaling.
- Antioxidants:Synthetic compounds including edaravone and N-acetylcysteine deploy established chemical manufacturing infrastructure with 12-18 month facility commissioning cycles. Hospital pharmacies in the United States and Germany concentrate procurement for acute stroke protocols, though pricing pressure from bundled care contracts compresses margins.
- Neurotrophic Factors:Recombinant proteins such as BDNF and GDNF analogs require GMP-compliant mammalian expression systems with 24-36 month capacity lead times and cold-chain distribution networks. Orphan indication pricing in Japan and the United States supports premium positioning, but manufacturing complexity limits supplier elasticity.
- Calcium Channel Blockers:Nimodipine and related compounds leverage existing pharmaceutical manufacturing platforms with moderate capital barriers.
- Omega-3 Fatty Acids:EPA and DHA formulations source from marine extraction or algal fermentation with established nutraceutical supply chains.
Most installed capacity flows through Antioxidants. Expansion is steepest in Neurotrophic Factors.
Application:
Development timelines and reimbursement pathways diverge sharply between acute cerebrovascular events and chronic neurodegenerative conditions.
- Stroke:Acute ischemic and hemorrhagic events drive immediate neuroprotective intervention with narrow therapeutic windows. FDA breakthrough designations and hospital protocol standardization in the United States compress adoption curves, though functional outcome requirements from CMS extend market access negotiations.
- Alzheimer's Disease:Disease-modifying neuroprotection targets amyloid and tau pathologies with multi-year treatment horizons. Biomarker qualification progress at EMA and FDA enables surrogate endpoint strategies, but Phase III attrition rates deter early-stage capital deployment.
- Parkinson's Disease:Dopaminergic neuroprotection trials concentrate at academic medical centers in Boston and Heidelberg with specialized investigator pools.
- Traumatic Brain Injury:Military and civilian trauma protocols in Germany and Japan drive concentrated demand for acute neuroprotective regimens.
Stroke applications command the largest prescription volume. Alzheimer's Disease presents the longest revenue duration as disease-modifying trials mature.
End User:
Purchasing authority and formulary control vary across institutional settings, reshaping sales force deployment and contract structures.
- Hospitals:Level I trauma centers and comprehensive stroke centers in the United States and Germany consolidate neuroprotective procurement into bundled protocol contracts with outcome guarantees. Pharmacy and therapeutics committees exercise centralized purchasing authority, displacing individual physician prescribing autonomy.
- Rehabilitation Centers:Post-acute facilities in the United States represent underpenetrated channels for oral neuroprotective maintenance therapy. Medicare reimbursement pathways for skilled nursing facilities create distinct access economics from acute care settings.
- Research Institutes:Academic medical centers in Tokyo, Boston, and Heidelberg concentrate investigator-initiated trials and biomarker validation studies.
- Pharmaceutical Companies:Sponsor organizations source neuroprotective candidates through licensing and acquisition for pipeline expansion.
Hospital procurement committees control the largest share of neuroprotective spending. Rehabilitation centers are gaining share fastest as post-acute protocols standardize.
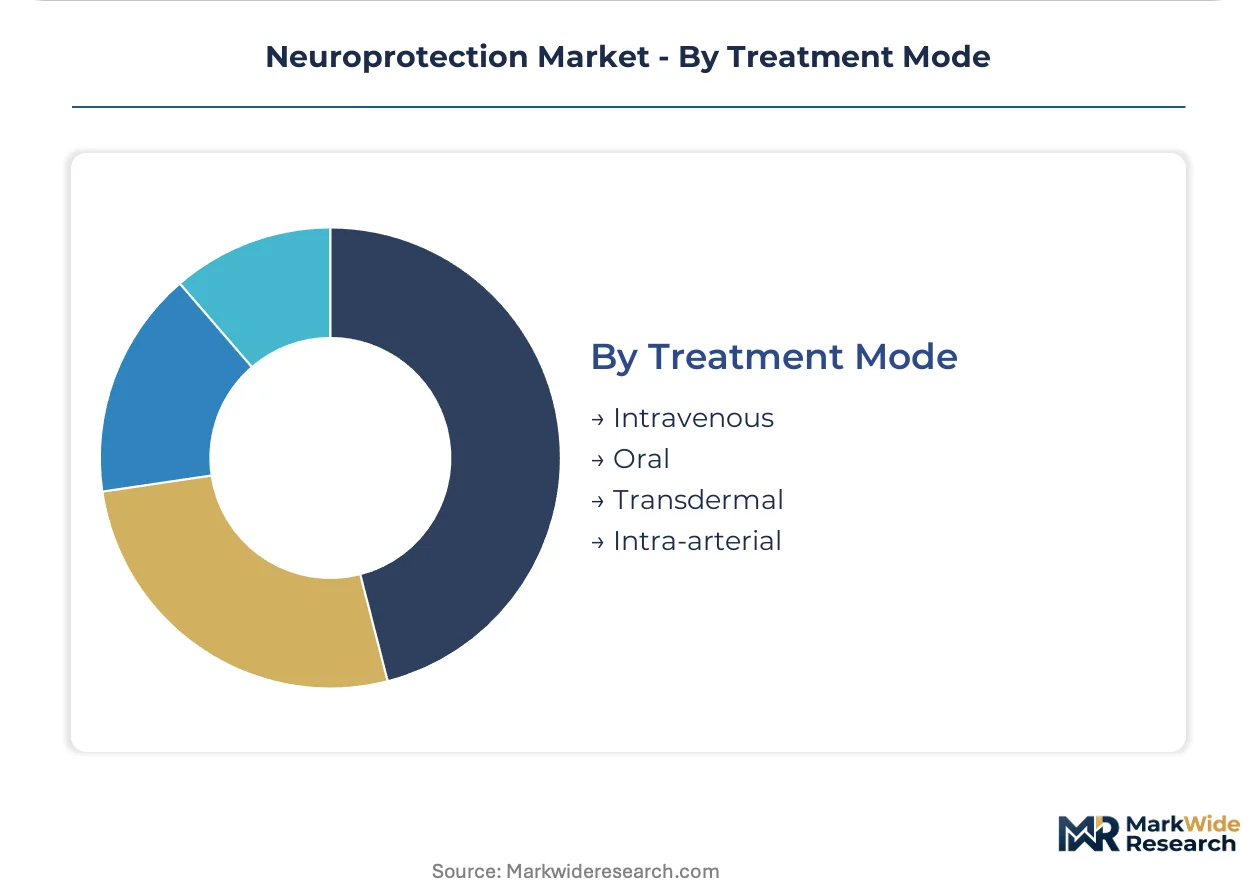
Treatment Mode:
Delivery technology requirements and patient compliance profiles determine competitive positioning across administration routes.
- Intravenous:Acute stroke and traumatic brain injury protocols in hospital emergency departments require immediate vascular access and infusion capability. EMA and FDA regulatory pathways for IV neuroprotectives emphasize pharmacokinetic bridging studies to establish therapeutic windows.
- Oral:Chronic neurodegenerative maintenance therapy in Alzheimer's and Parkinson's Disease prioritizes patient adherence and ambulatory administration. Formulation stability and bioavailability optimization command development investment from sponsors targeting rehabilitation channel expansion.
- Transdermal:Patch and gel formulations for neurotrophic factor delivery remain investigational with limited commercial penetration.
- Intra-arterial:Endovascular delivery during mechanical thrombectomy procedures concentrates at specialized stroke centers in Japan and Germany.
Intravenous administration dominates acute care volume. Oral formulations are expanding most quickly into post-acute and chronic maintenance settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuroprotection research originated in academic medical centers across the United States and Germany during the 1980s, with Japan subsequently scaling commercial manufacturing of neurotrophic factors. Today's demand geography reflects this legacy, with specialized neurology infrastructure concentrated in aging societies with robust hospital procurement systems.
United States
Level I trauma centers and comprehensive stroke centers drive neuroprotective protocol standardization, with bundled payment models from CMS accelerating formulary consolidation. FDA breakthrough therapy designations compress Phase II-to-approval timelines for Parkinson's and ALS candidates. Boston's academic medical cluster anchors investigator-initiated trials and biomarker validation studies.
Germany
G-BA reimbursement assessments demand functional outcome measures beyond mortality reduction, extending market access negotiations for acute stroke therapies. EU MDR standards govern post-market surveillance and clinical evidence requirements. Heidelberg's neurology research concentration specializes in dopaminergic neuroprotection trials with dedicated investigator pools.
Japan
Aging demographics and concentrated stroke incidence create sustained demand for acute neuroprotective intervention. PMDA regulatory pathways emphasize pharmacokinetic bridging studies for IV formulations in emergency departments. Tokyo's metropolitan hospital chains pilot point-of-care biomarker platforms to compress treatment initiation windows.
Switzerland
Orphan indication pricing frameworks support premium positioning for neurotrophic factor therapies with manufacturing complexity barriers. Swissmedic standards align with EMA pathways while offering specialized consultation for rare neurological disease indications. Basel's pharmaceutical cluster anchors neuroscience pipeline development and European commercialization strategy.
Neuroprotection Market Competitive Environment
Premium-margin players sit above commodity-margin players across manufacturing complexity and indication rarity, with biologic neurotrophic factors commanding 24-36 month capacity lead times against 12-18 month small-molecule cycles. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with neuroscience depth, specialized biologics manufacturers with mammalian cell culture captive supply, and generic-access players competing on rehabilitation channel penetration. Dominant competitive moves include strategic licensing of neurotrophic factor production platforms and backward integration into GMP-compliant mammalian expression systems.
Within the integrated pharmaceutical tier, Novartis AG and Roche Holding AG occupy positions anchored by neuroscience pipeline breadth and European hospital adoption networks. Biogen Inc. exemplifies the specialized biologics archetype through amyloid-targeting platform extension. Teva Pharmaceutical Industries Ltd. represents generic-access competition across rehabilitation center channels in multiple geographies.
| Leading Market Players |
|---|
| Novartis AG |
| Roche Holding AG |
| Biogen Inc. |
| Pfizer Inc. |
| AstraZeneca PLC |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Mammalian cell culture transitions for neurotrophic factor production simultaneously elevate unit economics and concentrate supplier power among GMP-certified biologics manufacturers in Switzerland and Japan. This technology shift compresses margin elasticity for orphan indication therapies while amplifying pricing leverage for producers with captive cold-chain distribution networks.
Pricing Analysis
Three-tier pricing structure across premium neurotrophic factors, standard antioxidants, and economy generic calcium channel blockers dominates procurement negotiations. Price differentiation hinges on manufacturing complexity and FDA breakthrough therapy designation status, with designated biologics commanding substantial premiums over undifferentiated small molecules. Cost compression in the antioxidant tier intensifies as bundled stroke protocol contracts displace standalone purchasing. Hospital pharmacy committees exhibit highest price sensitivity for maintenance oral formulations, while academic medical centers show lowest sensitivity for investigational IV neuroprotectives with biomarker-validated endpoints.
Supply Chain Analysis
Freight costs for cold-chain neurotrophic factor distribution consume disproportionate working capital versus ambient small-molecule logistics. Manufacturing concentrates in Switzerland, Japan, and Germany where GMP mammalian expression capacity and specialized neurology infrastructure co-locate. Supply rests on recombinant protein precursors, pharmaceutical-grade cell culture media, and single-use bioreactor systems. Single-source vulnerability pervades the neurotrophic factor tier where 24-36 month capacity lead times limit supplier switching. Distribution runs through hospital procurement committees and integrated delivery networks rather than wholesale pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Germany's G-BA functional outcome requirements and Japan's PMDA pharmacokinetic bridging pathways, with regulatory cost differentials exceeding manufacturing labor spreads. Sponsors can optimize development economics by anchoring Phase II trials in Tokyo while pursuing reimbursement negotiations in Heidelberg.
For Market Incumbents: Deepen backward integration into GMP mammalian cell culture capacity to defend margin position against biosimilar neurotrophic factor entrants. Anchor European hospital adoption through bundled protocol contracts with outcome guarantees, while accelerating FDA breakthrough therapy designations to compress competitive entry timelines for Parkinson's Disease candidates. For New Entrants and Emerging Players: Premium-to-economy pricing gaps in post-acute oral neuroprotective maintenance create white-space entry points. Rehabilitation centers in the United States represent the most penetrable channel, with Medicare reimbursement pathways distinct from acute care formulary control. A digital biomarker-integrated trial design offers differentiation against legacy EDC-dependent incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized biologics manufacturers with mammalian cell culture captive supply but limited commercial infrastructure. Long-term viability over a 5-10 year horizon hinges on biomarker qualification progress enabling surrogate endpoint strategies. Watch CSF neurofilament light chain standard adoption at FDA and EMA as the inflection signal for Phase III capital deployment into amyotrophic lateral sclerosis platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval timelines for ALS candidates. |
| Manufacturing Scale-Up | GMP mammalian cell culture expansion in Switzerland addresses 24-36 month capacity lead times. |
| Hospital System Partnership | Integrated delivery network contracts displace standalone neuroprotective procurement in Level I trauma centers. |
| Biomarker Qualification | CSF neurofilament light chain standards enable smaller trial designs at EMA and FDA. |
| Rehabilitation Channel Expansion | Post-acute facility penetration captures underutilized prescription volume for oral maintenance regimens. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates and validate supply-side assumptions. Primary fieldwork engaged drug development executives at neuroscience-focused sponsors, regulatory affairs leads navigating FDA and EMA accelerated pathways, hospital procurement managers at Level I trauma centers, formulary directors within integrated delivery networks, and payer access specialists at CMS and Germany's G-BA. Secondary validation drew from FDA filings, EMA PRIME eligibility databases, ClinicalTrials.gov neuroprotection protocols, and hospital formulary databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing underwent iterative reconciliation.
Comparable-period anchoring linked historical neuroprotective utilization patterns to forward projection assumptions across the analysis window. Segmentation dimensions modeled encompassed product type, application, end user, treatment mode, and regional regulatory cluster. CAGRs derived from logarithmic trend fitting across annualized volume and value estimates. Forecast inputs incorporated biomarker qualification progress, bundled payment penetration rates, and manufacturing capacity expansion announcements.
Caveats apply where clinical trial failure rates in neurodegenerative indications or reimbursement threshold hardening at CMS could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory designation rates and hospital protocol standardization velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Coma Diagnosis and Treatment Market
Neurology
CNS Therapeutics Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Interventional Neurology Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Status Epilepticus Treatment Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
CNS Lymphoma Market
Neurology
Global Neuroblastoma Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Global Vertigo Treatment Market
Neurology
Spinal Laminoplasty Market
Neurology
Hydrocephalus Market
Neurology
Netherlands Neurology Devices Market