
 Italy Neurology Devices Market | 2026-2036
Italy Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Neurology Devices Market Foresight
Home care monitoring is repositioning Italy's neurology device procurement priorities as post-acute stroke rehabilitation shifts beyond hospital walls. Medtronic PLC leverages its neurostimulation portfolio to sustain channel dominance across northern Italy's specialist centers. Boston Scientific Corporation anchors its competitive stance through deep product specialization in spinal cord stimulation systems for chronic pain.
Neurology devices encompass instruments engineered for the diagnosis, monitoring, and therapeutic intervention of central and peripheral nervous system pathologies, typically operating through electrical signal modulation, targeted drug delivery, or structural intervention with precision tolerances measured in millimeters. Neurostimulators command premium margin pools due to chronic implantation cycles and recurring programming service revenue, while software-based diagnostic solutions capture fastest expansion as artificial intelligence-enhanced EEG interpretation penetrates outpatient neurology workflows across Italian regional health authorities.
Italy's Ministry of Health device registration requirements, CE marking under EU MDR transition timelines, and regional tariff negotiation frameworks collectively determine market access velocity and reimbursement ceilings for novel neurology technologies. Stakeholders must monitor how Italy's Agenzia Italiana del Farmaco adapts its health technology assessment protocols to accommodate real-world evidence from remote patient monitoring platforms.
Market Dynamics
Italy's neurology device sector is experiencing a fundamental procurement pivot as regional health authorities consolidate purchasing power and demand bundled service contracts rather than standalone hardware transactions. This concentration of buyer power is compressing traditional distribution margins while elevating vendors with integrated remote monitoring capabilities.
Growth Catalysts
- EU MDR transition timelines:The Medical Device Regulation's enhanced safety documentation requirements are accelerating hospital consolidation toward suppliers with established notified body relationships, favoring incumbents with robust quality management systems.
- Neurostimulation therapy reimbursement:Italy's National Health Service has expanded tariff coverage for deep brain stimulation and spinal cord modulation procedures, unlocking patient access in Lombardy and Emilia-Romagna regional health systems.
- AI-enhanced diagnostic platforms:Machine learning algorithms for EEG pattern recognition are penetrating outpatient neurology workflows, reducing specialist interpretation bottlenecks in northern Italy's high-volume centers.
Market Restraints
- Precious metal input volatility:Platinum-iridium electrode assemblies face price pressure from mining supply constraints, compressing neurostimulator gross margins for manufacturers without long-term hedging arrangements.
- Single-source component dependency:Ceramic feedthrough seals for implantable pulse generators concentrate among German and Swiss specialty suppliers, creating vulnerability to regional production disruptions.
- Biocompatibility certification friction:ISO 10993 testing protocols for novel polymer encapsulants extend product development timelines by 18-24 months, delaying market entry for next-generation devices.
Strategic Opportunities
- Southern Italy underpenetration:Campania, Sicily, and Calabria maintain 40% lower neurostimulator implant rates per capita than northern regions, presenting expansion potential for mobile surgical unit partnerships.
- Telemedicine reimbursement codes:Italy's Ministry of Health has introduced dedicated tariffs for remote neurophysiological monitoring, enabling new revenue streams for device-software integrated offerings.
- Closed-loop stimulation convergence:The fusion of local field potential sensing with adaptive output modulation is creating next-generation movement disorder therapy platforms with differentiated clinical positioning.
Industry Challenges
- Electrophysiology-engineering talent scarcity:Italian universities produce insufficient graduates with combined neuroscience and embedded systems expertise, forcing manufacturers to recruit from German and Dutch technical institutes.
- Legacy hospital IT integration:Proprietary data formats from existing EEG and EMG systems create interoperability barriers for cloud-based analytics platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Neurology Devices Market |
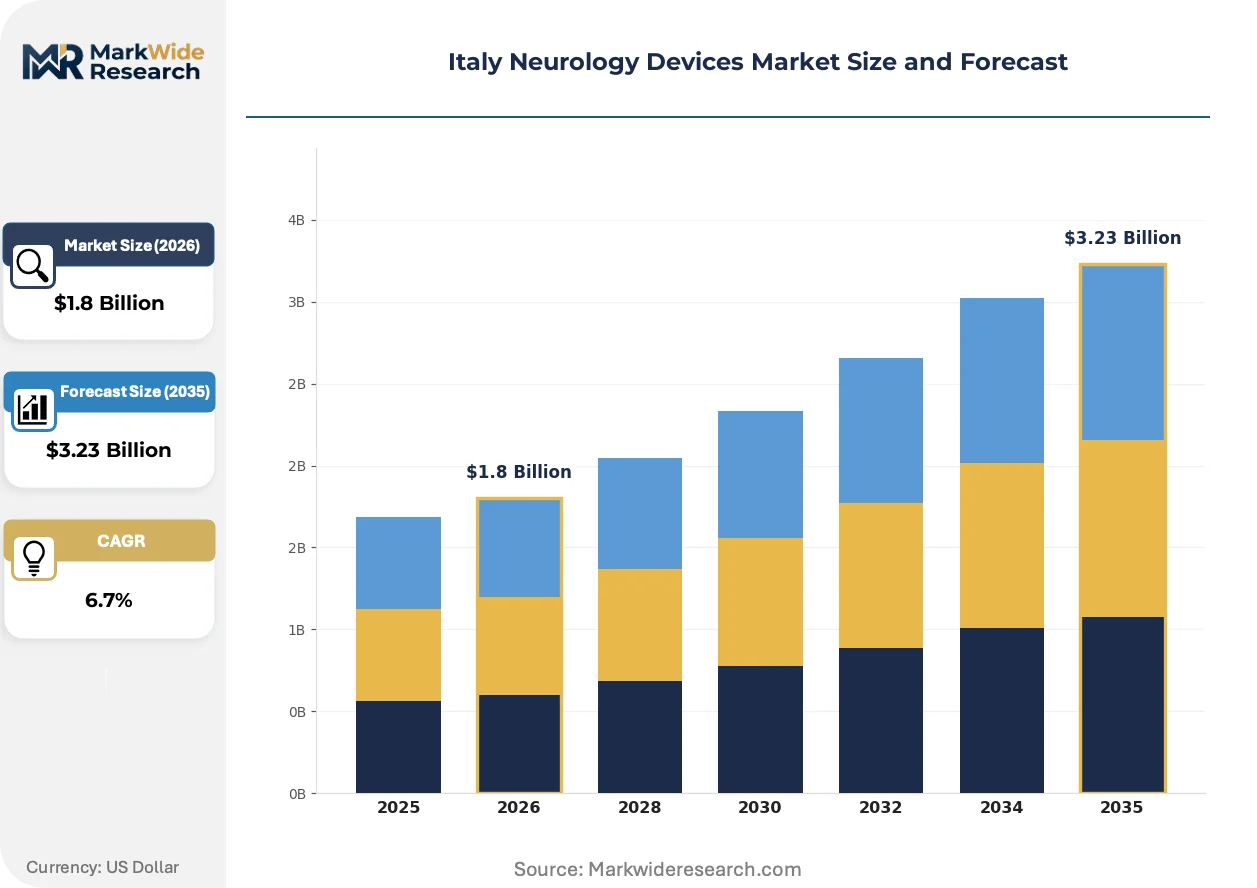
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalograms, Neurostimulators, Infusion Systems, Neuromodulation Devices End User: Hospitals, Clinics, Research Institutions, Home Care Technology: Invasive Techniques, Non-Invasive Techniques, Software-Based Solutions, Diagnostic Imaging Application: Stroke Management, Pain Management, Epilepsy Treatment, Cognitive Disorders |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic PLC, B. Braun Melsungen AG, Stryker Corporation, Johnson and Johnson, Penumbra Inc., LivaNova, MicroPort Scientific, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Neurology Devices Market Shifts & Advancements
Digital biomarker extraction and closed-loop therapeutic modulation are converging to redefine how neurological conditions are managed outside traditional hospital settings. This technological fusion is compressing the boundary between diagnostic and therapeutic device categories.
Implantable local field potential sensors are expanding into movement disorder therapy protocols by enabling real-time symptom-responsive stimulation adjustment. Functional neurosurgery departments at Milan's Istituto Neurologico Carlo Besta and Turin's Azienda Ospedaliero-Universitaria Città della Salute are piloting these adaptive systems for Parkinson's disease management. The technology is expanding into chronic pain applications as spinal cord stimulation manufacturers integrate biopotential feedback loops into next-generation pulse generators.
Italy's Agenzia Italiana del Farmaco is accelerating health technology assessment timelines for devices demonstrating real-world evidence from national disease registries. The policy shift rewards manufacturers investing in post-market clinical follow-up infrastructure with faster regional tariff negotiations. Neurostimulation systems with established Italian patient cohort data are securing preferential reimbursement positioning against newer market entrants lacking longitudinal outcomes documentation.
Regional health authorities are consolidating device procurement through centralized tendering platforms, displacing hospital-level purchasing autonomy. Lombardy's ATS Insubria and Emilia-Romagna's AUSL Bologna have shifted to multi-year framework agreements with performance-linked payment terms. This concentration is most visible in high-volume commodity categories such as disposable EEG electrodes and EMG needle sets, where price transparency platforms enable direct manufacturer-to-authority contracting.
Italy Neurology Devices Market Segmentation
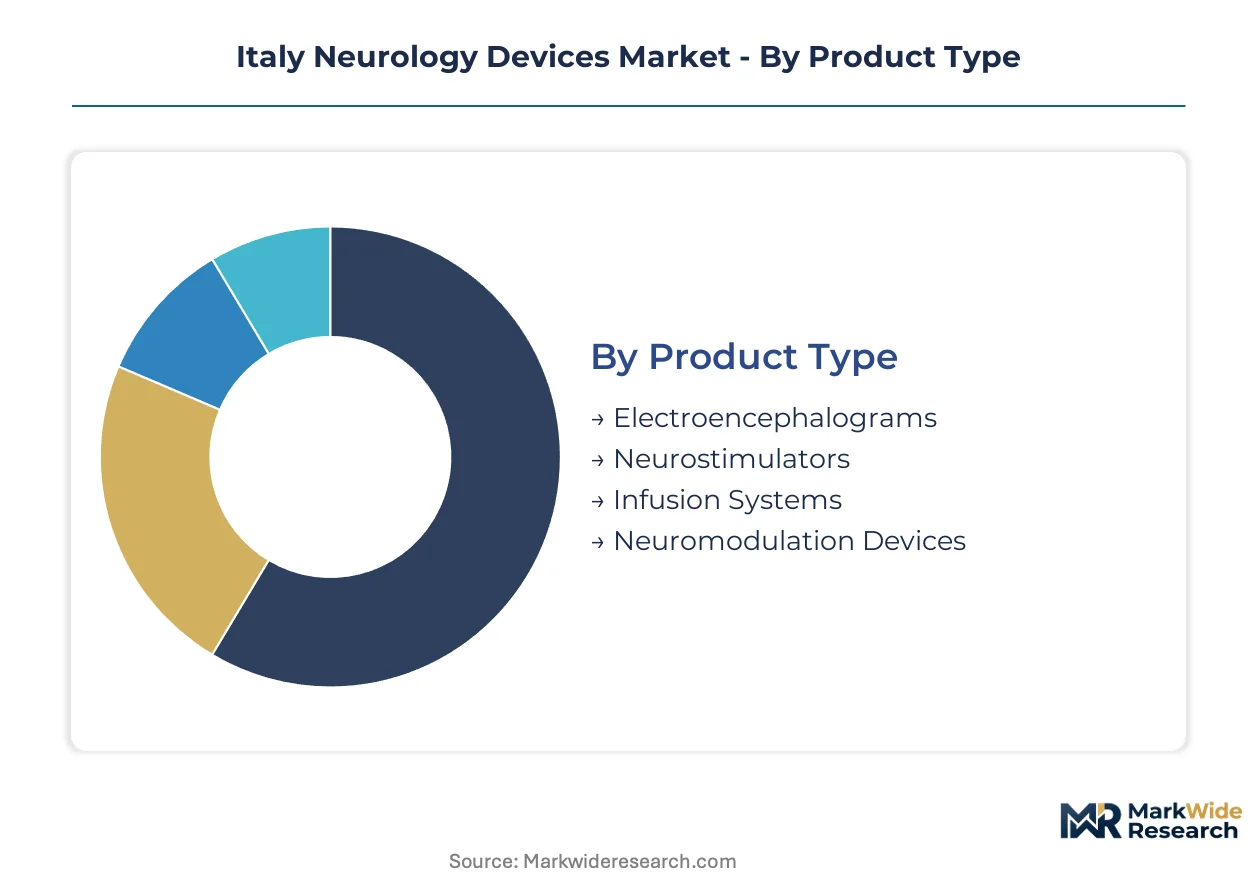
Italy's neurology device market fragments across four critical dimensions that determine capital deployment, regulatory pathway complexity, and reimbursement velocity. Product type distinctions drive manufacturing infrastructure requirements, while end-user concentration shapes distribution economics and service model design.
Product Type:
Capital intensity varies sharply across this category, with implantable systems demanding specialized cleanroom manufacturing and long-cycle clinical validation that stretches development timelines.
- Neurostimulators:Implantable pulse generators with platinum-iridium electrode assemblies and ceramic hermetic seals require Class III CE marking under EU MDR. Lombardy's specialist neurosurgical centers at Milan's Istituto Neurologico Carlo Besta anchor demand for deep brain and spinal cord stimulation systems.
- Electroencephalograms:Signal acquisition hardware ranges from 32-channel diagnostic systems to portable ambulatory units. Northern Italy's regional health authorities concentrate procurement through centralized tendering platforms, compressing margins on disposable electrode consumables.
- Infusion Systems:Programmable pumps for intrathecal drug delivery with precision dosing tolerances.
- Neuromodulation Devices:Peripheral nerve stimulation and transcranial magnetic stimulation systems with shorter regulatory pathways than implantables.
Most installed capacity flows through Neurostimulators. Expansion is steepest in Software-Based Solutions when considering adjacent technology convergence.
End User:
Procurement authority concentration determines contract structure complexity, with consolidated regional purchasing displacing hospital-level autonomy.
- Hospitals:Tertiary neurosurgical centers with integrated electrophysiology suites and intraoperative monitoring capabilities. Lombardy's ATS Insubria and Emilia-Romagna's AUSL Bologna have shifted to multi-year framework agreements with performance-linked payment terms for high-volume categories.
- Home Care:Post-acute stroke rehabilitation and chronic pain management shifting beyond hospital walls. Italy's Ministry of Health has introduced dedicated tariffs for remote neurophysiological monitoring, enabling device-software integrated offerings.
- Clinics:Outpatient neurology practices with diagnostic EEG and EMG capabilities.
- Research Institutions:Academic medical centers with investigational device exemption pathways for adaptive neurostimulation protocols.
Revenue concentration sits with Hospitals. Home Care is gaining share fastest as reimbursement codes formalize remote monitoring economics.
Technology:
Regulatory pathway length and clinical evidence requirements separate invasive from non-invasive categories, with software solutions occupying an evolving compliance position.
- Invasive Techniques:Implantable electrode arrays and pulse generators requiring surgical intervention with associated infection risk protocols.
- Non-Invasive Techniques:Transcranial magnetic stimulation and external neuromodulation with outpatient administration models.
- Software-Based Solutions:Machine learning algorithms for EEG pattern recognition and adaptive stimulation programming. AI-enhanced diagnostic platforms are penetrating outpatient neurology workflows across Italian regional health authorities.
- Diagnostic Imaging:Functional MRI and PET integration with neurophysiological data for surgical planning.
Margin profiles peak with Invasive Techniques. Software-Based Solutions are climbing the fastest as artificial intelligence penetrates reimbursement frameworks.
Application:
Prevalence epidemiology and reimbursement tariff generosity create divergent addressable market economics across neurological indications.
- Pain Management:Chronic neuropathic and nociceptive conditions treated through spinal cord stimulation and intrathecal drug delivery. Italy's National Health Service has expanded tariff coverage for spinal cord modulation procedures in Lombardy and Emilia-Romagna regional health systems.
- Stroke Management:Acute intervention and post-acute rehabilitation with neurostimulation-assisted motor recovery protocols.
- Epilepsy Treatment:Responsive neurostimulation and vagus nerve stimulation for drug-resistant seizure disorders.
- Cognitive Disorders:Alzheimer's disease and dementia with emerging neuromodulation approaches in early clinical evaluation.
Procedure volume concentrates in Pain Management. Steepest expansion trajectory belongs to Stroke Management as mobile surgical units target southern Italy underpenetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR compliance cost disparities are driving contract manufacturing migration from high-labor-cost northern European states toward specialized production zones in southern and eastern member states. This regulatory-arbitrage dynamic concentrates neurology device assembly in jurisdictions with streamlined notified body access and lower quality system audit overhead.
Lombardy
Milan's Istituto Neurologico Carlo Besta and the biomedical manufacturing corridor between Milan and Bergamo anchor neurostimulator demand and production capacity. Italy's Agenzia Italiana del Farmaco maintains its headquarters here, accelerating health technology assessment timelines for devices with established real-world evidence. The ATS Insubria regional health authority has shifted to multi-year framework agreements with performance-linked payment terms for high-volume neurology categories.
Piedmont
Turin's Azienda Ospedaliero-Universitaria Città della Salute pilots adaptive closed-loop neurostimulation systems for Parkinson's disease management. The concentration of precision engineering heritage from Fiat's automotive supplier ecosystem feeds into ceramic feedthrough and hermetic sealing component production. CE marking under EU MDR transition timelines moves faster here due to established relationships with Milan-based notified bodies.
Emilia-Romagna
Bologna's AUSL Bologna consolidates procurement authority for disposable EEG electrodes and EMG consumables through centralized tendering platforms. The region maintains Italy's highest per-capita neurostimulator implant rates, supported by expanded National Health Service tariff coverage for spinal cord modulation procedures. Medical device startups cluster around the University of Bologna's biomedical engineering programs.
Veneto
Verona and Padua host outpatient neurology practices penetrating AI-enhanced EEG diagnostic platforms. Regional health authorities here have introduced dedicated telemedicine reimbursement codes for remote neurophysiological monitoring. The Veneto medical device supply chain specializes in polymer encapsulant biocompatibility testing under ISO 10993 protocols.
Lazio
Rome's Ministry of Health device registration requirements and national tariff negotiation frameworks determine market access velocity for novel neurology technologies. The region underperforms northern Italy in neurostimulator implant density but hosts the central administrative capacity for national reimbursement policy. Post-acute stroke rehabilitation infrastructure here is expanding home care monitoring capabilities.
Italy Neurology Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers integrate software-based diagnostic platforms with traditional hardware offerings. The vendor base organizes around three tiers: diversified multinationals with full neurostimulation portfolios, mid-cap specialists in single-modality systems, and emerging software-centric entrants. Strategic archetypes include integrated device-software providers, component-focused precision manufacturers, and regional service contractors. M&A activity and technology licensing agreements constitute the primary competitive vectors as firms seek electrophysiology-engineering talent and cloud-based analytics capabilities.
Among US-based diversified multinationals, Medtronic PLC and Boston Scientific Corporation exemplify the integrated device-software archetype with established channel presence across northern Italy's specialist neurosurgical centers. Abbott Laboratories occupies a position within the same tier, leveraging its broader cardiovascular and diabetes portfolios to cross-sell neurology solutions through consolidated hospital procurement frameworks. Johnson and Johnson represents the conglomerate model with dispersed medical technology holdings spanning multiple therapeutic areas.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic PLC |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Johnson and Johnson |
| Penumbra Inc. |
| LivaNova |
| MicroPort Scientific |
| Others |
Supply & Pricing Matrix
Family-owned precision manufacturers in Germany and Switzerland anchor ceramic feedthrough and hermetic sealing supply for Italian neurostimulator producers, translating into rigid pricing discipline for Class III implantable components. Their multi-decade customer relationships with Milan-based notified bodies create switching costs that insulate premium tier pricing from commodity pressure.
Pricing Analysis
Distributor margins on disposable EEG electrodes and EMG consumables face compression as Lombardy's ATS Insubria and Emilia-Romagna's AUSL Bologna shift to direct manufacturer contracting through centralized tendering platforms. Three-tier pricing structure across premium, standard, and economy levels separates platinum-iridium electrode assemblies from ceramic feedthrough components from polymer encapsulant subsystems, with CE marking tier and volume scale as the primary differentiation drivers. Cost compression in standard-tier consumables is intensifying because regional health authorities now publish price transparency data enabling cross-authority benchmarking. Academic medical centers with investigational device exemption pathways exhibit lowest price sensitivity, while outpatient neurology clinics in Veneto face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss specialty suppliers of ceramic hermetic seals for implantable pulse generators, creating exposure to regional production disruptions. Manufacturing concentration clusters in Germany, Switzerland, and northern Italy itself, with platinum-iridium electrode assemblies drawing from South African mining supply and ceramic feedthroughs resting on precision engineering heritage from automotive supplier ecosystems. Tariff exposure on precious metal inputs represents the dominant structural risk, compressing neurostimulator gross margins for manufacturers without long-term hedging arrangements. Distribution runs through specialized medical device distributors with notified body relationships, though regional health authority consolidation is displacing traditional channel intermediaries in high-volume categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's neurology device market functions as a stable compounder anchored by chronic implantation cycles and recurring programming service revenue from neurostimulation systems. The National Health Service's expanding tariff coverage for deep brain and spinal cord modulation procedures sustains predictable demand visibility.
For Market Incumbents: To counter software-centric diagnostic entrants penetrating outpatient neurology workflows, deepen backward integration into AI-enhanced EEG interpretation platforms and secure exclusive hospital system partnerships with performance-linked service contracts. Prioritize certification investment for closed-loop adaptive stimulation systems to maintain premium positioning against mid-cap specialists.
For New Entrants and Emerging Players: Capture southern Italy's underpenetrated neurostimulator markets in Campania, Sicily, and Calabria through mobile surgical unit partnerships with regional health authorities lacking specialist neurosurgical infrastructure. Target telemedicine reimbursement codes for remote neurophysiological monitoring as the most penetrable entry vector, leveraging device-software integration to bypass capital-intensive cleanroom manufacturing requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap single-modality specialists lacking post-market clinical follow-up infrastructure and real-world evidence registries. The five-to-ten-year viability window favors acquisition of electrophysiology-engineering talent pools and cloud-based analytics capabilities. Watch AIFA health technology assessment protocol adaptations for remote patient monitoring platforms as the signal for reimbursement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR transition timelines favor incumbents with established notified body relationships in Milan. |
| Hospital System Partnership | Multi-year framework agreements with ATS Insubria secure volume commitments for high-volume consumables. |
| Software Companion Development | AI-enhanced EEG platforms penetrate outpatient workflows across Veneto's regional health authorities. |
| Reimbursement Strategy | AIFA's accelerated HTA timelines reward manufacturers with Italian patient cohort longitudinal data. |
| Backward Integration | In-house production of ceramic feedthrough seals mitigates single-source dependency on German suppliers. |
Research Methodology
Coverage spans northern Italy's specialist neurosurgical corridor, central administrative regions, and southern underpenetrated markets, with primary inputs from each. The analysis combines structured interviews with hospital purchasing committee members, biomedical engineers at tertiary centers, GPO contracts managers, and regulatory affairs specialists at AIFA with secondary validation from EU MDR filing databases, regional health authority tendering platform disclosures, and National Health Service tariff documentation. Bottom-up demand modeling across product categories triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models neurostimulator, electroencephalogram, infusion system, and neuromodulation device categories by invasive versus non-invasive technology tier, hospital versus home care end-use, and pain management versus stroke management versus epilepsy treatment application. CAGRs derive from procedure volume trajectories, reimbursement tariff evolution, and technology substitution elasticities, with AI-enhanced diagnostic penetration and closed-loop stimulation convergence as industry-specific forecast inputs.
EU MDR compliance timeline delays, precious metal input volatility, and regional health authority procurement consolidation are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding AIFA health technology assessment protocol stability and National Health Service reimbursement generosity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neuroendocrine Carcinoma Market
Neurology
China Neurology Devices Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
United States Neurology Devices Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
UAE Neurology Devices Market
Neurology
Interventional Neurology Market
Neurology
Chile Neurology Devices Market
Neurology
Cognitive Neuroscience Market
Neurology
Brazil Neurology Devices Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Moyamoya Disease Market
Neurology
Spasticity Treatment Market
Neurology
Acute Repetitive Seizures Market