
 Traumatic Brain Injuries Assessment Market | 2026-2036
Traumatic Brain Injuries Assessment Market Size, Share, and Industry Trends Forecast 2026-2036
Traumatic Brain Injuries Assessment Market Outlook
Hospital emergency departments are bifurcating from rehabilitation centers as the dominant procurement channel for TBI assessment platforms. Philips leverages its installed imaging base to anchor CT and MRI workflows in acute settings. Siemens Healthineers differentiates through advanced MRI sequences optimized for diffuse axonal injury detection. BrainScope competes with handheld EEG-based devices that enable point-of-care triage without radiology department bottlenecks.
Traumatic brain injuries assessment encompasses standardized clinical protocols, neuroimaging modalities, neurophysiological monitoring, and blood-based biomarker quantification used to detect structural damage, functional impairment, and metabolic disruption following cranial trauma. CT scanning remains the frontline modality for intracranial hemorrhage exclusion within the technology dimension, while MRI protocols capture growing share for subtle parenchymal injury characterization. Among end users, hospitals sustain the largest equipment footprint, though diagnostic labs are expanding biomarker analysis capacity as validated blood tests enter clinical workflows.
The FDA breakthrough device program and the EU MDR framework collectively shape product development timelines and commercial access for novel TBI diagnostics in the United States and Europe. In the United States, the Centers for Medicare & Medicaid Services reimbursement determinations for concussion-specific CPT codes directly influence hospital capital allocation toward advanced assessment platforms. Stakeholders must monitor evolving biomarker validation standards and parallel regulatory pathways across multiple jurisdictions to anticipate competitive positioning shifts.
Market Dynamics
The FDA breakthrough device designation pathway is compressing commercialization timelines for novel TBI diagnostics, creating competitive pressure on traditional imaging workflows while blood-based biomarker platforms capture emergency department triage decisions.
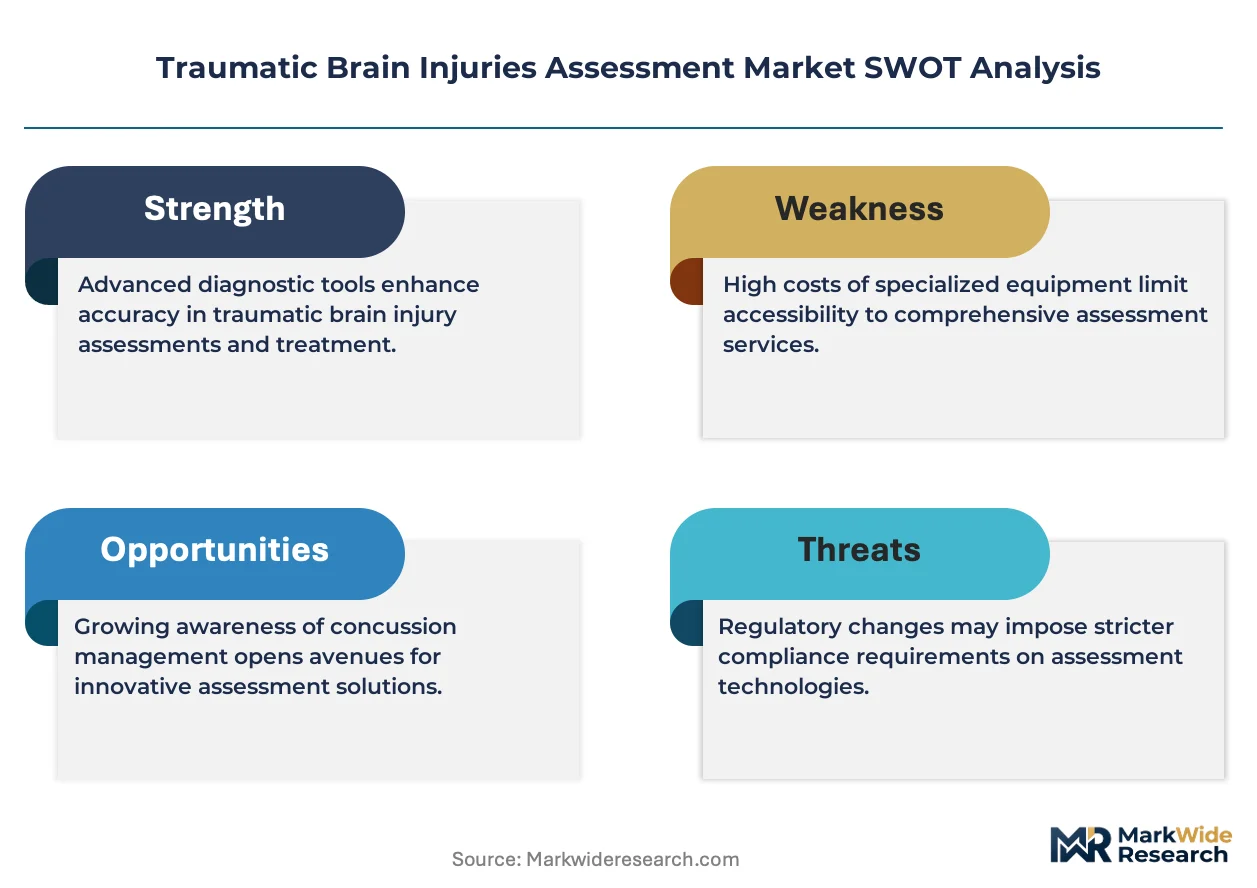
Growth Catalysts
- EU MDR framework:Accelerated CE marking timelines for TBI assessment devices enable faster European market entry and standardized clinical adoption across trauma networks in Germany, France, and Italy.
- Collegiate athletic departments:Mandatory baseline concussion testing protocols drive recurring demand for neurocognitive assessment platforms and portable diagnostic tools across NCAA Division I programs.
- Diffuse axonal injury detection:Advanced MRI sequence development enables characterization of subtle parenchymal injuries previously invisible to conventional CT scanning, expanding addressable patient populations.
Market Restraints
- Reimbursement fragmentation:CMS determinations for concussion-specific CPT codes vary by Medicare Administrative Contractor, creating capital allocation uncertainty for hospital procurement committees.
- Radiology department bottlenecks:CT scanner availability constraints in Level III trauma centers limit throughput for TBI exclusion protocols during mass casualty events.
- Biomarker validation gaps:Lack of harmonized reference ranges for blood-based TBI markers across clinical laboratories complicates multi-site trial design and regulatory submissions.
Strategic Opportunities
- Point-of-care triage:Handheld EEG-based devices enable emergency department throughput expansion without radiology infrastructure investment, particularly in rural and community hospital settings.
- German national concussion registry:Standardized data collection mandates create procurement pull for interoperable assessment platforms across the country's trauma network infrastructure.
- Blood test workflow integration:Diagnostic laboratories expanding biomarker analysis capacity can capture recurring revenue streams as validated TBI panels enter clinical guidelines.
Industry Challenges
- Neuroimaging specialist shortages:Neuroradiologist workforce gaps in secondary markets delay MRI interpretation for subtle TBI cases, compressing diagnostic confidence windows.
- Legacy PACS integration:Novel assessment platforms face technical friction connecting to hospital imaging archives, extending implementation timelines and IT resource demands.
- Multi-jurisdictional regulatory navigation:Parallel FDA breakthrough and EU MDR pathways require divergent clinical evidence packages, duplicating development costs for emerging diagnostic developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traumatic Brain Injuries Assessment Market |
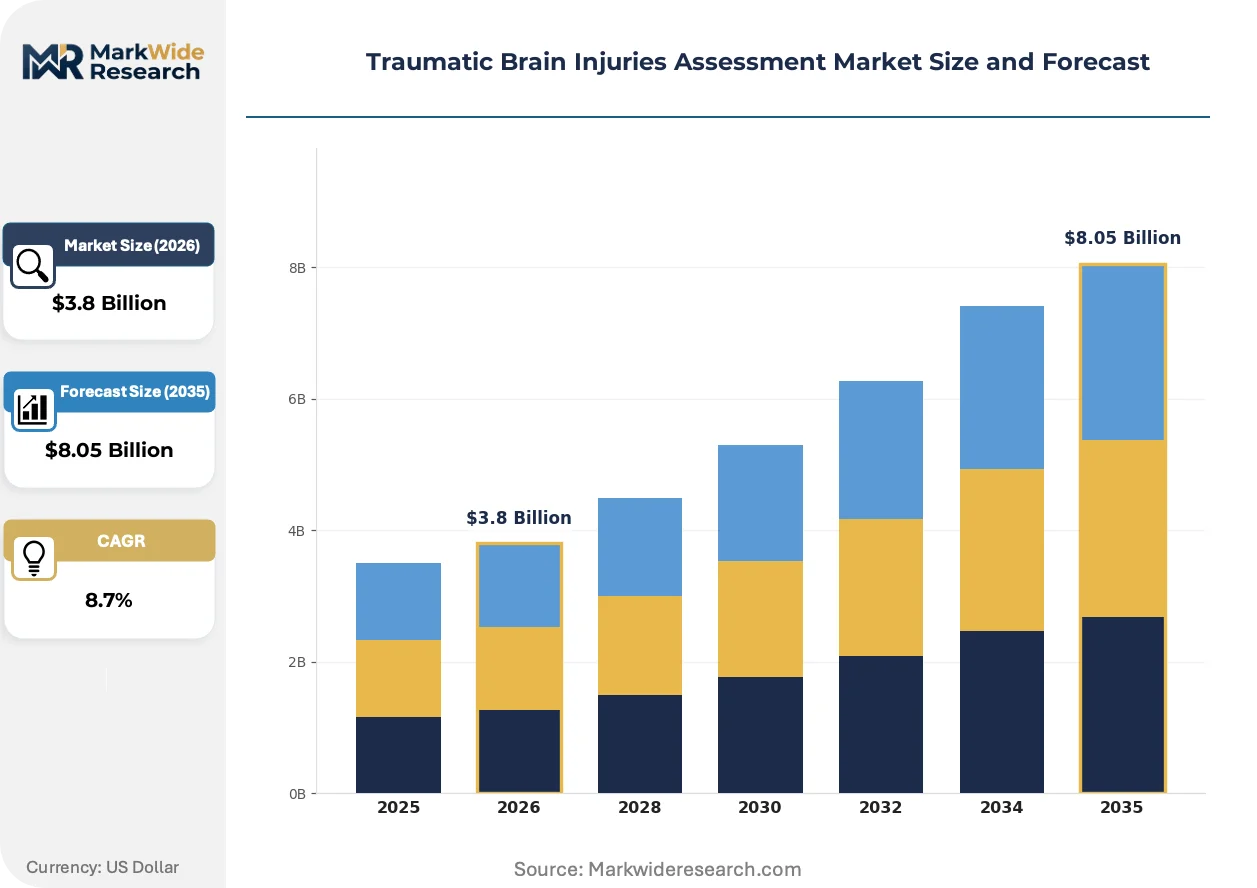
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Assessment Type: Neuropsychological Testing, Imaging Techniques, Clinical Evaluations, Biomarker Analysis Technology: CT Scan, MRI, EEG, TBI Protocols End User: Hospitals, Rehabilitation Centers, Research Institutions, Diagnostic Labs Application: Acute Management, Prognostic Assessment, Long-term Monitoring, Treatment Response Evaluation |
| Companies Covered | Philips, GE Healthcare, Siemens Healthineers, Raumedic AG, Nihon Kohden Corp., Integra LifeSciences, Natus Medical, BrainScope, InfraScan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traumatic Brain Injuries Assessment Market Strategic Shifts
Handheld neurophysiological monitoring is compressing the diagnostic chain from emergency department arrival to clinical decision, while regulatory pathways accelerate competitive entry for blood-based biomarker platforms.
Portable EEG-based triage devices deliver rapid structural brain injury assessment without radiation exposure or radiology department queues. Emergency medicine physicians in high-volume trauma centers adopt these tools for immediate severity stratification. Point-of-care neurophysiology is supplanting CT-first protocols for low-risk concussion presentations, reducing healthcare system imaging costs and patient throughput times.
The FDA breakthrough device program grants priority review and enhanced agency engagement for novel TBI diagnostics demonstrating substantial improvement over standard of care. Manufacturers gain accelerated market access and favorable reimbursement positioning through this pathway. Blood-based biomarker developers leverage this regulatory tailwind to compress traditional 510(k) timelines and secure hospital formulary placement ahead of competitors.
Hospital procurement committees now unbundle assessment platform decisions from radiology capital budgets, creating separate funding streams for point-of-care diagnostics. Emergency department directors gain direct purchasing authority for triage-enabling technologies previously controlled by imaging service lines. This organizational shift concentrates buying power with clinical department heads in United States health systems and drives faster adoption cycles for non-imaging TBI tools.
Traumatic Brain Injuries Assessment Market Segmentation
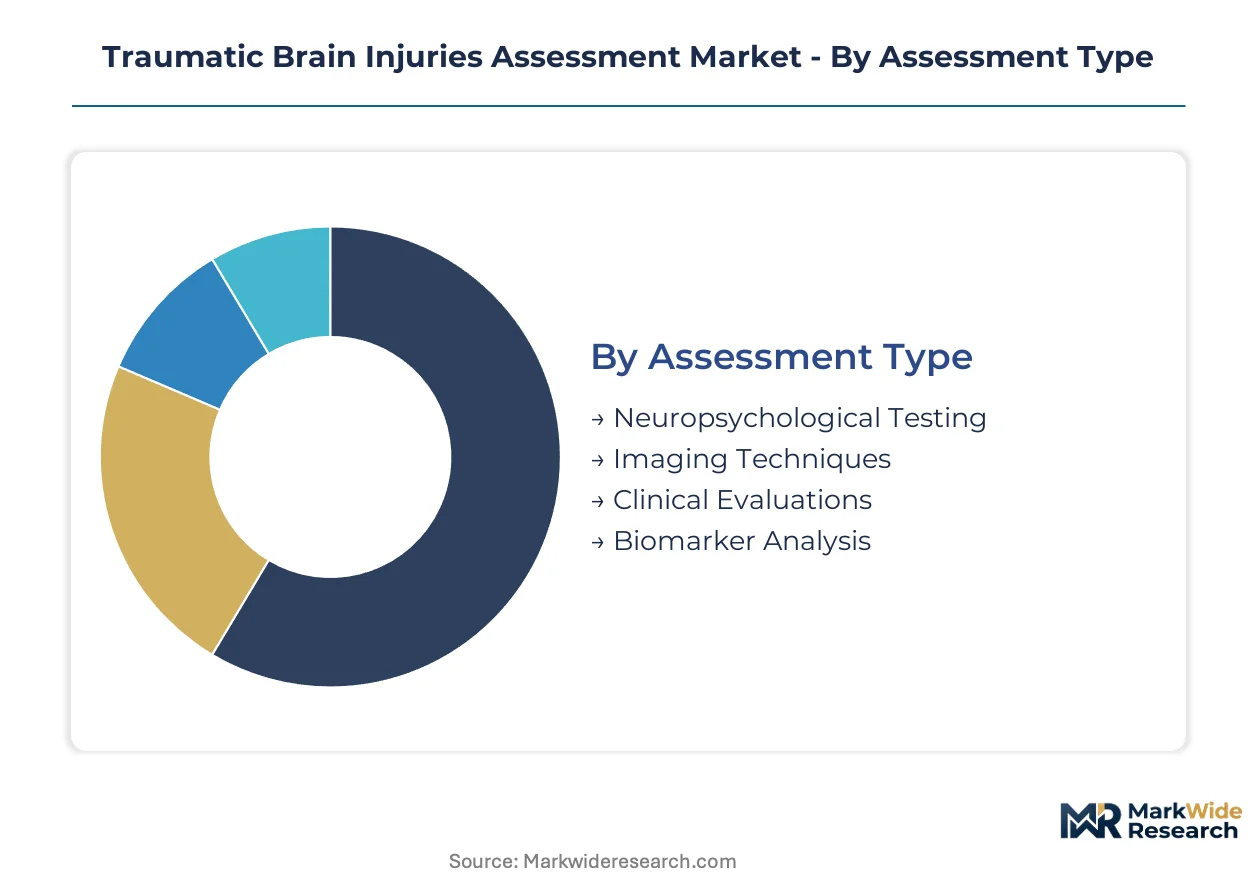
Segmentation reveals how procurement authority fragments across clinical settings and how technology choices cascade from emergency triage protocols through longitudinal patient management. Understanding these divides exposes where capital budgets concentrate and where workflow integration creates competitive moats.
Assessment Type:
Margin pools concentrate in modalities that compress time-to-decision for high-acuity presentations.
- Imaging Techniques:CT and MRI modalities deliver structural visualization for hemorrhage exclusion and parenchymal characterization. Emergency departments in Level I trauma centers allocate the largest capital budgets here, driven by CMS reimbursement structures for concussion-specific CPT codes.
- Biomarker Analysis:Blood-based quantification of glial fibrillary acidic protein and ubiquitin C-terminal hydrolase L1 enables rapid triage without radiology infrastructure. Diagnostic labs in Germany's national concussion registry network are expanding analytical capacity fastest.
- Neuropsychological Testing:Standardized cognitive batteries assess attention, memory, and executive function post-injury.
- Clinical Evaluations:Physical examination protocols and symptom inventories remain the frontline screening layer.
Imaging Techniques holds installed capacity. Biomarker Analysis is rotating up the share rankings.
Technology:
Cost tiering separates premium diagnostic depth from throughput-optimized screening layers.
- CT Scan:Non-contrast head CT remains the emergency department standard for intracranial hemorrhage exclusion within the first hour of presentation. Rural hospitals in the United States prioritize 64-slice systems for TBI protocols amid neuroradiologist workforce gaps.
- EEG:Quantitative electroencephalography and handheld devices enable point-of-care structural injury detection without radiation exposure. Community hospital emergency departments adopt these tools to bypass radiology department bottlenecks during mass casualty surges.
- MRI:Advanced sequences including susceptibility-weighted imaging and diffusion tensor imaging characterize diffuse axonal injury.
- TBI Protocols:Standardized imaging and monitoring algorithms integrate multiple modalities into cohesive clinical pathways.
CT Scan holds installed capacity. EEG is rotating up the share rankings.
End User:
Customer type determines whether procurement flows through radiology service lines or clinical department budgets.
- Hospitals:Acute care facilities sustain the dominant equipment footprint across imaging and monitoring platforms. Emergency department directors in United States health systems now control separate capital streams for triage-enabling technologies.
- Diagnostic Labs:Specialized facilities expand biomarker analysis capacity as validated blood panels enter clinical guidelines. German trauma networks mandate interoperable platforms feeding the national concussion registry.
- Rehabilitation Centers:Post-acute facilities concentrate on functional recovery monitoring and long-term outcome tracking.
- Research Institutions:Academic medical centers drive protocol development and biomarker validation studies.
Hospitals hold installed capacity. Diagnostic Labs is rotating up the share rankings.
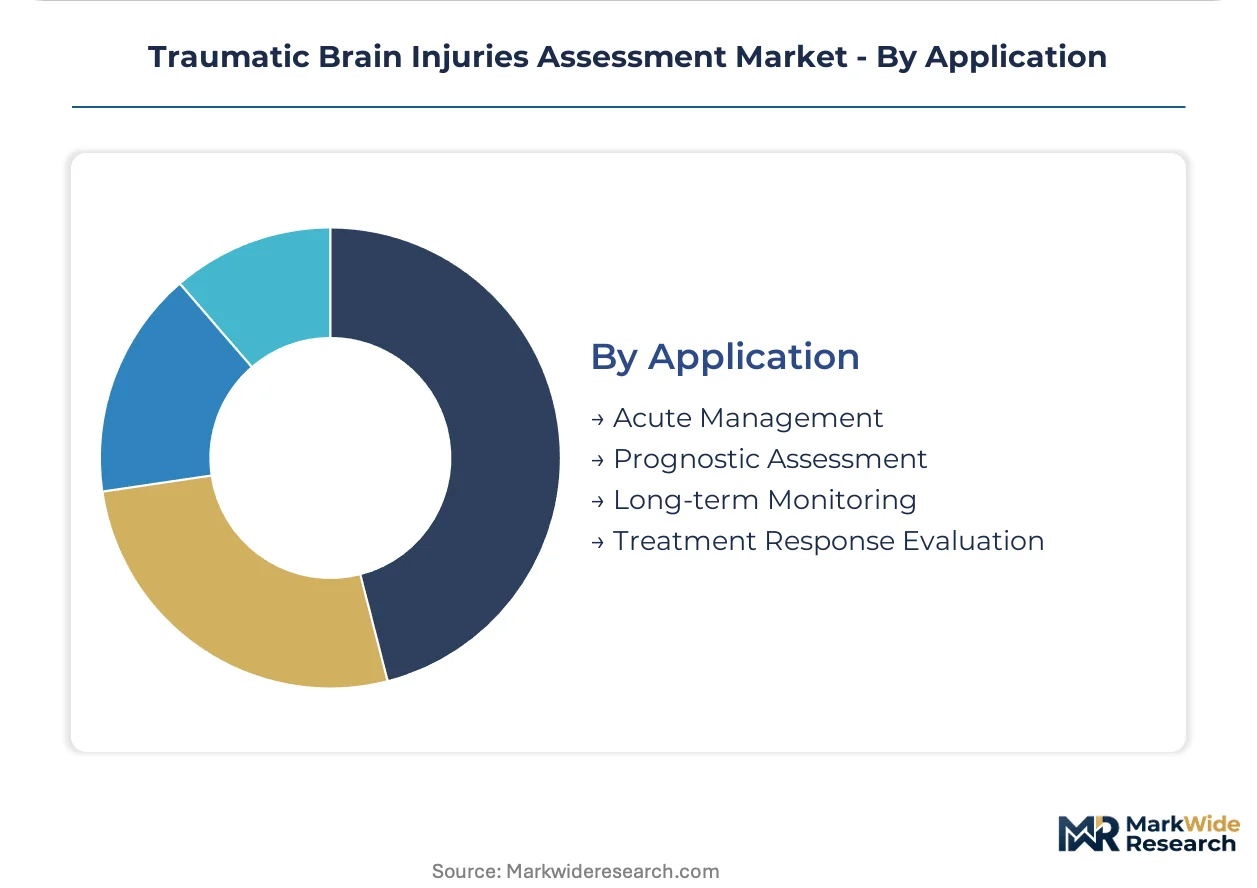
Application:
Application arc spans from immediate life-threatening event management through years of functional monitoring.
- Acute Management:Immediate triage, hemorrhage exclusion, and severity stratification dominate emergency department workflows. FDA breakthrough device designation accelerates clearance for novel diagnostics targeting this high-decision-density window.
- Long-term Monitoring:Repeated assessment of cognitive trajectory and functional recovery extends across months to years. Collegiate athletic departments in NCAA Division I programs drive recurring demand for baseline comparison protocols.
- Prognostic Assessment:Early prediction of functional outcomes guides resource allocation and family counseling.
- Treatment Response Evaluation:Serial measurement tracks intervention efficacy across rehabilitation phases.
Acute Management holds installed capacity. Long-term Monitoring is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan control the largest capital allocations for TBI assessment platforms. Academic medical centers in these markets anchor biomarker validation studies and drive protocol standardization across trauma networks.
United States
Emergency departments at Level I trauma centers in Baltimore and Houston deploy the highest CT scanner densities for hemorrhage exclusion protocols. FDA breakthrough device designation accelerates clearance timelines for novel diagnostics targeting acute triage windows. The Johns Hopkins trauma network in Maryland anchors multi-site biomarker validation trials for blood-based TBI panels.
Germany
The national concussion registry mandates standardized data collection across trauma networks, creating procurement pull for interoperable assessment platforms. EU MDR framework compresses CE marking timelines for novel TBI diagnostics entering European markets. The Munich-Berlin corridor concentrates neuroradiology specialist training programs that feed workforce pipelines for diffuse axonal injury detection.
Japan
PMDA regulatory pathways prioritize clinical evidence packages demonstrating substantial improvement over CT-first protocols for concussion presentations. METI funding programs accelerate domestic development of portable neurophysiological monitoring devices. The Tokyo-Osaka medical device cluster hosts validation trials for handheld EEG-based triage tools targeting emergency department throughput expansion.
United Kingdom
NHS England procurement frameworks unbundle assessment platform decisions from radiology capital budgets, concentrating buying power with emergency department directors. NICE technology appraisals determine reimbursement eligibility for blood-based biomarker panels entering clinical guidelines. The Oxford-Cambridge-London triangle anchors academic medical centers driving MRI sequence development for subtle parenchymal injury characterization.
Australia
TGA regulatory assessments align with FDA breakthrough pathways for TBI diagnostics, enabling parallel submission strategies for emerging developers. State-level trauma registry mandates in New South Wales and Victoria drive standardized assessment adoption across regional hospital networks. The Melbourne biomedical precinct concentrates neuroimaging research institutions validating quantitative EEG protocols for point-of-care structural injury detection.
Traumatic Brain Injuries Assessment Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with installed imaging bases, mid-cap neurodiagnostic specialists, and emerging point-of-care device developers. Imaging incumbents leverage CT and MRI workflow integration to defend emergency department capital allocations. Portable diagnostic developers compress triage timelines without radiology infrastructure investment. Strategic moves concentrate on M&A for biomarker platform capabilities and strategic partnerships for trauma network procurement contracts.
Within the imaging systems tier, Philips and Siemens Healthineers exemplify diversified conglomerates anchoring acute care capital budgets through CT and MRI modality portfolios. BrainScope occupies a position among emerging developers targeting point-of-care triage decisions with handheld neurophysiological devices that bypass radiology department bottlenecks. These three companies represent the structural divide between installed-base incumbents and workflow-disrupting entrants reshaping emergency department procurement authority.
| Leading Market Players |
|---|
| Philips |
| GE Healthcare |
| Siemens Healthineers |
| Raumedic AG |
| Nihon Kohden Corp. |
| Integra LifeSciences |
| Natus Medical |
| BrainScope |
| InfraScan |
| Others |
Value Chain & Pricing Dynamics
Installed CT and MRI base utilization rates above 85% in Level I trauma centers compress per-scan cost floors while concentrating pricing power with manufacturers holding radiology workflow integration. This scale dynamic anchors premium pricing for acute-care imaging platforms while squeezing margins for point-of-care entrants lacking comparable installed-base leverage.
Pricing Analysis
Cost-plus contracts with consumer price indexation dominate equipment procurement for hospital radiology departments, particularly in United States health systems negotiating multi-year CT and MRI service agreements. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated diagnostics from 510(k) cleared devices and unvalidated research-use-only platforms. Pricing pressure stems from CMS reimbursement compression for concussion-specific CPT codes, with Medicare Administrative Contractors in high-volume states extracting steeper discounts. Community hospitals exhibit highest price sensitivity due to capital budget fragmentation, while academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Port congestion on the Rotterdam-Hamburg corridor and container availability constraints on Asia-Europe trade lanes extend lead times for MRI magnet components and CT detector arrays sourced from German and Japanese precision manufacturers. Manufacturing concentration in Germany, Japan, and the United States for high-field MRI systems and advanced CT platforms creates single-source vulnerability for superconducting wire and photon-counting detector materials. Distribution runs through regional medical device distributors holding GPO contracts with hospital procurement alliances, with direct manufacturer relationships reserved for flagship academic medical center installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as handheld EEG-based triage devices displace CT-first protocols in low-risk concussion presentations, threatening installed-base incumbents with workflow bypass.
For Market Incumbents: Secure radiology workflow integration through PACS compatibility investments and embedded AI interpretation tools that lock emergency departments into CT and MRI dependency. Deepen backward integration into superconducting magnet production to defend cost position against Siemens Healthineers and Philips. Prioritize FDA breakthrough designation pursuit for next-generation MRI sequences targeting diffuse axonal injury detection to maintain premium pricing against point-of-care substitutes. For New Entrants and Emerging Players: Differentiate on emergency department throughput metrics by demonstrating radiology queue bypass in mass casualty surge scenarios. Target rural and community hospital settings in the United States where neuroradiologist shortages create acute capacity constraints. Pursue German trauma network procurement contracts leveraging national concussion registry interoperability mandates as the most penetrable geographic entry point. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biomarker platform developers with validated blood panels approaching clinical guideline inclusion over pure-play imaging hardware. Five-to-ten year viability hinges on reimbursement capture for concussion-specific diagnostic codes across multiple jurisdictions. Watch for FDA breakthrough designation announcements paired with simultaneous CMS national coverage determination petitions as the critical inflection signal for platform commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerated review timelines compress competitive entry windows for novel TBI diagnostics. |
| Hospital System Partnership | Multi-site validation trials anchor biomarker platform adoption across trauma networks. |
| CE Marking Pathway | EU MDR compliance enables German national concussion registry procurement eligibility. |
| Software Companion Development | AI-embedded PACS integration locks radiology departments into incumbent imaging workflows. |
| Reimbursement Strategy | CMS national coverage determinations for concussion CPT codes drive hospital capital allocation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and breakthrough device filings, CMS reimbursement determinations, and EU MDR technical documentation databases. Clinicians, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided qualitative inputs on procurement decision criteria and workflow integration priorities. Bottom-up equipment installation data triangulates against top-down trauma center capacity estimates and national concussion registry reporting volumes.
Segmentation dimensions modeled include assessment type, technology modality, end-user facility category, and application phase across the projection horizon. CAGRs derive from trauma center admission trend analysis, collegiate athletic department baseline testing protocol expansion rates, and biomarker validation study completion timelines. Diffuse axonal injury detection capability advancement and blood-based panel clinical guideline inclusion probability weight forecast scenario outcomes.
Material uncertainties — FDA breakthrough designation grant rates, CMS national coverage determination timing, and EU MDR notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway efficiency and reimbursement code valuation stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurology Services Market
Neurology
Global Neuroblastoma Market
Neurology
Chiari Malformation Treatment Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
India Neurology Devices Market
Neurology
Bell Palsy Treatment Market
Neurology
Brazil Neurology Devices Market
Neurology
CNS Therapeutics Market
Neurology
Nerve Repair Market
Neurology
Spasticity Treatment Market
Neurology
Neuro Critical Care Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Cluster Headache Syndrome Market
Neurology
South America Neurology Monitoring Market
Neurology
Optic Neuropathy Management Market