
 Biomarker Testing Services Market | 2026-2036
Biomarker Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Biomarker Testing Services Market Intelligence
Software-defined assay customization is consolidating around platform-agnostic bioinformatics pipelines that let clients reconfigure test panels without wet-lab redesign. Thermo Fisher Scientific Inc. leverages its instrument-installed base to bundle consumables with cloud analytics, while IQVIA anchors its position through real-world evidence integration that links biomarker data to patient outcomes. Eurofins Scientific competes on geographic density, operating accredited labs across multiple regulatory jurisdictions to shorten sample logistics.
Biomarker testing services comprise laboratory and analytical workflows that detect and quantify biological indicators—proteins, nucleic acids, metabolites, or cellular signatures—using validated platforms with defined sensitivity thresholds, typically picogram-per-milliliter detection limits for immunoassays. These services support drug development decisions, patient stratification, and diagnostic claims by translating specimen data into clinically actionable readouts. Oncology applications dominate current revenue within the application dimension, given the volume of immuno-oncology trials requiring PD-L1 and circulating tumor DNA monitoring. Next-Generation Sequencing within the technology dimension captures the fastest expansion as panel sizes grow and per-run costs fall, though ELISA retains margin strength in high-throughput safety pharmacology settings where regulatory familiarity reduces validation burden.
The FDA's companion diagnostics guidance and EMA's In Vitro Diagnostic Medical Devices Regulation together shape validation requirements and market access timelines for service providers seeking multi-territory study support. ISO 15189 accreditation and CAP proficiency testing standards further constrain which laboratories pharmaceutical sponsors qualify for pivotal trial work. Stakeholders must monitor how emerging FDA guidance on artificial intelligence-enabled biomarker algorithms reshapes the boundary between laboratory-developed tests and regulated diagnostic devices.
Market Dynamics
Pharmaceutical sponsors now embed biomarker testing into Phase I protocols, compressing traditional trial timelines and forcing service providers to restructure laboratory workflows around adaptive study designs rather than fixed analytical panels.
Growth Catalysts
- Companion Diagnostic Mandates:FDA guidance requiring co-development of biomarker assays with targeted therapies pulls testing services into earlier drug development stages.
- Immuno-Oncology Pipeline Expansion:PD-L1 expression profiling and circulating tumor DNA monitoring now accompany the majority of checkpoint inhibitor trials.
- Real-World Evidence Integration:Linking biomarker data to longitudinal patient outcomes creates new contract structures for service providers.
Market Restraints
- Reference Material Scarcity:Limited availability of certified calibrators for novel protein biomarkers extends validation timelines and increases analytical uncertainty.
- Reimbursement Fragmentation:Divergent coding practices across Medicare contractors and commercial payers create pricing opacity for laboratory-developed tests.
- Platform Lock-In Effects:Proprietary instrument ecosystems from dominant vendors constrain client migration between service providers.
Strategic Opportunities
- Artificial Intelligence-Enabled Assay Design:Machine learning algorithms predicting biomarker performance from sequence data reduce wet-lab iteration cycles.
- Decentralized Trial Logistics:Home-based sample collection and direct-to-patient shipping networks expand addressable patient populations for rare disease studies.
- Asia-Pacific Regulatory Convergence:MFDS and NMPA alignment with ICH biomarker qualification guidelines opens multi-territory submission pathways.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists capable of integrating multi-omics datasets constrains service expansion.
- CAP Proficiency Testing Burden:Maintaining accreditation across multiple analytical platforms requires continuous external quality assessment expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomarker Testing Services Market |
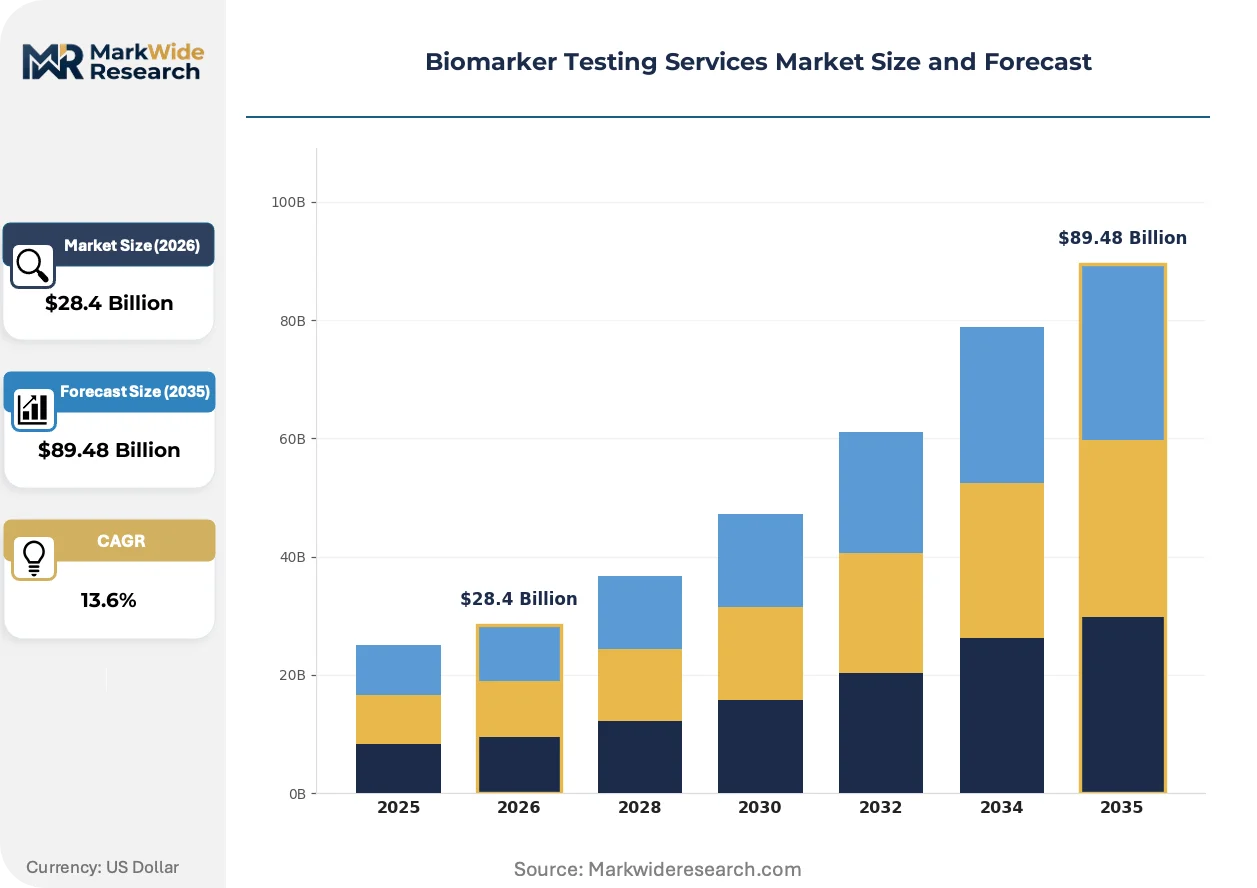
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $89.48 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Genetic Testing, Protein Analysis, Metabolomic Profiling, Biomarker Discovery End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Clinics Technology: PCR, Next-Generation Sequencing, ELISA, Mass Spectrometry Application: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | Charles River Laboratories, ICON Plc, Eurofins Scientific, IQVIA, Syneos Health, BioAgilytix Labs, Laboratory Corporation of America Holdings, SGS SA, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomarker Testing Services Market Strategic Shifts & Innovations
Liquid biopsy workflows are compressing tissue acquisition requirements while expanding the temporal resolution of treatment monitoring. Three developments are restructuring competitive positioning.
Next-Generation Sequencing-based minimal residual disease monitoring is overtaking flow cytometry in hematologic malignancy trials. Sponsors at major academic medical centers now specify ctDNA-based endpoints in protocol designs. This shift is compressing the addressable market for multi-parameter flow platforms while expanding demand for bioinformatics pipelines capable of variant allele frequency quantification below 0.1%.
EMA's In Vitro Diagnostic Medical Devices Regulation imposes notified body oversight on companion diagnostic components previously classified as laboratory-developed tests. Service providers must now maintain quality management systems meeting Annex IX technical documentation requirements. European oncology trials face extended startup timelines as sponsors navigate conformity assessment procedures for biomarker stratification protocols.
Site-less clinical trial models are fragmenting traditional central laboratory relationships. Direct-to-patient sample collection kits and local phlebotomy networks displace investigator-site processing for biomarker timepoint collection. This restructuring concentrates in United States immuno-oncology studies where geographic patient dispersion and competitive enrollment pressures reward decentralized logistics.
Biomarker Testing Services Market Segmentation
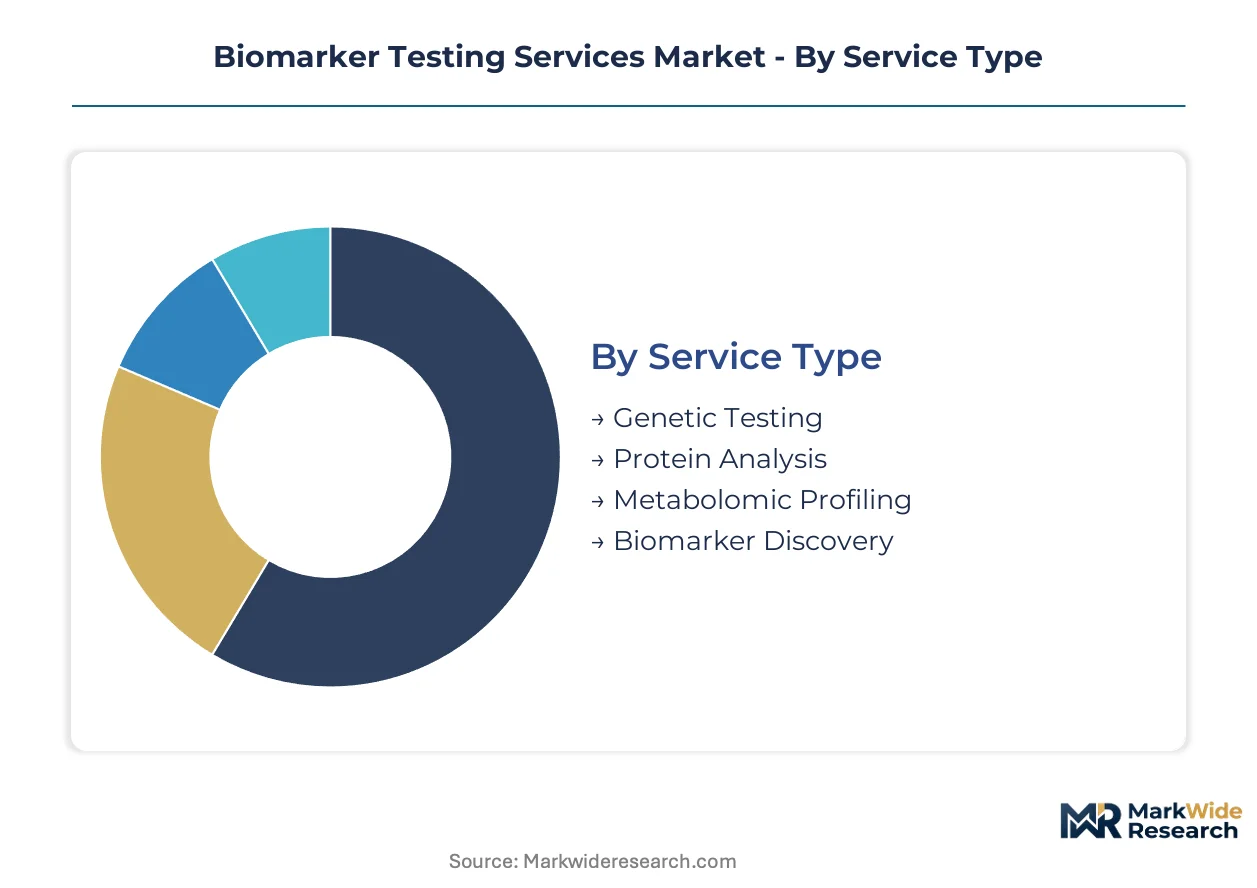
Biomarker testing services fragment across four operational dimensions that shape procurement decisions and vendor selection criteria. Pharmaceutical sponsors prioritize technology-platform compatibility and regulatory validation status when contracting analytical workflows. Service providers must align capability portfolios against these segment boundaries to capture contract volume from distinct buyer archetypes.
Service Type:
Contract value concentrates in segments offering regulatory-grade documentation and multi-territory submission support.
- Genetic Testing:Nucleic acid-based assays detect somatic mutations, germline variants, and gene expression signatures using validated PCR and NGS workflows. Pharmaceutical sponsors in the United States and Germany drive demand for companion diagnostic co-development programs requiring FDA and EMA submission packages. The segment commands premium pricing where laboratories hold dual accreditation under CAP and ISO 15189 standards.
- Protein Analysis:Immunoassay platforms quantify protein biomarkers with defined sensitivity thresholds, typically picogram-per-milliliter detection limits for cytokine panels and pharmacokinetic endpoints. High-throughput safety pharmacology studies at contract research organizations in Boston and San Diego sustain volume demand despite slower growth trajectories compared to nucleic acid methods.
- Metabolomic Profiling:Mass spectrometry-based workflows characterize small-molecule signatures for drug mechanism studies and toxicity biomarker identification.
- Biomarker Discovery:Exploratory services apply multi-omics approaches to identify novel targets without predefined assay validation requirements.
Genetic Testing leads on scale; Metabolomic Profiling gains share fastest in immuno-oncology applications.
End User:
Buyer sophistication and internal analytical capabilities determine outsourcing depth and contract structure preferences.
- Pharmaceutical Companies:Large sponsors embed biomarker testing into Phase I protocols to compress traditional trial timelines and reduce attrition rates. Adaptive study designs at Pfizer, Roche, and AstraZeneca facilities require service providers to restructure laboratory workflows around flexible analytical panels rather than fixed menus.
- Biotechnology Firms:Venture-backed developers lack internal infrastructure and depend on full-service partnerships spanning discovery through regulatory submission. Cambridge, Massachusetts and South San Francisco clusters concentrate demand for integrated bioinformatics and biostatistics support.
- Research Institutions:Academic medical centers prioritize technology access and collaborative publication rights over throughput metrics.
- Clinics:Hospital-based laboratories seek validated assays with established reimbursement codes for patient care applications.
Pharmaceutical Companies anchor contract value; Biotechnology Firms show the steepest expansion trajectory in emerging therapeutic areas.
Technology:
Platform selection balances sensitivity requirements, sample throughput, and regulatory familiarity against per-sample economics.
- Next-Generation Sequencing:Panel-based and whole-genome approaches capture the fastest expansion as per-run costs fall and bioinformatics pipelines mature. Circulating tumor DNA monitoring for minimal residual disease endpoints now specifies variant allele frequency quantification below 0.1% in hematologic malignancy trials.
- PCR:Quantitative and digital methods retain dominance in infectious disease diagnostics and gene expression profiling where rapid turnaround and established validation protocols reduce regulatory risk.
- ELISA:Enzyme-linked immunosorbent assays maintain margin strength in high-volume safety pharmacology settings where regulatory familiarity reduces validation burden.
- Mass Spectrometry:Proteomic and metabolomic applications require specialized operator expertise and extended method development timelines.
PCR leads on installed base and regulatory precedent; Next-Generation Sequencing climbs fastest in oncology companion diagnostic development.
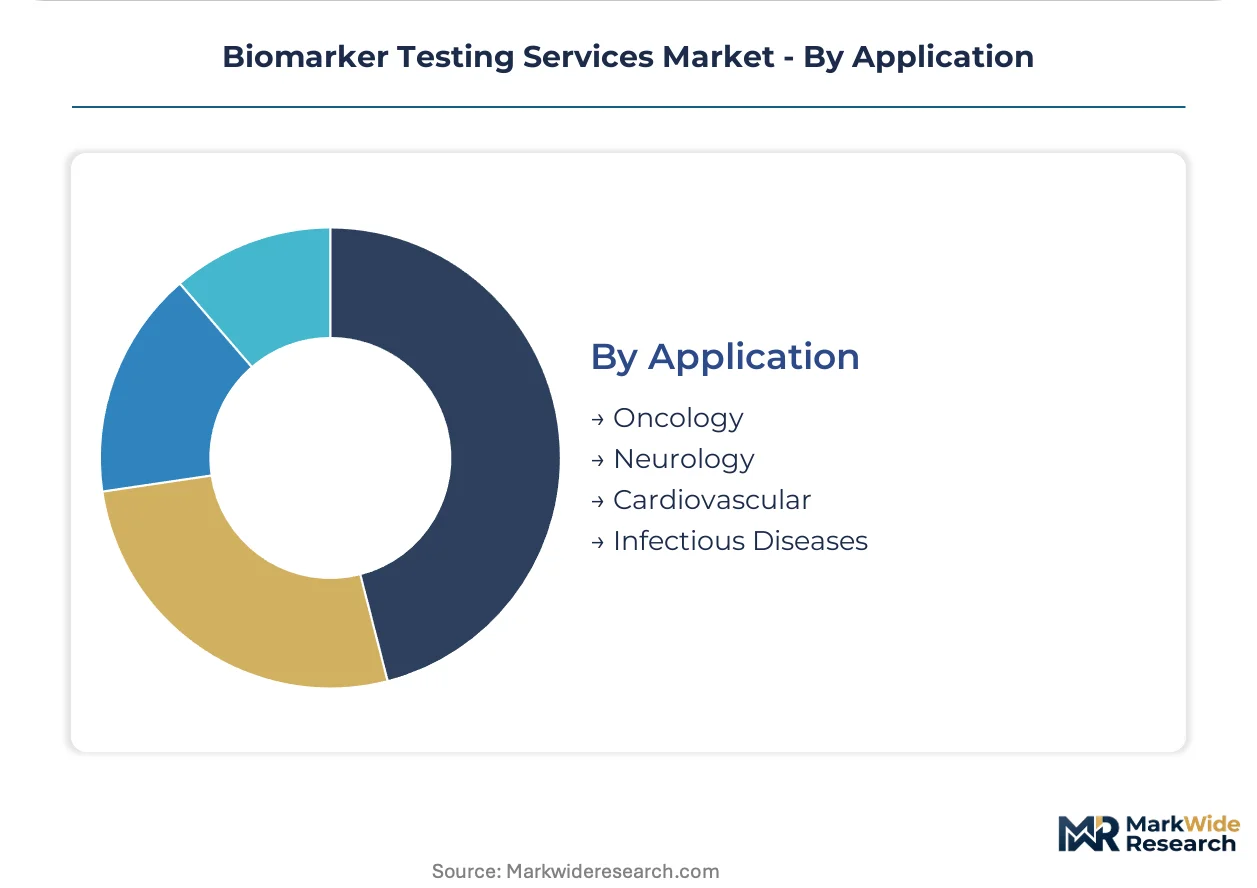
Application:
Therapeutic area focus determines assay menu requirements and biomarker class concentration.
- Oncology:PD-L1 expression profiling and circulating tumor DNA monitoring accompany the majority of checkpoint inhibitor trials. Immuno-oncology pipeline expansion concentrates demand at academic medical centers in the United States, Germany, and Japan.
- Neurology:Cerebrospinal fluid biomarkers for neurodegenerative disease progression face validation challenges due to reference material scarcity and longitudinal outcome data gaps.
- Cardiovascular:Protein biomarkers for heart failure risk stratification compete against established imaging modalities for inclusion in outcomes trials.
- Infectious Diseases:Pathogen detection and antimicrobial resistance profiling sustain demand for rapid molecular diagnostics in pandemic preparedness frameworks.
Oncology leads on revenue concentration; Neurology shows the most rapid capability investment as sponsors target disease-modifying therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's laboratory network density exceeds that of France, yet both trail the United States in companion diagnostic submission volume. Regulatory convergence across the European Union, Japan, and South Korea is compressing multi-territory study timelines.
United States
Academic medical centers in Boston and San Diego drive contract concentration for immuno-oncology trials. FDA companion diagnostic guidance mandates co-development of biomarker assays with targeted therapies. Cambridge, Massachusetts anchors biotechnology firm clustering for integrated bioinformatics partnerships.
Germany
Pharmaceutical sponsors leverage ISO 15189-accredited laboratories for EMA submission packages. EMA In Vitro Diagnostic Medical Devices Regulation imposes notified body oversight on companion diagnostic components. Heidelberg and Munich concentrate precision medicine infrastructure for hematologic malignancy studies.
Japan
PMDA alignment with ICH biomarker qualification guidelines accelerates multi-territory submission pathways. METI funding for genomic medicine infrastructure expands NGS platform adoption. Tokyo and Osaka anchor contract research organization clustering for Asia-Pacific trial coordination.
China
NMPA regulatory convergence with international standards opens global study participation for domestic biotechnology firms. National genomic medicine initiatives expand CLIA-equivalent laboratory capacity. Shanghai and Suzhou concentrate precision medicine industrial parks for multinational sponsor partnerships.
United Kingdom
NHS genomic medicine service contracts sustain reference laboratory throughput for rare disease biomarker panels. MHRA post-Brexit regulatory autonomy maintains alignment with FDA and EMA validation standards. London and Cambridge anchor pharmaceutical sponsor R&D clustering for early-phase trial biomarker integration.
Biomarker Testing Services Market Key Industry Players
Top-tier vendors anchor multi-platform service portfolios, while mid-tier specialists compete on therapeutic-area depth or geographic density. The market structure reflects consolidation around instrument-installed bases and regulatory accreditation breadth. Three archetypes dominate: full-service contract research organizations, instrument-anchored platform providers, and geographic-density-focused laboratory networks. Competitive moves concentrate on strategic partnerships for real-world evidence integration and capacity expansion for decentralized trial logistics.
Among full-service contract research organizations, IQVIA and Charles River Laboratories exemplify the integrated bioinformatics archetype. Eurofins Scientific occupies a position within the geographic-density tier, operating accredited laboratories across multiple regulatory jurisdictions. Thermo Fisher Scientific Inc. anchors the instrument-platform archetype, leveraging consumable bundling with cloud analytics capabilities.
| Leading Market Players |
|---|
| Charles River Laboratories |
| ICON Plc |
| Eurofins Scientific |
| IQVIA |
| Syneos Health |
| BioAgilytix Labs |
| Laboratory Corporation of America Holdings |
| SGS SA |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Next-Generation Sequencing platform commoditization is compressing per-run costs while concentrating reagent supply among three dominant vendors, simultaneously eroding price floors in genetic testing segments and amplifying procurement leverage for high-volume pharmaceutical sponsors.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for NGS consumables and compressing margins on standardized immunoassay panels. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited reference laboratories from ISO-certified regional providers and uncertified discovery-service shops. Cost compression in protein analysis is intensifying because ELISA platform oversupply outpaces safety pharmacology study volume growth. Biotechnology firms in Cambridge and South San Francisco show highest price sensitivity due to venture funding constraints, while large pharmaceutical sponsors at Pfizer and Roche facilities prioritize regulatory-grade documentation over unit economics.
Supply Chain Analysis
Direct-to-patient sample collection networks bypass traditional investigator-site processing for decentralized immuno-oncology trials in the United States. Reagent supply concentrates in the United States, Germany, and Japan for certified calibrators and validated antibody lots. Raw material dependencies span synthetic oligonucleotides, recombinant protein standards, and fluorophore-conjugated detection reagents. Single-source vulnerability runs through sole-supplier relationships for critical PD-L1 assay clones. Distribution runs through central laboratory hubs in Boston, San Diego, and Heidelberg, with regional satellite labs handling last-mile logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory capacity arbitrage between the United States and China creates margin expansion opportunities as NMPA regulatory convergence reduces duplicate validation costs for multi-territory studies.
For Market Incumbents: To counter bioinformatics talent scarcity constraining multi-omics service expansion, anchor defensive positioning through backward integration into cloud analytics infrastructure and captive training pipelines for computational biologists. Prioritize CAP accreditation maintenance across decentralized trial logistics networks to preserve pharmaceutical sponsor relationships against site-less model fragmentation. For New Entrants and Emerging Players: Capture neurology biomarker validation services where reference material scarcity has delayed incumbent assay development, positioning around cerebrospinal fluid collection logistics and longitudinal outcome data partnerships. Target Asia-Pacific regulatory convergence opportunities as MFDS and NMPA alignment with ICH guidelines opens submission pathway support contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier geographic-density laboratory networks lacking real-world evidence integration capabilities but holding multi-jurisdiction ISO 15189 accreditation. Long-term viability hinges on artificial intelligence-enabled assay design adoption curves and companion diagnostic co-development contract attach rates. Watch FDA guidance on AI-enabled biomarker algorithms as the inflection signal reshaping laboratory-developed test classification boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA-mandated assay co-development with targeted therapies locks in multi-year pharmaceutical sponsor relationships. |
| Real-World Evidence Integration | IQVIA-style longitudinal patient outcome linking creates differentiated contract structures beyond transactional testing. |
| Decentralized Trial Logistics Buildout | Direct-to-patient sample collection networks expand addressable populations for rare disease studies. |
| Artificial Intelligence Assay Design | Machine learning biomarker performance prediction reduces wet-lab iteration cycles and accelerates validation timelines. |
| Asia-Pacific Regulatory Convergence Positioning | MFDS and NMPA ICH alignment opens multi-territory submission support contracts for domestic biotechnology firms. |
Research Approach
Bottom-up pharmaceutical sponsor demand modeling reconciled against top-down laboratory capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, clinical operations directors, and central laboratory procurement managers were validated against FDA 510(k) filings, EMA companion diagnostic submissions, ClinicalTrials.gov protocol specifications, and CAP proficiency testing records. Secondary triangulation incorporated ISO 15189 accreditation databases, pharmaceutical R&D expenditure disclosures, and academic medical center contract award announcements.
Historical trendline analysis across genetic testing, protein analysis, metabolomic profiling, and biomarker discovery service types informed projection frameworks. Segmentation dimensions spanned technology platform, therapeutic area application, end-user sophistication tier, and regional regulatory cluster. CAGR derivation rested on laboratory capacity expansion schedules, pharmaceutical pipeline biomarker endpoint specifications, and reimbursement code adoption curves. Forecast inputs included NGS per-run cost decline trajectories and companion diagnostic submission volume trends.
Regulatory guidance revision, reimbursement coding fragmentation, and platform technology substitution are the dominant revision risks to projection assumptions. Forecasts reflect prevailing validation standards and accreditation requirements without anticipating structural regulatory shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Creatinine Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
West Nile Virus Testing Market
Testing Services
Healthcare Testing, Inspection, and Certification Outsourcing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Bleeding Disorders Testing Market