
 Global Vertigo Treatment Market | 2026-2036
Global Vertigo Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vertigo Treatment Market Foresight
A shortage of certified vestibular rehabilitation therapists is collapsing access timelines in rural healthcare systems. Pfizer leverages its neurology manufacturing scale to maintain supply continuity for benzodiazepine-based protocols. Teva Pharmaceutical Industries competes through generic antihistamine portfolios that anchor cost-sensitive hospital procurement. Medtronic differentiates via implantable vestibular nerve stimulators that occupy the high-acuity surgical segment.
Vertigo treatment encompasses pharmacological, interventional, and rehabilitative modalities targeting pathological dizziness stemming from peripheral labyrinthine, central neurological, or cervical vestibular dysfunction. Antihistamine-class vestibular suppressants remain the dominant first-line oral therapy due to favorable safety margins and broad formulary inclusion. Intratympanic corticosteroid delivery represents the fastest-growing modality as otolaryngologists seek site-specific intervention for refractory Meniere's presentations. Telemedicine-enabled remote vestibular therapy is maturing fastest among delivery modes, though reimbursement parity lags behind in-person protocols.
The FDA's 505(b)(2) pathway shapes competitive dynamics by enabling abbreviated development for repurposed CNS compounds, while the EMA's MDR requirements extend certification burdens for active implantable devices. India's CDSCO accelerated approval track for orphan neurological indications creates parallel market access for specialty manufacturers. Stakeholders must monitor how Health Canada's evolving digital health guidance will classify AI-assisted vestibular diagnostic platforms, as this determination will reshape capital allocation between hardware and algorithmic development priorities.
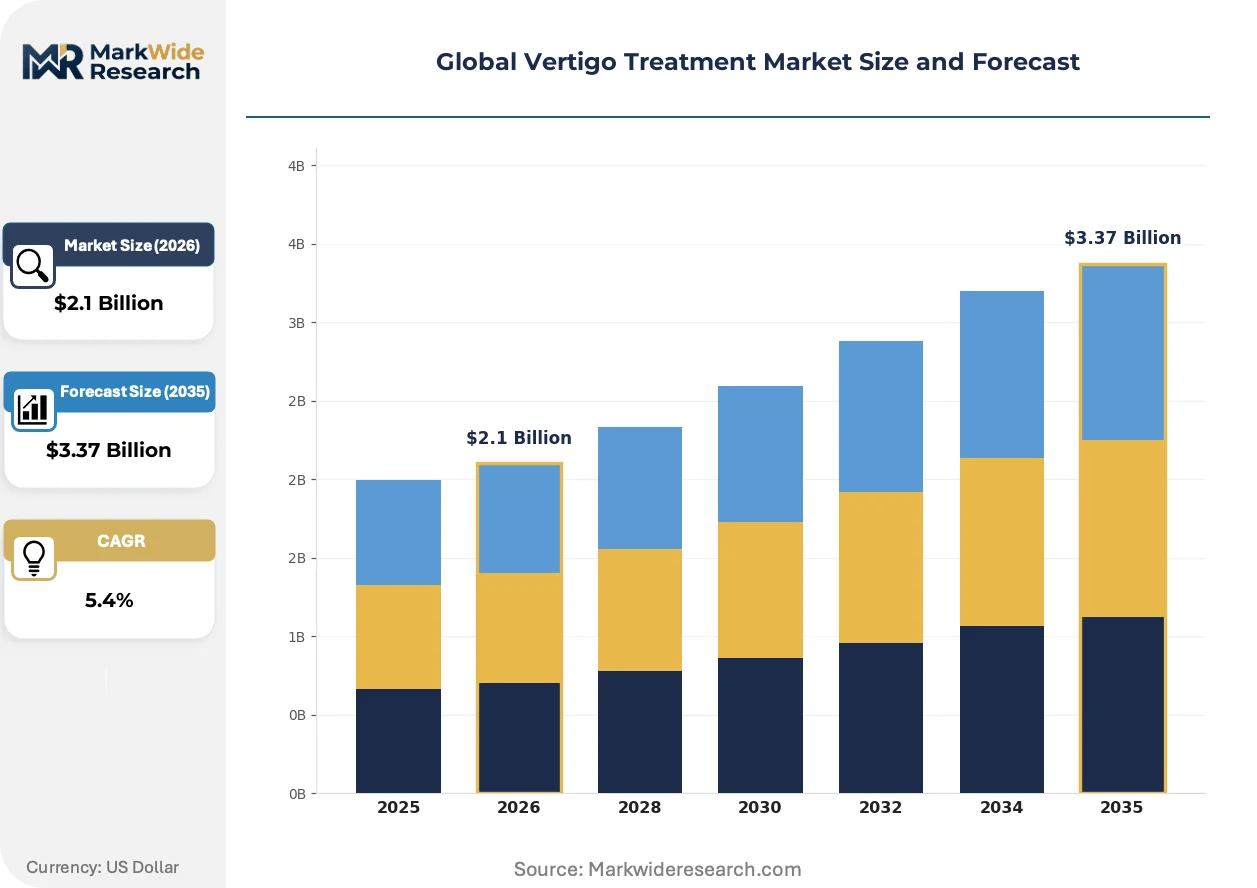
Market Dynamics
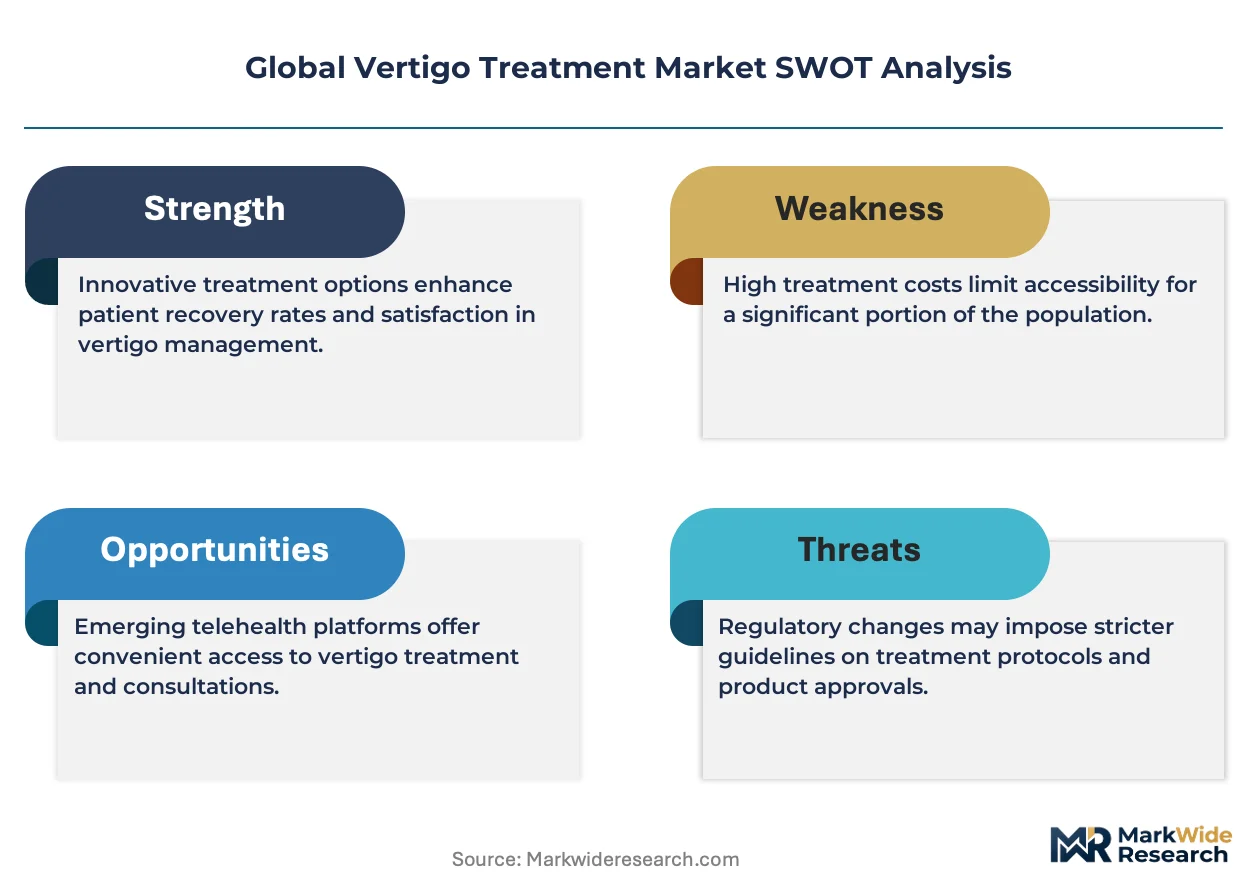
The FDA's 505(b)(2) regulatory pathway is compressing development timelines for repurposed neurological compounds, while EMA's MDR certification burdens for active implantables create divergent competitive entry barriers across regulatory jurisdictions.
Growth Catalysts
- 505(b)(2) Pathway Acceleration:The FDA's abbreviated approval track enables faster market entry for reformulated vestibular suppressants, reducing clinical trial burdens for sponsors targeting peripheral labyrinthine dysfunction.
- Telemedicine Infrastructure Maturation:Remote vestibular therapy platforms are expanding addressable patient populations beyond urban ENT hospital networks into underserved rural healthcare systems.
- Germany's ENT Cluster Density:Concentrated specialist hospital networks in Bavaria and North Rhine-Westphalia generate concentrated demand for high-acuity surgical interventions and site-specific drug delivery systems.
Market Restraints
- Certified Therapist Scarcity:Rural healthcare systems face collapsed access timelines due to insufficient vestibular rehabilitation specialists, limiting penetration of evidence-based physical therapy protocols.
- EMA MDR Certification Burden:Extended conformity assessment timelines for active implantable devices delay commercialization of next-generation vestibular nerve stimulators in European markets.
- Generic Antihistamine Substitution:Cost-sensitive hospital procurement committees prioritize formulary-standard vestibular suppressants over novel therapeutic classes, compressing premium pricing power.
Strategic Opportunities
- India's CDSCO Orphan Track:Accelerated approval pathways for neurological indications enable parallel market access for specialty manufacturers targeting refractory Meniere's presentations.
- AI-Assisted Diagnostic Convergence:Machine learning algorithms paired with wearable motion sensors are creating new product categories for ambulatory vertigo monitoring outside clinical settings.
- Intratympanic Delivery Innovation:Site-specific corticosteroid administration represents white space for device-drug combination products targeting refractory peripheral vestibular disorders.
Industry Challenges
- Reimbursement Parity Deficits:Telemedicine-enabled remote vestibular therapy lacks payment equivalence with in-person protocols, constraining provider adoption despite clinical efficacy.
- Health Canada Digital Classification Uncertainty:Evolving guidance on AI-assisted vestibular diagnostic platforms creates capital allocation paralysis between hardware and algorithmic development priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vertigo Treatment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vestibular Suppressants, Anticholinergics, Antihistamines, Benzodiazepines, Corticosteroids Therapy Area: Peripheral Vertigo, Central Vertigo, Positional Vertigo, Vestibular Migraine, Mal de Debarquement End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Diagnostic Laboratories, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Intratympanic Injection, Physical Therapy, Telemedicine |
| Companies Covered | GlaxoSmithKline, Viatris, Pfizer, Lupin, Dr. Reddy’s Laboratories, Novartis, Teva Pharmaceutical Industries, Medtronic, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vertigo Treatment Market Shifts & Advancements
Digital health convergence and site-specific intervention modalities are restructuring competitive advantage away from oral pharmacology toward integrated diagnostic-therapeutic systems.
Implantable vestibular nerve stimulators are decomposing the traditional surgical intervention landscape by enabling chronic neuromodulation for refractory central vestibular dysfunction. Otolaryngology departments in German university hospitals are piloting these devices for high-acuity patient segments. This modality is compressing the addressable market for repeated intratympanic injections and ablative procedures.
EMA's Medical Device Regulation (MDR) is extending certification timelines for active implantable devices, forcing manufacturers to restructure quality management systems and clinical evidence packages. European notified bodies face capacity constraints for Class III neurological device reviews. Smaller device sponsors are redirecting initial commercialization toward US FDA pathways while awaiting European technical documentation acceptance.
Hospital procurement committees are consolidating vendor relationships for vestibular therapy devices, favoring suppliers offering bundled diagnostic hardware and rehabilitation software platforms. Integrated system contracts are displacing standalone device purchasing in Germany's centralized hospital procurement frameworks. This concentration is most visible in North Rhine-Westphalia's university hospital networks, where multi-year sole-source agreements now dominate capital equipment allocation.
Global Vertigo Treatment Market Segmentation
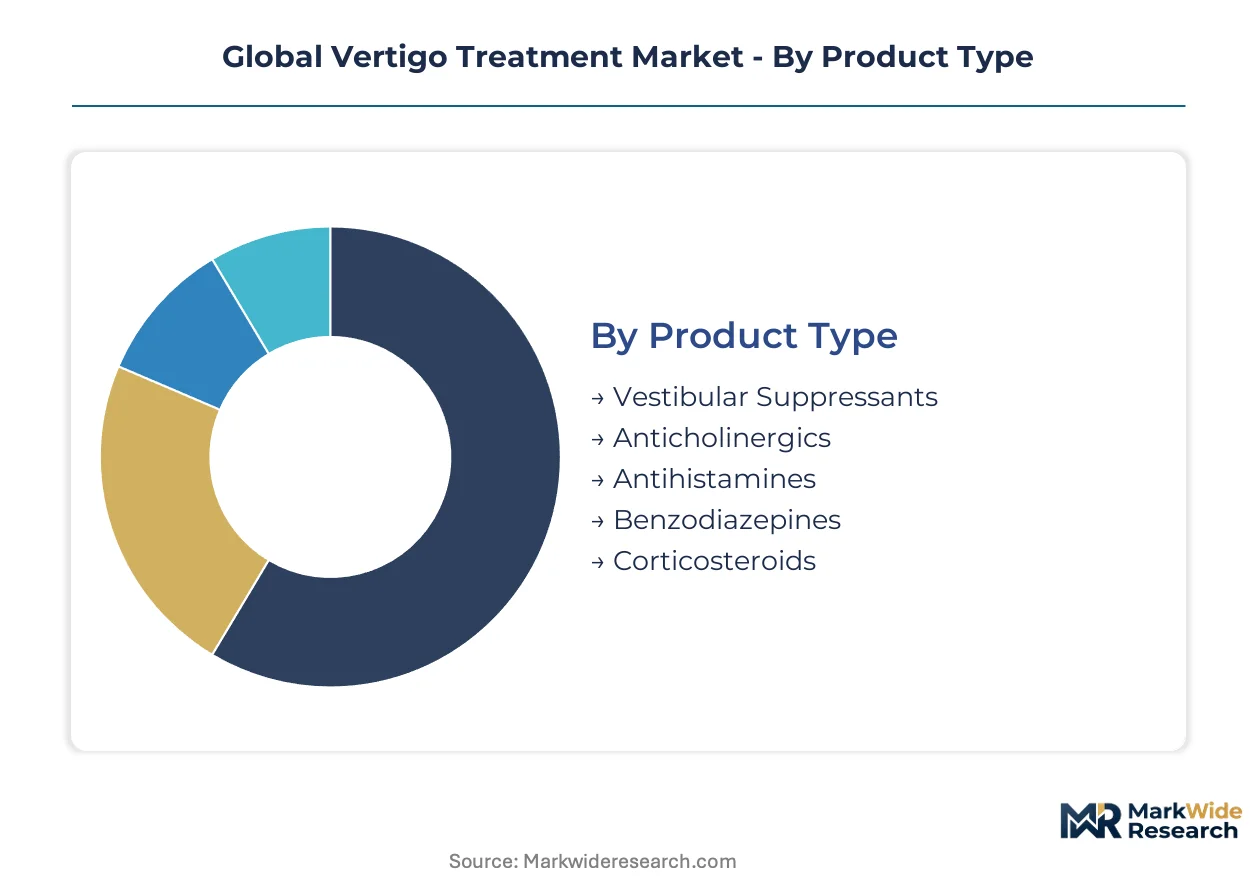
Segmentation in vertigo treatment reveals distinct channel economics across pharmacological, interventional, and rehabilitative modalities. Product type and delivery mode determine reimbursement pathways, while therapy area and end-user concentration shape geographic deployment strategies for manufacturers.
Product Type:
Channel mix varies sharply across pharmacological classes, with oral vestibular suppressants flowing through retail pharmacy networks while intratympanic formulations concentrate in hospital-based ENT departments.
- Antihistamines:First-line oral therapy with broad formulary inclusion across US and German hospital systems. Demand concentrates in primary care and emergency department settings where rapid symptom control drives prescribing patterns.
- Corticosteroids:Site-specific intratympanic delivery for refractory Meniere's presentations requires otolaryngologist administration. Bavarian university hospitals in Germany anchor adoption for this high-acuity intervention modality.
- Vestibular Suppressants:Combination compounds targeting acute vertigo episodes through central nervous system modulation.
- Anticholinergics:Niche application in motion sickness-related presentations with limited formulary penetration.
- Benzodiazepines:Reserved for severe acute episodes with controlled substance scheduling constraints.
Antihistamines dominate installed base. Corticosteroids represent where expansion concentrates.
Therapy Area:
Application severity dictates intervention intensity, with peripheral labyrinthine disorders supporting outpatient pharmacological management while central neurological presentations require multidisciplinary hospital-based care.
- Peripheral Vertigo:Benign paroxysmal positional vertigo and Meniere's disease comprise the highest-volume treatable population. German ENT hospital networks generate concentrated procedural demand for canalith repositioning and intratympanic interventions.
- Vestibular Migraine:Expanding recognition among neurologists drives dual-specialty referral patterns. US academic medical centers are piloting integrated headache-vestibular clinics that combine pharmacological and rehabilitative protocols.
- Central Vertigo:Cerebrovascular and demyelinating etiologies requiring neurological subspecialty management.
- Positional Vertigo:BPPV presentations amenable to physical therapy-first approaches.
- Mal de Debarquement:Rare persistent post-motion syndrome with limited evidence-based interventions.
Peripheral Vertigo captures the majority of addressable volume. Vestibular Migraine is climbing the fastest as diagnostic criteria expand.
End User:
Customer type segmentation reveals procurement concentration effects, with German hospital procurement frameworks favoring sole-source agreements while US ambulatory settings sustain fragmented vendor relationships.
- Hospitals:Acute intervention capabilities and surgical suites support high-acuity device implantation and intratympanic delivery. North Rhine-Westphalia's centralized purchasing in Germany consolidates multi-year contracts for integrated diagnostic-therapeutic systems.
- Specialty Clinics:Otolaryngology and neurology-focused facilities concentrate vestibular rehabilitation expertise. Rural US markets face collapsed access timelines due to certified therapist scarcity.
- Ambulatory Care Centers:Cost-sensitive settings prioritizing generic antihistamine protocols.
- Diagnostic Laboratories:Vestibular function testing supporting referral network triage.
- Rehabilitation Centers:Physical therapy-focused facilities with telemedicine integration potential.
Hospitals anchor premium intervention revenue. Specialty Clinics represent the steepest expansion trajectory for telemedicine-enabled service models.
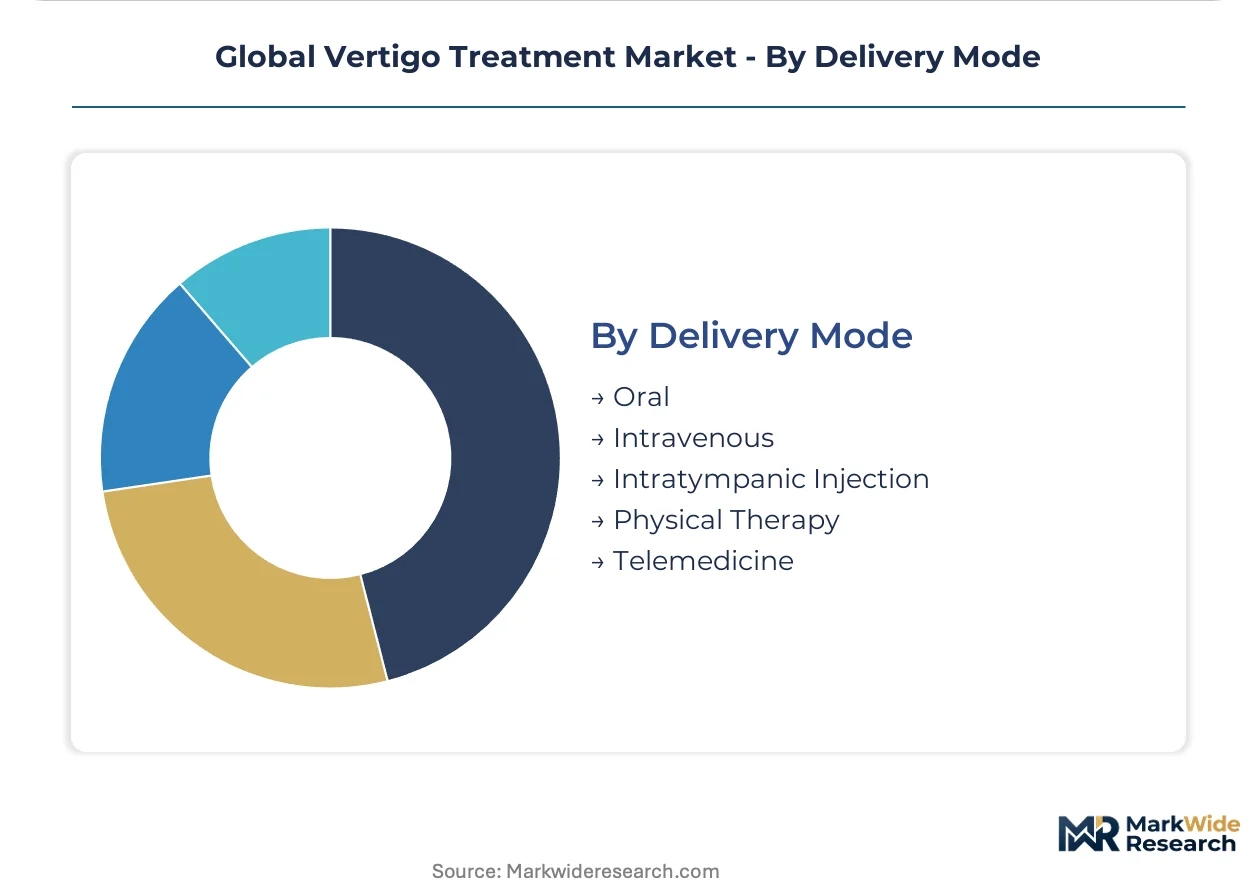
Delivery Mode:
Margin structure diverges across delivery modalities, with oral generics compressing pricing power while device-enabled site-specific delivery sustains premium positioning.
- Physical Therapy:Canalith repositioning and vestibular rehabilitation protocols require certified specialist administration. Therapist scarcity in rural US healthcare systems limits penetration despite clinical efficacy.
- Telemedicine:Remote vestibular therapy platforms are expanding fastest among delivery modes. Reimbursement parity deficits with in-person protocols constrain provider adoption in US Medicare and commercial payer networks.
- Oral:Standard tablet and capsule formulations with broad distribution.
- Intravenous:Acute hospital administration for severe presentations.
- Intratympanic Injection:Otolaryngologist-administered site-specific delivery for refractory cases.
Physical Therapy holds the largest existing service volume. Telemedicine is gaining share fastest as infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulatory frameworks anchor the dominant geography, while EMA certification requirements and India's accelerated approval tracks create divergent entry conditions across major markets.
United States
The FDA's 505(b)(2) pathway compresses development timelines for reformulated vestibular suppressants, reducing clinical trial burdens for sponsors. Telemedicine infrastructure expansion is extending remote vestibular therapy into rural healthcare systems lacking certified specialists. Academic medical centers in Boston and the Research Triangle pilot integrated headache-vestibular clinics.
Germany
EMA Medical Device Regulation extends certification timelines for active implantable vestibular nerve stimulators, forcing manufacturers to restructure quality management systems. Bavarian university hospitals anchor adoption for intratympanic corticosteroid delivery in refractory Meniere's presentations. North Rhine-Westphalia's centralized hospital procurement consolidates multi-year sole-source agreements for integrated diagnostic-therapeutic systems.
India
CDSCO accelerated approval tracks for orphan neurological indications enable parallel market access for specialty manufacturers. Cost-sensitive hospital procurement prioritizes generic antihistamine protocols over novel therapeutic classes. Maharashtra's pharmaceutical manufacturing clusters supply active pharmaceutical ingredients for vestibular suppressants across domestic and export markets.
Japan
PMDA neurological drug review standards shape development priorities for CNS-modulating vertigo compounds. Aging demographics expand the addressable patient population for chronic vestibular rehabilitation services. Tokyo's university hospital networks concentrate demand for high-acuity surgical interventions and implantable neuromodulation devices.
United Kingdom
NHS England referral pathway reforms are consolidating vestibular diagnostic services into specialist ENT hubs. MHRA post-Brexit regulatory autonomy creates parallel certification requirements for device sponsors. London's tertiary hospital networks generate concentrated procedural demand for canalith repositioning and advanced vestibular function testing.
Global Vertigo Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical conglomerates controlling oral therapy distribution while device manufacturers occupy surgical intervention segments. The market structures around three archetypes: neurology-focused pharmaceutical developers with manufacturing scale, generic antihistamine suppliers competing on hospital formulary inclusion, and active implantable device specialists targeting high-acuity surgical centers. Competitive moves concentrate on portfolio diversification into site-specific delivery modalities and strategic partnerships bundling diagnostic hardware with rehabilitation software platforms.
Within the integrated pharmaceutical tier, Pfizer and Novartis exemplify scale-driven positions leveraging neurology manufacturing infrastructure, while Teva Pharmaceutical Industries occupies the generic substitution segment. Medtronic anchors the active implantable device specialist archetype, with its vestibular nerve stimulator portfolio targeting German university hospital networks and US academic medical centers.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Viatris |
| Pfizer |
| Lupin |
| Dr. Reddy's Laboratories |
| Novartis |
| Teva Pharmaceutical Industries |
| Medtronic |
| Sanofi |
| Others |
Supply & Pricing Matrix
Generic antihistamine substitution in hospital formularies simultaneously compresses pricing premiums in oral vestibular suppressants and redirects supply chain investment toward site-specific delivery modalities in Germany and the United States. This input shift rewards manufacturers with intratympanic device-drug capabilities while eroding margins for pure-play oral pharmaceutical suppliers.
Pricing Analysis
Long-term sole-source agreements dominate procurement in German hospital networks, particularly North Rhine-Westphalia's centralized purchasing frameworks. Pricing stratifies across premium implantable neuromodulation systems, standard intratympanic corticosteroid protocols, and economy generic antihistamine tiers. Cost compression in the oral segment stems from formulary substitution pressures, while device-enabled modalities sustain premium positioning. Ambulatory care centers exhibit highest price sensitivity; German university hospitals show lowest sensitivity due to bundled diagnostic-therapeutic contracting.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for vestibular suppressants, while Germany and the United States concentrate finished device manufacturing and sterile formulation fill-finish. Supply chains draw from benzodiazepine precursor chemicals, corticosteroid raw materials, and implantable electrode components. Single-source vulnerability concentrates in specialized otolaryngology device components. Distribution runs through hospital procurement committees in Germany and GPO-mediated channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across delivery modalities creates niche expansion opportunities as telemedicine infrastructure matures and reimbursement pathways diverge between remote and in-person vestibular rehabilitation protocols.
For Market Incumbents: Fortify positions through backward integration into intratympanic delivery device manufacturing and captive supply of corticosteroid formulations. Pfizer-scale neurology manufacturers face margin compression from generic antihistamine substitution; vertical control over site-specific delivery modalities preserves pricing power. Certification investment in FDA 505(b)(2) pathways accelerates reformulation pipelines. For New Entrants and Emerging Players: Differentiate on AI-assisted diagnostic convergence paired with wearable motion sensors. Rural United States healthcare systems represent the most penetrable geography due to certified therapist scarcity. Telemedicine-enabled remote vestibular therapy offers the clearest go-to-market angle through direct-to-specialist-clinic software licensing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed otolaryngology device specialists holding CE marking progress but awaiting EMA MDR certification completion. Long-term viability centers on reimbursement parity achievement for remote delivery modalities. The signal to watch is Health Canada's digital health guidance classification for AI-assisted vestibular diagnostic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Intratympanic Delivery Device Development | Site-specific corticosteroid administration captures premium positioning in German ENT hospital networks. |
| Telemedicine Platform Integration | Remote vestibular therapy expands addressable patient populations beyond urban specialist concentrations. |
| AI-Assisted Diagnostic Certification | Health Canada digital health guidance determination reshapes capital allocation between hardware and algorithmic priorities. |
| 505(b)(2) Regulatory Pathway Utilization | FDA abbreviated approval accelerates market entry for reformulated CNS-modulating compounds. |
| Hospital System Partnership Structuring | North Rhine-Westphalia's sole-source agreements demonstrate bundled diagnostic-therapeutic system contracting viability. |
Research Methodology
Operator-level perspectives from otolaryngology department heads, hospital procurement committee members, vestibular rehabilitation therapists, and formulary directors anchored the qualitative base. Secondary validation drew from FDA 505(b)(2) submission databases, EMA MDR technical documentation filings, ClinicalTrials.gov vestibular intervention records, and German hospital procurement contract disclosures. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation structured quantitative foundations.
Sensitivity analysis tested forecast robustness across alternative reimbursement parity scenarios for telemedicine-enabled delivery and varying EMA MDR certification timeline assumptions. Segmentation dimensions included product pharmacological class, therapy area severity, end-user facility type, and delivery mode modality. CAGRs derived from patient volume growth rates applied to average revenue per treated episode estimates. Forecast inputs incorporated certified therapist supply constraints and intratympanic procedure adoption curves.
The analysis sits within stated boundaries; outcomes outside maintained FDA 505(b)(2) pathway efficiency or sustained EMA MDR notification body capacity would require recalibration. Forecasts reflect documented assumptions regarding telemedicine reimbursement evolution and implantable device clinical evidence standards. Recalibration cycles align with material shifts in regulatory pathway timelines and digital health classification determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Australia Neurology Devices Market
Neurology
Movement Disorder Market
Neurology
Arachnoiditis Treatment Market
Neurology
Cognitive Neuroscience Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Brazil Neurology Devices Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Intracranial Aneurysm Market
Neurology
North America Neurology Monitoring Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Global Sciatica Treatment Market