
 Global Acoustic Neuroma Market | 2026-2036
Global Acoustic Neuroma Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acoustic Neuroma Market Foresight
Gamma Knife certification standards are bifurcating the competitive landscape into accredited high-precision providers and generalist neurosurgery units. Elekta leverages its proprietary cobalt-60 source technology to sustain leadership in stereotactic radiosurgery installations across North American academic medical centers. Siemens Healthineers anchors its position through integrated MRI-linear accelerator platforms that merge real-time imaging with adaptive radiation delivery. Medtronic competes via surgical navigation and intraoperative monitoring systems that complement microsurgical resection workflows.
Acoustic neuroma, also termed vestibular schwannoma, denotes a benign intracranial nerve sheath tumor arising from Schwann cell proliferation along the vestibular division of cranial nerve VIII, typically presenting as a unilateral, slow-growing mass measuring 1–3 cm at diagnosis with consequential compression of the cerebellopontine angle structures. Its primary clinical purpose centers on preserving facial nerve function and usable hearing while achieving durable tumor control through either microsurgical excision or precision radiation modalities. Radiosurgery equipment now captures the dominant share of capital expenditure as outpatient shift economics favor single-session Gamma Knife and CyberKnife protocols over inpatient craniotomy. Pharmacotherapy represents the fastest-emerging therapy area, with targeted biologics and small-molecule inhibitors entering Phase II investigation for neurofibromatosis type 2-associated bilateral disease where surgery carries prohibitive morbidity.
The FDA's 510(k) and premarket approval pathways govern commercial entry for novel surgical devices and radiation platforms, while the EU MDR and CE marking requirements impose strengthened clinical evidence standards for implantable cranial hardware marketed across European member states. Japan's PMDA operates a separate pharmaceutical and medical device agency review track that conditions reimbursement listing on demonstrated superiority against existing standard-of-care interventions. Stakeholders must monitor convergence between real-time intraoperative MRI guidance and artificial intelligence-enabled contouring algorithms, as this integration promises to redefine margin precision and treatment planning velocity without expanding specialist workforce supply.
Market Dynamics
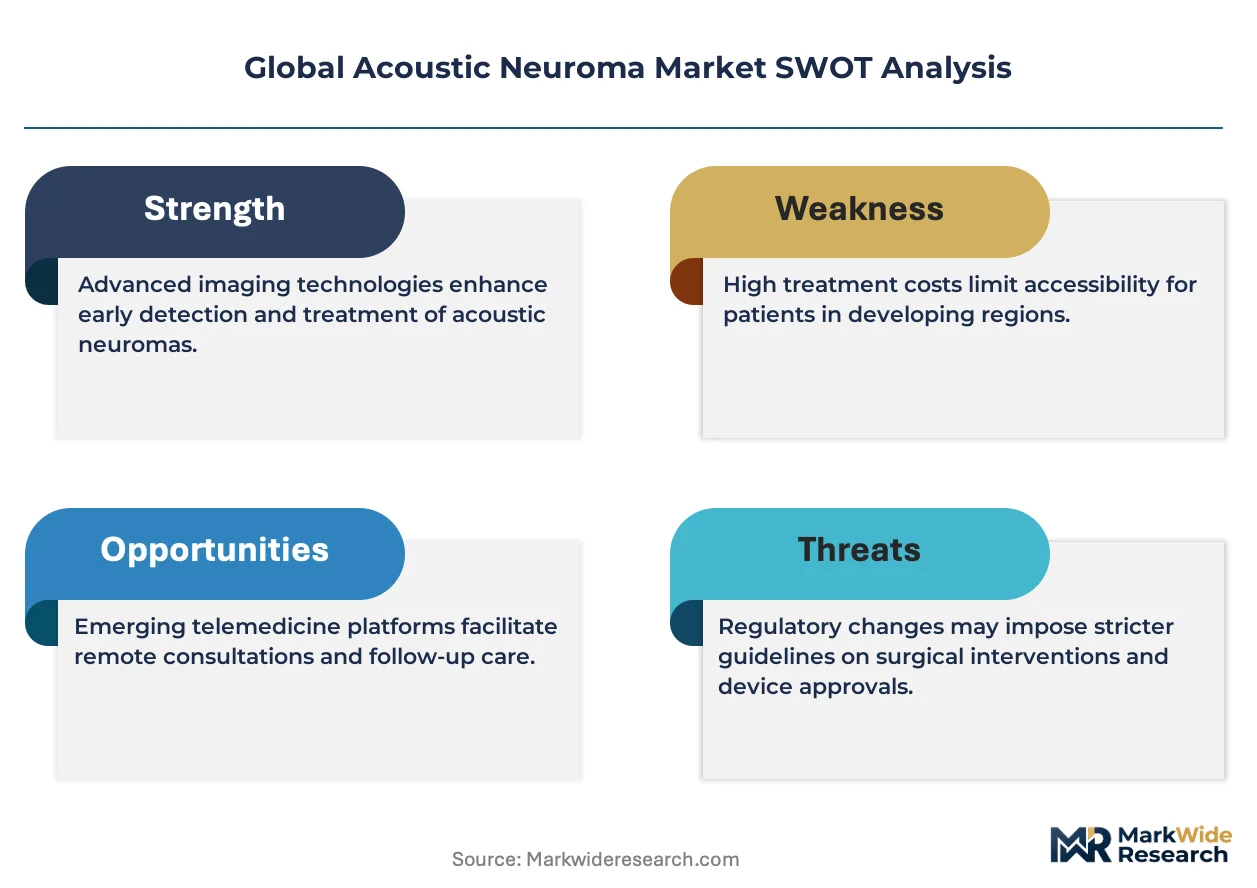
Gamma Knife certification standards are bifurcating provider networks into accredited high-precision centers and generalist neurosurgery units, compressing referral flows toward tertiary skull-base programs in the United States, Germany, and Japan.
Growth Catalysts
- Minimally Invasive Protocols:Neurosurgery centers across Germany, Japan, and the United States are expanding adoption of single-session radiosurgery over inpatient craniotomy, reducing recovery timelines and facility costs.
- FDA Pre-Market Pathways:The FDA's accelerated premarket approval pathway for novel radiosurgery platforms is compressing commercialization timelines for device innovators entering the precision radiation segment.
- NF2 Pharmacotherapy Pipeline:Targeted biologics and small-molecule inhibitors are entering Phase II investigation for neurofibromatosis type 2-associated bilateral disease where surgical morbidity proves prohibitive.
Market Restraints
- Cobalt-60 Supply Concentration:Elekta's proprietary cobalt-60 source technology creates supplier lock-in for stereotactic radiosurgery installations, limiting price competition in capital equipment procurement.
- EU MDR Compliance Burden:Strengthened clinical evidence standards for implantable cranial hardware under the EU MDR are extending CE marking timelines and inflating regulatory costs for European market entry.
- Microsurgical Skill Scarcity:The finite pool of fellowship-trained skull-base surgeons capable of facial nerve preservation surgery restricts service capacity expansion in high-volume referral markets.
Strategic Opportunities
- AI-Enabled Contouring Convergence:Integration between real-time intraoperative MRI guidance and artificial intelligence-enabled contouring algorithms promises to redefine margin precision without expanding specialist workforce supply.
- Japan PMDA Superiority Track:Japan's PMDA operates a separate review track conditioning reimbursement listing on demonstrated superiority against existing standard-of-care interventions, creating first-mover advantages for innovators.
- Outpatient Shift Economics:Single-session Gamma Knife and CyberKnife protocols are capturing dominant capital expenditure share as payors and patients favor ambulatory settings over inpatient craniotomy.
Industry Challenges
- Workforce Pipeline Constraints:Fellowship-trained skull-base neurosurgeons and medical physicists specializing in stereotactic radiosurgery remain scarce relative to expanding case volumes in tertiary care networks.
- Technology Integration Complexity:Merging real-time imaging with adaptive radiation delivery requires substantial IT infrastructure overhaul and staff retraining, delaying operational deployment of integrated MRI-linear accelerator platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acoustic Neuroma Market |
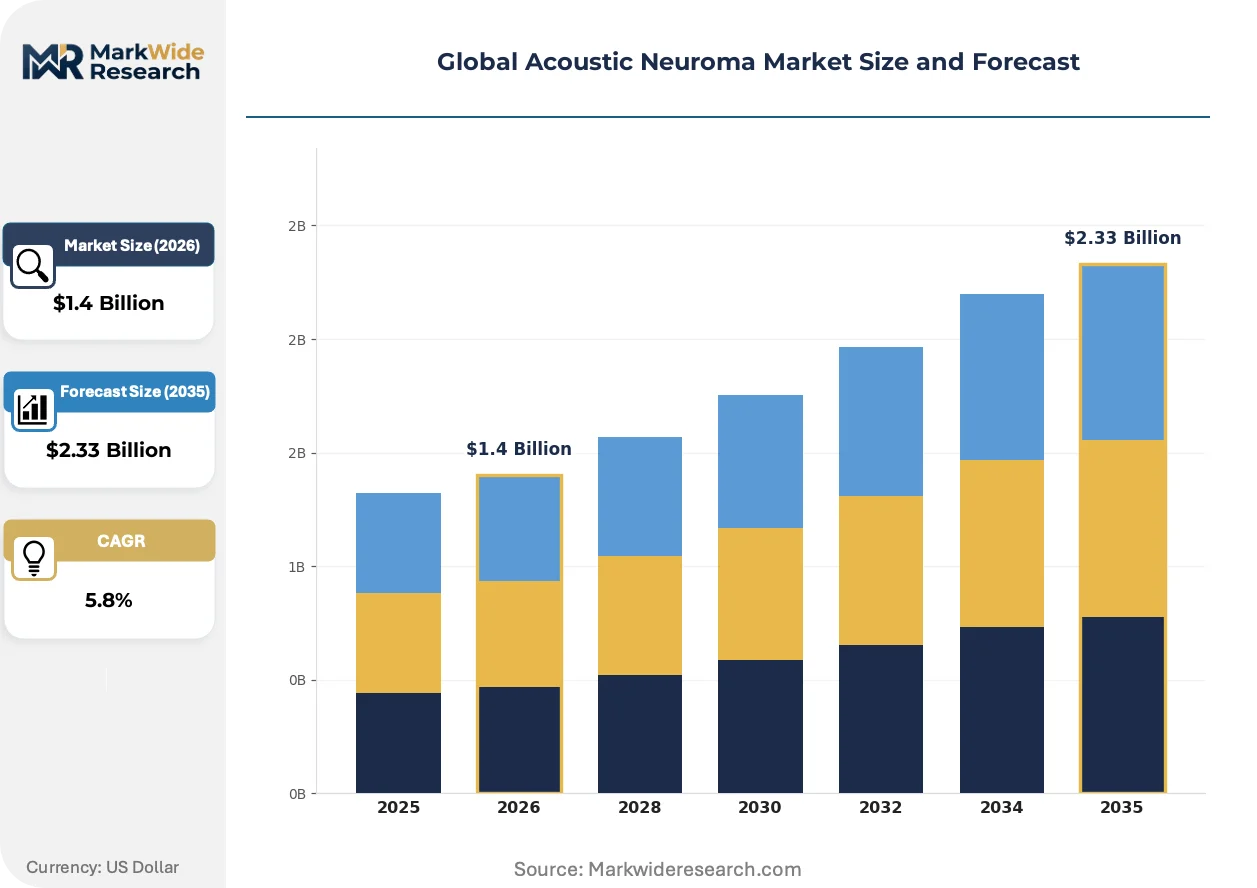
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Devices, Radiosurgery Equipment, Diagnostic Tools, Monitoring Systems Therapy Area: Microsurgery, Stereotactic Radiosurgery, Observation, Pharmacotherapy End User: Neurosurgery Centers, Specialty Clinics, Research Institutions, Rehabilitation Facilities Treatment Technique: Open Surgery, Gamma Knife, CyberKnife, Linear Accelerator |
| Companies Covered | Medtronic, Elekta, Siemens Healthineers, Accuray Incorporated, Natus Medical Incorporated, Amgen, Pfizer, F. Hoffmann-La Roche, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acoustic Neuroma Market Shifts & Advancements
Real-time imaging fusion with adaptive radiation systems is compressing treatment planning velocity and redefining margin precision standards across academic medical centers and specialized radiosurgery networks.
Adaptive MRI-linear accelerator platforms are displacing conventional fixed-source cobalt systems in North American academic medical centers. Siemens Healthineers anchors this transition through integrated platforms merging real-time imaging with adaptive radiation delivery. The structural consequence is a capital equipment refresh cycle favoring vendors with imaging-radiation convergence capabilities over legacy cobalt-60 suppliers.
The EU MDR imposes strengthened clinical evidence standards for implantable cranial hardware marketed across European member states. Device manufacturers must now submit expanded clinical data packages for CE marking renewal, inflating regulatory costs and compressing margins for mid-tier suppliers. Cranial implant and neurostimulation segments are responding by consolidating clinical trial operations and prioritizing high-volume SKUs.
Patient preference for single-session ambulatory protocols is displacing multi-fraction radiation and inpatient microsurgical resection in United States tertiary care networks. Integrated skull-base programs at academic medical centers are capturing complex case referrals through bundled pricing and guaranteed facial nerve preservation outcomes. This behavioral shift concentrates demand in certified high-volume centers while marginalizing generalist neurosurgery units.
Global Acoustic Neuroma Market Segmentation
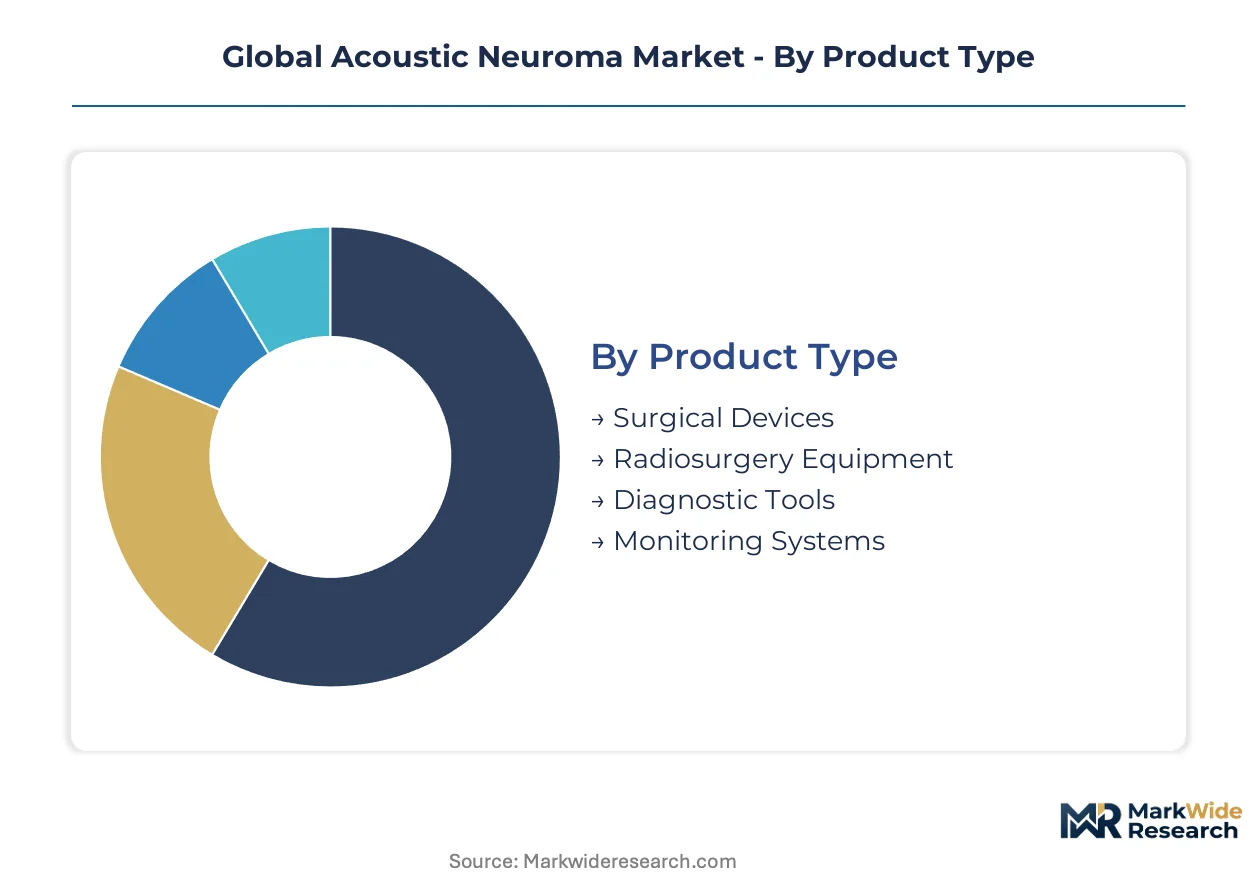
Acoustic neuroma treatment pathways diverge sharply by tumor size, patient age, and hearing preservation goals. Segmentation reveals how capital equipment preferences channel demand toward integrated skull-base programs while pharmacotherapy creates parallel entry points for biologic innovators.
Product Type:
Surgical devices flow through distributor networks serving hospital systems, while radiosurgery equipment sells direct to academic medical centers with dedicated physics staff.
- Surgical Devices:Microsurgical instruments including high-speed drills, ultrasonic aspirators, and nerve integrity monitors enable facial nerve preservation during retrosigmoid and translabyrinthine approaches. Demand concentrates in United States tertiary care networks where bundled reimbursement rewards complete resection outcomes.
- Radiosurgery Equipment:Gamma Knife and CyberKnife platforms deliver single-session stereotactic radiation with submillimeter precision using cobalt-60 or linear accelerator sources. German and Japanese neurosurgery centers are expanding installed base fastest as outpatient shift economics displace inpatient craniotomy volume.
- Diagnostic Tools:MRI protocols with contrast-enhanced T1-weighted sequences and FIESTA/CISS sequences enable submillimeter vestibular nerve visualization.
- Monitoring Systems:Intraoperative facial nerve monitoring and auditory brainstem response systems reduce iatrogenic injury rates during microsurgical resection.
Radiosurgery equipment dominates installed base. Surgical devices are where expansion concentrates.
Therapy Area:
Cost tiers separate acute intervention from surveillance protocols, with pharmacotherapy occupying an emerging premium position for genetically defined patient subsets.
- Microsurgery:Open resection via retrosigmoid, middle fossa, or translabyrinthine routes achieves immediate tumor removal with facial nerve preservation rates exceeding 90% in high-volume centers. United States academic medical centers capture complex case referrals through guaranteed outcome contracts.
- Stereotactic Radiosurgery:Single-session Gamma Knife or fractionated CyberKnife delivery achieves tumor control rates comparable to surgery for lesions under 3 cm with lower cranial neuropathy risk. Japanese and German reimbursement frameworks favor ambulatory delivery, accelerating protocol adoption.
- Observation:Serial MRI surveillance with conservative management applies to elderly patients or small asymptomatic tumors showing minimal growth velocity.
- Pharmacotherapy:Bevacizumab and other targeted agents address neurofibromatosis type 2-associated bilateral disease where surgical morbidity proves prohibitive.
Stereotactic radiosurgery commands the largest patient volume. Pharmacotherapy is climbing the fastest.
End User:
Customer type determines procurement authority, with neurosurgery centers controlling capital budgets above threshold levels while specialty clinics influence device selection through physician preference.
- Neurosurgery Centers:Integrated skull-base programs at academic medical centers combine microsurgical and radiosurgical capabilities under unified governance. These United States, German, and Japanese centers attract complex referrals through bundled pricing and outcome guarantees.
- Specialty Clinics:Gamma Knife-only facilities and standalone radiosurgery centers serve lower-acuity cases with faster scheduling and lower facility fees.
- Research Institutions:NIH-funded centers and university hospitals conduct Phase II trials for NF2 pharmacotherapy and next-generation contouring algorithms.
- Rehabilitation Facilities:Post-treatment vestibular therapy and facial nerve rehabilitation programs address balance dysfunction and synkinesis following surgical or radiation intervention.
Neurosurgery centers dominate procedure volume. Specialty clinics are where expansion concentrates.
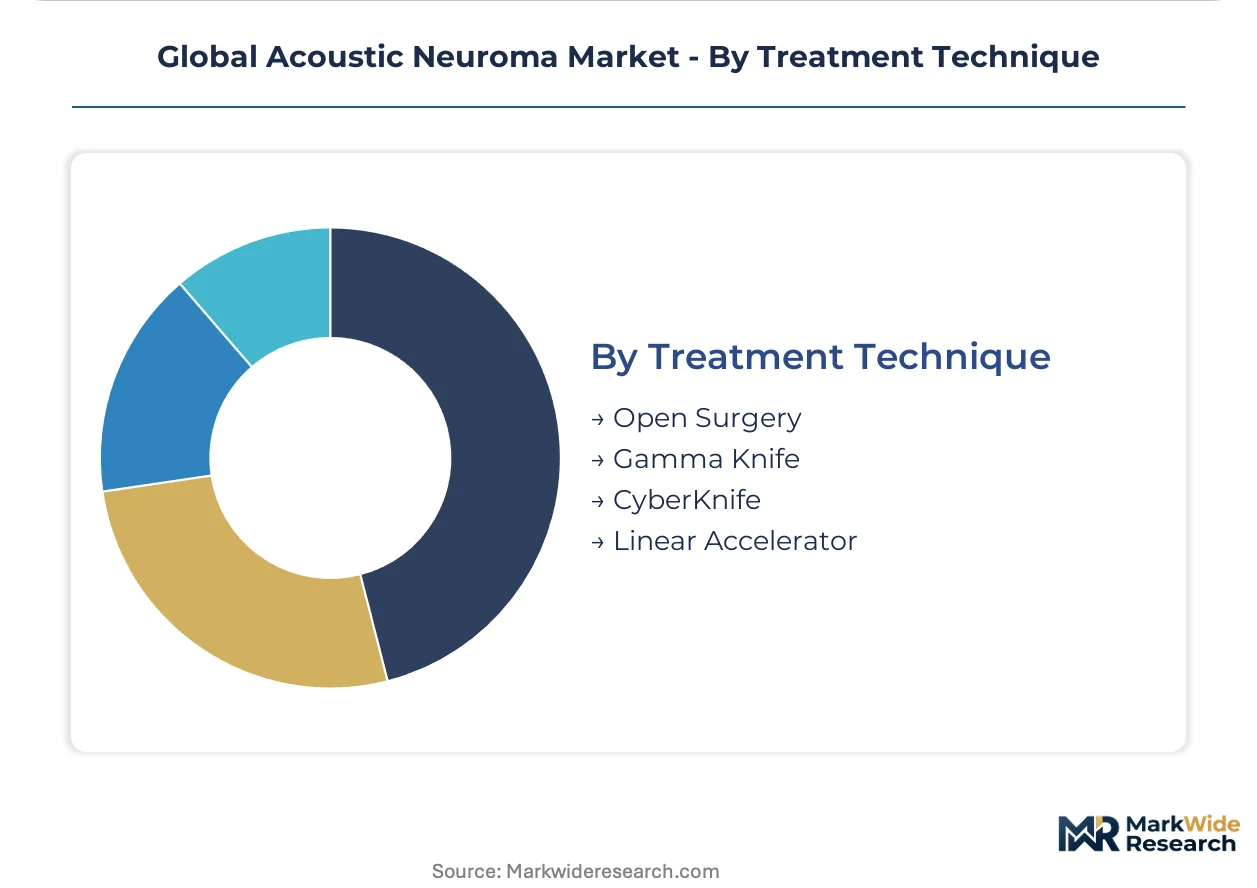
Treatment Technique:
Maturity curves separate established cobalt-60 platforms from emerging linear accelerator systems, with technology refresh cycles driving replacement demand in North American markets.
- Open Surgery:Microsurgical resection via retrosigmoid craniotomy remains the definitive intervention for large tumors exceeding 3 cm or those causing brainstem compression. Fellowship-trained skull-base surgeons in United States academic centers preserve facial nerve function in over 90% of cases.
- Gamma Knife:Elekta's cobalt-60 based Leksell system delivers single-session radiation with 0.15 mm targeting precision through 192 fixed beams. German and Japanese certification standards bifurcate providers into accredited high-precision centers and excluded generalist units.
- CyberKnife:Accuray's robotic linear accelerator enables fractionated treatment for larger lesions or those abutting critical structures with real-time tumor tracking.
- Linear Accelerator:Conventional LINAC-based stereotactic systems with cone-beam CT guidance offer lower capital cost entry points for community hospital programs.
Gamma Knife dominates installed base. Linear accelerator platforms are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net equipment exports from Germany and the United States exceed acoustic neuroma device imports across Japan and emerging markets, concentrating high-value manufacturing in established precision radiation hubs while Asia-Pacific demand absorbs outbound capital shipments.
United States
Integrated skull-base programs at Johns Hopkins, Mayo Clinic, and UCSF Medical Center drive Gamma Knife installation demand. FDA premarket approval pathways compress commercialization timelines for novel radiosurgery platforms. Tertiary care networks in Boston and Houston attract complex case referrals through bundled pricing contracts.
Germany
Charité Berlin and Heidelberg University Hospital anchor stereotactic radiosurgery adoption across Central Europe. EU MDR strengthened clinical evidence standards extend CE marking timelines for implantable cranial hardware. Bavarian and North Rhine-Westphalian neurosurgery centers expand minimally invasive protocol certification.
Japan
Tokyo Women's Medical University and Osaka University Hospital lead CyberKnife utilization for vestibular schwannoma. PMDA superiority-track reimbursement listing conditions create first-mover advantages for device innovators. Kanto and Kansai metropolitan clusters concentrate high-precision radiation capacity.
United Kingdom
NHS England specialized commissioning frameworks channel acoustic neuroma referrals to designated tertiary neuroscience centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards for implantable devices. London and Manchester academic medical centers consolidate skull-base surgical fellowship programs.
Switzerland
University Hospital Zurich and Geneva University Hospital serve as precision radiation referral hubs for Alpine-region patients. Swissmedic maintains stringent clinical evidence requirements for novel surgical navigation systems. Basel and Zurich pharmaceutical clusters support NF2 pharmacotherapy trial infrastructure.
Global Acoustic Neuroma Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment and surgical device segments, producing a bifurcated structure where scale-driven imaging conglomerates face focused precision radiation pure-plays. Tier-one positions cluster around integrated platform vendors with real-time imaging capabilities, while mid-tier surgical navigation specialists defend niche positions through neurophysiological monitoring depth. Two dominant competitive moves define current positioning: M&A activity targeting AI-enabled contouring software assets, and strategic partnerships between cobalt-60 source holders and linear accelerator developers.
Within the precision radiation tier, Elekta and Accuray Incorporated exemplify divergent technological anchoring—Elekta through fixed-source cobalt-60 certification dominance, Accuray through robotic linear accelerator flexibility. Siemens Healthineers AG occupies a position spanning imaging integration across academic medical center procurement cycles. These three entities represent the capital equipment archetype spectrum: legacy source technology, robotic delivery innovation, and converged imaging-radiation platforms.
| Leading Market Players |
|---|
| Medtronic |
| Elekta |
| Siemens Healthineers |
| Accuray Incorporated |
| Natus Medical Incorporated |
| Amgen |
| Pfizer |
| F. Hoffmann-La Roche |
| Novartis AG |
| Others |
Supply & Pricing Matrix
High-volume Gamma Knife installations at academic medical centers in the United States, Germany, and Japan generate scale economies that compress per-procedure costs while elevating price floors for mid-tier community hospitals lacking certification access. This concentration of precision radiation capacity creates asymmetric bargaining power where accredited centers command premium reimbursement rates while generalist neurosurgery units face margin compression from outpatient shift economics.
Pricing Analysis
Industrial OEM buyers anchor equipment procurement through long-term service contracts bundling cobalt-60 source replacement, physics staffing, and maintenance coverage. Pricing stratifies across premium Gamma Knife certification tiers, standard CyberKnife robotic platforms, and economy LINAC-based systems lacking real-time tracking. Cost compression in the standard tier intensifies as Siemens Healthineers and Accuray compete on imaging integration. Academic medical centers demonstrate lowest price sensitivity due to bundled reimbursement frameworks, while standalone specialty clinics face acute margin pressure from payor rate compression.
Supply Chain Analysis
Sweden and the United States anchor cobalt-60 source production and precision radiation platform assembly. Germany supplies high-field MRI magnets and linear accelerator components, while Japan contributes robotic positioning systems and real-time tracking sensors. Raw material dependencies center on high-purity cobalt isotopes, superconducting niobium-titanium wire, and precision-machined tungsten collimators. Single-source vulnerability concentrates in Elekta's proprietary cobalt-60 supply chain. Distribution runs through direct sales forces serving academic medical centers, with aftermarket parts flowing via authorized service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustic neuroma market is emerging from a cyclical trough driven by deferred capital expenditure during healthcare budget constraints, with replacement demand for aging cobalt-60 systems now accelerating across North American and European installed bases.
For Market Incumbents: Shield market position by securing exclusive cobalt-60 supply agreements with radiochemical producers and accelerating FDA premarket approval submissions for next-generation MRI-linear accelerator platforms. Vertical integration into AI-enabled contouring software defends against pure-play algorithm entrants threatening margin capture in treatment planning workflows. For New Entrants and Emerging Players: Differentiate on pharmacotherapy delivery for NF2-associated bilateral disease, where surgical morbidity creates addressable white space absent incumbent dominance. Target Japan's PMDA superiority-track reimbursement pathway for first-mover listing advantages. Pursue hospital system partnerships offering risk-sharing arrangements on facial nerve preservation outcomes. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision radiation platform vendors with captive service contracts and cobalt-60 source replenishment cycles. Long-term viability favors integrated imaging-radiation convergence plays over legacy fixed-source pure-plays. Watch FDA breakthrough device designations for AI-contouring algorithms as inflection signals for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Compresses commercialization timelines for novel radiosurgery platforms entering precision radiation segments. |
| CE Marking Pathway | EU MDR strengthened evidence standards extend timelines but create defensive moats for compliant implantable hardware vendors. |
| Hospital System Partnership | Integrated skull-base programs at academic medical centers capture complex referrals through bundled outcome guarantees. |
| Software Companion Development | AI-enabled contouring algorithms merge with real-time MRI guidance to redefine margin precision without specialist workforce expansion. |
| Reimbursement Strategy | PMDA superiority-track listing in Japan conditions payment on demonstrated standard-of-care advancement. |
Research Methodology
Operator-level perspectives from skull-base neurosurgeons, medical physicists, hospital procurement directors, and GPO contract managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) and PMA filings, PMDA reimbursement listings, EU MDR technical documentation, and hospital equipment procurement databases. Bottom-up installed base modeling and top-down therapy-area spend analysis triangulated market sizing across product type, therapy area, end user, and treatment technique segmentation.
Sensitivity analysis tested forecast robustness across cobalt-60 supply disruption scenarios, regulatory approval timeline variations, and NF2 pharmacotherapy pipeline progression rates. The analytical framework modeled volume and value outputs across the projection horizon by treatment technique maturity, certification tier penetration, and regional reimbursement framework. CAGRs derived from procedure volume growth, equipment replacement cycles, and emerging therapy area adoption curves. Forecast inputs incorporated real-time imaging adoption rates, AI contouring algorithm regulatory clearances, and fellowship-trained surgeon pipeline constraints.
Material uncertainties — regulatory pathway delays, cobalt-60 supply concentration disruptions, and pharmacotherapy trial failures — sit outside the modeled envelope. Forecasts reflect assumptions on outpatient shift velocity, payor bundling expansion, and technology refresh cycle timing. Recalibration cycles align with material shifts in FDA premarket approval timelines, EU MDR implementation enforcement, and Japan PMDA superiority-track listing decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neuroprotection Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Moyamoya Disease Market
Neurology
Optic Neuropathy Management Market
Neurology
Global Neurology Clinical Trials Market
Neurology
United States Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Bell Palsy Treatment Market
Neurology
Chile Neurology Devices Market
Neurology
Arachnoiditis Treatment Market
Neurology
Brazil Neurology Devices Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Sweden Neurology Devices Market
Neurology
Spasticity Treatment Market