
 Peptide Receptor Radionuclide Therapy (PRRT) Market | 2026-2036
Peptide Receptor Radionuclide Therapy (PRRT) Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide Receptor Radionuclide Therapy (PRRT) Market Analytics
Modular dosing protocols paired with companion diagnostic bundling is hardening as the standard commercial configuration, pushing buyers toward integrated therapy packages rather than standalone isotope procurement. Novartis AG leverages its vertically integrated radiopharmaceutical network to control manufacturing from cyclotron to clinic. ITM Isotope Technologies Munich SE anchors European supply security through dedicated isotope production facilities. Eckert & Ziegler AG specializes in radiolabeling infrastructure that sustains downstream therapy availability.
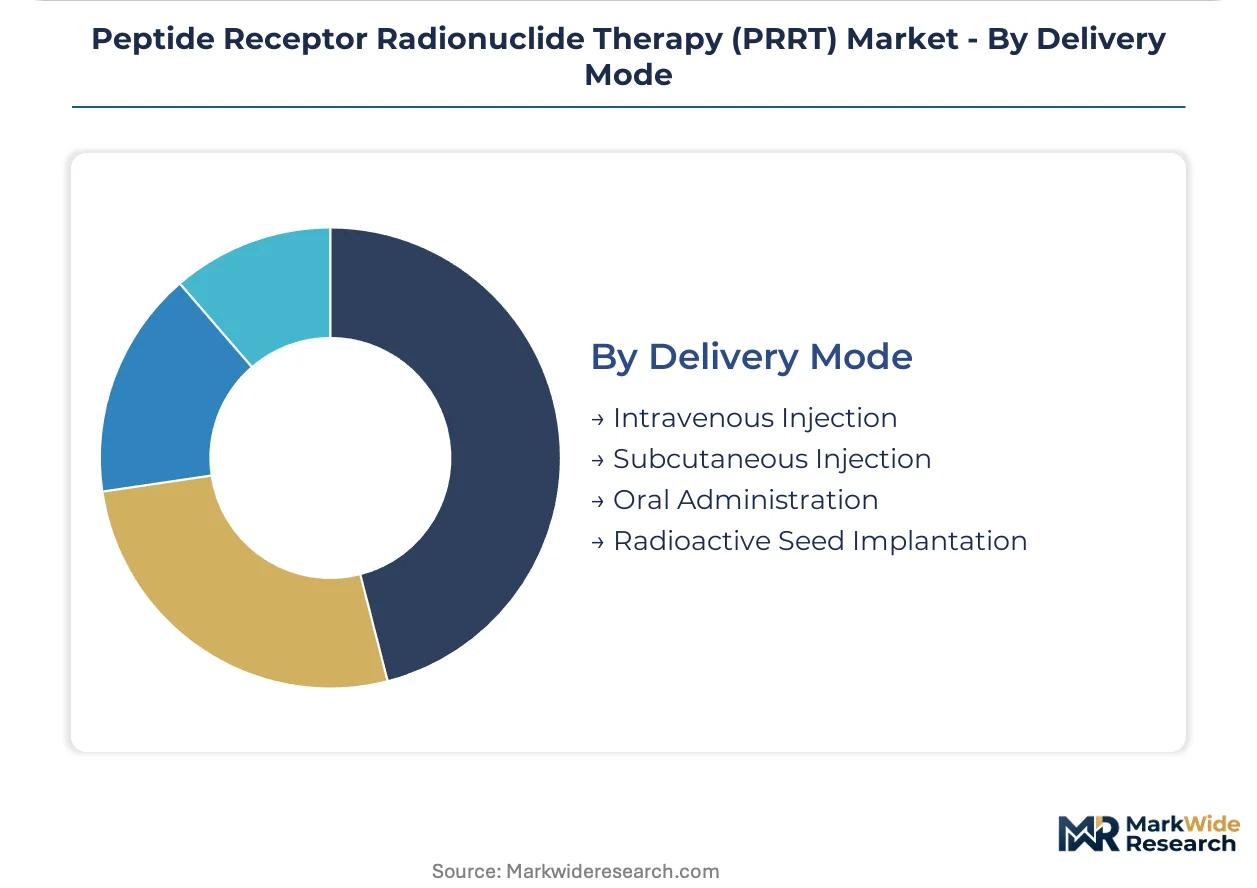
Peptide Receptor Radionuclide Therapy deploys radiolabeled somatostatin analogs, typically lutetium-177 or yttrium-90 conjugated to DOTA-chelated peptides, to deliver targeted beta-particle radiation to somatostatin receptor-expressing tumor cells for cytoreduction in metastatic disease. Therapeutic radiotracers command the dominant value share within product type segmentation due to high isotope costs and complex manufacturing requirements, while diagnostic agents grow fastest as theranostic pairing becomes standard practice. Intravenous injection remains the leading delivery mode, though subcutaneous formulations attract development interest for outpatient administration.
FDA orphan drug and breakthrough therapy designations shape US market access timelines and reimbursement positioning, while EMA's centralized marketing authorization governs European commercialization pathways for radiopharmaceuticals. The EU's F-Gas Regulation and REACH framework constrain isotope production chemistry and cold-chain logistics standards, elevating compliance costs for cross-border distribution. Stakeholders must monitor evolving theranostic reimbursement bundling decisions by national health technology assessment bodies to align portfolio investments with viable payment models.
Market Dynamics
PRRT market structure hardens around theranostic bundling, where diagnostic imaging and therapeutic isotope delivery merge into unified clinical protocols. This integration forces manufacturers to control cyclotron production, radiolabeling, and cold-chain logistics simultaneously.
Growth Catalysts
- FDA Orphan Drug Framework:The designation accelerates regulatory review timelines and secures seven-year market exclusivity for rare neuroendocrine tumor indications. Developers leverage this pathway to compress commercialization cycles.
- Lutetium-177 Production Scale-Up:High-purity no-carrier-added isotope manufacturing is expanding into dedicated reactor facilities. Reactor operators in Belgium and the Netherlands anchor European supply security.
- Oncology Clinic Consolidation:Hospital networks are centralizing nuclear medicine services into specialized theranostic centers. These hubs aggregate patient volumes sufficient to justify dedicated radiopharmacy infrastructure.
Market Restraints
- Isotope Supply Concentration:High-flux reactor capacity clusters in five government-operated facilities worldwide. Any unplanned outage disrupts global lutetium-177 availability for 6-12 months.
- REACH Chemical Compliance:The EU framework imposes registration burdens on DOTA-chelator imports and radiolabeling reagents. Cross-border shipment documentation adds 15-20% to logistics costs.
- Short Half-Life Economics:Lutetium-177's 6.7-day radioactive decay forces just-in-time production. Waste rates exceed 30% for doses not administered within 72 hours of calibration.
Strategic Opportunities
- Subcutaneous Formulation Development:Depot injection technologies promise outpatient administration without infusion center dependency. Formulation specialists are filing INDs for somatostatin analog slow-release matrices.
- Japan Reimbursement Expansion:MHLW price listing for PRRT in gastroenteropancreatic neuroendocrine tumors opens access to 127 million covered lives. Domestic isotope production partnerships with JAEA secure supply autonomy.
- Alpha-Emitter Conjugation:Actinium-225 and lead-212 are expanding into next-generation radiopharmaceutical pipelines. These isotopes deliver higher linear energy transfer for resistant micrometastases.
Industry Challenges
- Radiopharmacist Workforce Scarcity:Compounding sterile radioactive biologics requires dual certification in nuclear pharmacy and aseptic technique. Training programs graduate fewer than 200 specialists annually across OECD markets.
- Cold-Chain Infrastructure Capex:Validated -80°C storage and lead-shielded transport containers demand $2-4 million per distribution hub. Regional distributors defer expansion until patient density justifies fixed cost absorption.
- Theranostic Coding Fragmentation:Separate reimbursement for diagnostic and therapeutic components varies by payer. Bundled payment pilots at CMS create uncertainty for standalone imaging agent pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide Receptor Radionuclide Therapy (PRRT) Market |
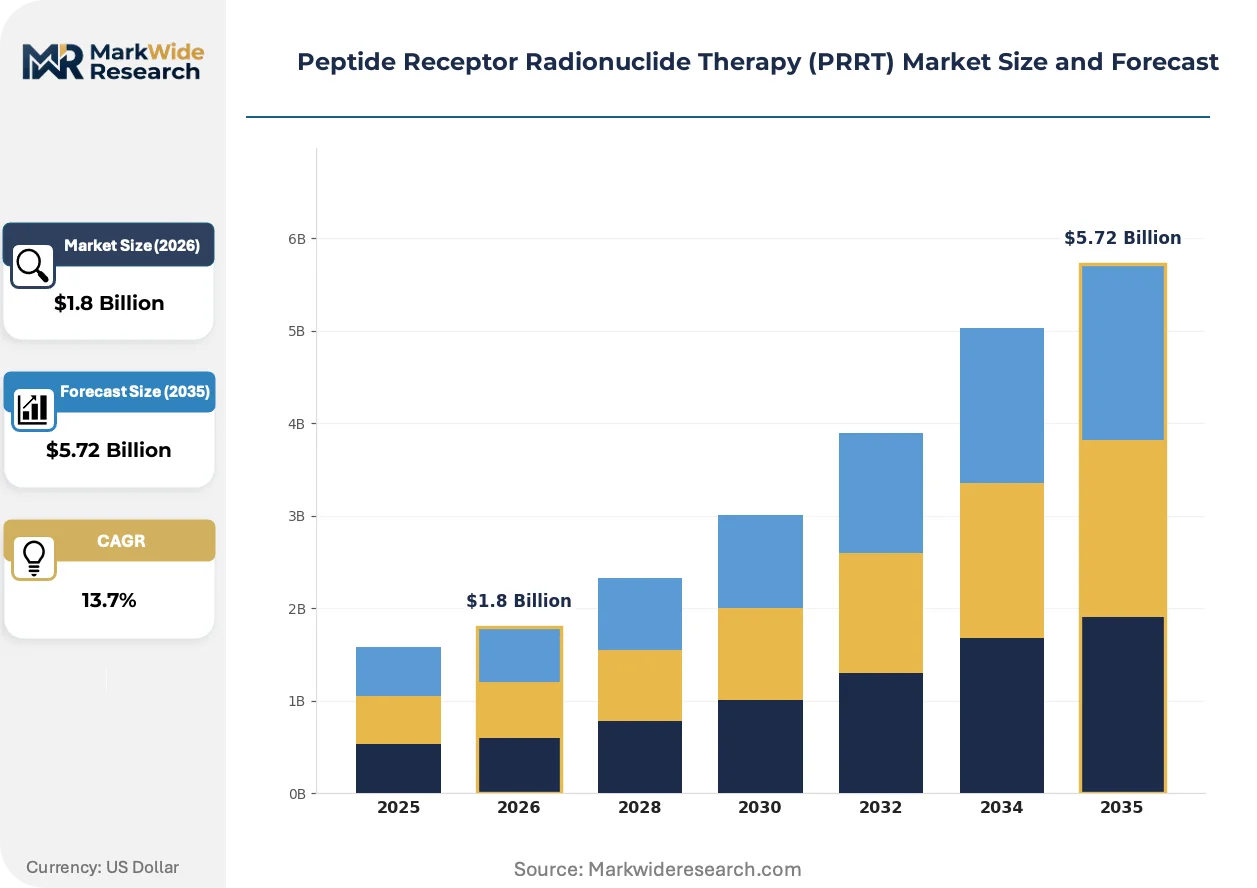
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiolabeled Peptides, Therapeutic Radiotracers, Diagnostic Agents, Combination Therapies End User: Hospital, Oncology Clinics, Research Institutions, Specialized Medical Centers Application: Cancer Treatment, Imaging, Metastatic Disease, Neuroendocrine Tumors Delivery Mode: Intravenous Injection, Subcutaneous Injection, Oral Administration, Radioactive Seed Implantation |
| Companies Covered | Eckert & Ziegler AG, Telix Pharmaceuticals, Novartis AG, Lantheus Holdings, Inc., Radiomedix, Inc., Curium Pharma, Fusion Pharmaceuticals Inc., ABX Advanced Biochemical Compounds, ITM Isotope Technologies Munich SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide Receptor Radionuclide Therapy (PRRT) Market Evolving Landscape
Theranostic convergence is restructuring how clinicians sequence diagnosis and therapy. Radiopharmaceutical developers now design paired agents from discovery, collapsing the historical gap between imaging and treatment tool development.
Alpha-emitting radiolabels are expanding into clinical pipelines previously dominated by beta-emitters. Research hospitals in Germany and Switzerland are adopting actinium-225-DOTATATE for patients progressing after lutetium-177 therapy. This isotope shift is expanding into earlier treatment lines as dosimetry protocols mature.
EMA's centralized marketing authorization for radiopharmaceuticals is harmonizing batch-release standards across member states. The MDR's Annex XVI classification of software-driven dose calculators forces manufacturers to validate algorithm outputs as medical devices. German notified bodies are processing the first combined drug-device marketing applications under this framework.
Hospital procurement departments are consolidating vendor relationships into multi-year radiopharmaceutical supply agreements. Oncology networks in the United States are replacing spot purchasing with guaranteed minimum volume contracts that lock isotope allocation. This contractual shift concentrates purchasing power among the ten largest academic medical center systems.
Peptide Receptor Radionuclide Therapy (PRRT) Market Segmentation
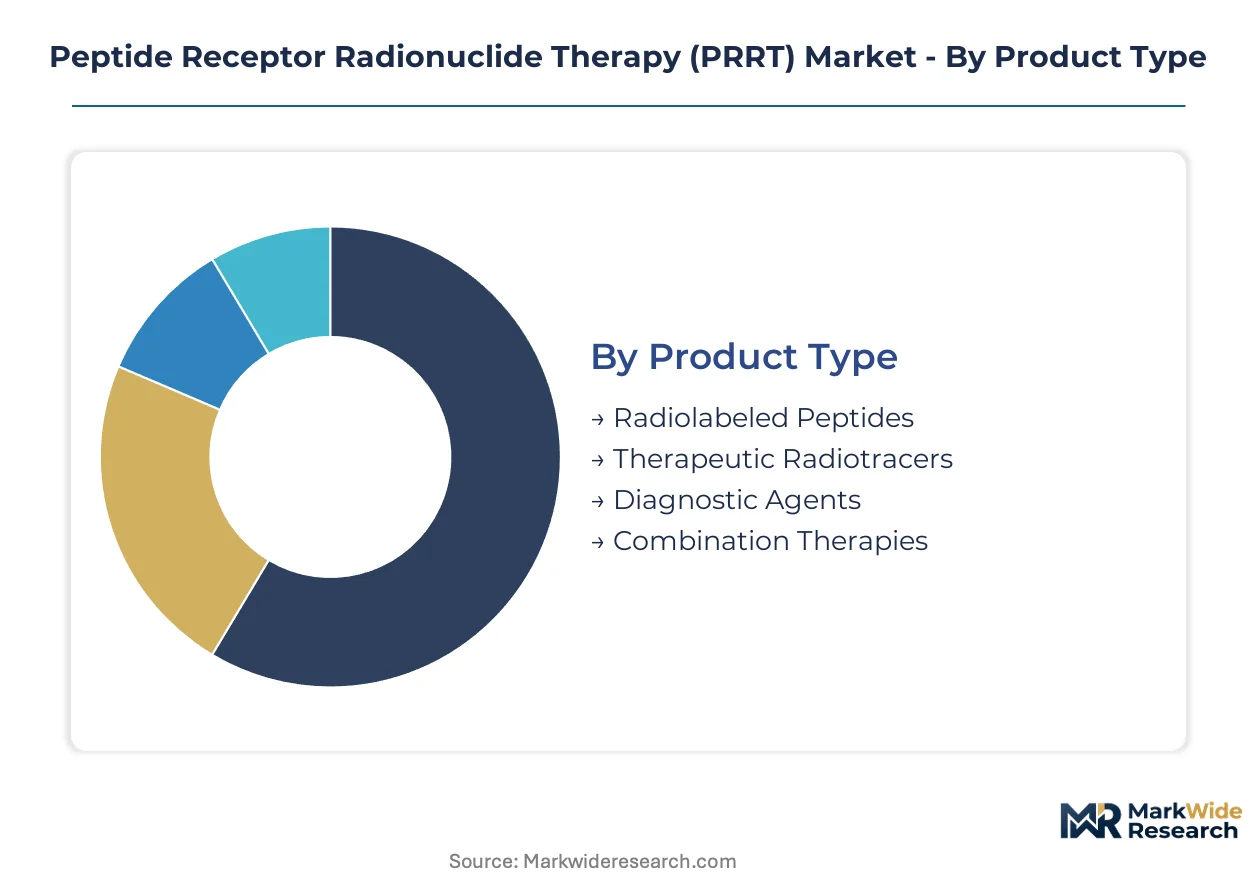
PRRT market segmentation reflects the theranostic convergence reshaping nuclear medicine procurement. Buyers now evaluate diagnostic-therapy pairings as unified systems rather than discrete products, forcing manufacturers to align portfolio breadth with clinical workflow integration.
Product Type:
Supply concentration in high-purity isotope manufacturing determines which product categories command premium positioning and secure hospital formulary placement.
- Therapeutic Radiotracers:Lutetium-177 and yttrium-90 conjugated to DOTA-chelated peptides deliver targeted beta-particle radiation for cytoreduction. Demand concentrates in the United States and Germany where nuclear medicine infrastructure supports just-in-time radiopharmacy compounding.
- Diagnostic Agents:Gallium-68 labeled somatostatin analogs enable PET imaging for patient selection and therapy monitoring. Oncology clinics in Japan are expanding fastest as MHLW reimbursement pathways mature for gastroenteropancreatic tumor staging.
- Radiolabeled Peptides:Synthetic somatostatin analogs with optimized receptor binding affinity serve as the molecular scaffold for both diagnostic and therapeutic conjugation.
- Combination Therapies:Bundled regimens pairing PRRT with chemotherapy or immunotherapy are entering investigator-initiated trials at research institutions.
Today's leader: Therapeutic Radiotracers. Tomorrow's challenger: Diagnostic Agents.
End User:
Capital intensity requirements for cyclotron infrastructure and radiopharmacy certification are concentrating patient volumes among facilities with sufficient scale to absorb fixed costs.
- Oncology Clinics:Specialized theranostic centers aggregate neuroendocrine tumor caseloads sufficient to justify dedicated Lu-177 production partnerships. Hospital networks in the United States are consolidating nuclear medicine services into these hubs.
- Hospital:Academic medical centers with in-house cyclotron facilities control the full manufacturing chain from isotope production to patient administration.
- Specialized Medical Centers:European reference centers in Belgium and the Netherlands leverage proximity to high-flux reactors for supply security.
- Research Institutions:German and Swiss university hospitals are pioneering actinium-225-DOTATATE protocols for patients progressing after lutetium-177 therapy.
Volume concentrates at Oncology Clinics. Margin protection sits with Hospital systems.
Application:
Clinical evidence accumulation and regulatory pathway clarity are determining which indications attract manufacturer investment and payer coverage.
- Neuroendocrine Tumors:Well-differentiated gastroenteropancreatic and bronchial neuroendocrine tumors constitute the established indication with mature reimbursement. FDA orphan drug designation accelerates developer incentives for rare tumor subtypes.
- Metastatic Disease:Cytoreductive applications in liver-dominant metastases are expanding as dosimetry protocols enable personalized dosing.
- Cancer Treatment:Broader solid tumor applications remain investigational, with early-phase trials exploring somatostatin receptor expression in pancreatic and small-cell lung cancers.
- Imaging:Diagnostic staging and response assessment represent the fastest-expanding application as theranostic pairing becomes standard clinical practice.
Revenue anchors at Neuroendocrine Tumors. Pipeline momentum favors Metastatic Disease protocols.
Delivery Mode:
Administration complexity and facility dependency are shaping competitive differentiation between infusion-based and outpatient-capable formulations.
- Intravenous Injection:Infusion center administration remains the standard delivery mode, requiring specialized nuclear medicine suites with radiation shielding and waste handling infrastructure.
- Subcutaneous Injection:Depot formulation technologies promise outpatient administration without infusion center dependency. Formulation specialists are filing INDs for slow-release somatostatin analog matrices.
- Oral Administration:No clinically validated oral radiopharmaceutical formulations exist; gastrointestinal radiolysis and chelator stability barriers remain unresolved.
- Radioactive Seed Implantation:Brachytherapy-derived delivery modes are not commercially applied in PRRT; preclinical research explores intratumoral injection for resistant micrometastases.
Standard of care: Intravenous Injection. Development priority: Subcutaneous Injection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PRRT's commercial foundations trace to German and Swiss research hospitals that pioneered somatostatin receptor-targeted radiotherapy in the 1990s. These institutions established the clinical protocols and regulatory precedents that later shaped FDA and EMA approval pathways.
United States
Oncology clinic networks in Houston and Boston aggregate sufficient neuroendocrine tumor volumes to justify dedicated Lu-177 production partnerships. FDA's orphan drug designation compresses review timelines for rare tumor subtypes. MD Anderson Cancer Center anchors theranostic protocol development for metastatic disease applications.
Germany
University hospitals in Munich and Heidelberg pioneered actinium-225-DOTATATE protocols for patients progressing after lutetium-177 therapy. EMA's centralized marketing authorization harmonizes batch-release standards across member states. The Bavarian cluster around ITM Isotope Technologies anchors European isotope supply security through dedicated reactor partnerships.
Japan
MHLW price listing for gastroenteropancreatic neuroendocrine tumors opened reimbursement access to 127 million covered lives. Domestic isotope production partnerships with JAEA secure supply autonomy against import disruption. Tokyo and Osaka academic medical centers are expanding PET imaging capacity for diagnostic staging applications.
Belgium
BR2 and HFR research reactors in Mol anchor global no-carrier-added lutetium-177 production capacity. ANSM's radiopharmaceutical licensing framework enables cross-border distribution into France and the Netherlands. The Brussels-Leuven corridor concentrates radiopharmacy compounding expertise for Benelux hospital networks.
Switzerland
Swissmedic's streamlined marketing authorization attracts radiopharmaceutical developers seeking rapid European market entry. University Hospital Zurich and Geneva University Hospital pioneer dosimetry protocols for personalized dosing. The Basel-Zurich corridor concentrates pharmaceutical manufacturing infrastructure for radiolabeled peptide production.
Peptide Receptor Radionuclide Therapy (PRRT) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across isotope purity grades and cyclotron proximity to treatment centers. The market structure hardens around three tiers: vertically integrated pharmaceutical conglomerates controlling full manufacturing chains, specialized isotope producers with reactor access, and regional radiopharmacy service providers handling last-mile compounding. Strategic moves concentrate on securing long-term reactor supply agreements and acquiring companion diagnostic capabilities to complete theranostic bundling.
Among European-based isotope specialists, ITM Isotope Technologies Munich SE and Eckert & Ziegler AG exemplify contrasting archetypes: the former anchors dedicated production facility investments while the latter occupies a position in radiolabeling infrastructure provision. Novartis AG represents the integrated pharmaceutical tier with backward integration into cyclotron networks. These three entities collectively illustrate how competitive positioning depends on controlling distinct value chain segments rather than competing directly across all activities.
| Leading Market Players |
|---|
| Eckert & Ziegler AG |
| Telix Pharmaceuticals |
| Novartis AG |
| Lantheus Holdings, Inc. |
| Radiomedix, Inc. |
| Curium Pharma |
| Fusion Pharmaceuticals Inc. |
| ABX Advanced Biochemical Compounds |
| ITM Isotope Technologies Munich SE |
| Others |
Value Network & Pricing Analysis
Lutetium-177 spot pricing indices cascade through the PRRT value chain into three distinct procurement tiers: academic medical centers with captive reactor partnerships command standard-cost allocation, while regional oncology clinics without direct isotope contracts absorb 15-20% premiums for third-party radiopharmacy compounding. This cost stratification hardens around half-life economics, where doses unused within 72 hours of calibration convert to radioactive waste.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs PRRT procurement, with differentiation driven by isotope purity grade and cold-chain service bundling. Premium tiers attach dedicated logistics support and dosimetry consultation. Pricing pressure stems from oncology clinic consolidation into theranostic hubs that aggregate volume for contract negotiation leverage. Community hospitals without nuclear medicine infrastructure exhibit highest price sensitivity; academic centers with in-house cyclotrons demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in Japan's MHLW reimbursement framework are reshaping sourcing patterns toward JAEA-partnered production facilities and away from Belgian and Dutch import dependency. High-purity no-carrier-added lutetium-177 production concentrates in Belgium, the Netherlands, and Russia's remaining research reactor capacity. Supply chains rest on DOTA-chelator imports from specialized chemical manufacturers and sterile peptide synthesis capacity. Single-source vulnerability clusters around the five government-operated high-flux reactors worldwide. Distribution runs through validated -80°C cold-chain networks with lead-shielded transport containers to regional radiopharmacy hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PRRT market entry rewards geographic arbitrage between the United States' premium reimbursement environment and Japan's expanding MHLW price listing, where regulatory pathway costs diverge by approximately 40% for equivalent clinical evidence packages.
For Market Incumbents: Lock in long-term reactor supply agreements with BR2 or HFR facilities before capacity allocation tightens. Secure companion diagnostic capabilities through licensing partnerships to complete theranostic bundling against emerging radiopharmaceutical developers. Capacity addition in Japan through JAEA partnerships offers defensive positioning against supply disruption threats. For New Entrants and Emerging Players: Alpha-emitter conjugation technologies offer technology-first wedge positioning for patients progressing after lutetium-177 therapy, a white-space target with minimal competitive saturation. Subcutaneous depot formulations for outpatient administration represent the most penetrable delivery mode segment. Go-to-market execution should prioritize German university hospital investigator-initiated trial partnerships to generate clinical evidence before FDA submission. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized isotope producers with confirmed reactor access and radiolabeling infrastructure assets. Long-term viability across the 5-10 year window favors entities with backward integration into cyclotron networks rather than pure-play peptide synthesis houses. Watch FDA breakthrough therapy designation velocity as the inflection indicator for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Supply Agreement | Secures no-carrier-added lutetium-177 allocation from BR2 or HFR facilities against global shortage risk. |
| Companion Diagnostic Licensing | Completes theranostic bundling with gallium-68 PET imaging agents for patient selection protocols. |
| Subcutaneous Formulation IND | Enables outpatient administration without infusion center dependency, expanding addressable clinic base. |
| Alpha-Emitter Pipeline Expansion | Positions for actinium-225-DOTATATE commercialization in post-lutetium-177 progression settings. |
| Japanese MHLW Price Listing | Opens reimbursement access to 127 million covered lives through domestic isotope production partnerships. |
Research Methodology
Multiple input streams — structured interviews with nuclear medicine department heads, regulatory affairs specialists at radiopharmaceutical developers, and hospital procurement managers — were reconciled against secondary validation from FDA orphan drug filings, EMA centralized marketing authorization submissions, and MHLW reimbursement bulletins. Bottom-up patient volume modeling across oncology clinics and academic medical centers was triangulated with top-down isotope production capacity assessments from research reactor operators.
Data-stream reconciliation applied treatment line, delivery mode, and regional regulatory cluster segmentation across the projection horizon. CAGRs were derived from installed base expansion of theranostic centers and reimbursement pathway maturation trajectories. Forecast inputs incorporated half-life waste economics, cyclotron capacity buildout announcements, and radiopharmacist workforce graduation rates from OECD training programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unplanned research reactor outages, REACH chemical compliance cost escalation, and theranostic coding bundling decisions by CMS. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market