
 Arachnoid Cysts Treatment Market | 2026-2036
Arachnoid Cysts Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Arachnoid Cysts Treatment Market Analysis
Asset-light leasing models for neurosurgical implant inventories are fragmenting competitive access across mid-tier hospitals that previously relied on capital-intensive procurement. Medtronic leverages its broad neurosurgery portfolio to sustain high R&D intensity across shunt and endoscopic systems. Johnson & Johnson anchors its position through DePuy Synthes and its specialized cranial access instrumentation. Christoph Miethke GmbH & Co. KG differentiates via precision programmable valve technology that commands premium positioning in European and Asian markets.
Arachnoid cysts treatment encompasses cerebrospinal fluid diversion, pharmacological management, and neurosurgical intervention for benign intracranial or spinal fluid-filled sacs arising from arachnoid membrane splitting, typically requiring intracranial pressure monitoring between 5-15 mmHg for procedural guidance. The primary purpose is to prevent neurological deficit progression, seizure onset, or hydrocephalus development in symptomatic patients. Surgery and drainage modalities capture the deepest margin pools due to implantable device dependency and repeat intervention requirements. Pediatric application demand outpaces adult segments owing to congenital presentation prevalence and early intervention protocols. Hospitals and specialized care centers dominate end-user throughput because arachnoid cyst procedures require intraoperative neuromonitoring and intensive care unit capacity.
FDA premarket notification pathways and the EU Medical Device Regulation shape product standards for cerebrospinal fluid shunts, with both frameworks demanding biocompatibility validation and long-term implant performance data. Japan's PMDA enforces stringent clinical evidence requirements for neurosurgical devices that filter market entrants without domestic trial infrastructure. Stakeholders must monitor evolving reimbursement coding for minimally invasive endoscopic fenestration versus shunt placement across Medicare, NHS England, and German statutory health insurance structures.
Market Dynamics
Minimally invasive endoscopic fenestration protocols are compressing average hospitalization duration for arachnoid cyst interventions. This procedural shift is restructuring capital allocation across tertiary neurosurgical centers toward single-use disposable instrumentation and intraoperative navigation suites.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for novel cerebrospinal fluid diversion technologies compress commercialization timelines from 36 to 18 months in the United States.
- Pediatric Early Intervention Protocols:Congenital presentation screening mandates in German statutory health insurance structures expand addressable procedure volumes for asymptomatic cyst detection.
- Programmable Valve Technology:Precision pressure-adjustable shunt systems enable patient-specific intracranial pressure management without revision surgery.
Market Restraints
- Silicone Biocompatibility Validation:Long-term implant performance data requirements under EU Medical Device Regulation extend development cycles by 24-36 months.
- Specialized Neurosurgeon Concentration:Fellowship-trained pediatric neurosurgeons cluster in 12 metropolitan US hospital systems, creating access bottlenecks for rural referral networks.
- Pharmacological Substitution:Acetazolamide and diuretic management protocols delay surgical intervention in stable adult presentations.
Strategic Opportunities
- Asset-Light Leasing Models:Implant inventory financing programs unlock mid-tier hospital participation without capital-intensive procurement.
- Telemedicine-Enabled Triage:Remote neurology consultations filter urgent versus surveillance cases in Japanese prefectural health systems.
- CE Marking Mutual Recognition:Streamlined conformity assessment pathways facilitate parallel entry into Swiss and Norwegian markets.
Industry Challenges
- Intraoperative Neuromonitoring Certification:EEG and somatosensory evoked potential technician shortages constrain operating room throughput in regional medical centers.
- ICU Step-Down Capacity:Post-operative intracranial pressure monitoring requires dedicated neurocritical care beds that compete with stroke and trauma admissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arachnoid Cysts Treatment Market |
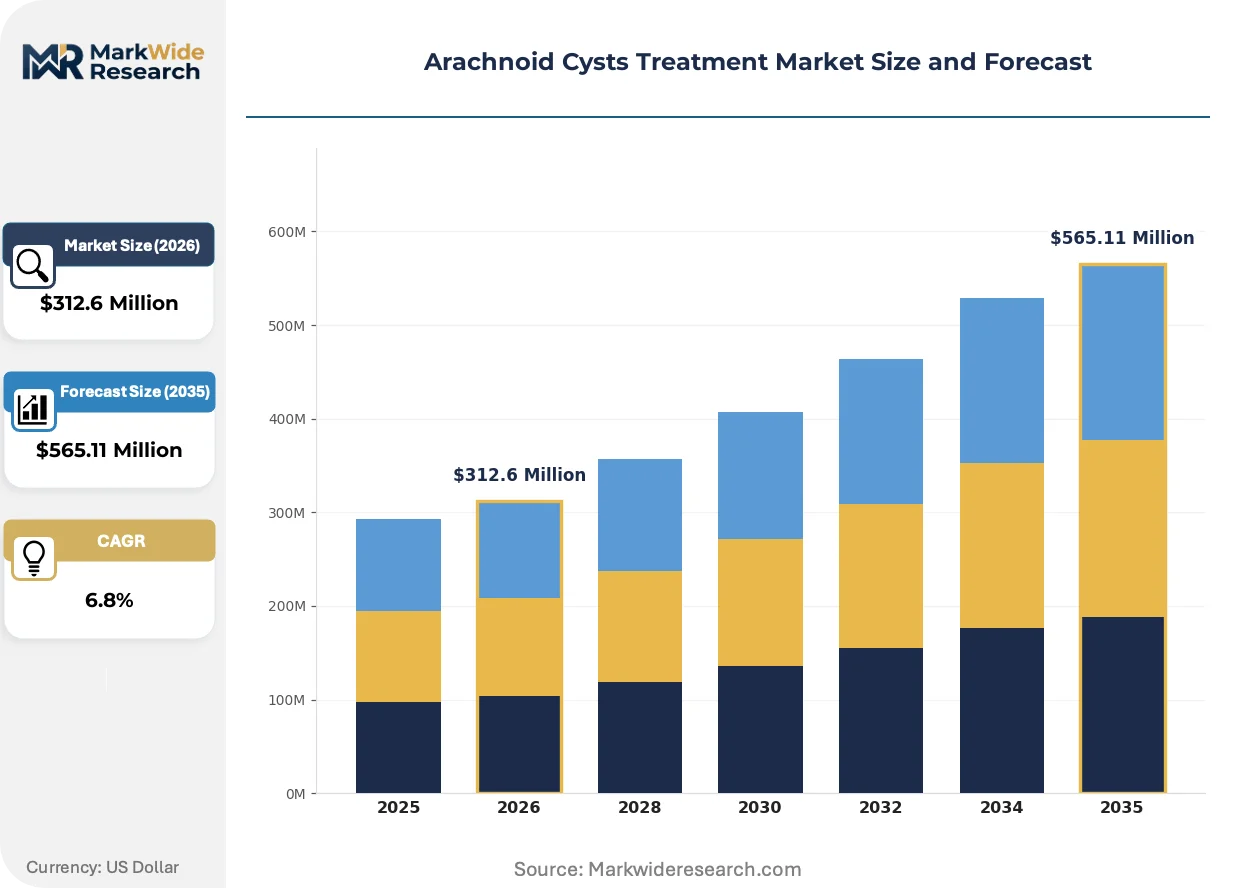
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Medication, Surgery, Observation, Drainage Application: Pediatric, Adult, Neurological Disorders, Emergency Care End User: Hospitals, Clinics, Specialized Care Centers, Research Institutions Delivery Mode: Injectables, Oral, Intravenous, Topical |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun, DePuy Synthes, Sophysa, Christoph Miethke GmbH & Co. KG, Boston Scientific, Spiegelberg GmbH & Co. KG, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arachnoid Cysts Treatment Market Emerging Trajectories
Digital surgical planning platforms are restructuring preoperative workflow efficiency for fenestration procedures. This technological infusion is compressing variation in operative time and reducing revision rates across high-volume centers.
Intraoperative magnetic resonance imaging guidance systems are virtualizing traditional neuronavigation boundaries for deep cyst localization. Pediatric neurosurgical units at Boston Children's Hospital and Great Ormond Street Hospital deploy these platforms for suprasellar and posterior fossa approaches. The technology is virtualizing conventional frame-based stereotaxy into real-time imaging feedback loops that eliminate registration drift.
Japan's PMDA revised clinical evidence requirements for neurosurgical devices in 2023, mandating domestic trial infrastructure for novel shunt materials. This regulatory friction filters market entrants without established investigator networks in Tokyo or Osaka medical centers. Programmable valve manufacturers are responding through joint development agreements with Japanese university hospitals to satisfy post-market surveillance obligations.
Hospital procurement committees are unbundling device procurement from service contracts for shunt systems. Specialized care centers in Germany and the United States now negotiate implant costs separately from programming and troubleshooting support. This behavioral shift is most visible in NHS England's recent framework agreements that separate valve hardware from specialist nurse training programs.
Arachnoid Cysts Treatment Market Segmentation
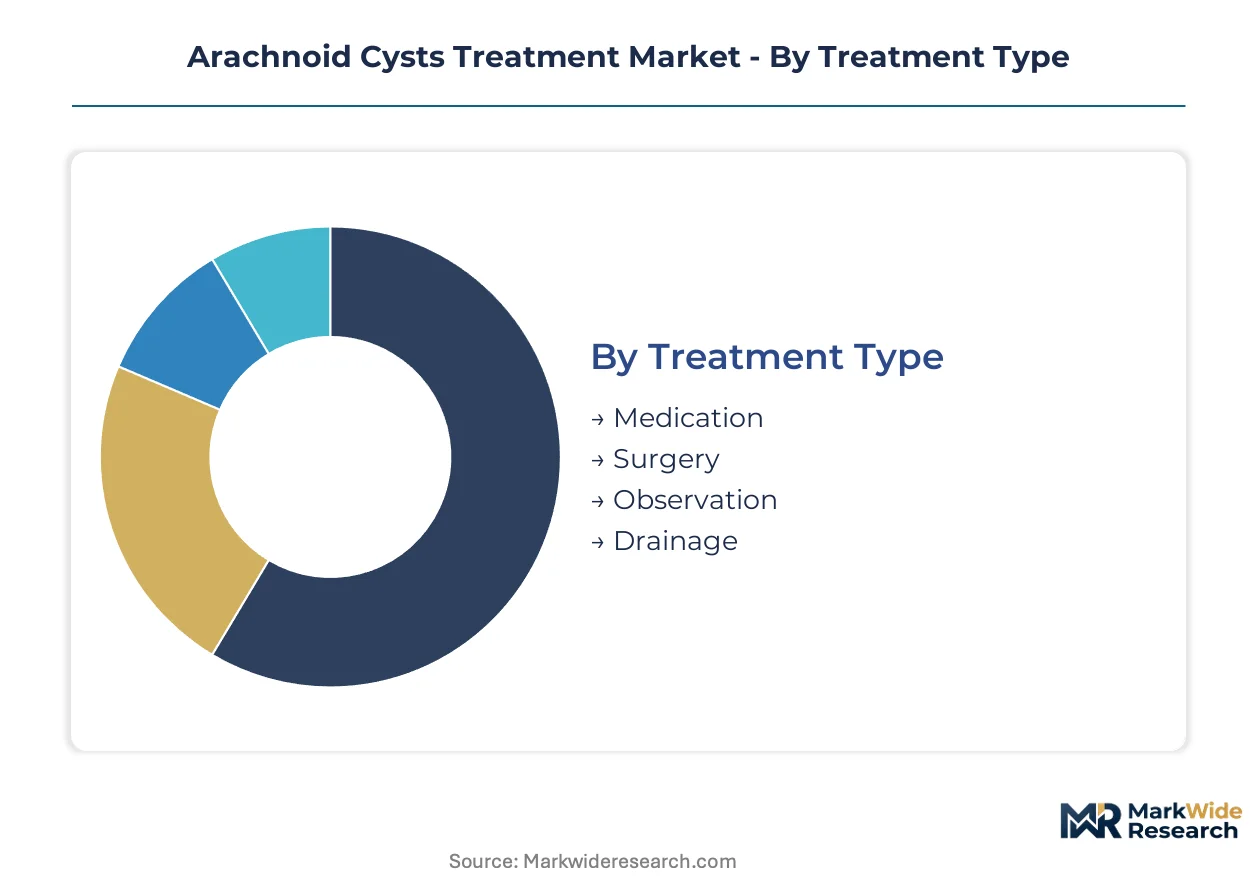
Segmentation reveals how arachnoid cysts treatment markets stratify across intervention intensity, patient acuity, and care setting economics. Each dimension carries distinct margin profiles, regulatory pathways, and capacity constraints that shape commercial strategy.
Treatment Type:
The use-case spectrum spans watchful surveillance through invasive neurosurgical intervention, with selection hinging on cyst location, symptom progression, and intracranial pressure dynamics.
- Surgery:Craniotomy and endoscopic fenestration procedures command premium positioning through implantable shunt dependency and repeat intervention requirements. German tertiary hospitals and US metropolitan pediatric centers concentrate demand for programmable valve systems that enable non-invasive pressure adjustment.
- Drainage:Cerebrospinal fluid diversion via ventriculoperitoneal or cystoperitoneal shunting addresses refractory cases with persistent mass effect. Japanese university hospitals drive adoption of magnetic resonance imaging-compatible programmable valves under PMDA post-market surveillance frameworks.
- Medication:Acetazolamide and diuretic protocols manage stable presentations without surgical candidacy.
- Observation:Surveillance protocols dominate asymptomatic incidental findings detected through expanded neuroimaging access.
Established volume favors Surgery; emerging adoption favors Observation.
Application:
Patient demographics segment sharply across congenital versus acquired presentation patterns, with age-specific protocols driving divergent technology requirements.
- Pediatric:Congenital arachnoid cysts detected through prenatal ultrasound or early childhood neuroimaging mandate early intervention protocols to prevent developmental delay. German statutory health insurance screening mandates and US referral networks at Boston Children's Hospital, Children's Hospital of Philadelphia, and Cincinnati Children's Hospital Medical Center concentrate procedure volume.
- Adult:Symptomatic de novo or progressive cysts present with headache, seizure, or focal neurological deficit requiring individualized surgical planning. Stable adult presentations frequently encounter pharmacological substitution that delays operative intervention.
- Neurological Disorders:Cysts comorbid with epilepsy or hydrocephalus require integrated management approaches.
- Emergency Care:Acute decompensation with herniation risk demands immediate surgical decompression.
Pediatric captures deepest margin pools; Adult presents volume scale.
End User:
Care setting infrastructure determines access to intraoperative neuromonitoring, neurocritical care capacity, and specialized neurosurgical expertise.
- Hospitals:Tertiary academic medical centers with dedicated pediatric neurosurgical units perform complex fenestration and shunt procedures requiring intraoperative magnetic resonance imaging and frameless neuronavigation. Twelve metropolitan US hospital systems cluster fellowship-trained pediatric neurosurgeons, creating access bottlenecks for rural referral networks.
- Specialized Care Centers:Dedicated neurological institutes concentrate high-volume caseloads that justify capital investment in navigation suites and disposable instrumentation. NHS England framework agreements and German statutory health insurance structures increasingly unbundle device procurement from service contracts at these facilities.
- Clinics:Outpatient settings manage surveillance protocols and post-operative valve programming.
- Research Institutions:Academic centers conduct clinical trials for novel shunt materials and programmable valve technologies.
Hospitals anchor procedure volume; Specialized Care Centers gain share through focused expertise.
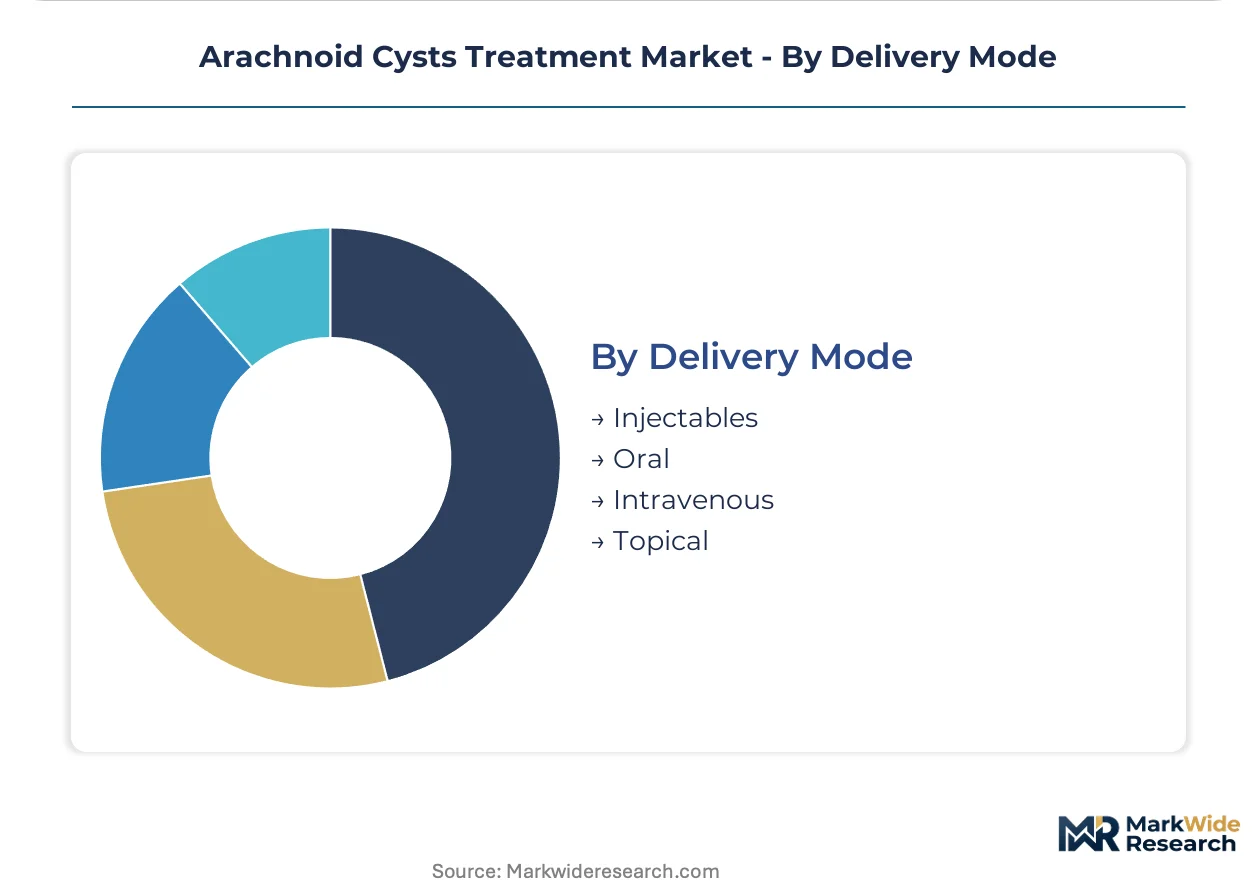
Delivery Mode:
Pharmacological administration routes align with treatment setting constraints and patient acuity levels.
- Oral:Acetazolamide tablets enable outpatient management of stable intracranial pressure without hospitalization.
- Intravenous:Acute perioperative administration supports fluid management and electrolyte balance.
- Injectables:Intrathecal or intra-cystic interventions remain investigational with limited commercial penetration.
- Topical:No established therapeutic application in arachnoid cyst management.
Oral dominates ambulatory pharmacological management; Intravenous supports surgical episode care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough pathways and German statutory screening mandates concentrate neurosurgical device demand in developed health systems with established pediatric referral networks. National regulators enforce divergent evidence standards that filter market entry and shape commercialization timelines.
United States
Tertiary pediatric neurosurgical units at Boston Children's Hospital and Children's Hospital of Philadelphia drive programmable valve adoption for congenital presentations. FDA premarket notification pathways demand biocompatibility validation and long-term implant performance data for cerebrospinal fluid shunts. Twelve metropolitan hospital systems cluster fellowship-trained pediatric neurosurgeons, creating access bottlenecks for rural referral networks.
Germany
Statutory health insurance screening mandates for asymptomatic cyst detection expand addressable procedure volumes in pediatric populations. CE marking under EU Medical Device Regulation enforces stringent silicone biocompatibility validation that extends development cycles. University hospitals in Berlin and Munich anchor high-volume fenestration caseloads with dedicated intraoperative magnetic resonance imaging suites.
Japan
PMDA post-market surveillance frameworks drive adoption of magnetic resonance imaging-compatible programmable valves at Tokyo and Osaka university hospitals. Revised 2023 clinical evidence requirements mandate domestic trial infrastructure for novel shunt materials. Joint development agreements with Japanese university hospitals satisfy regulatory obligations for foreign manufacturers.
United Kingdom
NHS England framework agreements increasingly unbundle device procurement from specialist nurse training programs at dedicated neurological institutes. Great Ormond Street Hospital deploys intraoperative magnetic resonance imaging guidance for suprasellar and posterior fossa approaches. Regional concentration of pediatric neurosurgical expertise in London and Manchester shapes referral patterns.
Switzerland
Swissmedic streamlined conformity assessment pathways facilitate parallel market entry alongside EU CE marking for neurosurgical device manufacturers. University Hospital Zurich and Geneva University Hospitals concentrate fenestration expertise with frameless neuronavigation capabilities. Premium reimbursement structures support precision programmable valve positioning in pediatric interventions.
Arachnoid Cysts Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments. The vendor base stratifies between diversified medical technology conglomerates with broad neurosurgery portfolios and focused precision valve manufacturers with premium positioning. Three archetypes dominate: diversified conglomerates leveraging cross-selling infrastructure, programmable valve specialists commanding premium pricing, and mid-tier leasing-enabled distributors unlocking capital-constrained hospitals. Competitive moves concentrate on unbundling service contracts from hardware procurement and establishing joint development agreements for regulatory compliance.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson occupy positions sustained by broad neurosurgery portfolios and specialized cranial access instrumentation. Christoph Miethke GmbH & Co. KG exemplifies the precision programmable valve specialist archetype with premium positioning in European and Asian markets. Sophysa and Spiegelberg GmbH & Co. KG represent mid-tier European manufacturers navigating unbundled procurement frameworks.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun |
| DePuy Synthes |
| Sophysa |
| Christoph Miethke GmbH & Co. KG |
| Boston Scientific |
| Spiegelberg GmbH & Co. KG |
| Integra LifeSciences |
| Others |
Supply Flow & Price Mechanics
Single-source silicone biocompatibility validation under EU Medical Device Regulation creates regulatory chokepoint exposure that widens pricing spreads between CE-marked premium shunt systems and standard-grade alternatives while compressing supplier choice for mid-tier hospitals.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus standard ISO) creates the primary spread between programmable valve tiers. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and programming support intensity. Cost compression in the standard tier is intensifying because German statutory health insurance unbundling separates hardware from specialist nurse training. Mid-tier hospitals with capital constraints exhibit highest price sensitivity; pediatric tertiary centers with dedicated neurosurgical units demonstrate lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Contract manufacturing for silicone shunt components concentrates among German precision polymer processors and Swiss medical device foundries. Raw material flows draw from medical-grade silicone suppliers in Germany, titanium forging specialists in the United States, and magnetic resonance imaging-compatible ceramic manufacturers in Japan. Single-source vulnerability runs through EU-notified body capacity for biocompatibility testing. Distribution runs through specialized neurosurgical device distributors serving hospital procurement committees and GPO contract managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programming and troubleshooting service contracts represent the fastest-expanding recurring-revenue layer, outpacing hardware sales growth as NHS England and German insurers unbundle procurement from training support.
For Market Incumbents: Build regulatory data moats through long-term implant performance registries that satisfy FDA and PMDA post-market surveillance obligations. Deepen backward integration into medical-grade silicone compounding to secure supply continuity against EU MDR testing bottlenecks. Acquire specialized neuromonitoring technician training capabilities to defend hospital service contract renewals. For New Entrants and Emerging Players: Mid-tier Japanese prefectural hospitals without Tokyo-Osaka investigator networks represent the most penetrable entry point for magnetic resonance imaging-compatible programmable valves. Asset-light leasing programs for implant inventories unlock capital-constrained German community hospitals excluded from high-volume academic procurement. Partner with regional medical device distributors possessing existing neurosurgical relationships rather than building direct sales infrastructure. For Investors and Strategic Acquirers: PMDA's 2023 domestic trial infrastructure mandate reshapes the acquisition landscape toward Japanese university hospital joint ventures as regulatory compliance vehicles. Five-to-ten-year viability hinges on programmable valve technology platforms with software companion development roadmaps. Target precision valve specialists with established CE marking and FDA breakthrough device designation pipelines. Monitor FDA breakthrough device approval velocity as inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR silicone biocompatibility validation unlocks German statutory insurance reimbursement access. |
| Hospital System Partnership | Boston Children's and Cincinnati Children's referral networks concentrate pediatric programmable valve demand. |
| Software Companion Development | Remote valve programming applications satisfy unbundled procurement frameworks in NHS England. |
| Reimbursement Strategy | Medicare coding alignment for endoscopic fenestration versus shunt placement determines procedure economics. |
| Joint Development Agreement | Tokyo and Osaka university hospital collaborations satisfy PMDA post-market surveillance obligations. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR technical documentation, and PMDA approval databases preceded structured interviews with pediatric neurosurgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, NHS England framework agreements, and German statutory health insurance procedure volumes. Bottom-up procedure volume estimates triangulated against top-down market value assessments across treatment type, application, and end-user segments.
Fixed assumptions held regulatory approval timelines and reimbursement coding structures constant across the projection horizon, while varying pediatric early intervention protocol adoption rates and minimally invasive endoscopic fenestration penetration. Segmentation dimensions modeled encompassed treatment intensity, patient acuity, care setting infrastructure, and regional regulatory cluster. CAGRs derived from procedure volume growth trajectories weighted by implantable device dependency and repeat intervention frequency. Forecast inputs incorporated intraoperative magnetic resonance imaging suite deployment rates and fellowship-trained pediatric neurosurgeon concentration patterns.
Practitioners should monitor FDA breakthrough device designation velocity, EU notified body capacity constraints, and PMDA joint development agreement formation for early signals of competitive access shifts. Quarterly review of Medicare reimbursement coding updates, NHS England procurement unbundling progress, and German statutory insurance screening mandate expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Grand Mal Seizure Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Diabetic Neuropathy Market
Neurology
Moyamoya Disease Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
CNS Therapeutics Market
Neurology
White Matter Injury Treatment Market
Neurology
Neurology Software Market
Neurology
Arachnoiditis Market
Neurology
Brazil Neurology Devices Market
Neurology
Neurology Services Market
Neurology
Movement Disorder Market
Neurology
Neurocutaneous Disorders Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
North America Neurology Monitoring Market
Neurology
Peripheral Neuritis Treatment Market