
 North America Neurology Devices Market | 2026-2036
North America Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Neurology Devices Market Analytics
FDA breakthrough device designation is rebalancing competitive economics by compressing clinical trial timelines and reducing regulatory capital burdens for novel neuromodulation platforms. Medtronic PLC leverages its deep brain stimulation franchise to sustain leadership in movement disorder therapy. Boston Scientific Corporation anchors its position through specialized neurovascular intervention portfolios. Abbott Laboratories differentiates via rechargeable implantable pulse generator architectures.
Neurology devices encompass implantable and non-implantable instruments engineered for neural signal modulation, cerebrovascular access, electrophysiological recording, or structural brain imaging, typically operating at precision tolerances below 50 microns for catheter-based or electrode-tipped systems. These technologies serve to restore motor function, ablate pathological tissue, monitor seizure activity, or enable minimally invasive clot retrieval in acute ischemic stroke. Neurostimulation devices command the largest installed base among product categories, reflecting durable generator replacement cycles and expanding indications beyond Parkinson's disease into obsessive-compulsive disorder and epilepsy. Deep brain stimulation technology within the technology dimension attracts disproportionate R&D allocation due to its programmable parameter sets and reversible therapeutic mechanism. Cranial monitors represent the fastest-growing product type as health systems prioritize continuous intracranial pressure surveillance in neurocritical care units.
FDA premarket notification and premarket approval pathways govern device commercialization, while Health Canada issues comparable medical device licenses under the Medical Devices Regulations. The Centers for Medicare and Medicaid Services reimbursement determinations directly shape hospital capital allocation for neuroimaging and intervention suites. Stakeholders must monitor evolving CMS national coverage determinations for closed-loop neurostimulation, as these rulings will determine whether ambulatory surgical centers or hospital outpatient departments capture incremental procedure volume.
Market Dynamics
FDA breakthrough device designation is compressing regulatory timelines for neuromodulation systems while hospital neurointerventional suite expansion concentrates capital deployment in stroke and epilepsy service lines.
Growth Catalysts
- Breakthrough Device Pathway:FDA's accelerated review mechanism shortens premarket approval timelines for novel deep brain stimulation platforms, reducing regulatory capital requirements for innovators.
- Neurocritical Care Expansion:Academic medical centers across California and Texas are investing in continuous intracranial pressure monitoring infrastructure, driving cranial monitor procurement.
- Rechargeable IPG Architectures:Extended battery life and reduced surgical replacement cycles are improving patient compliance and lowering lifetime cost of ownership for implantable neurostimulation systems.
Market Restraints
- CMS Coverage Determination Uncertainty:Pending national coverage decisions for closed-loop neurostimulation create reimbursement ambiguity that delays hospital capital commitment to ambulatory surgical centers.
- Precision Manufacturing Concentration:Catheter-based systems requiring sub-50 micron tolerances depend on specialized contract manufacturers clustered in Minnesota and Massachusetts, creating single-source vulnerability.
- Biocompatibility Material Costs:Platinum-iridium electrode alloys and medical-grade silicone encapsulants face price volatility from precious metals markets and specialty polymer supply chains.
Strategic Opportunities
- Obsessive-Compulsive Disorder Indication:FDA expanded approval pathways for deep brain stimulation beyond Parkinson's disease into psychiatric applications represent addressable white space.
- Texas Medical Center Cluster:Houston's concentration of neurosurgical volume and research institutions offers anchor tenancy for neuromodulation clinical trial sites and specialized distribution.
- Closed-Loop Algorithm Convergence:Integration of local field potential sensing with adaptive stimulation parameters enables personalized therapy adjustment without clinician intervention.
Industry Challenges
- Neurointerventionalist Training Pipeline:Specialized fellowship programs produce insufficient stroke intervention specialists to match neurovascular suite expansion timelines.
- Legacy EMR Integration:Implantable device data streams require custom API development to interface with Epic and Cerner systems, extending implementation cycles.
- ISO 14155 Compliance Burden:Clinical investigation requirements for neuromodulation devices demand extended follow-up protocols that strain site resourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Neurology Devices Market |
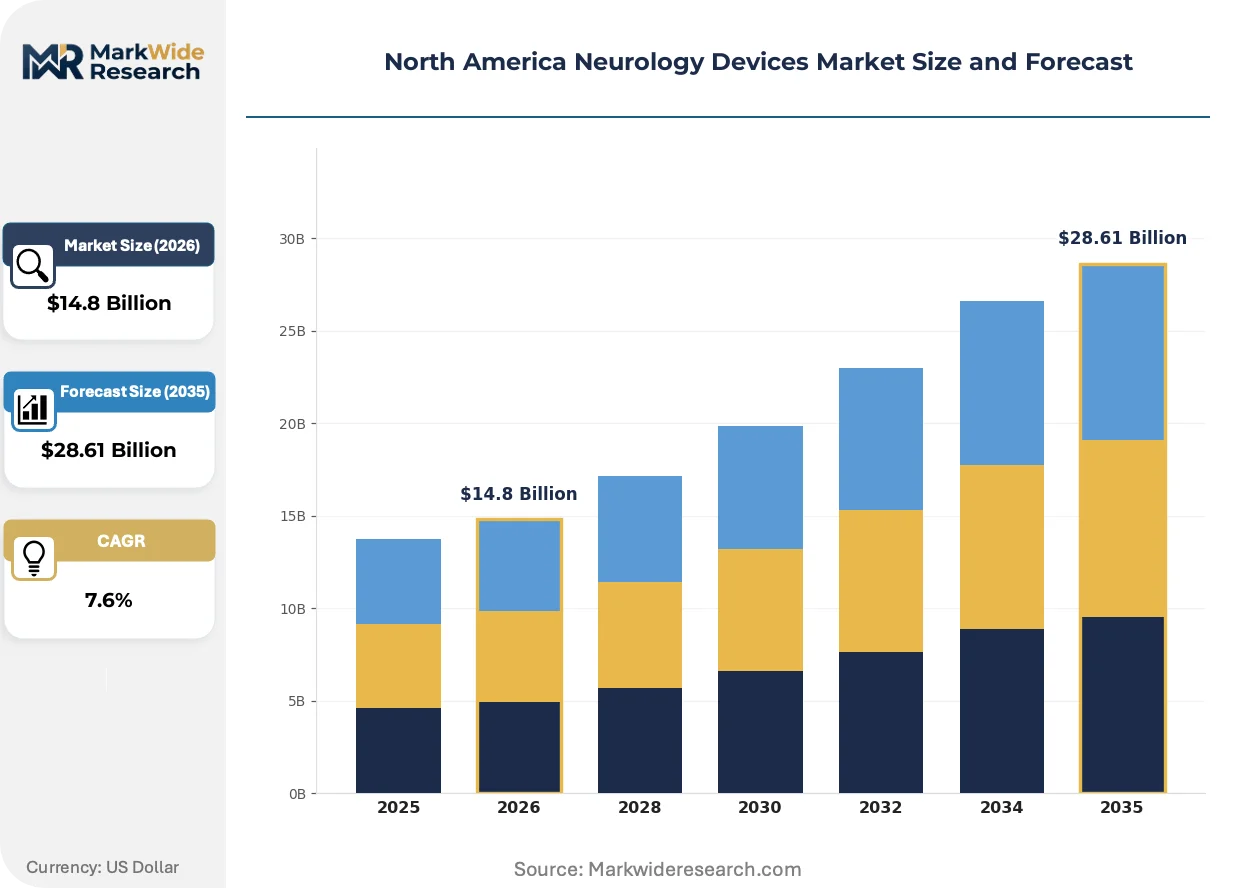
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, Cranial Monitors, Neuroimaging Equipment, Electrophysiology Devices End User: Hospitals, Clinics, Research Facilities, Home Care Settings Technology: Electroencephalography, Magnetic Resonance Imaging, Computed Tomography, Deep Brain Stimulation Application: Pain Management, Chronic Headache Treatment, Neurodegenerative Disorders, Epilepsy Monitoring |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Boston Scientific Corporation, Stryker Corporation, B. Braun SE, Johnson and Johnson, Penumbra Inc., Nihon Kohden Corporation, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Neurology Devices Market Evolving Landscape
Neural interface engineering and regulatory science advances are converging to reshape how neuromodulation systems achieve clinical validation and commercial scale.
Artificial intelligence-enabled seizure detection algorithms are automating responsive neurostimulation parameter adjustment in epilepsy management systems. Pediatric and adult epilepsy centers at Cleveland Clinic and NYU Langone are piloting these platforms for ambulatory patient monitoring. The technology is automating clinical workflow efficiency by reducing manual electroencephalogram review burden and enabling faster therapeutic response.
Health Canada's Medical Devices Regulations are harmonizing with FDA quality system requirements through the Medical Device Single Review Program, streamlining dual-market entry for neuromodulation manufacturers. This convergence reduces redundant facility inspections and documentation preparation for companies seeking simultaneous US and Canadian approval. Deep brain stimulation device sponsors are leveraging this alignment to compress total regulatory timeline by six to nine months.
Hospital purchasing committees are consolidating neurointerventional device procurement under integrated stroke service line contracts rather than discrete catheter or generator transactions. This bundling displaces traditional distributor relationships with direct manufacturer partnerships for capital equipment and consumables. The shift is most pronounced in Florida and Arizona health systems where population aging concentrates ischemic stroke incidence.
North America Neurology Devices Market Segmentation
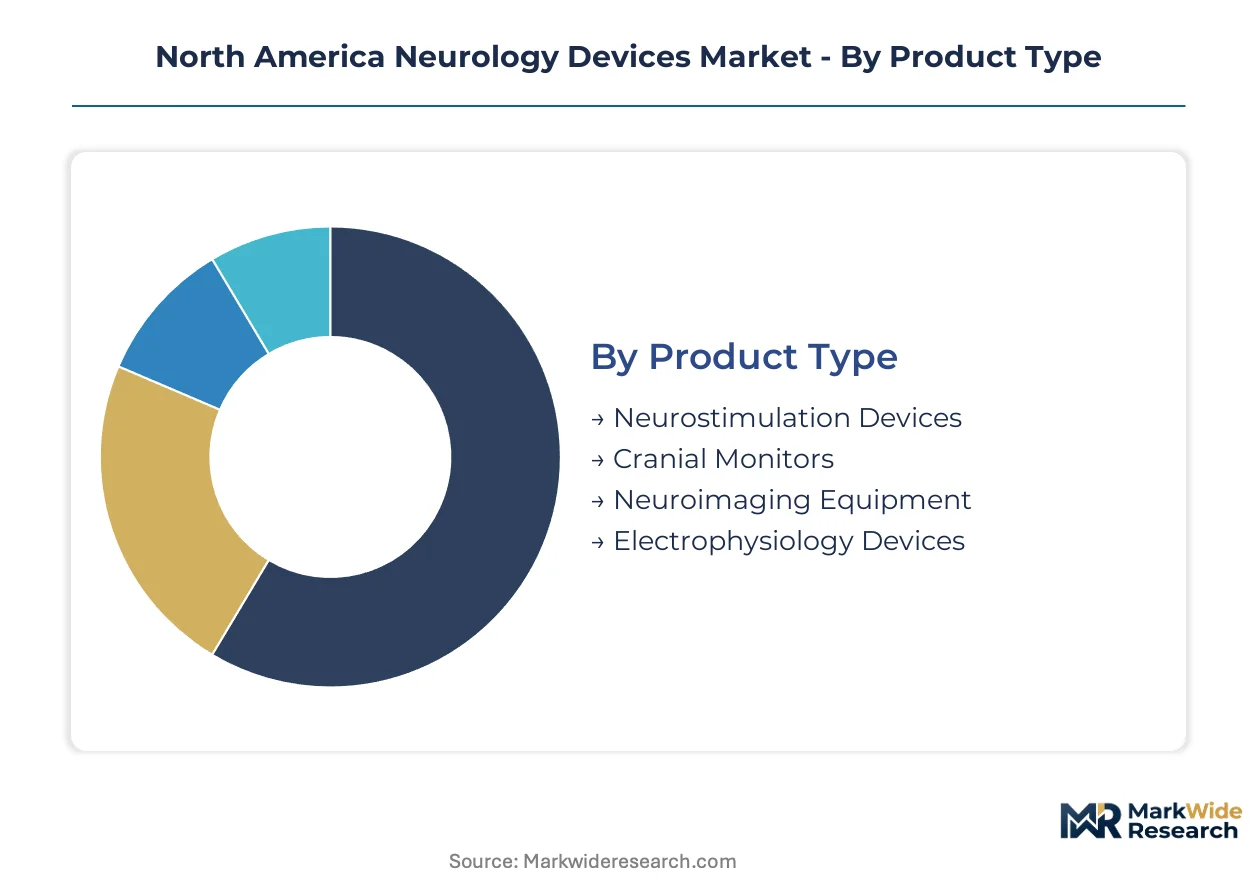
Neurology device procurement patterns diverge sharply across care settings and clinical applications. Hospital capital committees weight replacement cycles against reimbursement certainty, while ambulatory sites prioritize portable diagnostics over fixed imaging infrastructure.
Product Type:
Standardization dominates implantable systems where FDA premarket approval pathways enforce design rigidity, while neuroimaging platforms permit greater configuration flexibility.
- Neurostimulation Devices:Implantable pulse generators and lead assemblies deliver electrical modulation to targeted neural circuits. Demand concentrates in California and Texas academic medical centers where deep brain stimulation programs for movement disorders anchor surgical volume. Rechargeable battery architectures are compressing replacement intervals and improving patient compliance metrics.
- Cranial Monitors:Continuous intracranial pressure and cerebral oxygenation sensors enable real-time neurocritical care surveillance. Texas Medical Center hospitals in Houston are expanding monitoring infrastructure for traumatic brain injury protocols. Wireless telemetry integration is reducing infection risk from transcutaneous cabling.
- Neuroimaging Equipment:MRI and CT systems optimized for cranial protocols with specialized coil arrays.
- Electrophysiology Devices:Intraoperative recording and cortical mapping instruments for seizure focus localization.
Most installed capacity flows through Neurostimulation Devices. Expansion is steepest in Cranial Monitors.
End User:
Reimbursement environment shapes site selection, with CMS national coverage determinations privileging hospital outpatient departments over freestanding clinics for complex neuromodulation procedures.
- Hospitals:Comprehensive stroke centers and level-one trauma facilities anchor neurointerventional suite investment. Cleveland Clinic and Mayo Clinic Rochester anchor high-volume deep brain stimulation programs. FDA breakthrough device designation is accelerating capital procurement timelines for novel platforms.
- Clinics:Outpatient neurology practices concentrate diagnostic electrophysiology and headache management. California neurologist-owned ambulatory surgical centers are piloting closed-loop neurostimulation adjustments. Reimbursement parity gaps with hospital settings constrain device acquisition budgets.
- Research Facilities:Academic medical centers with NIH-funded neural engineering programs.
- Home Care Settings:Remote patient monitoring for seizure detection and therapy adherence.
Procedure volume concentrates in Hospitals. Regulatory tailwinds are strongest for Research Facilities.
Technology:
Imaging modalities compete on throughput and spatial resolution, while therapeutic technologies differentiate on programmability and biocompatibility.
- Electroencephalography:Scalp and intracranial electrode arrays capture neural oscillatory patterns for diagnostic and therapeutic targeting. NYU Langone epilepsy centers are deploying AI-enabled seizure prediction algorithms. Ambulatory systems are displacing inpatient monitoring for presurgical evaluation.
- Magnetic Resonance Imaging:High-field systems with specialized neurovascular coils enable microbleed detection and white matter tractography. Arizona health systems are prioritizing 3T upgrades for aging stroke populations. MRI-conditional implantable devices are expanding patient eligibility for concurrent diagnostics.
- Computed Tomography:Rapid hemorrhage detection and perfusion imaging for acute stroke triage.
- Deep Brain Stimulation:Directional leads and sensing-enabled generators for adaptive therapy delivery.
Clinical utility peaks with Deep Brain Stimulation. Deployment velocity is highest for Electroencephalography.
Application:
Indication expansion is redefining addressable populations, with psychiatric applications emerging alongside established movement disorder and epilepsy markets.
- Pain Management:Spinal cord and peripheral nerve stimulation systems for chronic refractory pain. Florida health systems are consolidating procurement under bundled service line contracts. High-frequency stimulation parameters are improving paresthesia-free outcomes.
- Chronic Headache Treatment:Occipital nerve stimulation and non-invasive vagus nerve modulation for migraine and cluster headache. Massachusetts General Hospital headache centers are piloting responsive neurostimulation platforms. Patient selection algorithms are reducing trial-to-implant conversion variability.
- Neurodegenerative Disorders:Deep brain stimulation for Parkinson's disease and essential tremor symptom control.
- Epilepsy Monitoring:Responsive neurostimulation and chronic intracranial recording for seizure localization and intervention.
Reimbursement maturity is deepest in Neurodegenerative Disorders. Regulatory momentum is strongest for Chronic Headache Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurointerventionalists and neural engineering PhD pipelines concentrate in Texas and California academic medical centers, anchoring procedure volume and clinical trial density across the continent.
United States
Deep brain stimulation programs at Cleveland Clinic and Mayo Clinic Rochester drive implantable device procurement. FDA breakthrough device designation compresses regulatory timelines for novel neuromodulation platforms. Texas Medical Center in Houston anchors neurovascular intervention volume with expanding stroke service line infrastructure.
California
Academic medical centers in Los Angeles and San Francisco prioritize responsive neurostimulation for epilepsy management. State-level medical device excise tax alignment with federal policy shapes manufacturer distribution strategies. Stanford and UCSF neural engineering programs anchor R&D partnerships with neuromodulation sponsors.
Texas
Houston's concentration of level-one trauma centers drives continuous intracranial pressure monitor deployment. CMS national coverage determinations for closed-loop neurostimulation influence hospital capital allocation across Dallas-Fort Worth health systems. Methodist Hospital and Memorial Hermann anchor specialized neurointerventional fellowship training pipelines.
Canada
Toronto Western Hospital and Montreal Neurological Institute anchor deep brain stimulation surgical volume. Health Canada's Medical Devices Regulations harmonize with FDA quality systems through the Medical Device Single Review Program. Ontario and Quebec health authorities prioritize MRI-conditional implantable device procurement for concurrent diagnostic eligibility.
North America Neurology Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across implantable and interventional neurology portfolios. Medtronic PLC, Abbott Laboratories, and Boston Scientific Corporation anchor the consolidated upper tier through decades of regulatory accumulated experience. Strategic archetypes separate into full-stack neuromodulation platform owners, specialized neurovascular intervention developers, and diversified medical technology conglomerates with neurology divisions. Competitive moves concentrate on rechargeable battery architecture differentiation and neurointerventional suite bundling contracts that displace traditional distributor relationships.
Within the diversified conglomerate tier, Medtronic PLC and Abbott Laboratories exemplify platform breadth across movement disorder and psychiatric indication expansion. Boston Scientific Corporation occupies a specialized position in neurovascular intervention portfolios. These three anchors represent distinct strategic postures: rechargeable implantable pulse generator architecture, deep brain stimulation programmable parameter leadership, and catheter-based clot retrieval system specialization respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Boston Scientific Corporation |
| Stryker Corporation |
| B. Braun SE |
| Johnson and Johnson |
| Penumbra Inc. |
| Nihon Kohden Corporation |
| Integra LifeSciences Corporation |
| Others |
Value Network & Pricing Analysis
Platinum-iridium electrode alloys flow from precious metals markets through Minnesota contract manufacturers into FDA-cleared implantable pulse generators, with biocompatibility material costs stratifying final device pricing across premium rechargeable and standard primary battery tiers.
Pricing Analysis
Bundled stroke service line contracts are displacing discrete catheter transactions in Florida and Arizona health systems, while unbundled generator-lead assemblies persist in academic medical centers. Price differentiation rests on MRI-conditional certification tiers and rechargeable architecture sophistication. Cost compression in standard primary battery systems is intensifying because hospital purchasing committees prioritize lifetime cost of ownership metrics. Ambulatory surgical centers exhibit highest price sensitivity; comprehensive stroke centers show lowest.
Supply Chain Analysis
Specialty polymer encapsulants and medical-grade silicone feed from Massachusetts and Minnesota precision manufacturers into catheter-based systems requiring sub-50 micron tolerances. Raw material dependencies center on platinum-iridium alloys, liquid crystal polymers, and biocompatible adhesives. Single-source vulnerability concentrates in Minnesota contract manufacturers serving neurovascular catheter programs. Distribution runs through direct manufacturer partnerships that displace traditional distributor relationships for capital equipment and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America neurology devices market functions as a stable compounder, with FDA breakthrough device designation compressing regulatory timelines and sustaining steady innovation-driven expansion across neurostimulation and neurointerventional portfolios.
For Market Incumbents: Extend rechargeable implantable pulse generator architectures into psychiatric indication expansions, particularly obsessive-compulsive disorder, to preempt emerging entrant challenges in white-space therapeutic categories. Deepen backward integration into platinum-iridium electrode supply through captive sourcing agreements with Minnesota specialty metals processors, insulating margin structures from precious metals volatility.
For New Entrants and Emerging Players: Launch via closed-loop algorithm partnerships with Texas Medical Center research institutions, leveraging Houston's neurosurgical volume concentration for clinical validation anchoring. Target ambulatory surgical centers in California for responsive neurostimulation pilot programs, where reimbursement parity gaps create procurement budget flexibility for novel platforms.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale neurovascular catheter specialists because hospital purchasing committee consolidation under bundled contracts favors scale players with direct manufacturer status. Five-to-ten year viability hinges on CMS national coverage determination resolution for closed-loop neurostimulation. Watch FDA premarket approval timeline compression for seizure detection algorithm platforms as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Shortens premarket approval timelines for novel deep brain stimulation platforms, reducing regulatory capital requirements. |
| Rechargeable IPG Architecture Development | Compresses replacement intervals and improves patient compliance metrics in California academic medical centers. |
| Hospital System Partnership | Enables bundled stroke service line contracts that displace traditional distributor relationships in Florida health systems. |
| Software Companion Development | Automates responsive neurostimulation parameter adjustment through AI-enabled seizure detection algorithms at Cleveland Clinic. |
| Reimbursement Strategy | Shapes CMS national coverage determinations for closed-loop neurostimulation in ambulatory surgical center settings. |
Research Methodology
Multiple input streams — primary interviews with neurointerventionalists and hospital purchasing committee directors, secondary validation through FDA premarket approval databases and CMS national coverage determination filings, and trade data reconciliation — were synthesized through bottom-up and top-down triangulation. Stakeholder consultations encompassed biomedical engineers at Texas Medical Center, GPO contracts managers, and neural engineering program directors at Stanford and UCSF. Secondary sources included Health Canada Medical Devices Regulations filings, hospital procurement databases, and neurocritical care infrastructure investment disclosures.
Historical implant volume trajectories were cross-referenced against expert panel inputs on neurointerventional suite expansion timelines across California and Texas academic medical centers. The analytical framework segmented by product type, end user, technology, and application dimensions across the projection horizon. CAGRs were derived from procedure volume growth rates, replacement cycle compression, and indication expansion curves. Industry-specific inputs incorporated FDA breakthrough device designation velocity and CMS reimbursement determination uncertainty effects on capital commitment timing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged CMS coverage determination delays or platinum-iridium supply disruptions. Forecasts reflect documented assumptions on regulatory pathway efficiency and hospital capital allocation priorities. A small set of named triggers — closed-loop neurostimulation CMS rulings, Minnesota contract manufacturer consolidation, and psychiatric indication FDA approvals — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
CNS Treatment and Therapy Market
Neurology
Global Acoustic Neuroma Market
Neurology
Intracranial Aneurysm Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Global Vertigo Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Mild Cognitive Impairment Market
Neurology
Diabetic Neuropathy Market
Neurology
Cognitive Neuroscience Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Cluster Headache Syndrome Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Chile Neurology Devices Market