
 Global Neurology Clinical Trials Market | 2026-2036
Global Neurology Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurology Clinical Trials Market Foresight
Patient recruitment and retention revenue is fragmenting across technology-enabled site networks and traditional academic medical centers. Novartis AG leverages its therapeutic area depth to sustain large-scale Alzheimer's and multiple sclerosis portfolios across four continents. Biogen anchors its competitive position through specialized neurodegenerative expertise, while Syneos Health competes by controlling integrated site-and-technology delivery models that compress trial timelines.
Neurology clinical trials constitute structured investigational programs evaluating therapeutic interventions for disorders of the central and peripheral nervous systems, typically requiring biomarker-validated endpoints, longitudinal cognitive assessment batteries, and specialized imaging protocols such as amyloid PET or quantitative MRI. Phase III trials command the largest value share given their extended duration, higher patient counts, and intensive site monitoring requirements, while biomarker-driven endpoints represent the fastest-expanding segment as sponsors pursue surrogate markers for accelerated regulatory review. Alzheimer's Disease and Parkinson's Disease therapy areas concentrate the majority of current pipeline investment, though Multiple Sclerosis maintains mature, well-established trial infrastructure with predictable enrollment dynamics.
FDA's Breakthrough Therapy and EMA's PRIME designation frameworks shape trial design by incentivizing earlier biomarker integration and adaptive statistical methods, while ICH E6(R2) Good Clinical Practice standards enforce risk-based quality management across all participating jurisdictions. Japan's PMDA Sakigake designation further accelerates neurodegenerative drug development through prioritized consultation pathways. Stakeholders must monitor how decentralized trial technologies and real-world evidence requirements reshape site selection criteria and data integrity standards.
Market Dynamics
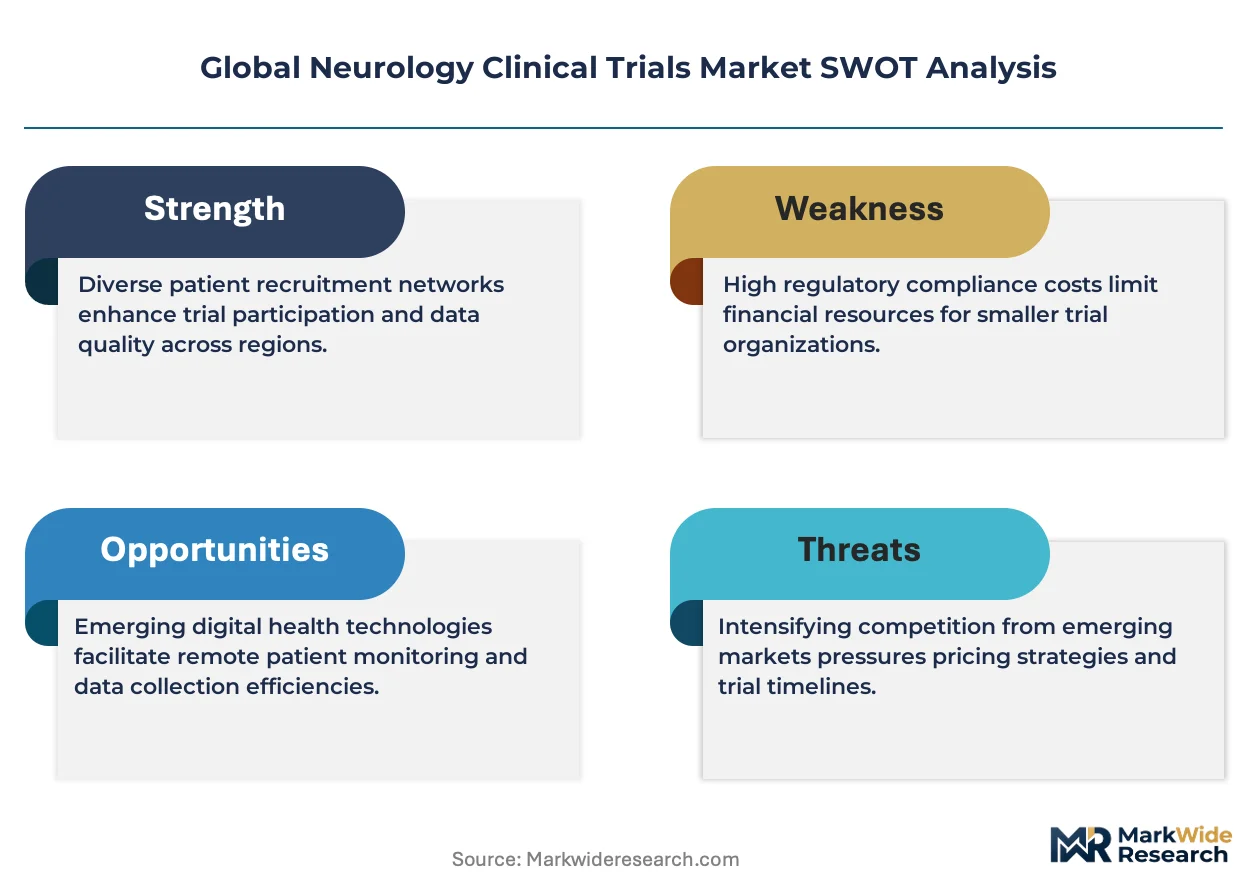
Decentralized trial infrastructure is restructuring site selection criteria as pharmaceutical sponsors demand remote patient monitoring capabilities and direct-to-patient logistics networks that bypass traditional academic medical centers.
Growth Catalysts
- FDA Breakthrough Therapy designation:The framework accelerates biomarker integration into Phase II protocols, compressing development timelines for neurodegenerative candidates.
- Amyloid PET imaging:Quantitative brain imaging protocols enable surrogate endpoint validation that satisfies accelerated regulatory review pathways.
- Germany's aging demographic:Concentrated patient recruitment pools in Bavaria and North Rhine-Westphalia expand enrollment velocity for Alzheimer's trials.
Market Restraints
- Specialized site concentration:North American academic medical centers control access to biomarker-validated patient populations, creating recruitment bottlenecks.
- Longitudinal cognitive assessment costs:Repeated neuropsychological testing batteries inflate per-patient expenditure beyond cardiovascular trial benchmarks.
- ICH E6(R2) compliance overhead:Risk-based quality management mandates impose documentation burdens that extend site initiation timelines.
Strategic Opportunities
- Japan's PMDA Sakigake pathway:Prioritized consultation mechanisms for neurodegenerative drugs create first-mover advantages for sponsors establishing Asian-Pacific footholds.
- Real-world evidence integration:Electronic health record linkage with trial databases enables post-approval safety surveillance that supports label expansion.
- Home-based digital biomarkers:Smartphone cognitive testing and wearable motor sensors expand trial access to rural patient populations previously excluded from site-based protocols.
Industry Challenges
- Neuroimaging technician scarcity:Quantitative MRI and tau PET protocols require specialized radiologic expertise concentrated at tertiary referral centers.
- Legacy electronic data capture migration:Site networks struggle to integrate cloud-based decentralized platforms with existing clinical trial management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurology Clinical Trials Market |
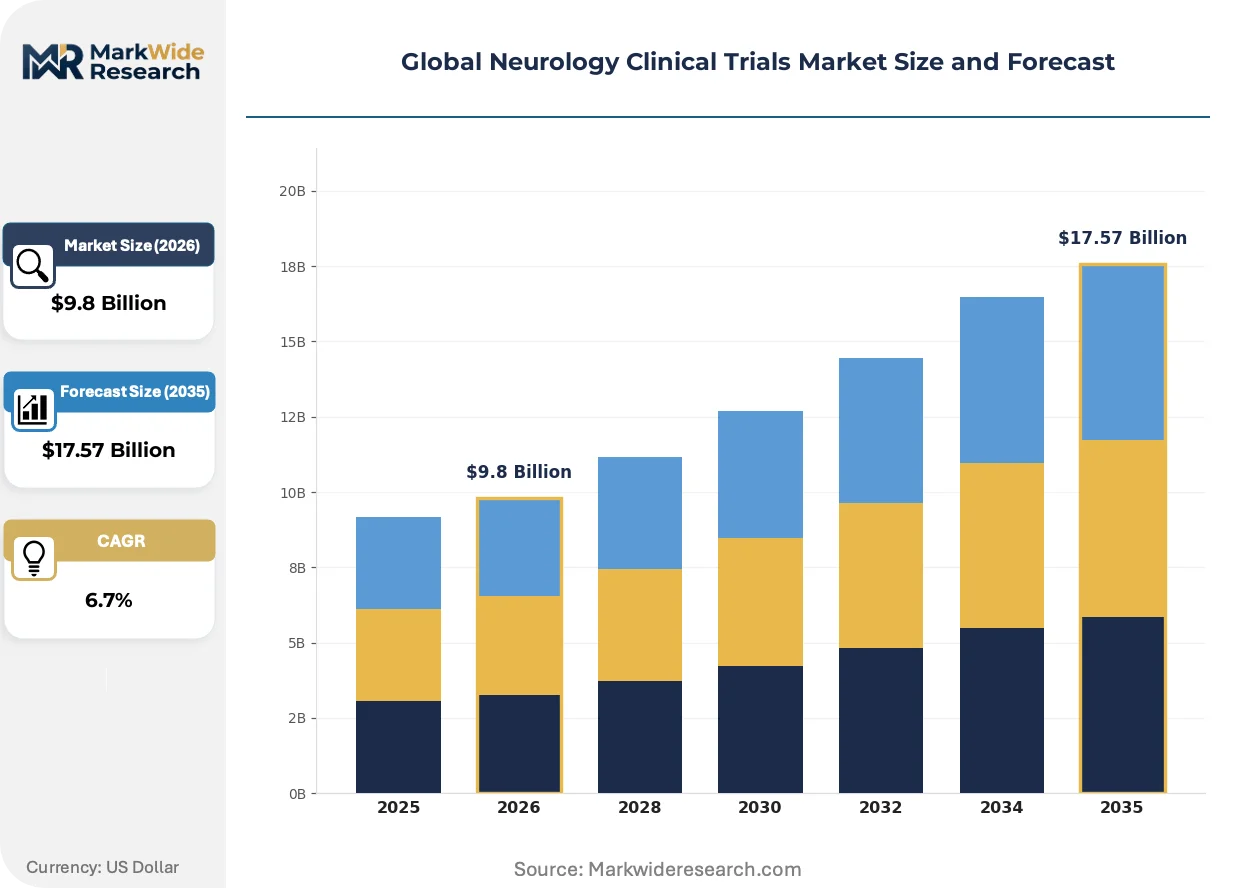
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV Therapy Area: Alzheimer's Disease, Parkinson's Disease, Multiple Sclerosis, Epilepsy, Migraine Endpoints Type: Clinical Outcomes, Biomarkers, Safety, Pharmacokinetics, Quality of Life Study Design: Randomized Controlled, Open Label, Double Blind, Cross Over, Observational |
| Companies Covered | Novartis AG, Biogen, Syneos Health, Icon Plc, Charles River Laboratories, GlaxoSmithKline, AbbVie, Eli Lilly and Company, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurology Clinical Trials Market Shifts & Advancements
Digital biomarker platforms and adaptive statistical designs are compressing traditional trial phases while regulatory frameworks evolve to accommodate surrogate endpoints.
Artificial intelligence-powered cognitive assessment tools are digitizing patient screening and endpoint measurement across Alzheimer's and Parkinson's protocols. Mid-tier biotechnology sponsors in the United States and Germany are adopting these platforms to reduce site visit frequency. The technology is digitizing data capture workflows that previously required in-person neuropsychologist administration.
EMA's PRIME designation framework mandates earlier patient input into trial design and accelerates scientific advice timelines for neurodegenerative indications. European sponsors now integrate biomarker strategies during pre-IND phases to satisfy accelerated assessment requirements. Multiple sclerosis developers in Switzerland and the Netherlands are restructuring protocols to align with these consultation pathways.
Site selection criteria now prioritize decentralized capability over geographic density as sponsors seek patients with rare movement disorders dispersed across secondary cities. Traditional academic medical center relationships are yielding to technology-enabled site networks that combine local physician access with central monitoring infrastructure. This behavioral shift is most visible in United States recruitment for amyotrophic lateral sclerosis trials.
Global Neurology Clinical Trials Market Segmentation
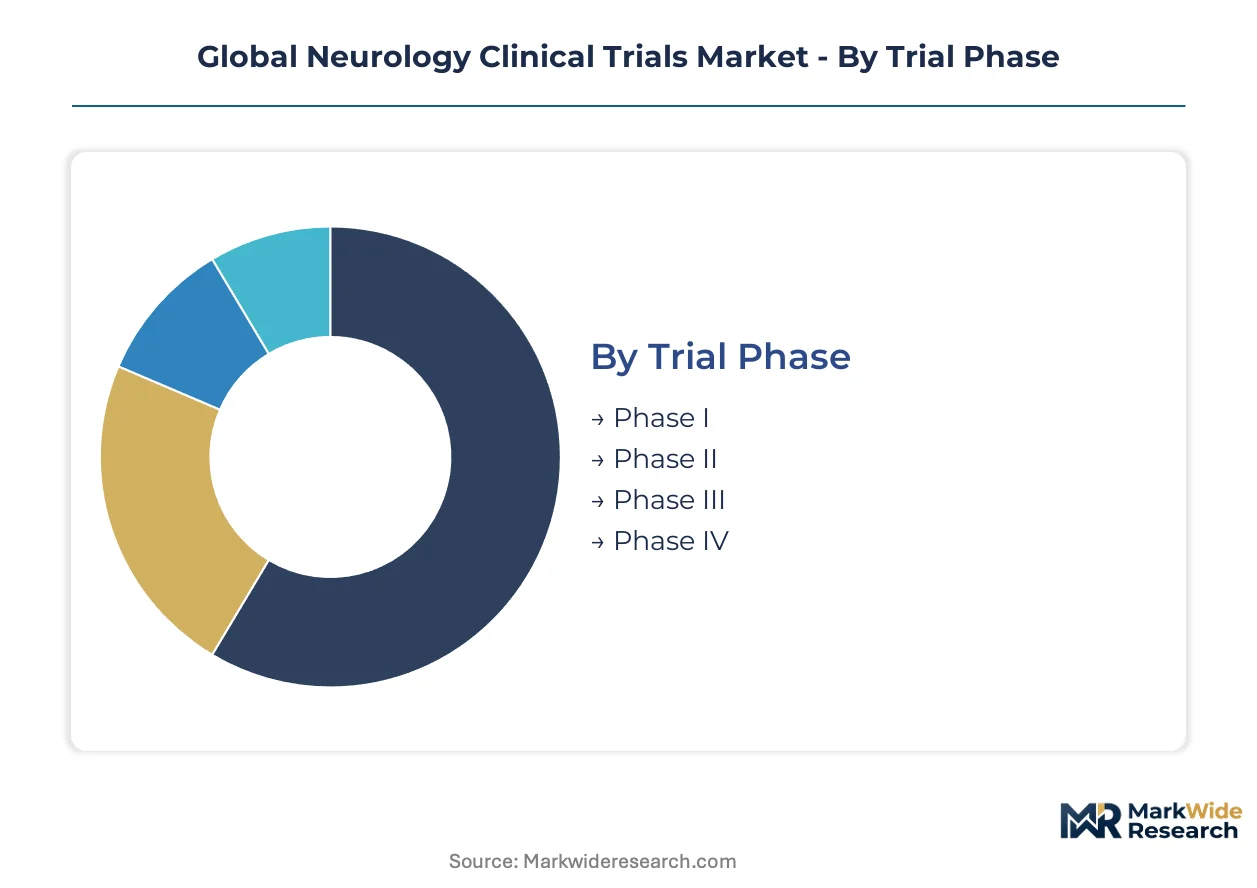
Neurology clinical trials segment across four critical dimensions that determine protocol complexity, regulatory pathway, and commercial viability. Each segmentation axis carries distinct implications for site selection, patient recruitment velocity, and endpoint validation requirements.
Trial Phase:
Cycle times compress dramatically from first-in-human through post-marketing surveillance, with Phase I turning over in months while Phase III extends across multiple years.
- Phase I:First-in-human safety and tolerability studies in healthy volunteers or patients, typically requiring 20-80 participants. Demand concentrates in United States and Germany where specialized early-phase units at academic medical centers in Boston and Munich maintain dedicated neuropharmacology expertise.
- Phase II:Efficacy and dose-ranging studies with 100-300 patients, increasingly incorporating biomarker endpoints to satisfy FDA Breakthrough Therapy and EMA PRIME designation requirements. Sponsors in Switzerland and the Netherlands are restructuring protocols to align with accelerated regulatory consultation pathways.
- Phase III:Large-scale confirmatory trials with 300-3,000+ patients, commanding extended duration and intensive site monitoring. Japan's PMDA Sakigake designation creates first-mover advantages for sponsors establishing Asian-Pacific footholds through these pivotal studies.
- Phase IV:Post-marketing surveillance and real-world evidence generation, leveraging electronic health record linkage for label expansion and safety monitoring.
Phase III dominates installed base. Phase II is where expansion concentrates as biomarker integration accelerates regulatory timelines.
Therapy Area:
Commercial maturity varies sharply across indications, with well-established trial infrastructure in some areas contrasting with emerging platforms in others.
- Alzheimer's Disease:Amyloid PET imaging and quantitative MRI protocols enable surrogate endpoint validation, though specialized neuroimaging technician scarcity at tertiary referral centers creates recruitment bottlenecks. Bavaria and North Rhine-Westphalia in Germany expand enrollment velocity through concentrated aging demographics.
- Parkinson's Disease:Wearable motor sensors and smartphone cognitive testing are digitizing endpoint measurement, expanding trial access to rural patient populations previously excluded from site-based protocols.
- Multiple Sclerosis:Mature trial infrastructure with predictable enrollment dynamics and established biomarker strategies.
- Epilepsy:Specialized patient populations requiring long-term seizure monitoring protocols.
- Migraine:Growing adoption of patient-reported outcome measures and digital diary technologies.
Multiple Sclerosis anchors stable revenue streams. Alzheimer's Disease is climbing the fastest as amyloid-targeting therapies drive protocol innovation.
Endpoints Type:
Regulatory acceptance patterns are forcing sponsors to diversify beyond traditional clinical measures toward surrogate markers.
- Clinical Outcomes:Longitudinal cognitive assessment batteries requiring repeated neuropsychological testing that inflates per-patient expenditure beyond cardiovascular trial benchmarks.
- Biomarkers:Amyloid PET, tau PET, and quantitative MRI protocols enabling accelerated regulatory review through surrogate endpoint validation. European sponsors integrate these strategies during pre-IND phases to satisfy EMA PRIME requirements.
- Safety:Standard adverse event monitoring across all phases with ICH E6(R2) risk-based quality management mandates.
- Pharmacokinetics:CNS penetration studies requiring specialized sampling protocols.
- Quality of Life:Patient-reported outcomes increasingly mandated by EMA's emphasis on early patient input into trial design.
Clinical Outcomes retains regulatory primacy. Biomarkers are gaining share fastest as FDA and EMA frameworks incentivize earlier integration.
Study Design:
Decentralized trial technologies are restructuring traditional design hierarchies as remote capabilities reshape feasibility constraints.
- Randomized Controlled:Gold standard for regulatory approval requiring complex allocation concealment and site infrastructure.
- Open Label:Simplified execution for certain neurodegenerative indications where blinding is impractical.
- Double Blind:Preferred for subjective endpoints in Alzheimer's and Parkinson's trials to minimize observer bias.
- Cross Over:Efficient for stable neurological conditions with washout period feasibility.
- Observational:Real-world evidence generation supporting post-approval safety surveillance and label expansion through electronic health record linkage.
Randomized Controlled trials dominate regulatory submissions. Observational designs are expanding most quickly as real-world evidence requirements reshape post-marketing strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sponsors deploy decentralized trial infrastructure most aggressively, while German sponsors emphasize biomarker-validated academic site networks, and Japanese sponsors prioritize PMDA Sakigake consultation pathways for neurodegenerative acceleration.
United States
FDA Breakthrough Therapy designation drives biomarker integration into Phase II Alzheimer's protocols, compressing development timelines for neurodegenerative candidates. The agency's accelerated approval pathway enables amyloid PET surrogate endpoints. Boston and San Francisco academic medical centers maintain concentrated early-phase neuropharmacology expertise with dedicated imaging infrastructure.
Germany
Bavaria and North Rhine-Westphalia aging demographics expand enrollment velocity for Alzheimer's trials through concentrated patient recruitment pools. EMA PRIME designation frameworks mandate earlier biomarker strategies during pre-IND phases. Munich and Heidelberg academic clusters control access to quantitative MRI and tau PET protocols with specialized radiologic expertise.
Japan
PMDA Sakigake designation creates first-mover advantages for sponsors establishing Asian-Pacific footholds through prioritized consultation mechanisms. The framework accelerates neurodegenerative drug development with compressed scientific advice timelines. Tokyo and Osaka site networks combine local physician access with central monitoring infrastructure for movement disorder trials.
Switzerland
Multiple sclerosis developers restructure protocols to align with EMA accelerated assessment requirements and early patient input mandates. Swissmedic maintains streamlined consultation pathways for biomarker-driven submissions. Basel and Zurich pharmaceutical clusters concentrate Phase II-III neurodegenerative trial management expertise with integrated site networks.
United Kingdom
MHRA post-Brexit regulatory autonomy enables flexible adaptive trial designs with streamlined ethics approvals for decentralized protocols. London and Cambridge academic medical centers leverage NHS electronic health record infrastructure for real-world evidence integration. The concentration supports post-approval safety surveillance and label expansion strategies.
Global Neurology Clinical Trials Market Competitive Landscape
Capability concentration sits with specialized neurodegenerative CROs; scale advantage sits with integrated site-and-technology networks. The market structures around three tiers: pharmaceutical sponsors with therapeutic area depth, full-service CROs controlling decentralized infrastructure, and niche academic site networks with biomarker validation expertise. Dominant competitive moves include strategic partnerships for imaging protocol standardization and technology licensing for digital biomarker platforms.
Within the pharmaceutical sponsor tier, Novartis AG and Biogen exemplify therapeutic area depth strategies, while Syneos Health occupies a position representing integrated site-and-technology delivery models. These three anchors demonstrate how competitive positioning separates sponsors leveraging proprietary compound pipelines from service providers compressing trial timelines through infrastructure control.
| Leading Market Players |
|---|
| Novartis AG |
| Biogen |
| Syneos Health |
| Icon Plc |
| Charles River Laboratories |
| GlaxoSmithKline |
| AbbVie |
| Eli Lilly and Company |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Boston's academic medical center cluster anchors specialized neuroimaging capacity that commands premium pricing for amyloid PET and quantitative MRI protocols, concentrating pricing power among tertiary referral centers with biomarker validation expertise while decentralized trial technologies erode traditional site premiums.
Pricing Analysis
Long-term offtake agreements between pharmaceutical sponsors and academic medical centers dominate Phase III trial pricing, locking in multi-year site access fees that insulate established centers from spot-market volatility. Price differentiation hinges on biomarker certification tier—FDA Breakthrough Therapy-aligned sites command substantial premiums over standard protocol centers—and geographic delivery cost differentials between urban tertiary hubs and emerging rural networks. Pricing pressure intensifies as technology-enabled site networks compress traditional academic center margins through remote patient monitoring capabilities. Small biotechnology sponsors exhibit highest price sensitivity, while large pharmaceutical incumbents prioritize timeline certainty over per-patient cost minimization.
Supply Chain Analysis
Export-control regimes governing radiopharmaceutical isotope production limit cross-border flows of amyloid PET tracers, constraining supply flexibility for biomarker-driven protocols. Geographic supply concentration centers on the United States, Germany, and Japan, where specialized cyclotron facilities and radiochemistry expertise cluster around Boston, Munich, and Tokyo. Raw material dependencies include fluorine-18 isotopes, gadolinium-based contrast agents, and specialized neuroimaging coils. Single-source vulnerability pervades tau PET tracer manufacturing, where limited commercial suppliers create bottleneck risk for accelerated regulatory pathways. Distribution runs through centralized radiopharmacy networks with 24-hour half-life logistics requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decentralized trial platforms threaten to displace traditional site-based revenue models, forcing incumbents to defend biomarker-validated patient access as their core moat against technology-enabled competitors.
For Market Incumbents: Insulate proprietary patient recruitment relationships in Germany's Bavaria and North Rhine-Westphalia regions through exclusive biomarker protocol partnerships with academic medical centers. Deepen backward integration into digital biomarker platforms to capture endpoint measurement value that decentralized technologies currently extract. The priority lever centers on controlling amyloid PET imaging infrastructure as regulatory agencies mandate surrogate endpoints for accelerated approval pathways. For New Entrants and Emerging Players: Secondary cities across the United States Midwest and Japan's Osaka corridor present underpenetrated patient pools for movement disorder trials where site density remains sparse. Target rural Alzheimer's populations through home-based digital cognitive assessment tools that bypass traditional neuropsychologist administration requirements. The most penetrable segment sits in observational real-world evidence studies where electronic health record integration demands lower capital intensity than interventional protocols. For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because biomarker validation expertise and decentralized technology infrastructure are consolidating into mutually reinforcing competitive positions. Acquisition targets should concentrate on mid-tier CROs with installed neurodegenerative trial management expertise and existing FDA Breakthrough Therapy track records. The signal to watch is PMDA Sakigake designation velocity, which indicates sponsor commitment to Asian-Pacific expansion and predicts site network utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Protocol Standardization | Amyloid PET imaging alignment with FDA accelerated approval pathways compresses regulatory timelines for Alzheimer's candidates. |
| Decentralized Site Network Expansion | Remote patient monitoring capabilities in secondary Japanese cities bypass Tokyo-Osaka concentration constraints. |
| Real-World Evidence Infrastructure | NHS electronic health record linkages in the United Kingdom enable post-approval label expansion strategies. |
| Specialized Radiochemistry Capacity | Cyclotron investments in Munich and Boston secure fluorine-18 isotope supply for tau PET protocol scaling. |
| Digital Cognitive Platform Licensing | Smartphone-based assessment tools expand rural patient access beyond traditional neuropsychologist coverage areas. |
Research Methodology
Initial hypotheses were tested against primary input from clinical operations directors, regulatory affairs leads at pharmaceutical sponsors, academic principal investigators, and decentralized technology vendors and refined through secondary validation across FDA Breakthrough Therapy designations, EMA PRIME submission records, ClinicalTrials.gov protocol registrations, and PMDA Sakigake consultation disclosures. Bottom-up trial volume estimates triangulated against top-down pharmaceutical R&D expenditure allocations.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling patient recruitment velocity against site capacity constraints by trial phase, therapy area, endpoint type, and study design. CAGRs derived from longitudinal protocol initiation trends and sponsor pipeline disclosure patterns. Industry-specific inputs included biomarker validation adoption curves and decentralized technology penetration assumptions across United States, German, and Japanese regulatory clusters.
Practitioners should monitor FDA guidance revisions on digital biomarker endpoints and EMA adaptive pathway rulemaking for early signals of forecast deviation. Material shifts in PMDA Sakigake designation criteria or ICH E6(R2) quality management enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Acoustic Neuroma Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Canada Neurology Devices Market
Neurology
Neurology Software Market
Neurology
White Matter Injury Treatment Market
Neurology
US Optic Neuritis Market
Neurology
Arachnoiditis Market
Neurology
Optic Neuritis Treatment Market
Neurology
Bell Palsy Treatment Market
Neurology
Neuro Critical Care Market
Neurology
Moyamoya Disease Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Cluster Headache Syndrome Market