
 Labyrinthitis Market | 2026-2036
Labyrinthitis Market Size, Share, and Industry Trends Forecast 2026-2036
Labyrinthitis Market Outlook
MDR is broadening the cost-of-entry calculus for labyrinthitis device and drug developers seeking European market access. Novartis AG leverages its neurology franchise to sustain R&D intensity across vestibular indications. Pfizer Inc. anchors its position through manufacturing scale in anti-inflammatory and antiemetic supply chains. Merck & Co., Inc. competes on geographic dominance, with established distribution across North American and Asian hospital networks.
Labyrinthitis denotes inflammation of the inner ear labyrinth comprising the cochlea and vestibular system, typically triggered by viral or bacterial infection and presenting with vertigo, hearing loss, and tinnitus. The condition demands prompt pharmacological intervention with antivirals, corticosteroids, or antiemetics to prevent permanent vestibular and auditory damage. Medications dominate current value generation due to recurring prescription cycles in acute and recurrent cases, while diagnostic tools represent the fastest-expanding segment as vestibular function testing migrates from hospital settings into outpatient clinics. Surgical interventions remain a mature, lower-volume category reserved for refractory cases, concentrating margin pools in specialized ENT surgical centers.
FDA, EMA, and WHO standards collectively shape labyrinthitis product development through divergent efficacy endpoints, pharmacovigilance reporting, and post-market surveillance requirements. These frameworks dictate trial design, labeling claims, and reimbursement negotiations across jurisdictions, directly influencing which therapies achieve commercial traction. Stakeholders must monitor evolving vestibular disorder classification criteria and payer coverage decisions to align pipeline investments with addressable patient populations.
Market Dynamics
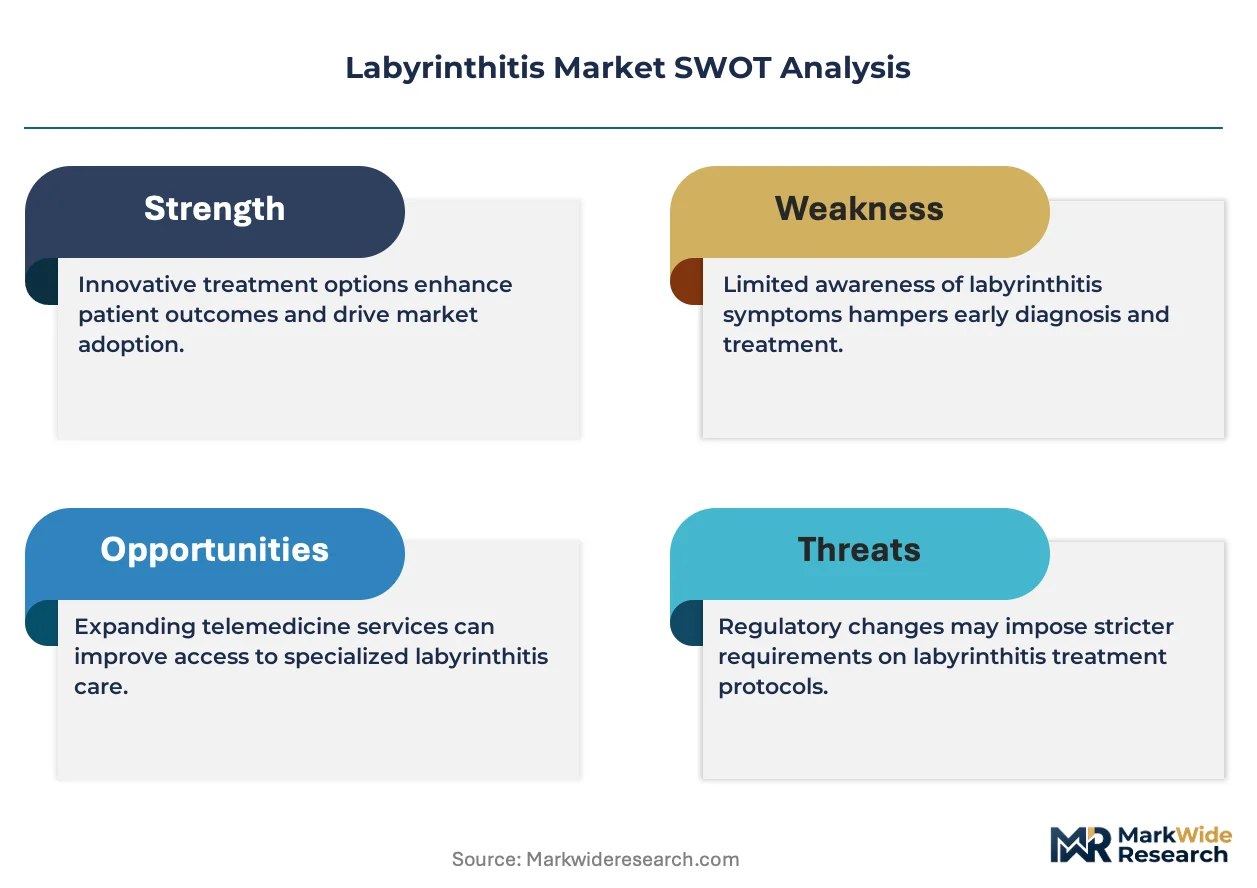
ENT specialists are pushing diagnostic protocols earlier in the patient journey, compressing the window between symptom onset and vestibular function testing. This clinical urgency is restructuring how pharmaceutical and device suppliers align their commercial operations with hospital procurement cycles.
Growth Catalysts
- Vestibular function testing migration:Outpatient clinics are absorbing diagnostic volumes previously reserved for hospital ENT departments. This decentralization expands addressable testing sites.
- MDR compliance timelines:The European Medical Device Regulation is accelerating quality system investments among diagnostic manufacturers, filtering subscale competitors and consolidating procurement toward certified suppliers.
- Tertiary care center specialization:United States academic medical centers are establishing dedicated balance disorder units, creating concentrated demand nodes for integrated diagnostic-therapeutic platforms.
Market Restraints
- Corticosteroid raw material volatility:Active pharmaceutical ingredient supply for dexamethasone and prednisolone concentrates in Indian and Chinese manufacturing clusters, exposing formulation partners to export restriction risk.
- Vestibular testing equipment concentration:Video head impulse test and rotary chair system production clusters in Germany and Japan create single-source vulnerability for North American hospital networks.
- Diagnostic reimbursement compression:CMS coding revisions for vestibular evoked myogenic potentials are narrowing margins for outpatient clinic operators.
Strategic Opportunities
- Home-based vestibular rehabilitation:Telehealth platforms are integrating remote monitoring of gaze stabilization exercises, opening chronic case management to digital therapeutics vendors.
- EMA parallel scientific advice:Developers can synchronize FDA and European regulatory pathways for novel anti-inflammatory intratympanic delivery systems, compressing time-to-market.
- Anti-viral prophylaxis protocols:Post-COVID vestibular sequela recognition is expanding prophylactic antiviral prescribing patterns in United States primary care networks.
Industry Challenges
- Vestibular physiologist staffing:Interpretation of computerized dynamic posturography requires specialized training; accredited programs in the United Kingdom and Australia produce insufficient graduates for clinic expansion plans.
- Legacy EMR integration:Diagnostic device data formats lack standardization with Epic and Cerner vestibular modules, forcing manual transcription workflows in hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labyrinthitis Market |
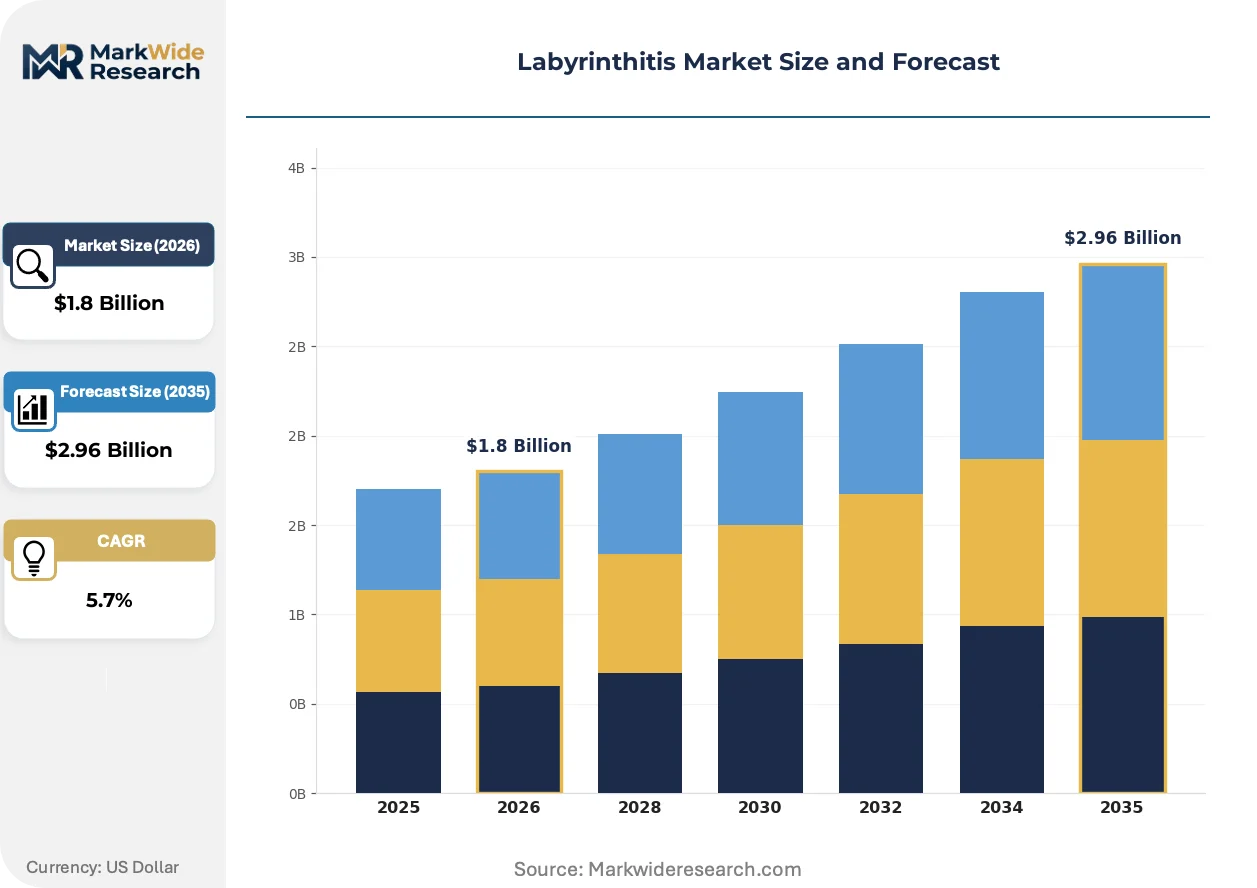
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Interventions, Therapeutic Procedures, Diagnostic Tools Application: Hospital Treatment, Outpatient Clinics, Home-based Care, Emergency Services End User: ENT Specialists, General Practitioners, Hospitals, Rehabilitation Centers Delivery Mode: Oral Administration, Intravenous Injection, Topical Treatment, Inhalation Therapy |
| Companies Covered | Mylan Pharms Inc., Novartis AG, Merck & Co., Inc., Eli Lilly and Company, GlaxoSmithKline plc, Sanofi S.A., Pfizer Inc., AstraZeneca plc, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labyrinthitis Market Strategic Shifts
Digital biomarker capture is displacing subjective symptom scales in clinical trials and reimbursement documentation. This metrological shift demands hardware-software convergence from established device manufacturers.
Artificial intelligence algorithms are integrating with video-oculography systems to automate nystagmus pattern recognition. Tertiary care centers in the United States are piloting these platforms to reduce specialist interpretation burden. The technology is integrating diagnostic throughput gains with reduced per-test labor costs, compressing the economic case for manual assessment protocols.
The FDA's evolving guidance on vestibular disorder therapeutics is mandating objective efficacy endpoints rather than patient-reported outcome measures. Trial sponsors must now incorporate computerized dynamic posturography and video head impulse test metrics into study designs. Intravenous steroid formulations face heightened evidentiary thresholds, while intratympanic delivery routes gain regulatory preference for refractory cases.
Hospital procurement committees are consolidating vendor relationships for vestibular diagnostic suites. United States health systems are shifting from single-device purchases to multi-year service contracts encompassing rotary chairs, posturography platforms, and vHIT systems. This bundling concentrates purchasing authority within supply chain executives and sidelines individual ENT department preferences.
Labyrinthitis Market Segmentation
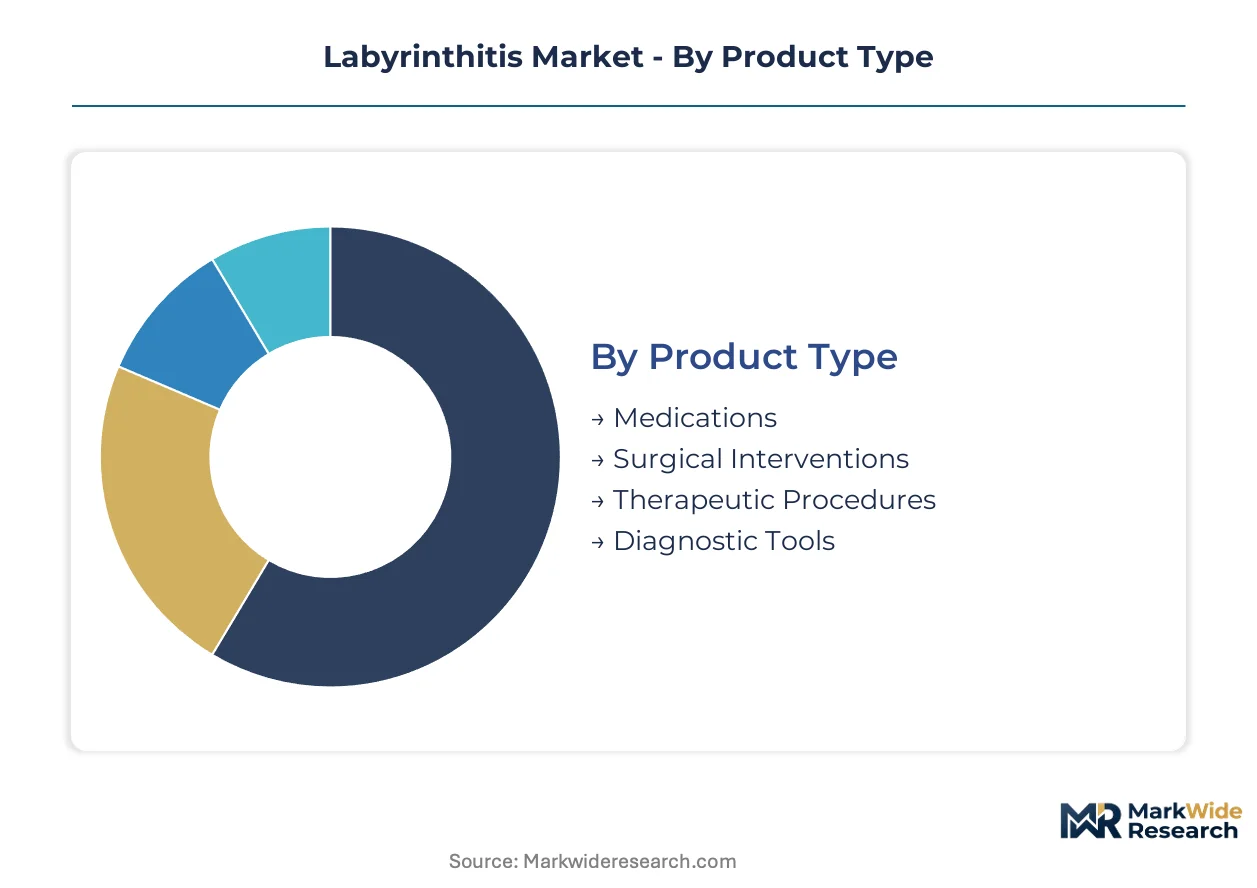
Segmentation in the labyrinthitis market determines procurement pathways and reimbursement eligibility. Product type dictates margin structure, while application setting influences device specification and service bundling. Understanding these divisions reveals where capital deployment concentrates across acute versus chronic care models.
Product Type:
Replacement cycles for diagnostic hardware and patent cliffs for pharmaceutical formulations are restructuring supplier revenue streams across categories.
- Medications:Corticosteroids, antivirals, and antiemetics constitute the revenue foundation through recurring acute prescriptions and recurrent episode management. Demand concentrates in United States hospital formularies where CMS reimbursement for oral prednisolone and intravenous dexamethasone protocols remains favorable.
- Diagnostic Tools:Video head impulse test systems, rotary chairs, and posturography platforms represent capital equipment procurement with 7-10 year replacement horizons. Outpatient clinics in Germany and Japan are absorbing hospital overflow volumes, expanding addressable installed base for manufacturers.
- Surgical Interventions:Labyrinthectomy and vestibular nerve section procedures reserved for refractory cases.
- Therapeutic Procedures:Vestibular rehabilitation therapy and intratympanic steroid injections delivered in clinical settings.
Medications sits at the top of the volume ranking, with Diagnostic Tools climbing the fastest.
Application:
Site-of-care migration is fragmenting purchasing authority between centralized hospital procurement and decentralized clinic operators.
- Hospital Treatment:Tertiary care centers with dedicated balance disorder units command integrated diagnostic-therapeutic platforms and specialist staffing. United States academic medical centers in Boston and San Francisco are concentrating high-complexity cases and surgical referrals.
- Outpatient Clinics:Community-based vestibular testing facilities are capturing diagnostic volumes previously reserved for hospital ENT departments. These settings prioritize compact, automated equipment with reduced interpretation burden.
- Home-based Care:Remote monitoring of gaze stabilization exercises and digital therapeutics delivery.
- Emergency Services:Acute vertigo differentiation protocols in emergency departments requiring rapid bedside assessment tools.
Hospital Treatment retains the largest installed base, though Outpatient Clinics are expanding most quickly.
End User:
Credentialing requirements and reimbursement eligibility are concentrating purchasing influence among accredited specialist networks.
- ENT Specialists:Otolaryngologists with vestibular subspecialty certification drive high-value diagnostic and surgical procurement decisions. Their prescribing authority for intratympanic therapies and surgical candidacy assessments shapes pharmaceutical and device demand in United States metropolitan markets.
- Hospitals:Institutional procurement committees are consolidating vendor relationships for multi-device suites under multi-year service contracts.
- General Practitioners:Primary gatekeepers for initial antiviral and antiemetic prescriptions in community settings.
- Rehabilitation Centers:Vestibular physiologists delivering structured rehabilitation programs for chronic case management.
ENT Specialists command the premium tier, with Hospitals controlling capital expenditure decisions.
Delivery Mode:
Route of administration determines manufacturing complexity, cold chain requirements, and site-of-care constraints.
- Oral Administration:Prednisolone tablets and meclizine capsules dominate first-line acute management with broad primary care prescribing authority. Formulation partners in India supply active pharmaceutical ingredients to United States and European generic manufacturers.
- Intravenous Injection:Hospital-administered high-dose corticosteroid protocols for severe acute presentations requiring inpatient monitoring.
- Topical Treatment:Intratympanic steroid delivery gaining preference for refractory cases per evolving FDA guidance on objective efficacy endpoints.
- Inhalation Therapy:Scopolamine transdermal patches for antiemetic prophylaxis during acute episodes.
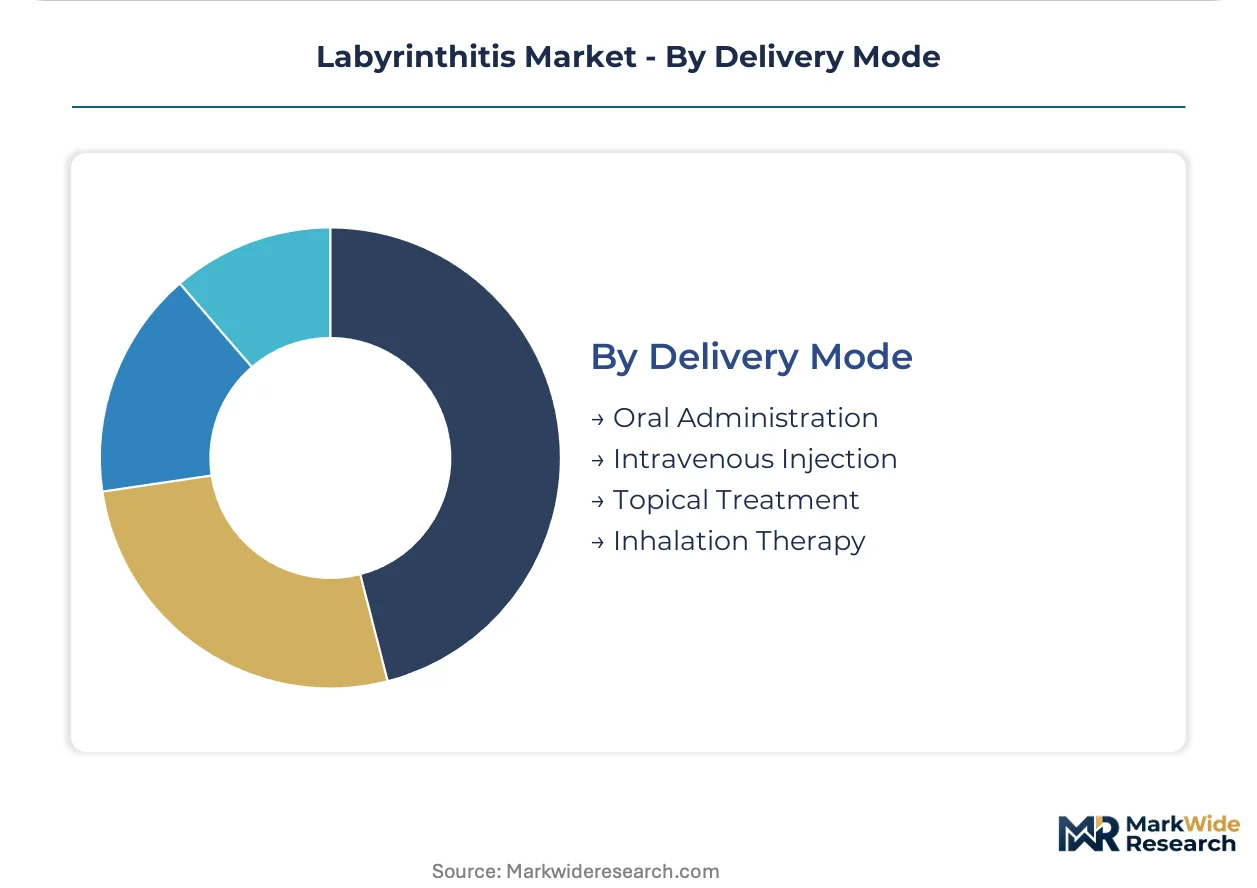
Oral Administration generates the highest prescription volumes, while Topical Treatment is gaining share fastest on regulatory preference signals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vestibular physiologists cluster in academic medical centers across Boston, London, and Tokyo, anchoring regional diagnostic capacity and training pipelines for labyrinthitis care.
United States
Tertiary care centers in Boston and San Francisco operate dedicated balance disorder units with integrated diagnostic-therapeutic platforms. FDA guidance on vestibular disorder therapeutics mandates objective efficacy endpoints, reshaping clinical trial requirements for intratympanic delivery systems. The Mayo Clinic in Rochester anchors vestibular rehabilitation research and specialist certification programs.
Germany
Video head impulse test and rotary chair system manufacturers concentrate production in Stuttgart and Munich industrial clusters. EMA parallel scientific advice pathways attract developers seeking synchronized FDA-European regulatory approval for novel anti-inflammatory intratympanic delivery systems. Charité Berlin operates Europe's largest vestibular research laboratory.
Japan
Computerized dynamic posturography equipment production clusters in Nagoya and Osaka supply North American hospital networks. PMDA standards for vestibular function testing devices align with international IEC specifications, facilitating export market access. Keio University Hospital in Tokyo leads Asia-Pacific vestibular physiologist training accreditation.
United Kingdom
Outpatient vestibular testing facilities in Manchester and Birmingham absorb diagnostic volumes from hospital ENT departments. NHS coding revisions for vestibular evoked myogenic potentials influence reimbursement margins for clinic operators. University College London Hospitals maintain the national vestibular rehabilitation protocol development center.
India
Active pharmaceutical ingredient manufacturing for dexamethasone and prednisolone concentrates in Hyderabad and Ahmedabad clusters. CDSCO regulatory pathways for generic corticosteroid formulations support export supply to United States and European formulation partners. All India Institute of Medical Sciences in Delhi anchors specialist ENT training for vestibular disorder management.
Labyrinthitis Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established neurology franchises. Market concentration remains moderate, with tiered competition separating global diversified players from regional generic specialists and device-focused manufacturers. Two strategic archetypes dominate: diversified pharmaceutical conglomerates leveraging manufacturing scale across anti-inflammatory and antiemetic supply chains, and specialized diagnostic equipment vendors concentrating on vestibular function testing hardware. Competitive moves center on multi-year service contract bundling for hospital procurement committees and regulatory pathway synchronization across FDA and EMA jurisdictions.
Within the diversified pharmaceutical tier, Novartis AG and Pfizer Inc. exemplify archetypes built on manufacturing scale and geographic distribution breadth. Novartis anchors its position through sustained R&D intensity across vestibular indications, while Pfizer occupies a scale-driven position in anti-inflammatory and antiemetic supply chain infrastructure. Merck & Co., Inc. represents the geographic dominance archetype, with established distribution networks across North American and Asian hospital procurement channels.
| Leading Market Players |
|---|
| Mylan Pharms Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Pfizer Inc. |
| AstraZeneca plc |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Accredited vestibular physiologists in the United Kingdom and Australia drive labor-cost differentials that widen pricing-tier spreads across diagnostic interpretation services. Their scarcity elevates premium-tier rates for specialist-certified clinics while compressing margins for generalist operators unable to command reimbursement premiums.
Pricing Analysis
Bundled multi-year service contracts versus unbundled single-device purchases split pricing architectures across hospital procurement committees. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service depth. Price erosion runs through economy-tier generic corticosteroid segments as Indian API manufacturers expand formulation partnerships. Outpatient clinic operators exhibit highest price sensitivity due to CMS coding compression, while tertiary academic centers prioritize integration guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese manufacturers of video head impulse test and rotary chair systems. Active pharmaceutical ingredient production for dexamethasone and prednisolone centers on Hyderabad and Ahmedabad clusters in India, with formulation finishing in United States and European facilities. Raw material dependencies include corticosteroid precursors, precision motion sensors, and specialized acoustic components. Regulatory restriction risk from Indian export controls on API shipments threatens North American hospital network supply continuity. Distribution runs through hospital procurement committees consolidating vendor relationships under multi-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The labyrinthitis market functions as a regulatory compounder where FDA guidance mandating objective efficacy endpoints for vestibular disorder therapeutics reshapes clinical trial investment and accelerates demand for integrated diagnostic-therapeutic platforms.
For Market Incumbents: Lock in multi-year service contract renewals with United States academic medical centers before procurement committee consolidation completes. Deepen backward integration into corticosteroid API supply through captive manufacturing partnerships in Indian clusters to mitigate export restriction exposure. Threat of diagnostic equipment single-source vulnerability from German and Japanese suppliers demands accelerated dual-sourcing qualification programs. For New Entrants and Emerging Players: Telehealth-enabled remote vestibular rehabilitation platforms offer the most penetrable white-space entry point. Target United States primary care networks for anti-viral prophylaxis protocol adoption in post-COVID vestibular sequela management. Go-to-market angle should emphasize digital biomarker capture compatibility with FDA-mandated objective efficacy endpoints. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with neurology franchises are the most active acquirer in this space. Long-term viability rests on pipeline positioning across intratympanic delivery innovation and vestibular diagnostic AI integration. Acquisition target archetype: specialized diagnostic equipment vendors with FDA-cleared video-oculography platforms and established hospital procurement relationships. Signal to watch: EMA parallel scientific advice pathway utilization rates as indicator of regulatory synchronization efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pathway Synchronization | EMA parallel scientific advice compresses time-to-market for intratympanic delivery systems. |
| Hospital System Partnership | Multi-year service contracts with Boston and San Francisco academic centers concentrate purchasing authority. |
| Software Companion Development | AI-integrated video-oculography platforms reduce specialist interpretation burden in tertiary care settings. |
| Backward Integration | Captive API manufacturing in Indian clusters mitigates corticosteroid raw material volatility exposure. |
| Reimbursement Strategy | CMS coding alignment for vestibular evoked myogenic potentials secures outpatient clinic margin stability. |
Study Parameters
Multiple input streams — primary interviews with ENT specialists and hospital procurement managers, regulatory filing analysis, and GPO contract databases — were reconciled against secondary validation from FDA guidance documents, EMA parallel scientific advice records, and CMS reimbursement coding revisions. Bottom-up and top-down triangulation anchored volume estimates across medication prescriptions, diagnostic equipment installations, and surgical procedure volumes.
Historical demand patterns were cross-referenced against expert panel inputs to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, application setting, delivery mode, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by patent cliff timing and replacement cycle dynamics. Industry-specific forecast inputs incorporated vestibular physiologist training pipeline capacity and MDR compliance timeline acceleration.
API export restrictions, diagnostic reimbursement coding revisions, and vestibular disorder classification criteria updates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory pathway convergence and site-of-care migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Intracranial Aneurysm Market
Neurology
Netherlands Neurology Devices Market
Neurology
Transcranial Doppler Market
Neurology
Chile Neurology Devices Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Arachnoiditis Market
Neurology
Vocal Cord Paralysis Market
Neurology
Neurology Services Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Pediatric Neurology Device Market
Neurology
Sweden Neurology Devices Market
Neurology
Arachnoiditis Treatment Market