
 Network Outsourcing Market | 2026-2036
Network Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Network Outsourcing Market Outlook
Copper-based legacy infrastructure is recalibrating total cost of ownership for enterprise network maintenance. Accenture leverages its global delivery footprint to anchor large-scale managed services contracts across financial institutions. Tata Consultancy Services specializes in multi-vendor network integration, while Huawei dominates proprietary equipment-to-service bundles in select geographies.
Network outsourcing encompasses the delegation of network design, operation, monitoring, and maintenance to third-party specialists, typically governed by service-level agreements specifying uptime thresholds of 99.99% or higher and mean-time-to-repair commitments under four hours. Managed Services and Cloud Services command the largest revenue pools due to recurring subscription structures and long contract tenures, whereas SD-WAN technology is displacing MPLS in hybrid deployment models as enterprises prioritize bandwidth elasticity over dedicated circuit costs.
FCC regulations in the United States mandate network reliability reporting for critical infrastructure providers, while the EU NIS2 Directive imposes incident-notification timelines that reshape vendor selection criteria across member states. ISO 27001 certification has become a baseline qualifier for contract eligibility in healthcare and government procurement frameworks. Stakeholders must weigh sovereign data requirements against cloud-native architectures when structuring multi-country outsourcing agreements.
Market Dynamics
SD-WAN adoption is fragmenting enterprise network procurement patterns, compressing MPLS contract durations and forcing managed service providers to restructure pricing around bandwidth elasticity rather than fixed circuit commitments.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident-notification timelines are compelling critical infrastructure operators to outsource network monitoring to certified specialists capable of meeting four-hour response thresholds.
- Private 5G deployment:Industrial automation clusters in Germany are contracting third-party network operators to design, build, and operate campus-wide cellular infrastructure.
- Copper decommissioning:Telecommunications operators are accelerating managed WAN contract expansions to shed operational overhead from aging copper-based legacy infrastructure.
Market Restraints
- Proprietary equipment lock-in:Huawei's bundled hardware-service offerings in select geographies create switching costs that limit multi-vendor integration flexibility.
- ISO 27001 certification barriers:Healthcare and government procurement frameworks now mandate this baseline qualifier, excluding smaller regional providers from contract eligibility.
- Skilled engineering scarcity:Multi-vendor network integration expertise concentrates within a limited pool of specialists, constraining service provider scaling capacity.
Strategic Opportunities
- Cloud-native sovereign data architectures:Stakeholders can capture multi-country outsourcing contracts by structuring solutions that satisfy EU data residency requirements while leveraging distributed cloud infrastructure.
- AI-driven predictive maintenance:Convergence of machine learning algorithms with network telemetry streams enables managed service providers to offer uptime guarantees exceeding 99.99%.
- Edge computing integration:Enterprise demand for low-latency processing at branch locations creates white space for outsourcing providers to bundle compute with connectivity.
Industry Challenges
- Mean-time-to-repair staffing models:Sustaining sub-four-hour response commitments across dispersed geographies requires redundant engineering coverage that compresses margin structures.
- Hybrid MPLS-SD-WAN integration complexity:Enterprises maintaining transitional network architectures demand seamless interoperability between legacy dedicated circuits and elastic broadband overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Outsourcing Market |
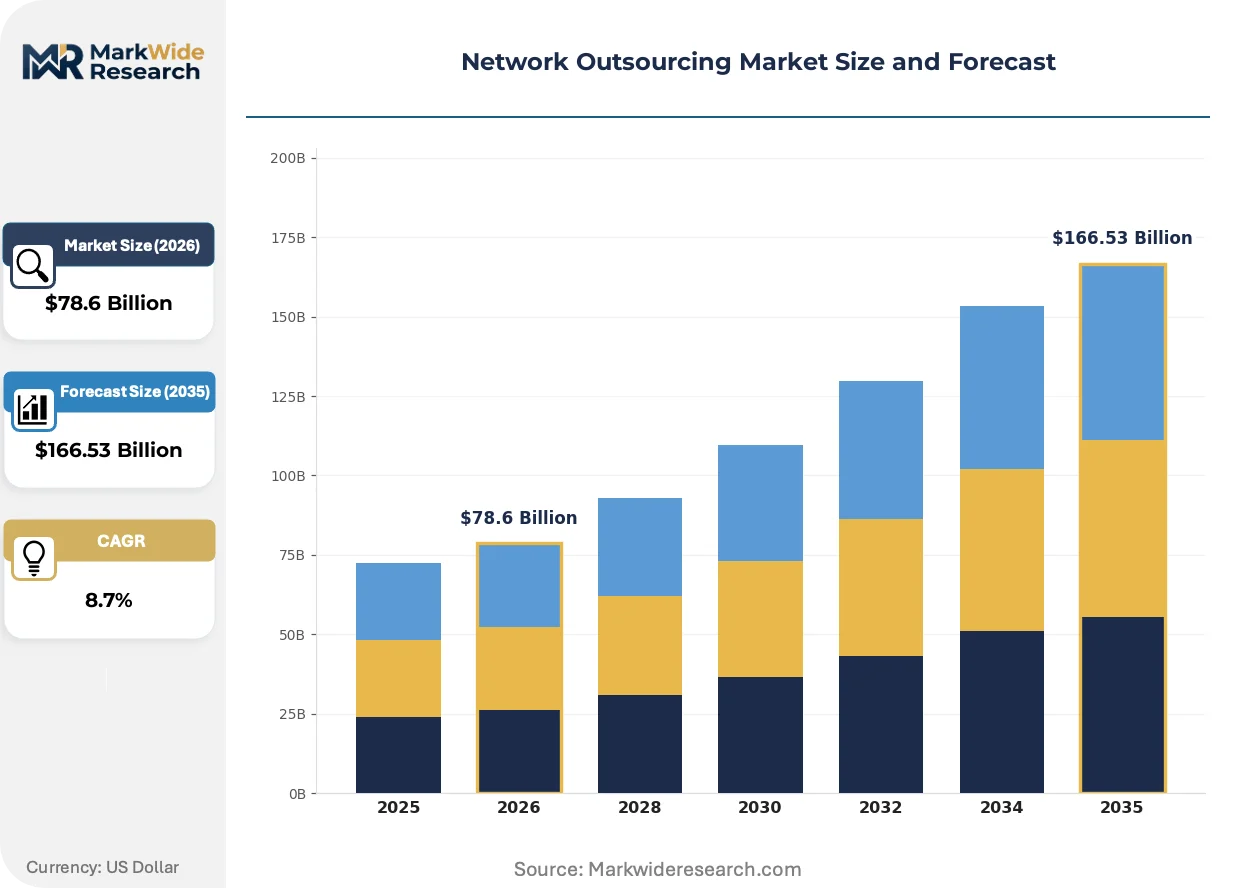
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $166.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Cloud Services, Network Monitoring, Data Center Management End User: Telecommunications, Financial Services, Healthcare, Government Deployment Model: On-Premises, Off-Premises, Hybrid, Multi-Cloud Technology: SD-WAN, MPLS, VoIP, Firewall |
| Companies Covered | Accenture, IBM, Cognizant, Tata Consultancy Services, Cisco, Huawei, Wipro, Infosys, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Outsourcing Market Strategic Shifts
Network infrastructure delivery is pivoting from hardware-centric ownership models to consumption-based service architectures, with automation and policy-driven orchestration displacing manual configuration workflows across enterprise deployments.
SD-WAN technology is modularizing enterprise branch connectivity by decoupling transport from security and application policy enforcement. Financial institutions with distributed footprints are adopting this architecture fastest, compressing procurement cycles from multi-year MPLS commitments to renewable annual subscriptions. This modularization is fragmenting vendor relationships and enabling enterprises to source transport, security, and management layers from distinct specialists rather than single carriers.
The EU AI Act is imposing risk-based compliance obligations on network operators deploying automated decision systems for traffic management or security anomaly detection. Providers must now document algorithmic transparency and human oversight protocols, increasing contractual complexity for managed security services. Healthcare and critical infrastructure sectors across Germany, France, and the Netherlands are demanding contractual indemnification clauses that allocate liability for AI-driven network decisions.
Enterprise buyers are consolidating vendor relationships under outcome-based frameworks that penalize downtime rather than rewarding capacity provision. Telecommunications operators are responding by unbundling professional services from connectivity charges, creating distinct pricing lines for design, implementation, and ongoing optimization. This unbundling is most pronounced in the United States, where FCC reliability reporting requirements give large enterprises leverage to demand service credits for threshold breaches.
Network Outsourcing Market Segmentation
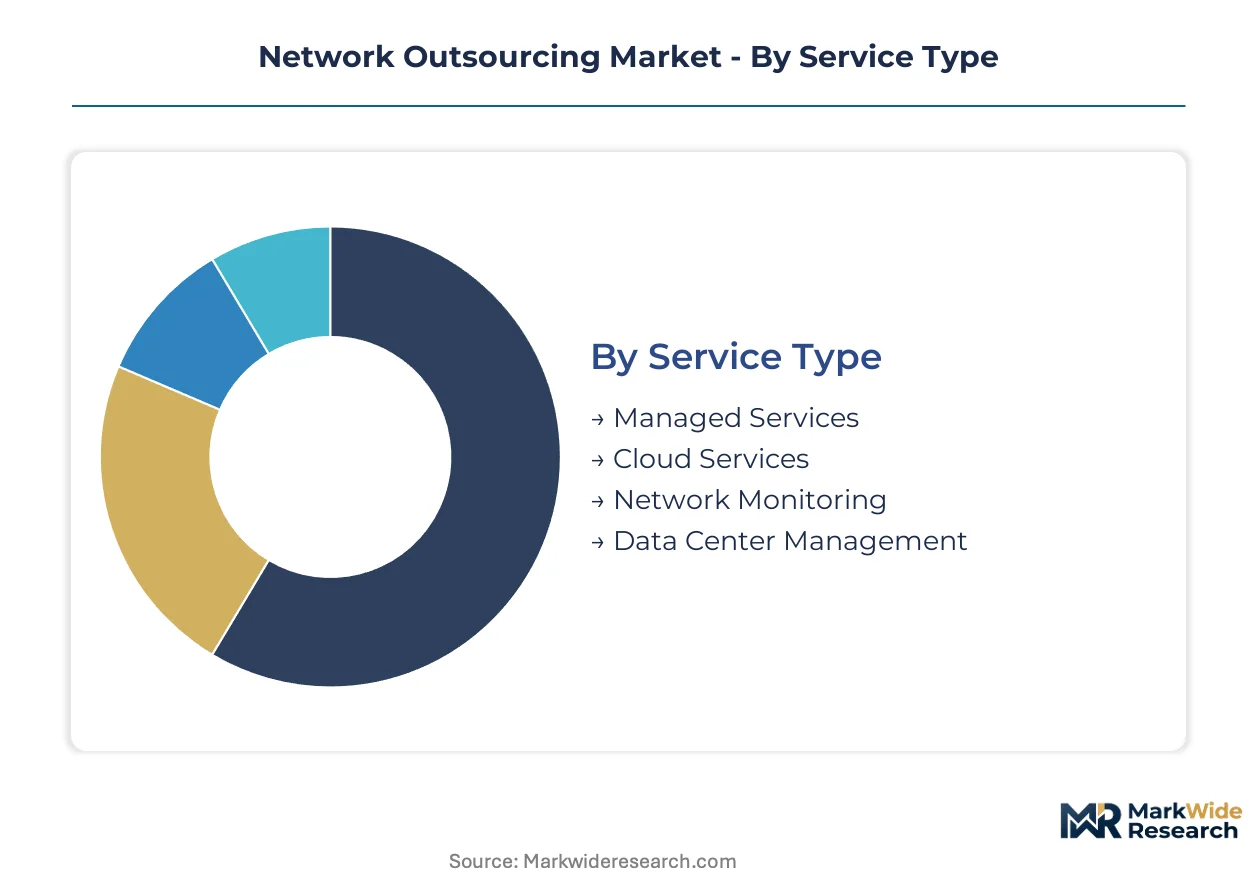
Network outsourcing procurement hinges on certification alignment across service tiers, with ISO 27001 and NIS2 compliance filtering vendor eligibility differently by segment. Buyers structure RFPs around deployment complexity and sovereign data requirements rather than generic capability claims.
Service Type:
ISO 27001 certification operates as a baseline gate for Managed Services and Cloud Services contracts, while Network Monitoring and Data Center Management face lighter documentation burdens in non-critical infrastructure sectors.
- Managed Services:Comprehensive delegation of network design, operation, and maintenance governed by SLA uptime thresholds of 99.99% or higher. German industrial automation clusters and U.S. financial institutions concentrate procurement here, driven by NIS2-mandated incident notification timelines and FCC reliability reporting requirements.
- Cloud Services:Subscription-based delivery of network infrastructure with recurring revenue structures and multi-year contract tenures. Healthcare providers across France and the Netherlands prioritize this segment for sovereign data architectures that satisfy EU residency requirements while leveraging distributed cloud infrastructure.
- Network Monitoring:Continuous telemetry collection and anomaly detection outsourced to certified specialists.
- Data Center Management:Physical infrastructure oversight including power, cooling, and hardware lifecycle management.
Managed Services sits at the top of the volume ranking, with Cloud Services climbing the fastest.
End User:
Cost tier differentiation separates telecommunications operators pursuing copper decommissioning from healthcare systems absorbing ISO 27001 certification overhead.
- Telecommunications:Incumbent carriers accelerating managed WAN contract expansions to shed operational overhead from aging copper-based legacy infrastructure. German operators lead procurement volume, with private 5G campus networks driving specialized outsourcing arrangements for industrial automation clusters.
- Financial Services:Distributed institutions adopting SD-WAN architectures fastest, compressing procurement cycles from multi-year MPLS commitments to renewable annual subscriptions. U.S. banks leverage FCC reliability reporting requirements to demand service credits for threshold breaches.
- Healthcare:Procurement frameworks mandating ISO 27001 baseline qualification, excluding smaller regional providers.
- Government:Critical infrastructure operators outsourcing network monitoring to meet four-hour response commitments under NIS2 Directive timelines.
Telecommunications commands the largest contract value, with Financial Services expanding most quickly.
Deployment Model:
Application criticality determines whether enterprises absorb on-premises capital burden or shift to consumption-based off-premises architectures.
- On-Premises:Dedicated infrastructure ownership retaining full control over physical security and data residency. German automotive manufacturers and Dutch healthcare systems favor this model for AI Act compliance documentation requiring algorithmic transparency in automated traffic management systems.
- Hybrid:Transitional architectures demanding seamless interoperability between legacy MPLS circuits and elastic SD-WAN broadband overlays. French critical infrastructure sectors contract third-party operators to manage integration complexity while maintaining sub-four-hour mean-time-to-repair commitments.
- Off-Premises:Fully outsourced infrastructure eliminating capital expenditure and operational staffing.
- Multi-Cloud:Distributed workload placement across hyperscaler environments with unified network policy enforcement.
Hybrid deployment dominates current procurement, with Multi-Cloud gaining share fastest among cloud-native enterprises.
Technology:
Margin compression in mature protocols versus pricing power in software-defined alternatives shapes vendor portfolio prioritization.
- SD-WAN:Decoupled transport and security layers enabling modular procurement from distinct specialists rather than single carriers. U.S. financial institutions with distributed footprints drive fastest adoption, fragmenting vendor relationships and compressing MPLS contract durations.
- VoIP:Voice traffic migration to packet-switched networks with quality-of-service guarantees.
- MPLS:Dedicated circuit commitments yielding to elastic broadband overlays as enterprises prioritize bandwidth flexibility.
- Firewall:Security policy enforcement bundled with connectivity or sourced from standalone specialists.
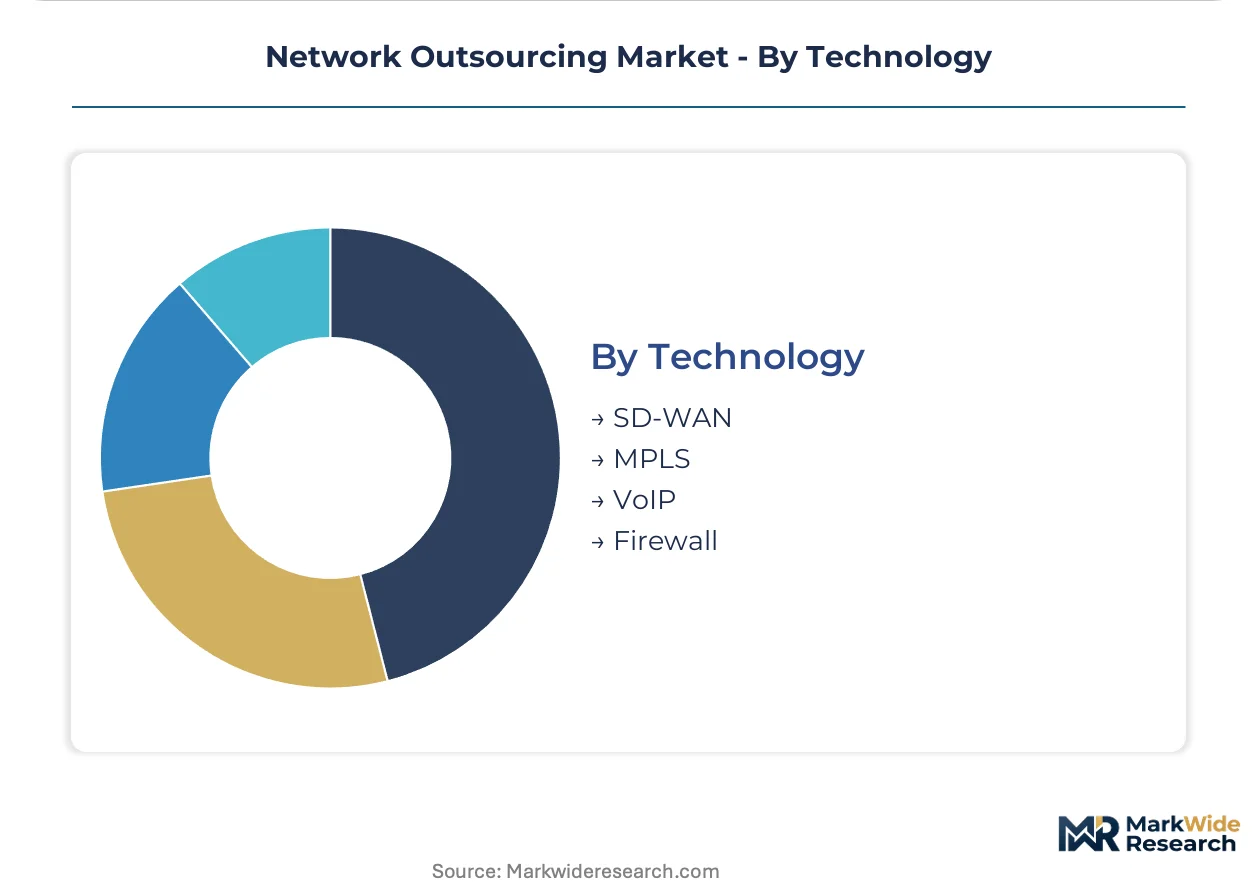
SD-WAN leads technology investment, with VoIP showing steepest expansion trajectory in healthcare and government sectors modernizing legacy PBX infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters anchor procurement concentration for private 5G network outsourcing, with EU regulatory mandates reshaping vendor selection criteria across member states. FCC reliability reporting requirements in the United States and NIS2 Directive compliance timelines in Europe are fragmenting procurement patterns toward certified specialists.
United States
Financial institutions with distributed footprints are compressing MPLS procurement cycles into renewable annual SD-WAN subscriptions. FCC regulations mandate network reliability reporting for critical infrastructure providers, giving large enterprises leverage to demand service credits. New York Metro and Chicago financial centers concentrate contract value for managed WAN expansions.
Germany
Industrial automation clusters in Baden-Württemberg and Bavaria are contracting third-party operators to design and operate campus-wide private 5G infrastructure. The EU NIS2 Directive imposes four-hour incident-notification timelines that reshape vendor selection toward certified specialists. Stuttgart and Munich automotive manufacturers favor on-premises deployment models for AI Act compliance documentation.
France
Healthcare providers across Île-de-France prioritize cloud services for sovereign data architectures satisfying EU residency requirements. ANSM and CNIL oversight tightens data localization mandates for network operators serving pharmaceutical and medical device sectors. Paris-based critical infrastructure operators outsource hybrid MPLS-SD-WAN integration to meet sub-four-hour repair commitments.
Netherlands
Dutch healthcare systems and Amsterdam financial services firms are consolidating vendor relationships under outcome-based frameworks that penalize downtime. GDPR compliance requirements filter cloud services procurement toward ISO 27001-certified providers. Rotterdam port logistics clusters drive demand for edge computing integration bundled with connectivity outsourcing.
India
TRAI regulations and the PLI scheme for telecom equipment are accelerating domestic network infrastructure modernization. Bangalore and Hyderabad technology campuses concentrate multi-vendor integration demand for enterprise SD-WAN deployments. Mumbai financial institutions contract managed services providers to meet RBI-mandated operational resilience standards for critical digital infrastructure.
Network Outsourcing Market Competitive Environment
Strategic partnerships dominate the current landscape as tiered service providers reposition around outcome-based pricing frameworks. The vendor base organizes into three distinct tiers: global consultancies with managed services scale, equipment manufacturers bundling hardware-to-service offerings, and regional specialists competing on NIS2 compliance certification. M&A activity concentrates among mid-tier providers seeking ISO 27001 credential coverage, while geographic expansion through delivery center buildouts characterizes the scale-driven tier.
Among global consultancies, Accenture exemplifies the managed services archetype through its delivery footprint anchoring financial institution contracts, while Tata Consultancy Services occupies a specialist position in multi-vendor network integration. Huawei represents the equipment-to-service bundling model in select geographies where proprietary hardware creates integrated outsourcing propositions.
| Leading Market Players |
|---|
| Accenture |
| IBM |
| Cognizant |
| Tata Consultancy Services |
| Cisco |
| Huawei |
| Wipro |
| Infosys |
| Capgemini |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 27001-qualified providers and uncertified regional operators manifests in both contract pricing and supplier qualification pipelines, with German automotive manufacturers and Dutch healthcare systems filtering procurement toward premium-tier specialists while copper-decommissioning telecommunications carriers absorb commodity-tier managed WAN pricing.
Pricing Analysis
Input-cost pass-through from skilled engineering scarcity and redundant coverage requirements for sub-four-hour response commitments compresses margin structures across managed services tiers. Pricing stratifies across NIS2-certified specialists, ISO 27001 baseline qualifiers, and uncertified regional providers. Cost compression in commodity-tier WAN management intensifies because telecommunications operators accelerate copper decommissioning. Government and healthcare buyers demonstrate lowest price sensitivity due to regulatory compliance mandates, while mid-market enterprises without critical infrastructure classification drive hardest bargain.
Supply Chain Analysis
Dual-sourcing requirements from German industrial automation clusters and U.S. financial institutions mandate multi-vendor network integration capability, fragmenting procurement across India, Germany, and the United States. Engineering talent pools draw from Bangalore technology campuses, Stuttgart automotive corridors, and Dallas-Fort Worth telecom hubs. Single-source vulnerability concentrates in proprietary equipment-to-service bundles from select geographies. Distribution runs through certified managed services partners and direct enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network outsourcing has entered a late-cycle quality phase where NIS2 compliance and AI Act documentation requirements filter demand toward premium-certified providers capable of algorithmic transparency and sovereign data architectures.
For Market Incumbents: To counter proprietary equipment lock-in from bundled hardware-service offerings, Accenture and Tata Consultancy Services should deepen multi-vendor integration capabilities through specialist acquisitions in Stuttgart and Bangalore. Certification investment in EU AI Act compliance documentation represents the critical defensive lever for healthcare and critical infrastructure contracts.
For New Entrants and Emerging Players: The mid-market gap between premium NIS2-certified specialists and commodity WAN providers offers white-space entry for cloud-native sovereign data architects targeting French healthcare and Dutch financial services. Edge computing integration bundled with connectivity outsourcing presents the most penetrable angle for Rotterdam port logistics and German automotive clusters.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification barriers exclude smaller regional providers from government and healthcare procurement frameworks. Mid-tier providers with NIS2 compliance credentials and established German industrial automation relationships represent prime acquisition targets. Watch for AI-driven predictive maintenance capability as the inflection signal separating viable long-term platforms from commodity connectivity resellers.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acquisition | ISO 27001 and NIS2 credentials unlock healthcare and government procurement eligibility. |
| Multi-Vendor Integration Capability | Specialist engineering pools in Bangalore and Stuttgart anchor complex hybrid deployments. |
| AI-Driven Predictive Maintenance | Machine learning telemetry integration enables 99.99% uptime guarantees for financial institutions. |
| Sovereign Data Architecture | EU residency-compliant cloud solutions capture French healthcare and Dutch financial services demand. |
| Edge Computing Bundling | Low-latency compute integration targets Rotterdam logistics and German automotive clusters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network operations executives, managed services procurement officers, regulatory compliance leads, and multi-vendor integration specialists with secondary validation through FCC reliability reports, EU NIS2 implementation guidance, ISO certification databases, and telecommunications operator capex disclosures. Bottom-up contract analysis and top-down market sizing triangulated volume estimates.
Segment-weighting across service type, end user, deployment model, and technology dimensions anchored the analytical framework across the analysis window. CAGRs derived from regression modeling against historical managed WAN contract expansions and SD-WAN displacement curves. Private 5G deployment timelines and copper decommissioning schedules served as industry-specific forecast inputs.
Caveats apply where EU AI Act enforcement intensity or NIS2 incident-notification interpretation could materially shift the outlook for certified provider demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Workforce Management Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Managed Services Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Europe Managed Services Market