
 US Enterprise Asset Management Market | 2026-2036
US Enterprise Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Enterprise Asset Management Market Insights
Buyer concentration among US energy and petrochemical operators is rebalancing as midstream companies consolidate while independent power producers fragment procurement across specialized vendors. IBM Corporation leverages its Watson IoT platform to anchor predictive maintenance contracts with large utility operators. Oracle Corporation sustains database-centric EAM architectures that dominate manufacturing accounts in the Ohio River Valley. SAP SE competes through deep ERP integration, positioning its Asset Intelligence Network for multi-site industrial rollouts.
Enterprise Asset Management comprises software systems that track physical asset lifecycles, maintenance schedules, and performance metrics through condition monitoring sensors, work order automation, and reliability-centered analytics. These platforms serve to minimize unplanned downtime, extend equipment useful life, and align capital expenditure planning with operational risk thresholds. Cloud Solutions now capture the fastest expansion as utilities migrate off legacy mainframe installations, while On-Premises Solutions retain dominance in defense and critical infrastructure settings where air-gapped security remains mandatory. Manufacturing end users generate the deepest margin pools due to complex asset hierarchies and regulatory audit trails.
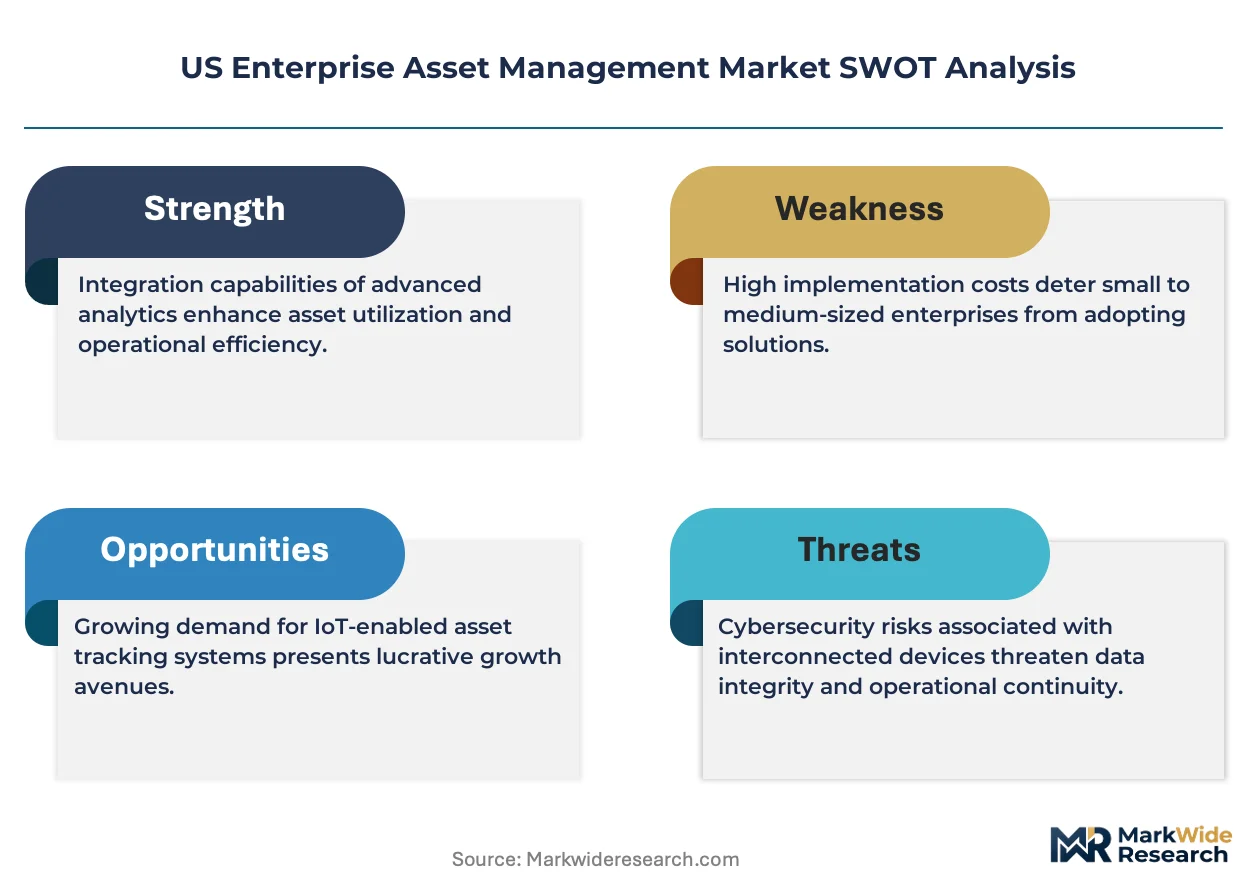
OSHA process safety management standards and NERC CIP cybersecurity frameworks shape EAM procurement by mandating documented maintenance histories and access controls for critical infrastructure operators. The SEC's climate disclosure rules and emerging EPA methane monitoring requirements are forcing energy firms to embed emissions-tracking modules within asset registers. Stakeholders must evaluate whether their current platforms can absorb sustainability reporting workloads without fragmenting core maintenance workflows.
Market Dynamics
The SEC's cybersecurity disclosure rules and EPA methane monitoring mandates are forcing asset-intensive operators to rebuild digital infrastructure around audit-ready data architectures. This regulatory compression is accelerating replacement cycles for legacy maintenance systems.
Growth Catalysts
- NERC CIP cybersecurity frameworks:Electric utilities must document access controls and maintenance histories for critical infrastructure, driving EAM procurement among independent power producers and transmission operators.
- Midwest manufacturing expansion:Automotive and heavy machinery facilities in Michigan and Ohio are deploying predictive maintenance modules to optimize equipment uptime amid labor constraints.
- Texas petrochemical corridors:Complex maintenance needs across upstream, midstream, and downstream operations create concentrated demand for reliability-centered analytics platforms.
Market Restraints
- Legacy system integration costs:Air-gapped defense and critical infrastructure installations face prohibitive capital requirements to migrate off mainframe architectures without operational disruption.
- Specialized talent scarcity:Reliability engineers with cross-functional expertise in both industrial operations and data science command premium compensation, constraining mid-market deployment timelines.
- Cloud security skepticism:NERC CIP and OSHA process safety standards create compliance friction for utilities evaluating off-premises solutions, slowing cloud migration in regulated segments.
Strategic Opportunities
- Emissions-tracking module integration:EPA methane monitoring requirements and emerging SEC climate disclosure rules create white space for EAM vendors embedding sustainability reporting into asset registers.
- Multi-site industrial rollouts:Asset Intelligence Network architectures enable centralized visibility across distributed manufacturing footprints, particularly in the Ohio River Valley.
- Condition monitoring sensor convergence:Vibration analysis, thermal imaging, and ultrasonic testing data streams are merging into unified reliability platforms for predictive maintenance contracts.
Industry Challenges
- Data architecture fragmentation:Industrial operators struggle to harmonize decades of maintenance records across incompatible CMMS, ERP, and SCADA systems without workflow disruption.
- Cyber-physical security certification:NERC CIP compliance timelines extend 18-24 months for critical infrastructure operators, delaying procurement decisions and stretching vendor sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Enterprise Asset Management Market |
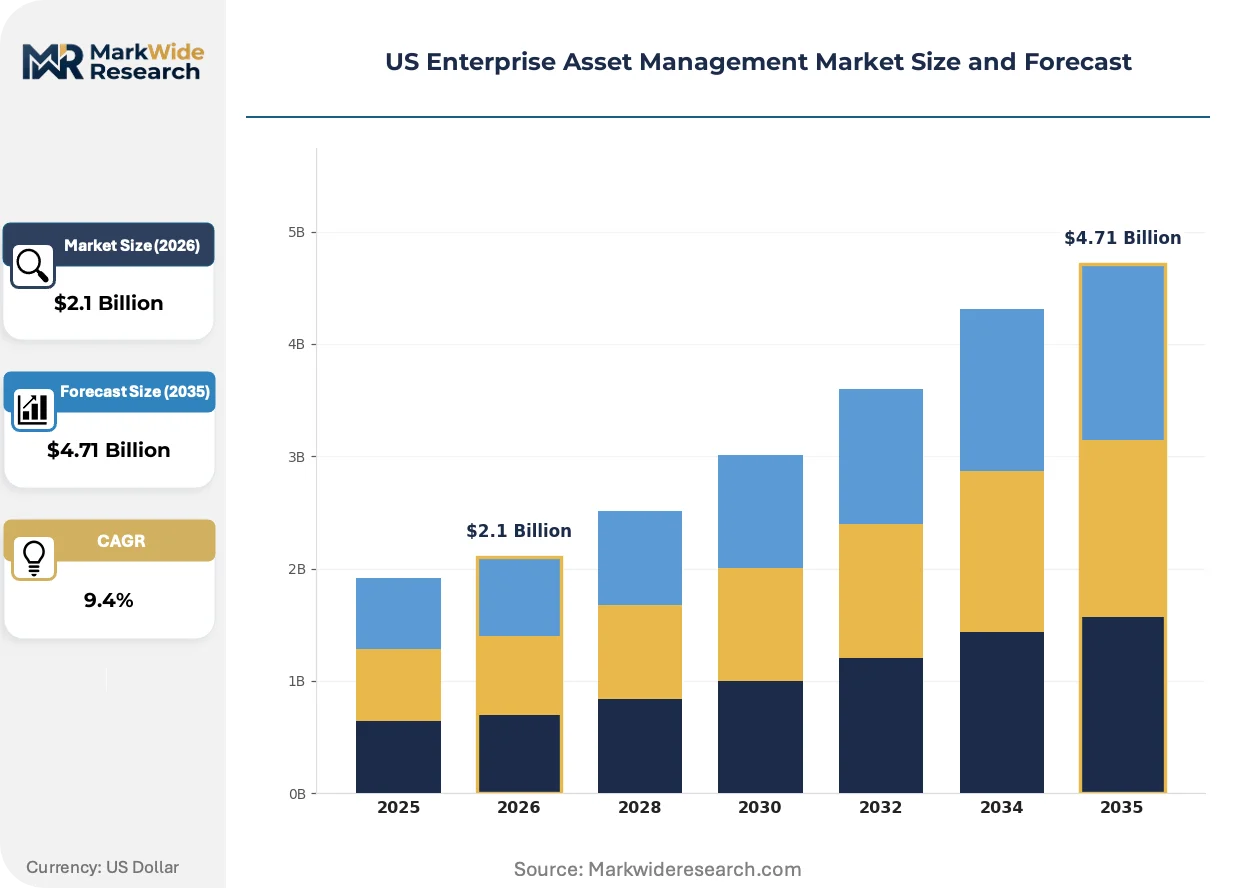
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Cloud Solutions, On-Premises Solutions, Mobile Applications End User: Manufacturing, Energy, Transportation, Healthcare Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | IBM Corporation, Oracle Corporation, SAP SE, Hexagon AB, IFS AB, ServiceNow Inc., Aptean Inc., Sage Group PLC, UpKeep Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Enterprise Asset Management Market Trends and Innovations
Cloud-native architectures are displacing on-premises installations across regulated industries, while AI-driven predictive models compress maintenance windows. Procurement patterns favor subscription-based reliability services over perpetual license models.
Digital twin technology is consolidating equipment performance data, simulation models, and maintenance histories into unified virtual representations. Petrochemical operators in Texas and Louisiana are deploying these systems at scale to optimize turnaround schedules. The technology is consolidating previously siloed engineering and operations workflows into single-pane asset intelligence.
OSHA process safety management standards now mandate documented mechanical integrity programs for high-hazard facilities. Chemical manufacturers face intensified audit scrutiny around preventive maintenance completion rates and equipment deficiency tracking. Midwest refineries are responding by embedding mobile work order automation to capture real-time technician activities.
Outcome-based service contracts are displacing traditional time-and-materials maintenance arrangements among utility operators. Large power producers now tie vendor compensation to availability guarantees and mean-time-between-failure metrics. This shift is most visible in the Southwest, where independent power producers fragment procurement across specialized reliability vendors rather than consolidating with single-platform providers.
US Enterprise Asset Management Market Segmentation
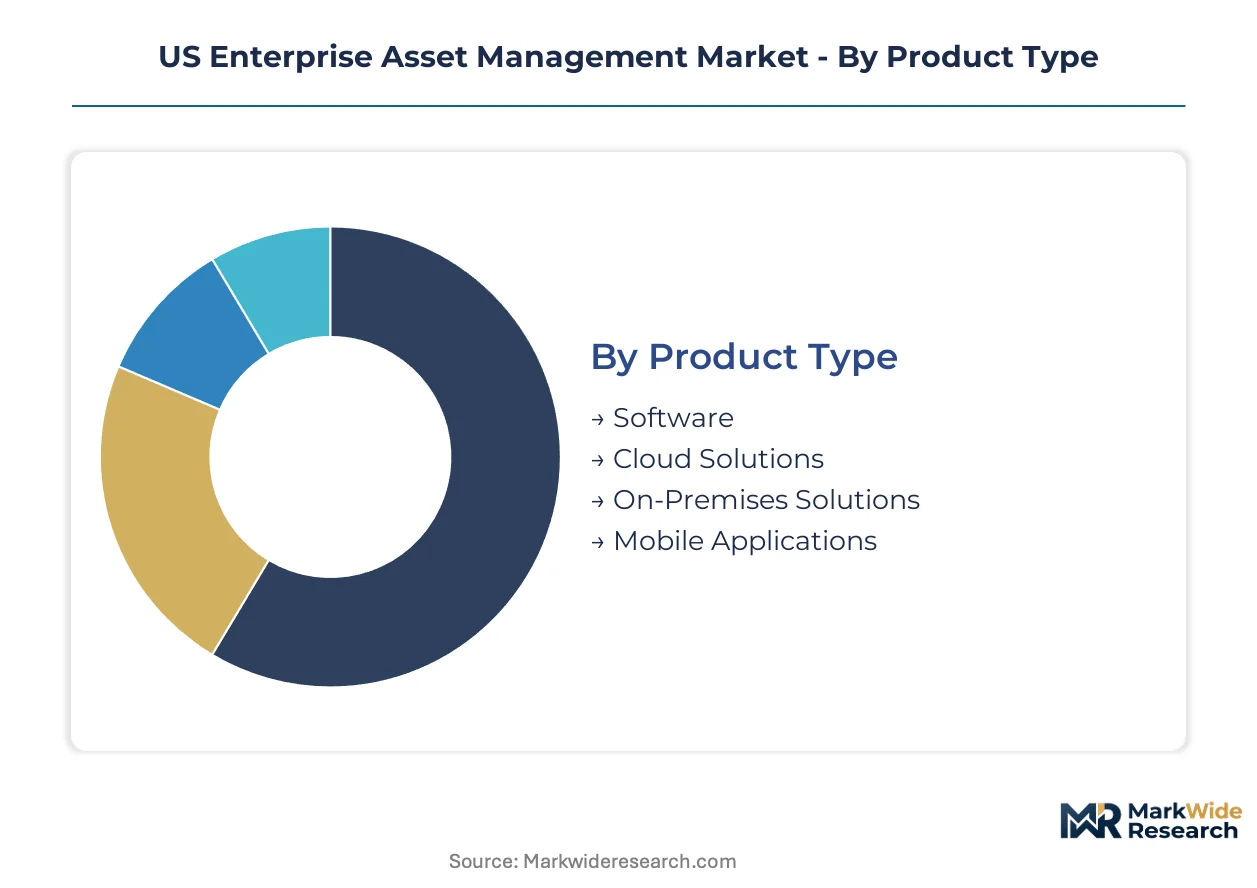
Segmentation in the US Enterprise Asset Management market reveals how upgrade cycles and compliance pressures concentrate procurement across technology architectures and service models. Buyers prioritize deployment flexibility and integration depth based on asset criticality and regulatory exposure.
Product Type:
Replacement cycles for legacy maintenance platforms are accelerating as SEC cybersecurity disclosure rules and EPA methane monitoring mandates force infrastructure overhauls. Organizations evaluate product categories against air-gapped security requirements, cloud migration readiness, and predictive analytics capabilities.
- Software:Core EAM platforms integrate work order automation, asset registers, and reliability analytics into unified databases. Manufacturing facilities across the Ohio River Valley deploy these systems to harmonize decades of fragmented CMMS records and satisfy OSHA process safety audit requirements.
- Cloud Solutions:Subscription-based architectures enable remote accessibility and automatic security patching for distributed asset portfolios. Electric utilities in Texas and independent power producers in the Southwest favor these deployments for scalability, though NERC CIP compliance timelines extend procurement cycles.
- On-Premises Solutions:Air-gapped installations serve defense contractors and critical infrastructure operators where physical network isolation remains mandatory. Petrochemical corridors accept higher capital intensity to maintain operational continuity.
- Mobile Applications:Field technician enablement tools capture real-time maintenance activities and equipment condition data. Midwest refineries embed these for OSHA mechanical integrity program documentation.
Software sits at the top of the volume ranking, with Cloud Solutions climbing the fastest.
End User:
Cost tier differentiation shapes procurement sophistication, with capital-intensive operators demanding integrated reliability analytics while smaller facilities prioritize work order efficiency.
- Manufacturing:Automotive and heavy machinery producers leverage complex asset hierarchies and regulatory audit trails to justify premium platform investments. Michigan and Ohio facilities drive predictive maintenance module adoption amid skilled technician shortages.
- Energy:Upstream, midstream, and downstream operators require emissions-tracking integration for EPA methane compliance and SEC climate disclosures. Texas petrochemical clusters generate concentrated demand for reliability-centered analytics.
- Transportation:Fleet and infrastructure operators prioritize mobile accessibility and geospatial asset tracking. Rail and aviation maintenance depots value integration with existing logistics systems.
- Healthcare:Medical equipment lifecycle management demands FDA-compliant maintenance histories and cybersecurity controls. Hospital networks balance clinical uptime requirements against constrained IT capital.
Manufacturing commands the deepest margin pools, while Energy shows the steepest expansion trajectory from regulatory compression.
Deployment:
Customer type stratification separates regulated utilities with extended compliance timelines from agile manufacturers pursuing rapid cloud migration.
- Private Cloud:Dedicated infrastructure deployments offer controlled environments for NERC CIP-regulated entities. Transmission operators and critical infrastructure owners accept premium pricing for air-gapped-equivalent security postures.
- Public Cloud:Shared infrastructure delivers cost efficiency and elastic scaling for non-regulated industrial operators. Mid-market manufacturers in the Midwest accelerate migration as legacy mainframe support contracts expire.
- Hybrid Cloud:Segmented architectures isolate sensitive operational technology data while exposing administrative functions to cloud accessibility. Petrochemical operators favor this model for turnaround schedule optimization across distributed sites.
- On-Premises:Fully captive infrastructure persists where FERC or OSHA mandates require physical data sovereignty. Defense supply chain participants maintain this deployment as a contractual precondition.
Hybrid Cloud is gaining share fastest among multi-site industrial rollouts, with On-Premises retaining defensive positions in critical infrastructure.
Service Type:
Supply concentration among specialized reliability engineers elevates implementation and training pricing, particularly for predictive analytics deployments requiring cross-functional expertise.
- Consulting:Reliability-centered maintenance program design and asset criticality ranking engagements. Texas energy corridors demand specialized expertise for emissions-tracking module configuration.
- Implementation:System integration, data migration, and workflow configuration services. Ohio River Valley manufacturing accounts require extensive legacy CMMS harmonization.
- Support:Ongoing technical assistance, security patching, and regulatory update management. Utilities prioritize 24/7 coverage for NERC CIP compliance maintenance.
- Training:Technician certification and administrator enablement programs. Midwest automotive facilities invest heavily to address reliability engineer scarcity.
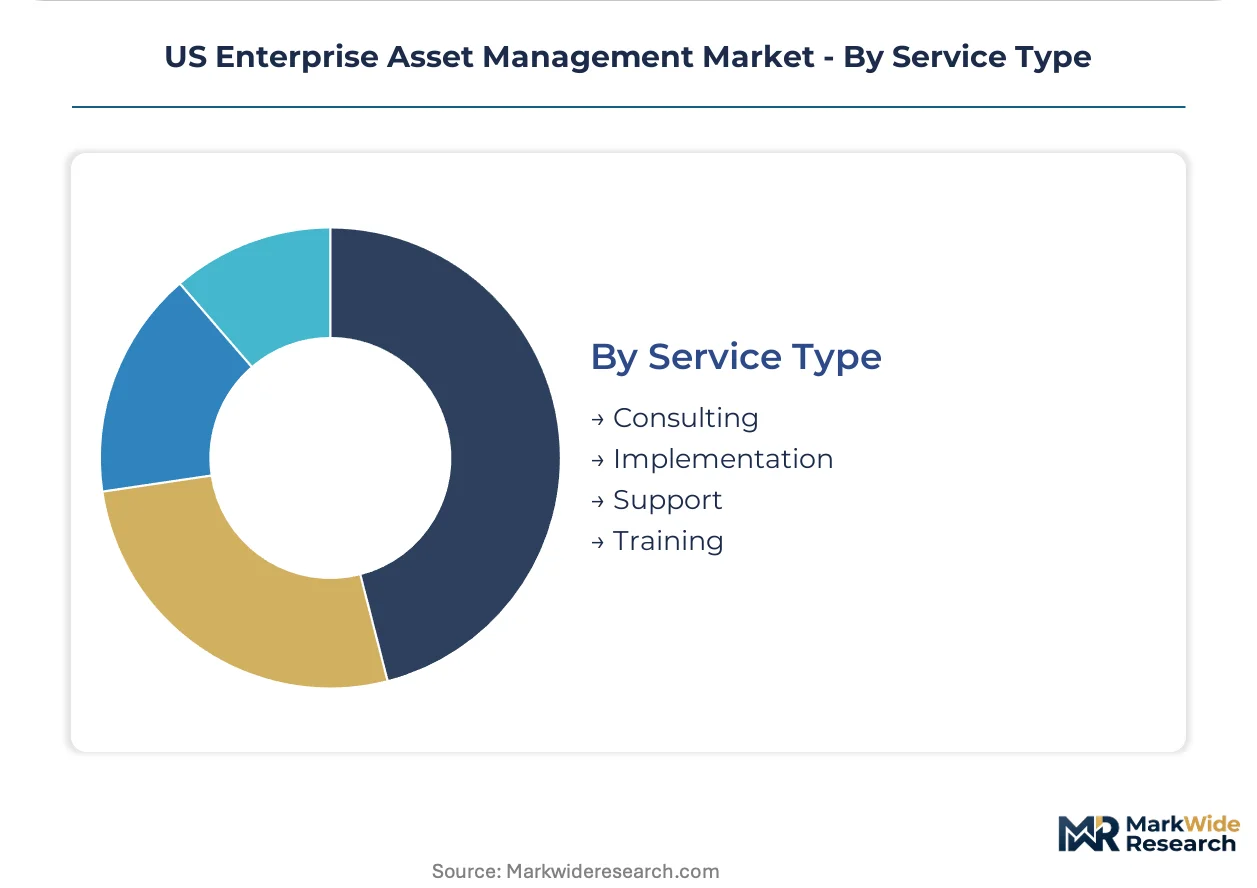
Implementation captures the largest service revenue share, with Consulting expanding most quickly from sustainability reporting workload integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas petrochemical corridors generate concentrated EAM demand from complex maintenance needs, while Midwest manufacturing clusters pursue predictive analytics amid labor constraints. The SEC's cybersecurity disclosure rules and EPA methane monitoring mandates compress upgrade timelines unevenly across state-level industrial bases.
Texas
Upstream, midstream, and downstream operators drive demand for reliability-centered analytics platforms across Houston and Port Arthur refining complexes. EPA methane monitoring requirements and SEC climate disclosure rules force energy firms to embed emissions-tracking modules within asset registers. The Gulf Coast petrochemical corridor accepts higher capital intensity for air-gapped security postures where operational continuity remains paramount.
Midwest
Michigan and Ohio automotive facilities deploy predictive maintenance modules to optimize equipment uptime amid skilled technician shortages. OSHA process safety management standards mandate documented mechanical integrity programs for high-hazard chemical manufacturers. Cleveland and Detroit industrial clusters embed mobile work order automation to capture real-time technician activities for audit trails.
Southwest
Independent power producers in Arizona and New Mexico fragment procurement across specialized reliability vendors rather than consolidating with single-platform providers. NERC CIP cybersecurity frameworks extend compliance timelines 18-24 months for critical infrastructure operators. Phoenix and Albuquerque utility markets favor outcome-based service contracts tying vendor compensation to availability guarantees.
Northeast
Defense contractors and critical infrastructure operators in Virginia and Maryland maintain fully captive on-premises infrastructure where FERC mandates require physical data sovereignty. The Ohio River Valley manufacturing accounts require extensive legacy CMMS harmonization to satisfy decades of fragmented maintenance records. Pittsburgh and Baltimore industrial bases prioritize 24/7 technical support coverage for regulatory update management.
Southeast
Hospital networks in Florida and Georgia balance clinical uptime requirements against constrained IT capital for medical equipment lifecycle management. FDA-compliant maintenance histories and cybersecurity controls shape procurement for healthcare asset registers. Atlanta and Miami healthcare clusters evaluate cloud-native architectures against HIPAA-aligned security postures for distributed medical device fleets.
US Enterprise Asset Management Market Competitive Landscape
US-based software giants anchor the premium tier; European specialists hold positions in ERP-integrated deployments and industrial IoT platforms. The vendor base stratifies across three layers: full-stack enterprise suites, vertical-specific reliability platforms, and cloud-native point solutions. Two dominant competitive moves are reshaping positioning: predictive analytics module acquisitions and multi-site rollout partnerships with industrial systems integrators.
Within the full-stack enterprise tier, IBM Corporation, Oracle Corporation, and SAP SE exemplify divergent architectural philosophies. IBM leverages Watson IoT platform capabilities to anchor predictive maintenance engagements with large utility operators. Oracle sustains database-centric EAM architectures that dominate manufacturing accounts requiring deep ERP integration. SAP positions its Asset Intelligence Network for multi-site industrial rollouts, competing through native connectivity to broader enterprise resource planning workflows.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Hexagon AB |
| IFS AB |
| ServiceNow Inc. |
| Aptean Inc. |
| Sage Group PLC |
| UpKeep Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up software specialists have consolidated mid-market EAM vendors across the Ohio River Valley and Texas corridors, compressing pricing discipline while extending payment terms for implementation services. This ownership pattern concentrates supply-side leverage among three platform archetypes, forcing buyers into longer contract lock-ins and bundled analytics modules.
Pricing Analysis
Capacity additions in cloud-native SaaS architectures are reshaping price floors for subscription tiers across the US market. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation hinging on predictive analytics depth and NERC CIP compliance certification. Cost compression in the standard tier is intensifying because hyperscaler infrastructure subsidies are eroding legacy vendor maintenance revenue. Independent power producers in the Southwest exhibit highest price sensitivity, while defense contractors accept premium pricing for air-gapped security postures.
Supply Chain Analysis
Refurbishment flows for legacy mainframe hardware and remanufactured condition monitoring sensors are extending equipment lifecycles across Midwest manufacturing clusters. Supply concentrates in the United States for core platform development, with India and Ireland hosting implementation and support centers. Component dependencies include cloud hyperscaler infrastructure, industrial IoT sensor arrays, and specialized reliability engineering talent pools. Single-source vulnerability around NERC CIP-certified cybersecurity modules creates procurement bottlenecks. Distribution runs through direct enterprise sales teams and industrial systems integrators serving petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Enterprise Asset Management market reads as a late-cycle quality story, with procurement shifting toward EPA methane compliance and SEC climate disclosure specifications that demand premium platform capabilities. Buyers now prioritize audit-ready data architectures over cost-minimization.
For Market Incumbents: To counter cloud-native point solutions eroding mid-market share, IBM and Oracle must anchor predictive maintenance contracts with deeper Watson IoT and database-centric integrations. Prioritize NERC CIP certification investments to extend compliance timelines as a competitive moat. Channel control through industrial systems integrators in Texas and Ohio River Valley manufacturing clusters defends margin position against vertical software challengers. For New Entrants and Emerging Players: Cloud-native mobile work order platforms offer the most penetrable entry vector, targeting Midwest automotive facilities with technician scarcity and OSHA mechanical integrity audit requirements. White space concentrates in emissions-tracking module integration for EPA methane compliance, where incumbent platforms fragment sustainability reporting from core maintenance workflows. Direct-to-plant-engineer digital marketing and freemium pilot programs bypass entrenched procurement committees. For Investors and Strategic Acquirers: Industrial software conglomerates are the most active acquirer in this space, rolling up specialized reliability analytics vendors to fill predictive maintenance capability gaps. Long-term viability centers on platforms absorbing sustainability reporting workloads without workflow fragmentation. Acquisition target archetype: vertical-specific EAM vendors with embedded EPA compliance modules and multi-site manufacturing reference accounts. Monitor SEC enforcement patterns around cybersecurity disclosure violations as early signals of replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Module Acquisition | Watson IoT capabilities anchor utility operator contracts with AI-driven maintenance windows. |
| Multi-Site Industrial Rollout Partnership | SAP's Asset Intelligence Network enables centralized visibility across Ohio River Valley manufacturing footprints. |
| Emissions-Tracking Module Integration | EPA methane compliance requirements create white space for sustainability-embedded asset registers. |
| NERC CIP Certification Investment | Cybersecurity framework compliance extends sales cycles but locks out unqualified competitors. |
| Condition Monitoring Sensor Convergence | Vibration, thermal, and ultrasonic data streams merge into unified reliability platforms for Texas petrochemical operators. |
Research Methodology
Multiple input streams — executive interviews with reliability engineering directors, procurement discussions with utility planning officers, and technical validation from industrial IoT platform architects — were reconciled against secondary sources. Primary fieldwork captured maintenance workflow priorities across Michigan automotive facilities, Texas petrochemical complexes, and Southwest independent power producers. Secondary validation drew from SEC cybersecurity disclosure filings, EPA methane monitoring rulemakings, NERC CIP compliance databases, and EAM vendor SEC 10-K segment disclosures. Bottom-up equipment installation counts and top-down software revenue estimates were triangulated to anchor market sizing.
Historical spending patterns were cross-referenced against panel input from maintenance directors and IT procurement officers to construct the projection framework. Segmentation modeling covered deployment architecture, end-use vertical, organization scale, and geographic regulatory cluster across the analysis window. CAGRs were derived from fitted growth curves calibrated to replacement cycle acceleration from compliance mandates. Industry-specific forecast inputs included NERC CIP compliance timeline distributions and EPA methane monitoring implementation schedules.
Regulatory enforcement variance, cloud migration adoption curve shifts, and reliability engineer labor market tightness are the dominant revision risks to projection assumptions. Forecasts reflect documented compliance deadlines and vendor sales cycle data, though actual procurement timing may diverge based on budget cycle alignment. Practitioners should monitor SEC cybersecurity disclosure enforcement actions and EPA methane monitoring pilot program outcomes for early signals of platform replacement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Shared Services Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Enterprise Social Graph Market