
 Global Supply Chain As a Service (Scaas) Market | 2026-2036
Global Supply Chain As a Service (Scaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Supply Chain As a Service (Scaas) Market Foresight
Third-party logistics brokerage channels is reconfiguring how manufacturers access capacity without owning physical assets. DHL Supply Chain leverages its warehouse footprint to anchor contract logistics offerings across European industrial corridors. FedEx Corporation competes through integrated air-ground networks that sustain express delivery guarantees for healthcare shippers. project44 differentiates via API-first visibility platforms that connect disparate carrier systems into unified data layers.
Supply Chain as a Service denotes the externalization of planning, execution, and control functions to specialized providers operating through cloud-based software stacks, API integrations, and multi-tenant platforms that orchestrate inventory, transportation, and fulfillment across distributed networks. The primary commercial purpose is to convert fixed logistics costs into variable expenditures while injecting real-time analytics into procurement and distribution decisions. Logistics Management occupies the largest service-type position due to enduring shipper preference for outsourced transportation procurement and warehouse operations. Cloud-Based deployment leads the infrastructure dimension as enterprises abandon capital-intensive on-premises installations in favor of subscription models with faster implementation cycles. Artificial Intelligence within the technology segment is capturing disproportionate investment focus as predictive algorithms reduce safety-stock requirements and automate exception handling in volatile demand environments.
The US Federal Motor Carrier Safety Administration shapes carrier eligibility and hours-of-service rules that directly constrain available capacity within digital freight platforms. The EU Green Deal emissions standards and Germany's KBA truck certification requirements are forcing fleet operators to accelerate electrification timelines, altering cost structures for logistics-as-a-service providers. China's MIIT data-localization mandates and SAMR platform governance rules create operational complexity for multinational SCaaS architectures spanning Asian manufacturing hubs. Stakeholders must evaluate whether to build compliant in-country nodes or cede regional market access to domestic competitors.
Market Dynamics
Cloud-native orchestration platforms are compressing implementation cycles from months to weeks, forcing logistics providers to restructure delivery models around subscription economics rather than perpetual license revenue.
Growth Catalysts
- EU Green Deal emissions standards:Fleet electrification mandates are accelerating demand for AI-powered route optimization that minimizes energy consumption across temperature-controlled pharmaceutical distribution networks.
- Pharmaceutical cold chain expansion:Biologics manufacturers in Germany and the United States are externalizing temperature-sensitive logistics to specialized providers with validated thermal packaging capabilities.
- API-first visibility architectures:Real-time data exchange between carrier TMS and shipper ERP systems is eliminating information latency that previously required safety stock buffers.
Market Restraints
- Data localization mandates:China's MIIT requirements force redundant infrastructure deployment, fragmenting platform economics across jurisdictional boundaries.
- Specialized talent scarcity:Cloud architecture expertise and supply chain analytics proficiency command premium compensation that erodes provider margins.
- Carrier capacity concentration:Digital freight platforms depend on fragmented owner-operator networks with high churn rates and limited asset-backed reliability.
Strategic Opportunities
- India's PLI scheme for logistics:Government incentives for warehousing automation are creating entry points for multi-tenant SCaaS platforms serving pharmaceutical exporters.
- Blockchain-IoT convergence:Immutable provenance tracking combined with sensor telemetry is opening subscription revenue streams in high-value pharmaceutical authentication.
- CSRD disclosure requirements:Scope 3 emissions reporting mandates are driving demand for carbon-accounting modules embedded within logistics orchestration software.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle on-premises installations resist API connectivity, requiring expensive middleware development for data synchronization.
- Cybersecurity certification timelines:SOC 2 Type II and ISO 27001 audits consume 9-14 months, delaying market entry for new platform entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Supply Chain As a Service (Scaas) Market |
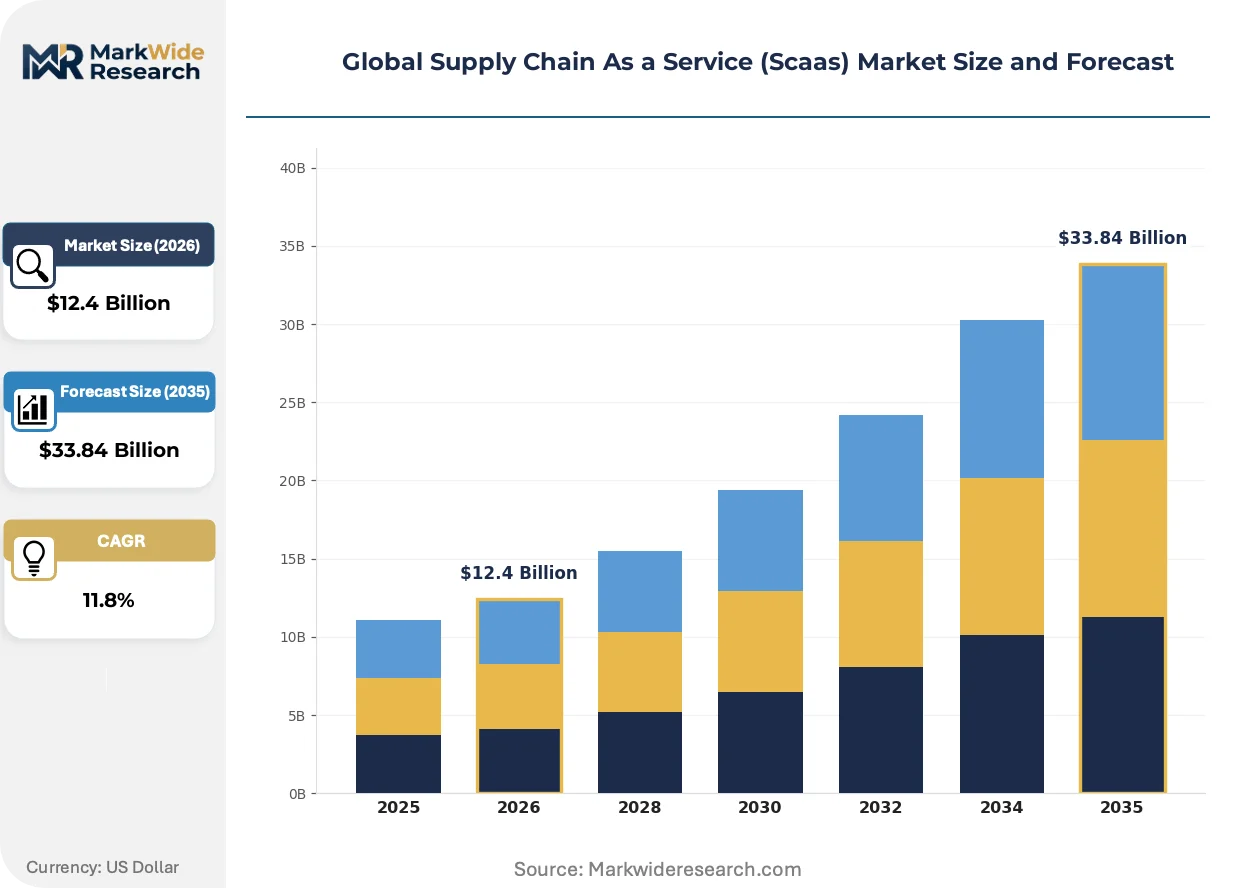
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.84 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Logistics Management, Inventory Optimization, Order Fulfillment, Freight Brokerage, Returns Management, Demand Forecasting Deployment Mode: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: Blockchain, IoT, Artificial Intelligence, Robotic Process Automation, Big Data Analytics End User: Manufacturing Firms, Wholesale Distributors, E-Commerce Enterprises, Third-Party Logistics Providers |
| Companies Covered | DHL Supply Chain, FedEx Corporation, UPS Supply Chain Solutions, Accenture, GEODIS, Ryder Supply Chain Solutions, project44, FourKites, Flexport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Supply Chain As a Service (Scaas) Market Shifts & Advancements
Real-time visibility infrastructure is becoming the default expectation rather than premium add-on, compressing competitive differentiation into predictive exception-handling capabilities and automated procurement execution.
Digital twin technology is digitizing physical warehouse and transportation networks into software-represented environments where scenario modeling occurs without operational disruption. Pharmaceutical distributors in Germany and the Netherlands are deploying these virtual replicas to test cold chain failure responses before live implementation. The technology is digitizing risk management from reactive incident response into proactive simulation-based preparedness.
The EU AI Act's risk-based classification framework is imposing documentation and transparency requirements on logistics algorithms that automate carrier selection and pricing. Providers serving European pharmaceutical shippers must now maintain algorithmic audit trails that explain automated decision pathways. High-risk applications in temperature-sensitive biologics distribution face conformity assessment procedures that extend platform certification timelines.
Shippers are consolidating vendor relationships around integrated platform providers that combine TMS, WMS, and freight payment functions under single contracts. This preference compression is marginalizing point-solution vendors that offer visibility or analytics without execution capabilities. Healthcare manufacturers in the United States are leading this consolidation, demanding unified data layers that eliminate reconciliation friction between planning and execution systems.
Global Supply Chain As a Service (Scaas) Market Segmentation
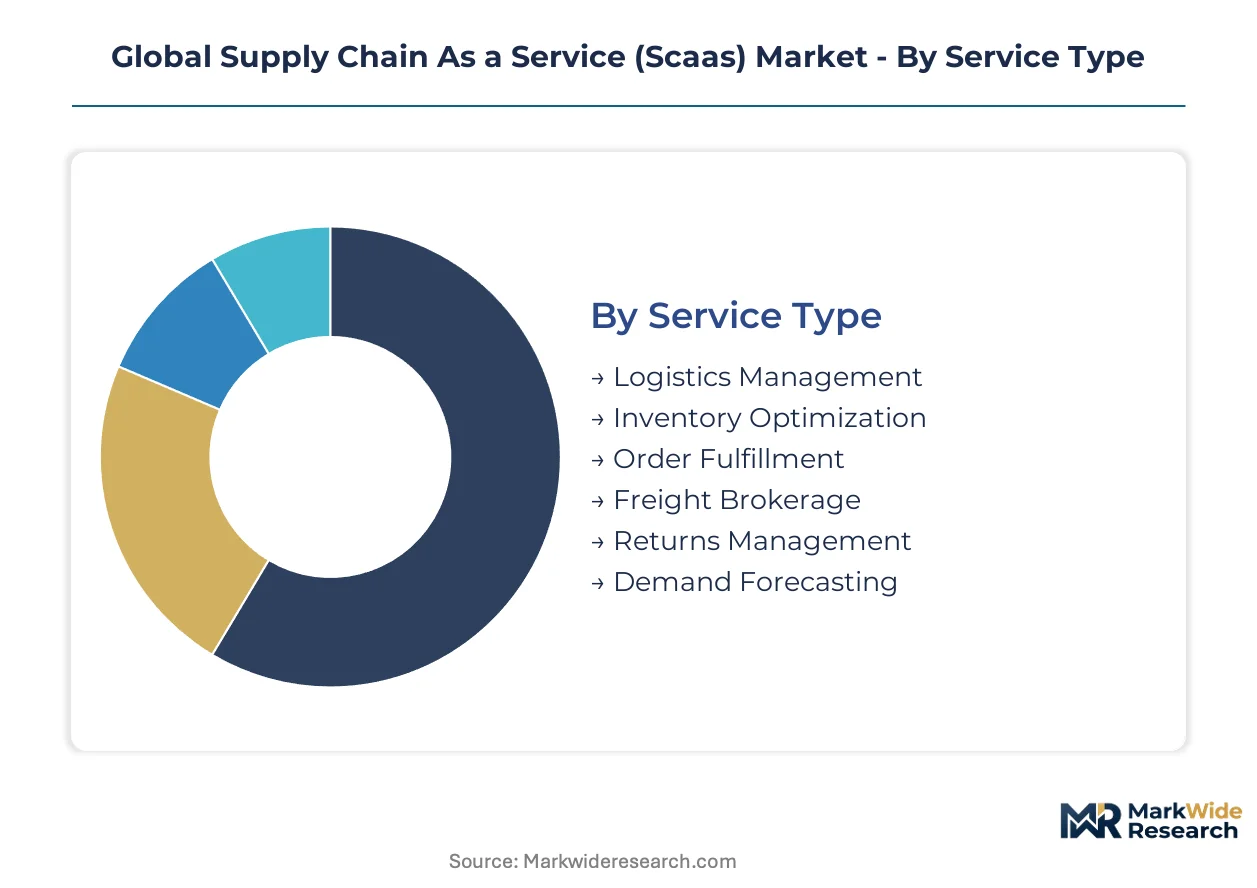
SCaaS segmentation reveals how specialized providers partition logistics functions across technology layers and operational domains. Distinct deployment architectures and end-user requirements create divergent margin profiles and implementation complexity across each category.
Service Type:
Mature execution services anchor revenue while emerging planning functions capture disproportionate investment flow.
- Logistics Management:Orchestrates transportation procurement, warehouse operations, and carrier performance management through unified control towers. Pharmaceutical manufacturers in Germany and the United States externalize these functions to avoid capital-intensive fleet ownership while maintaining GDP compliance for temperature-sensitive distribution.
- Inventory Optimization:Deploys multi-echelon algorithms that position safety stock across distributed nodes based on demand volatility and service-level constraints. E-commerce enterprises facing SKU proliferation leverage these capabilities to reduce carrying costs without sacrificing fulfillment velocity during peak seasons.
- Order Fulfillment:Manages pick-pack-ship operations and last-mile handoff coordination.
- Freight Brokerage:Matches shipper loads with carrier capacity through digital auction mechanisms and automated tendering.
- Returns Management:Handles reverse logistics workflows including inspection, refurbishment, and disposition routing.
- Demand Forecasting:Applies machine learning to external signals and historical patterns for replenishment timing.
Logistics Management handles the majority of throughput; Demand Forecasting is expanding most quickly on share.
Deployment Mode:
Cost tier separation distinguishes capital-intensive legacy installations from subscription-native alternatives.
- Cloud-Based:Delivers multi-tenant software via browser interfaces with API connectivity to shipper ERP systems and carrier TMS platforms. North American pharmaceutical distributors favor this model for rapid implementation without data center infrastructure commitments.
- On-Premises:Requires dedicated server installations behind corporate firewalls with perpetual licensing structures. Financial services and defense contractors in Germany maintain these deployments to satisfy data sovereignty requirements under GDPR and sector-specific confidentiality mandates.
- Hybrid:Combines cloud orchestration layers with on-premises execution nodes for sensitive transaction processing.
- Edge Computing:Deploys processing capability directly within warehouse and vehicle environments to minimize latency.
Cloud-Based deployments command the dominant revenue position; Edge Computing is climbing the fastest as IoT sensor density increases.
Technology:
Application maturity varies from production-grade automation to experimental ledger architectures.
- Artificial Intelligence:Powers predictive routing, dynamic pricing, and exception classification through neural networks trained on historical freight movements. EU AI Act documentation requirements are extending implementation timelines for European pharmaceutical shippers deploying automated carrier selection.
- IoT:Generates real-time telemetry from refrigerated containers, warehouse environmental sensors, and vehicle telematics units. Cold chain operators in the Netherlands integrate this data with digital twin simulations to pre-validate temperature excursion responses.
- Blockchain:Creates immutable provenance records for high-value pharmaceutical authentication.
- Robotic Process Automation:Automates repetitive data entry and document processing workflows.
- Big Data Analytics:Aggregates disparate logistics datasets for network optimization and cost benchmarking.
Artificial Intelligence absorbs the largest share of provider R&D investment; Blockchain is gaining share fastest in pharmaceutical traceability applications.
End User:
Customer type segmentation reflects divergent complexity tolerance and integration sophistication.
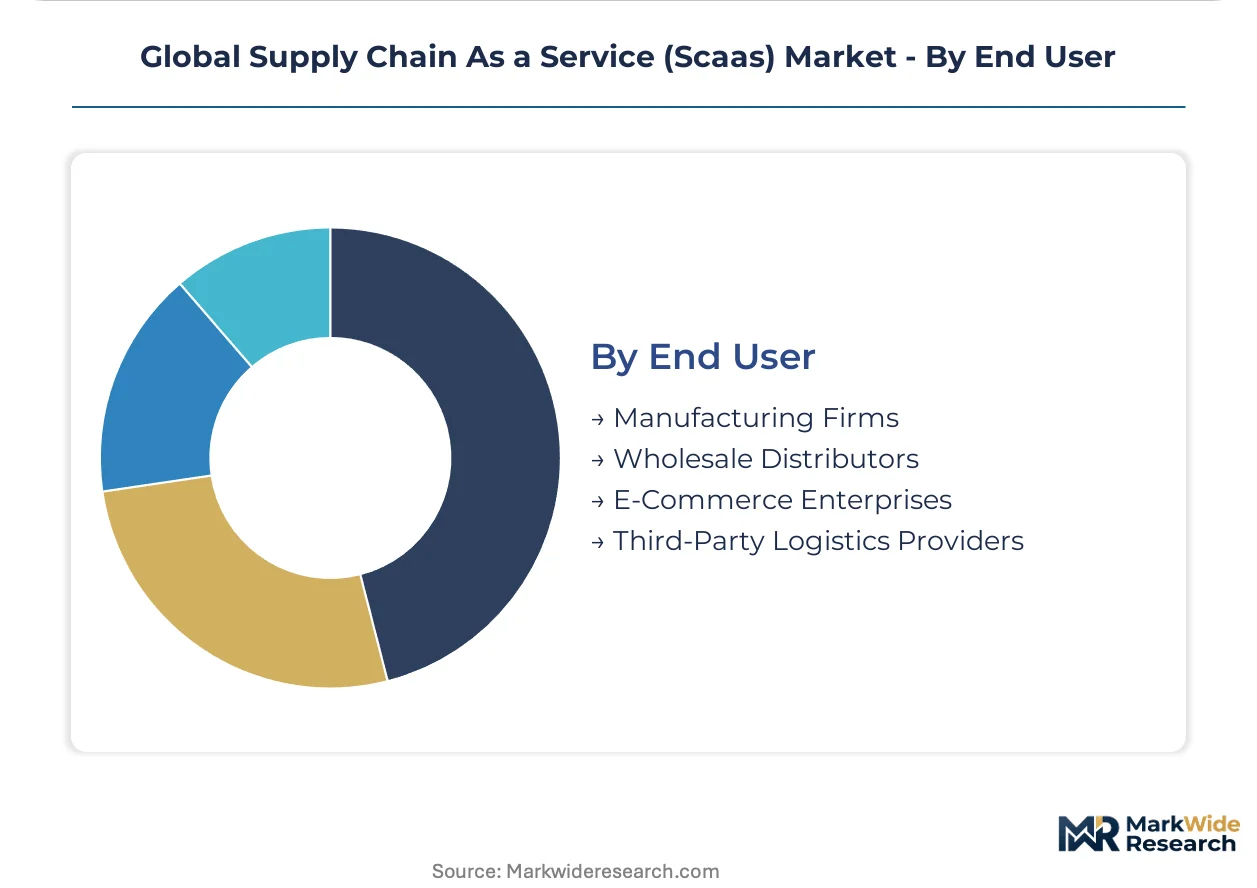
- Manufacturing Firms:Require synchronized inbound material flows and outbound finished goods distribution with production scheduling systems. Automotive suppliers around Stuttgart leverage SCaaS platforms to coordinate just-in-sequence deliveries across tiered supplier networks.
- Third-Party Logistics Providers:White-label platform capabilities to serve downstream shipper clients with differentiated service tiers. These intermediaries demand modular architectures that support rapid reconfiguration for contract-specific requirements.
- E-Commerce Enterprises:Prioritize fulfillment velocity and returns velocity over cost minimization.
- Wholesale Distributors:Balance inventory availability with working capital efficiency across fragmented customer bases.
Manufacturing Firms contribute the dominant transaction volume; E-Commerce Enterprises are expanding most aggressively on platform spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container terminals anchor European SCaaS demand by processing pharmaceutical cold chain volumes that require synchronized inland distribution networks.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts externalize temperature-sensitive logistics to avoid capital-intensive fleet ownership. FDA GDP guidelines and the Drug Supply Chain Security Act mandate serialized tracking that cloud-native platforms automate. The I-95 corridor from Boston to Washington anchors contract logistics concentration for biologics distribution.
Germany
Automotive suppliers around Stuttgart coordinate just-in-sequence deliveries through multi-tenant platforms. KBA truck certification requirements and EU Green Deal emissions standards accelerate fleet electrification timelines for logistics providers. Industrial clusters in Munich drive AI-enabled freight brokerage adoption for precision component flows.
China
E-commerce enterprises in Shanghai and Shenzhen demand fulfillment velocity that compresses warehouse automation implementation cycles. MIIT data-localization mandates force redundant infrastructure deployment across provincial boundaries. The Yangtze River Delta concentration of pharmaceutical manufacturers creates demand for compliant cloud nodes under SAMR platform governance.
India
Pharmaceutical exporters in Maharashtra and Gujarat leverage government incentives for warehousing automation under the PLI scheme. CDSCO cold chain requirements for vaccine distribution drive validated thermal packaging investments. The Mumbai-Pune industrial corridor anchors multi-tenant platform adoption for international outbound logistics.
Netherlands
Distribution operators in Amsterdam and Rotterdam deploy digital twin simulations to pre-validate cold chain failure responses. EMA pharmacovigilance requirements for temperature excursion documentation favor API-first visibility architectures. The Randstad logistics cluster concentrates pharmaceutical consolidation and cross-docking automation investments.
Global Supply Chain As a Service (Scaas) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in visibility and execution modules. The vendor base separates into consolidated logistics conglomerates with physical asset footprints and pure-play software providers with API-native architectures. Three archetypes dominate: asset-heavy contract logistics operators, digital freight orchestration platforms, and enterprise consulting integrators. Competitive dynamics center on M&A activity absorbing point-solution vendors and strategic partnerships bridging software stacks with carrier networks.
Among asset-backed operators, DHL Supply Chain and FedEx Corporation exemplify the integrated physical-digital model that healthcare manufacturers prefer for GDP-compliant distribution. project44 occupies a position within the visibility tier as an API-first platform connecting disparate carrier systems. These three entities represent the structural tension between owning warehouse networks and renting software connectivity that defines vendor selection criteria across pharmaceutical and automotive verticals.
| Leading Market Players |
|---|
| DHL Supply Chain |
| FedEx Corporation |
| UPS Supply Chain Solutions |
| Accenture |
| GEODIS |
| Ryder Supply Chain Solutions |
| project44 |
| FourKites |
| Flexport |
| Others |
Supply & Pricing Matrix
Stuttgart's automotive supplier cluster concentrates cloud-native platform capacity, granting German SCaaS providers pricing leverage over pharmaceutical manufacturers seeking GDP-compliant cold chain orchestration. Subscription economics displace perpetual licensing as fleet electrification mandates compress implementation timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the SCaaS market. Certification grade under EU GDP and FDA guidelines, alongside volume scale for multi-node deployments, drive price differentiation. Cost compression in standard tiers is intensifying because carrier capacity fragmentation erodes platform margins. E-commerce enterprises exhibit highest price sensitivity due to thin fulfillment economics, while pharmaceutical manufacturers accept premium pricing for validated thermal packaging capabilities.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for SCaaS platform hardware. Cloud infrastructure draws from server manufacturing in Taiwan, China, and South Korea. IoT sensor modules and edge computing chipsets feed from semiconductor fabrication concentrated in Taiwan and South Korea. Single-source vulnerability in advanced node semiconductors threatens platform scalability. Distribution runs through hyperscaler data centers in Frankfurt, Virginia, and Singapore anchoring regional service delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCaaS market is recovering from cyclical compression in logistics technology spending, with pharmaceutical cold chain expansion driving replacement demand across European and North American industrial corridors.
For Market Incumbents: Harden API-first architectures against emerging pure-play visibility vendors by embedding freight payment and carbon accounting modules within unified control towers. Accelerate backward integration into warehouse automation hardware to defend margin position against asset-light competitors. Prioritize SOC 2 Type II certification investments to extend compliance moats. For New Entrants and Emerging Players: India's PLI scheme for warehousing automation offers underpenetrated entry points for multi-tenant platforms serving pharmaceutical exporters in Maharashtra and Gujarat. Target mid-market manufacturing firms in the Mumbai-Pune corridor with modular TMS-WMS bundles. Lead with rapid implementation guarantees against incumbent deployment timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native visibility platforms with embedded execution capabilities. Long-term viability across the analysis window favors providers demonstrating carrier network density and pharmaceutical vertical penetration. Monitor EU AI Act conformity assessment timelines as an inflection indicator for European platform certification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying TMS, WMS, and freight payment under single contracts eliminates reconciliation friction for healthcare manufacturers. |
| Geographic Expansion | Establishing compliant cloud nodes under China's MIIT mandates preserves access to Yangtze River Delta pharmaceutical manufacturing. |
| Acquisition of Specialist Firm | Absorbing point-solution visibility vendors addresses shipper consolidation preferences around integrated providers. |
| Strategic Partnership | Aligning with electrified fleet operators under EU Green Deal standards secures capacity for temperature-controlled distribution. |
| Product Launch | Introducing carbon-accounting modules embedded within orchestration software addresses CSRD Scope 3 disclosure requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, EU regulatory databases, and hyperscaler capex disclosures. Interviews with supply chain directors, logistics procurement leads, platform engineers, and carrier operations managers informed demand-side validation. Bottom-up sizing of segment deployments triangulates against top-down market aggregation.
Forecast inputs incorporate deployment mode transitions, technology adoption curves, and end-user vertical expansion across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, technology layer, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for policy intervention effects, with pharmaceutical cold chain requirements and fleet electrification timelines as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-heavy logistics conglomerates or hyperscaler cloud entrants would shift outcomes. Macroeconomic contraction in European manufacturing, accelerated data localization mandates, or breakthroughs in autonomous freight matching could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Shared Services Center Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
Proactive Services Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Helpdesk Management Market