
 Managed Services Market | 2026-2036
Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Services Market Analysis
Cloud-certified engineering talent is rotating toward managed security and hybrid infrastructure roles faster than enterprises can build comparable in-house benches. Teleperformance leverages its geographic footprint to anchor delivery centers across multiple regulatory zones. Genpact sustains competitive intensity through deep process automation expertise in finance and supply chain verticals. Alorica specializes in customer-experience-managed services, occupying a distinct niche against technology-heavy competitors.
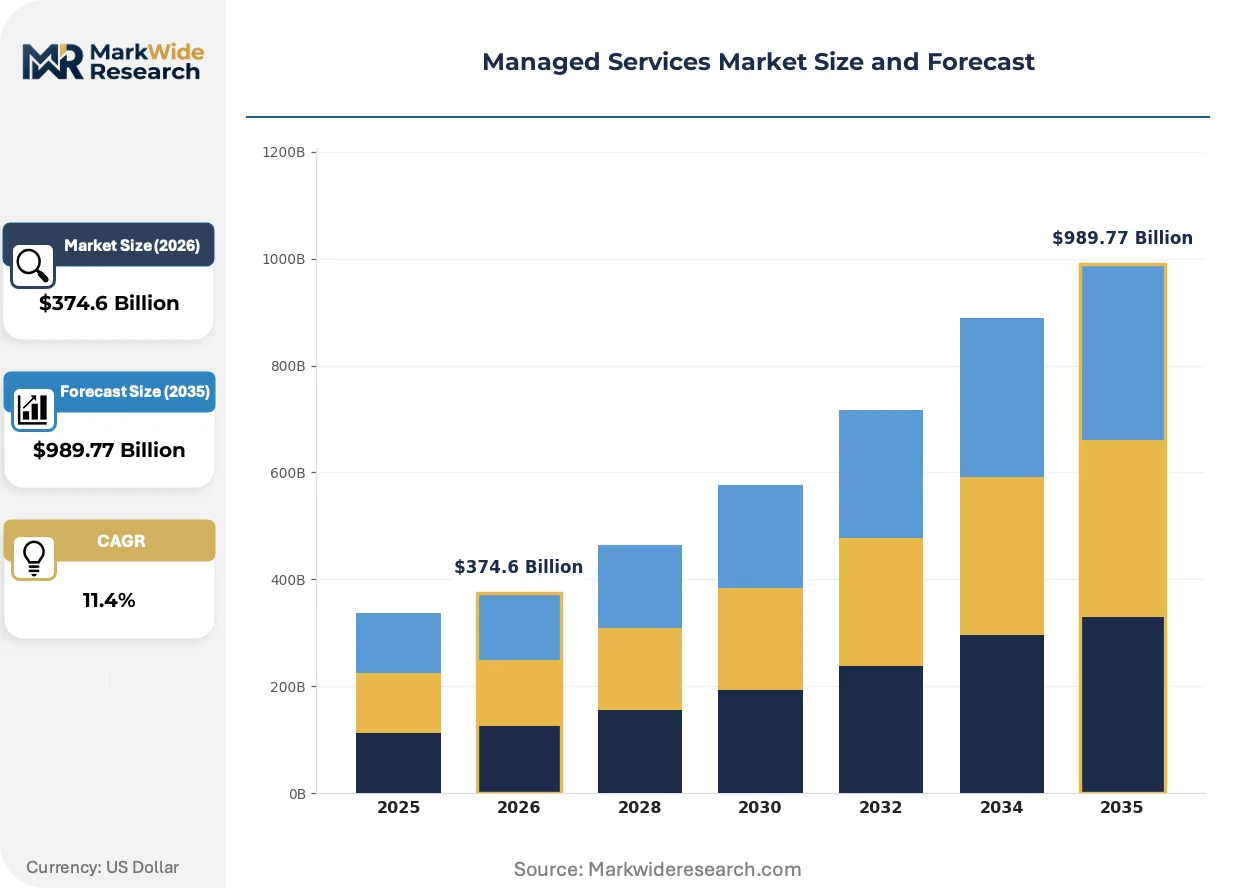
Managed services encompass the ongoing administration, monitoring, and optimization of IT infrastructure, applications, and business processes by external specialists operating under service-level agreements with defined uptime, response-time, and security parameters. These arrangements transfer operational risk from client organizations while embedding continuous technical modernization through vendor accountability. Security services and cloud-based deployment configurations represent the fastest-expanding margin pools, driven by ransomware frequency and multi-cloud complexity. Network management retains the largest revenue base among service types, though growth rates trail application management as enterprises containerize legacy workloads.
FDA cybersecurity guidance for connected medical devices, SEC disclosure rules on material cybersecurity incidents, and EU NIS2 requirements for critical infrastructure outsourcing are elevating vendor certification burdens and contract liability terms. HIPAA business associate agreements and GDPR processor obligations further constrain data residency and breach notification protocols for healthcare and cross-border engagements. Stakeholders must weigh specialization depth against platform breadth when selecting partners capable of absorbing escalating compliance accountability.
Market Dynamics
Cloud complexity is fragmenting enterprise IT capabilities faster than internal engineering benches can rebuild, forcing mid-market organizations toward external accountability structures that embed continuous modernization clauses into multi-year service agreements.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators across energy, transport, and healthcare must now vet third-party providers against mandatory cybersecurity benchmarks, expanding addressable contract value for certified managed security services.
- Containerization:Enterprises migrating legacy monoliths to Kubernetes environments require specialized orchestration expertise that internal teams rarely retain, accelerating demand for application management outsourcing.
- Ransomware frequency:Incident response retainers and 24/7 security operations center coverage have become non-negotiable procurement criteria for financial services and healthcare buyers.
Market Restraints
- Certified talent scarcity:AWS, Azure, and GCP-certified engineers command compensation premiums that compress provider margins below sustainable thresholds for undifferentiated infrastructure monitoring.
- Data residency mandates:GDPR processor obligations and national data localization laws fragment delivery architecture, requiring redundant infrastructure footprints that dilute economies of scale.
- Vendor consolidation risk:Mid-tier providers dependent on single hyperscaler partnerships face contract renegotiation vulnerability when platform providers vertically integrate into adjacent services.
Strategic Opportunities
- India:The country's PLI scheme for IT hardware and data center infrastructure creates localized delivery capacity that satisfies data sovereignty requirements for European and Middle Eastern buyers.
- FDA cybersecurity guidance:Connected medical device manufacturers must now document third-party security management in premarket submissions, opening specialized healthcare vertical contracts.
- FinOps convergence:Cloud cost optimization tooling integrated with managed services contracts addresses buyer frustration with unpredictable consumption billing, creating stickier revenue models.
Industry Challenges
- Multi-cloud credential sprawl:Engineers must maintain concurrent certifications across AWS, Azure, and GCP platforms, extending onboarding timelines and elevating training expenditure.
- Legacy integration debt:Mainframe and AS/400 systems in financial services and insurance resist API-first modernization, requiring expensive bespoke middleware that erodes standardization benefits.
- Breach liability allocation:Cyber insurance underwriters now demand granular service-level agreement language on incident response timelines, complicating contract negotiation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Services Market |
| Market Size in 2026 | $374.6 Billion |
| Market Size in 2035 | $989.77 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Application Management, Security Services, Data Backup End User: SMBs, Large Enterprises, Government Agencies, Educational Institutions Deployment: On-premises, Cloud-based, Hybrid, Managed Infrastructure Industry Vertical: Healthcare, Retail, Finance, Telecommunications |
| Companies Covered | Foundever, Alorica, Teleperformance, Conduent, Genpact, Concentrix, TTEC, Xavor Corporation, TaskUs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Services Market Emerging Trajectories
Operational technology convergence with enterprise IT is dissolving traditional air-gap security models and forcing managed services providers to absorb accountability for industrial control environments previously outside their scope.
Zero-trust network architecture is fragmenting perimeter-based security service portfolios. Managed security providers now engineer microsegmentation policies for containerized workloads that financial services firms deploy across hybrid cloud estates. This technology compression is collapsing standalone firewall management contracts into comprehensive identity-centric service bundles.
The EU AI Act's risk classification framework for automated decision-making systems imposes documentation and human oversight mandates on financial services algorithm deployments. Providers serving EU-based banks must now maintain model governance capabilities that trace AI system lineage and monitor drift. German and French regulators are already enforcing these provisions through on-site audits of third-party service centers.
Consumption-based pricing models are displacing fixed-fee infrastructure management contracts as buyers demand cost alignment with actual cloud resource utilization. Mid-market enterprises in the United States are piloting FinOps-embedded managed services that tie provider compensation to realized savings against committed spend baselines. This procurement evolution is compressing traditional three-year agreements into rolling quarterly engagements with performance clawback provisions.
Managed Services Market Segmentation
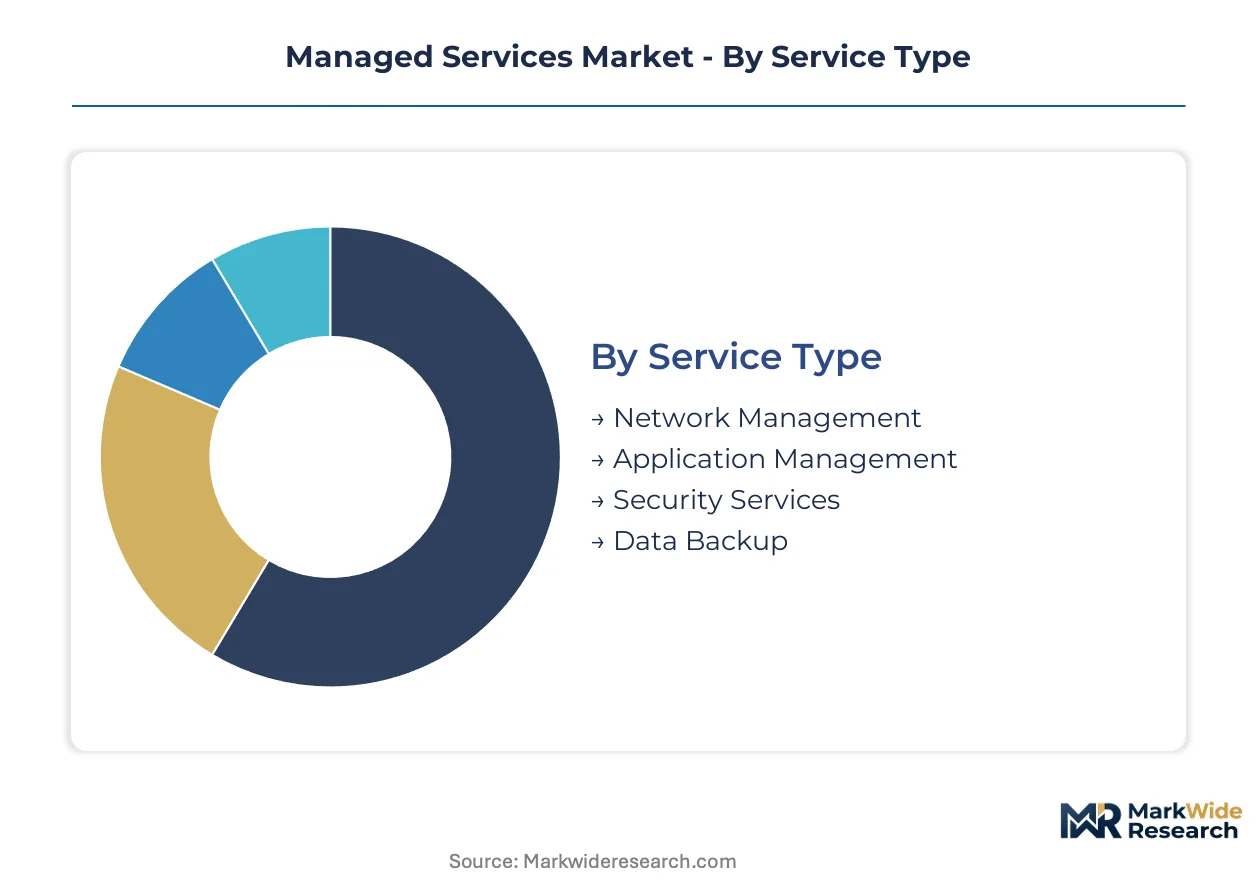
Managed services procurement fractures across technical capabilities, organizational scale, and regulatory exposure. Buyers select segments based on internal engineering deficits and compliance liability transfer requirements.
Service Type:
Substitution pressure concentrates in commoditized infrastructure monitoring as hyperscalers bundle basic tooling into platform subscriptions.
- Network Management:Backbone connectivity administration spanning WAN optimization, SD-WAN orchestration, and latency-sensitive traffic engineering. Demand concentrates in United States financial services firms modernizing branch infrastructure, constrained by legacy MPLS contract rollover timelines.
- Security Services:Continuous threat detection, incident response retainers, and compliance-aligned security operations center staffing. United States healthcare systems drive procurement acceleration following FDA cybersecurity guidance for connected devices.
- Application Management:Container orchestration and legacy middleware maintenance for hybrid cloud estates.
- Data Backup:Immutable storage architectures and ransomware recovery orchestration.
Network Management anchors the volume base while Security Services gains share at the steepest rate.
End User:
Cost tier stratification separates turnkey solutions for resource-constrained buyers from bespoke engineering for complex environments.
- Large Enterprises:Multi-year agreements embedding continuous modernization clauses and dedicated engineering pods. United States mid-market enterprises expanding hybrid cloud footprints drive contract value growth, constrained by certified talent scarcity across AWS and Azure specializations.
- SMBs:Standardized service catalogs with limited customization and consumption-based pricing tiers. Demand clusters in professional services and regional healthcare networks seeking HIPAA-aligned backup and endpoint protection without internal security benches.
- Government Agencies:FedRAMP-authorized offerings with classified data handling protocols.
- Educational Institutions:FERPA-compliant student data management and stretched IT staffing augmentation.
SMBs dominate transaction velocity while Large Enterprises capture the highest per-contract value expansion.
Deployment:
Application criticality determines residency decisions, with latency-sensitive workloads resisting full cloud migration despite vendor pressure.
- Cloud-based:Fully outsourced infrastructure on hyperscaler platforms with shared responsibility models. United States retail and media buyers concentrate demand, driven by seasonal elasticity requirements and OpEx preference over capital-intensive data center builds.
- Hybrid:Orchestrated workloads spanning on-premises private cloud and public hyperscaler resources. Financial services firms in United States and Germany anchor adoption, constrained by GDPR processor obligations and derivatives trading latency floors.
- On-premises:Dedicated hardware administration for air-gapped or sovereignty-sensitive environments.
- Managed Infrastructure:Colocation and bare-metal provisioning with provider-operated virtualization layers.
Hybrid deployment captures the steepest expansion trajectory as containerization dissolves binary cloud-versus-data-center decisions.
Industry Vertical:
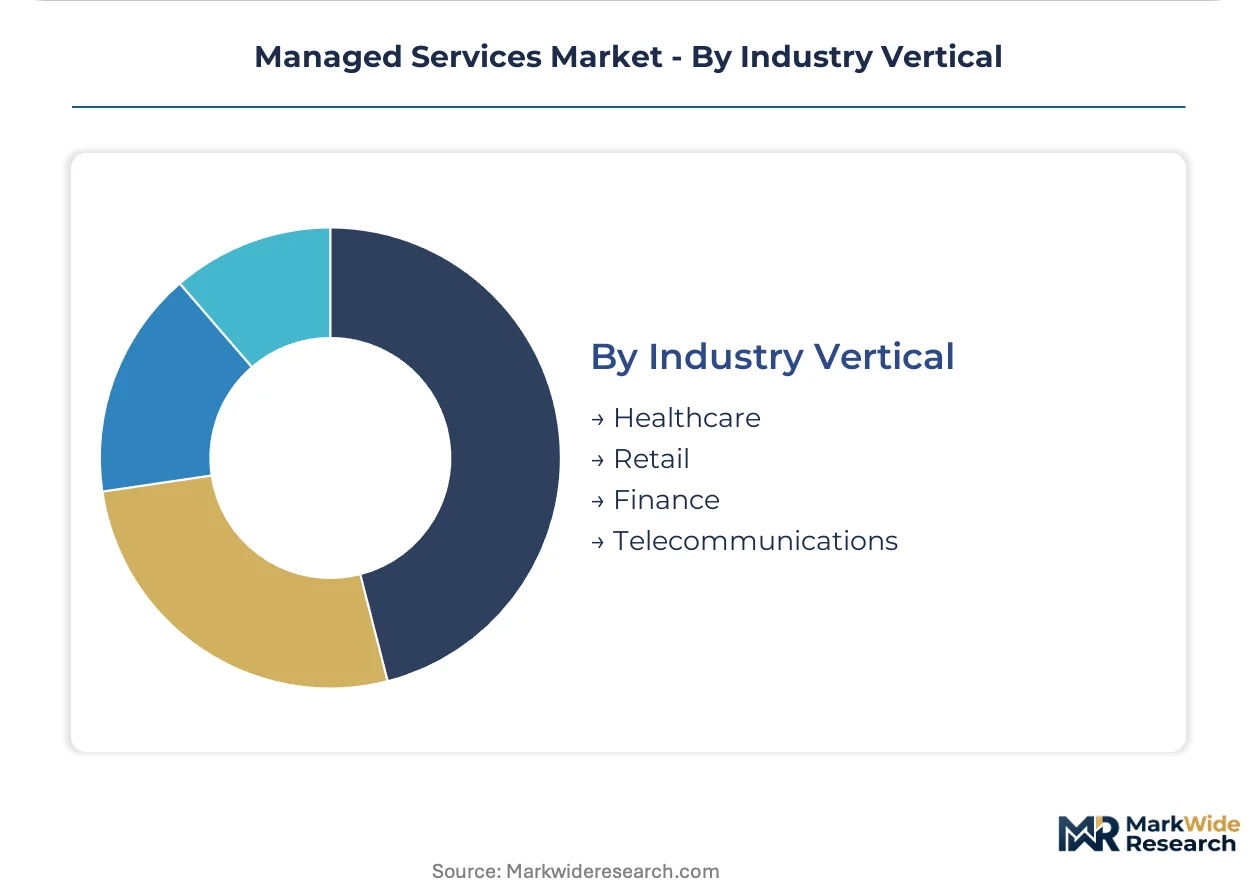
Margin concentration follows regulatory burden intensity, with healthcare and finance commanding premium pricing for compliance-embedded service tiers.
- Healthcare:HIPAA business associate agreements, FDA cybersecurity documentation, and connected medical device lifecycle management. United States hospital systems and medical device manufacturers drive specialized contract growth following premarket submission requirements for third-party security management.
- Finance:SEC disclosure alignment, PCI-DSS attestation, and algorithm governance for EU AI Act compliance. German and French banking regulators enforce model lineage documentation through on-site audits of third-party service centers.
- Retail:Seasonal demand elasticity and omnichannel transaction integrity.
- Telecommunications:Network function virtualization and subscriber data platform administration.
Healthcare anchors contract value per seat while Finance demonstrates the fastest vertical expansion rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure rules on material cybersecurity incidents are tightening procurement criteria for managed security services across United States financial institutions. Cloud complexity and regulatory fragmentation are redirecting enterprise IT spending toward external accountability structures in multiple jurisdictions.
United States
Mid-market enterprises in financial services and healthcare are expanding hybrid cloud management contracts to address internal engineering deficits. FDA cybersecurity guidance for connected medical devices mandates third-party security documentation in premarket submissions. Hospital systems in Boston and medical device manufacturers in Minneapolis are driving specialized healthcare vertical contracts.
Germany
Industrial manufacturers and automotive suppliers require managed security operations centers to satisfy EU NIS2 Directive cybersecurity benchmarks for critical infrastructure. German banking regulators enforce model lineage documentation and human oversight mandates under EU AI Act provisions through on-site audits. Frankfurt's financial services cluster anchors demand for algorithm governance and compliance-embedded service tiers.
United Kingdom
Professional services firms and regional healthcare networks are procuring HIPAA-aligned backup and endpoint protection without internal security benches. GDPR processor obligations constrain data residency and breach notification protocols for cross-border engagements. London's insurance and fintech corridor concentrates demand for incident response retainers and 24/7 security coverage.
India
The country's PLI scheme for IT hardware and data center infrastructure creates localized delivery capacity satisfying data sovereignty requirements for European and Middle Eastern buyers. Cloud-certified engineering talent rotates toward managed security and hybrid infrastructure roles faster than enterprises can build comparable in-house benches. Bangalore and Hyderabad anchor delivery centers serving multi-regional compliance zones.
France
French banking regulators are enforcing EU AI Act provisions through on-site audits of third-party service centers, elevating vendor certification burdens. Algorithm governance capabilities tracing AI system lineage and monitoring drift have become procurement prerequisites for financial services buyers. Paris anchors specialized contracts for automated decision-making system documentation and human oversight mandates.
Managed Services Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation concentrating in compliance-embedded service capabilities and geographic delivery footprints. The vendor base organizes around three strategic archetypes: technology-heavy infrastructure operators, customer-experience specialists, and process-automation verticalists. Dominant competitive moves include geographic expansion across multiple regulatory zones and portfolio diversification into adjacent security and cloud optimization services.
Within the customer-experience specialist tier, Alorica occupies a distinct niche against technology-heavy competitors through deep expertise in customer-experience-managed services. Teleperformance leverages its geographic footprint to anchor delivery centers across multiple regulatory zones. Genpact exemplifies the process-automation verticalist archetype through sustained competitive intensity in finance and supply chain verticals. These three companies represent alternative positioning strategies against consolidated infrastructure leaders.
| Leading Market Players |
|---|
| Foundever |
| Alorica |
| Teleperformance |
| Conduent |
| Genpact |
| Concentrix |
| TTEC |
| Xavor Corporation |
| TaskUs |
| Others |
Supply Flow & Price Mechanics
Ninety-day onboarding timelines for AWS-certified engineers concentrate pricing power with established providers holding pre-cleared talent pools, while compressing margins for challengers scrambling to match service-level commitments. This lead-time asymmetry reinforces tiered contract structures where incumbents capture premium multi-year engagements and regional specialists compete on price for standardized monitoring tiers.
Pricing Analysis
United States-Germany pricing spreads of 40-60% reflect divergent compliance-embedding costs and data residency infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized federal contracts from mid-market hybrid cloud packages and SMB endpoint protection bundles. Pricing pressure stems from hyperscaler vertical integration into adjacent security services, eroding standalone infrastructure monitoring margins. SMB healthcare networks exhibit highest price sensitivity, while financial services firms prioritize liability transfer over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for hardware-dependent delivery centers, particularly affecting Indian PLI-subsidized infrastructure builds. Supply concentrates in India, Poland, and Philippines for certified engineering talent, with Germany and United States anchoring high-touch compliance consulting. Raw material dependencies span server hardware from Taiwan, network equipment from South Korea, and facility power infrastructure from China. Single-source vulnerability concentrates in hyperscaler platform partnerships. Distribution runs through direct enterprise sales teams for large contracts and channel partners for SMB segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The managed services market tracks enterprise IT capital expenditure cycles, with recovery signals emerging from mid-market cloud migration backlogs accumulated during recent interest rate compression.
For Market Incumbents: Consolidate certified talent pools through targeted acquisition of boutique AWS and Azure-specialized shops in Bangalore and Warsaw, defending against hyperscaler direct engagement models. Deepen vertical integration into FinOps tooling and algorithm governance capabilities to capture EU AI Act-mandated service tiers. Prioritize FedRAMP authorization investments to anchor federal contract pipelines. For New Entrants and Emerging Players: Lead with container orchestration expertise targeting German automotive suppliers struggling with EU NIS2 Directive compliance deadlines, a segment incumbent providers underserve due to legacy integration complexity. Develop rapid-certification partnerships with regional technical universities to bypass talent scarcity constraints. Position through outcome-based pricing tied to realized cloud cost reductions. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-embedded infrastructure play because regulatory fragmentation across FDA, SEC, and EU AI Act regimes creates durable moats for certified providers. Target mid-tier specialists with established healthcare or financial services vertical depth and existing regulatory audit relationships. Watch hyperscaler partnership renegotiation clauses as inflection signals for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Talent Acquisition | AWS and Azure-cleared engineering teams in India and Eastern Europe anchor multi-regional delivery capacity. |
| Vertical Compliance Integration | FDA cybersecurity documentation capabilities open specialized healthcare contracts with medical device manufacturers. |
| FinOps Platform Embedding | Cloud cost optimization tooling creates stickier revenue models tied to consumption savings realization. |
| EU AI Act Service Tier Development | Algorithm governance and model lineage documentation satisfy French and German banking regulator audit requirements. |
| Hyperscaler Partnership Diversification | Multi-cloud credentials reduce contract renegotiation vulnerability when platform providers expand adjacent services. |
Methodological Framework
Desk research of hyperscaler certification databases, EU regulatory filings, and healthcare procurement records preceded structured interviews with managed services procurement officers, cloud engineering directors, compliance audit leads, and channel sales executives. Primary fieldwork across United States, Germany, and India validated secondary findings on talent rotation patterns and contract structuring norms. Bottom-up segment sizing triangulated against top-down IT services spending benchmarks.
Variance decomposition across service type, deployment model, and vertical regulatory intensity shaped analytical framework construction over the projection horizon. Modeled dimensions encompass network management, security services, application management, and data backup segments crossed with cloud, hybrid, and on-premises deployment configurations. CAGRs derived from elasticity-adjusted adoption curves and compliance-mandated replacement cycles. Forecast inputs incorporated FDA premarket submission timelines and EU NIS2 Directive enforcement phasing.
Forecasts assume regulatory continuity in FDA medical device cybersecurity guidance and EU AI Act risk classification frameworks; material policy shifts would require re-modeling. Model boundaries exclude pure professional services arrangements lacking recurring revenue structures and hardware resale without operational accountability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Employee Engagement Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
IT Staffing Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Field Service Management Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Shared Services Market
Enterprise Services
Enterprise Service Bus Software Market