
 North America Public Sector Consulting and Advisory Services Market | 2026-2036
North America Public Sector Consulting and Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Public Sector Consulting and Advisory Services Market Insights
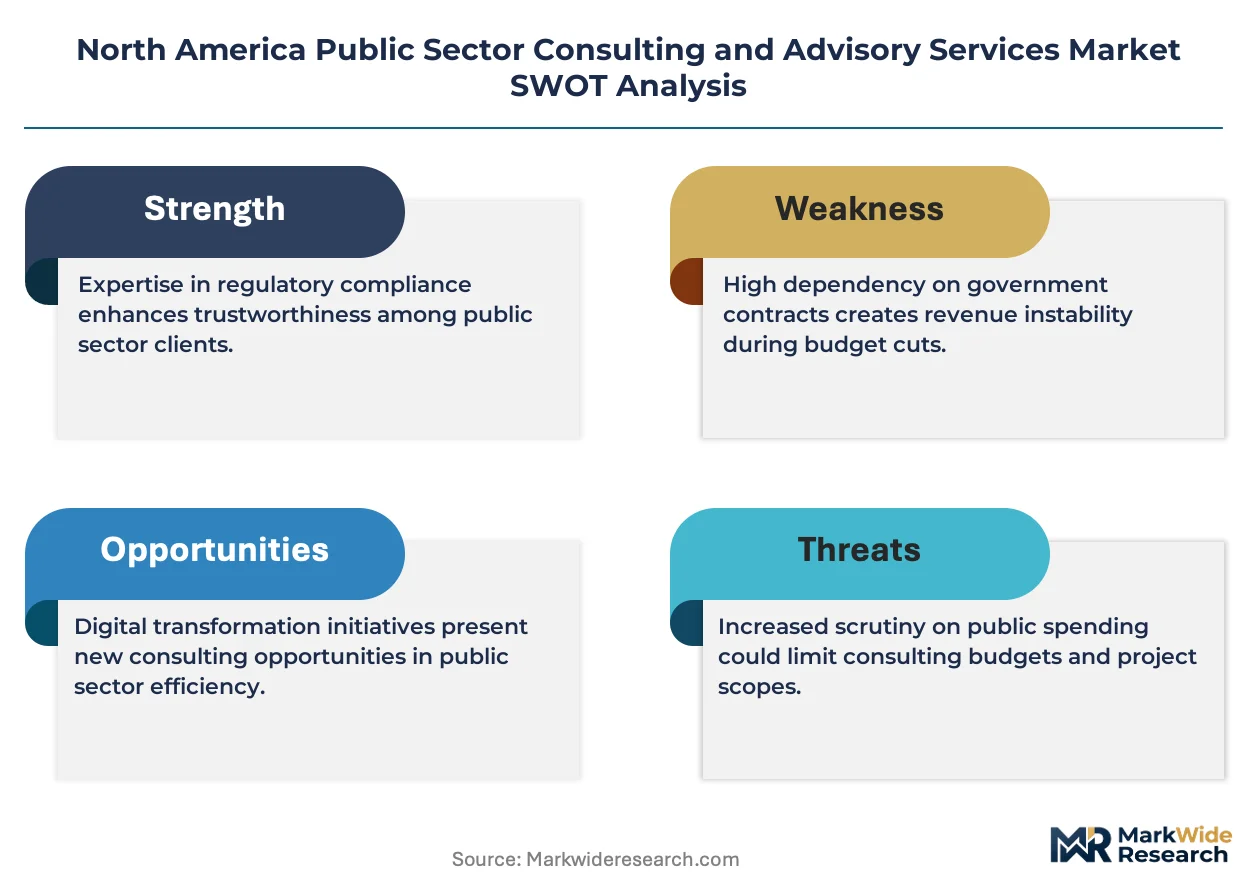
The gap between premium strategy boutiques and commodity implementation shops is hardening in North American public sector consulting. Deloitte Consulting LLP leverages its scale across federal health and defense accounts to dominate large-scale transformation programs. Booz Allen Hamilton anchors its position through deep security clearances and intelligence community relationships that competitors struggle to replicate. EY competes aggressively on price in state and municipal advisory work where procurement rules favor incumbent auditors.
Public sector consulting and advisory services encompass structured problem-solving engagements where external experts diagnose organizational challenges, design intervention frameworks, and oversee implementation for government entities; engagements typically blend quantitative policy modeling with qualitative stakeholder facilitation to improve service delivery outcomes. Strategic planning engagements command the highest fee premiums because they shape multi-year capital allocation decisions at the federal level. Operational improvement work spreads fastest across mid-sized municipalities seeking to stretch constrained tax bases. Process optimization and change management assignments carry thinner margins but generate recurring revenue through renewable task orders.
The Federal Acquisition Regulation, Canada's Treasury Board contracting policies, and state-level procurement codes collectively determine how consultants qualify for government business and what cost structures prevail. The Office of Management and Budget's guidance on evidence-based policymaking pushes agencies toward outcome-linked consulting contracts rather than open-ended staff augmentation. Stakeholders must monitor how federal grant conditions evolve, as each new funding tranche reshapes which service lines and engagement models agencies can deploy.
Market Dynamics
Federal grant conditions under the Infrastructure Investment and Jobs Act are concentrating consulting demand around transportation and healthcare modernization mandates. State procurement offices now prioritize outcome-linked contracts over staff augmentation, compressing vendor selection timelines and reshaping fee structures.
Growth Catalysts
- IIJA Funding Tranches:The Infrastructure Investment and Jobs Act directs capital toward state transportation agencies, creating sustained demand for program management and engineering advisory services across the United States.
- Evidence-Based Mandates:The Office of Management and Budget's guidance on outcome-linked contracting pushes federal agencies toward performance-based consulting engagements rather than time-and-materials arrangements.
- Municipal Fiscal Stress:Mid-sized cities across Canada and the United States seek operational improvement advisory to stretch constrained property tax bases and deferred maintenance backlogs.
Market Restraints
- Security Clearance Bottlenecks:The intelligence community and defense agencies require personnel with active clearances, creating a supply scarcity that limits vendor pool depth for sensitive federal work.
- Procurement Code Rigidity:State-level competitive bidding rules and Canada's Treasury Board contracting policies favor incumbent auditors, raising switching costs for new advisory entrants.
- Federal Acquisition Regulation Complexity:FAR compliance costs and cost-accounting standards requirements impose overhead burdens that squeeze margins on fixed-price engagements.
Strategic Opportunities
- Healthcare Administration Modernization:State Medicaid agencies and provincial health authorities seek eligibility system upgrades and fraud detection analytics, opening new service lines for data-intensive advisory.
- Climate Resilience Planning:Municipal infrastructure vulnerability assessments represent underpenetrated terrain where engineering and policy advisory capabilities converge.
- Interoperability Standards:Federal push for cross-agency data sharing creates demand for enterprise architecture consulting that bridges legacy mainframes and cloud-native platforms.
Industry Challenges
- Talent Retention in Public Sector Practice:Consulting firms struggle to retain staff with security clearances and domain expertise in federal health and defense, as commercial sector compensation premiums widen.
- Legacy System Integration Complexity:State agencies operate decades-old eligibility and financial management systems that resist modernization, extending implementation timelines and eroding project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Public Sector Consulting and Advisory Services Market |
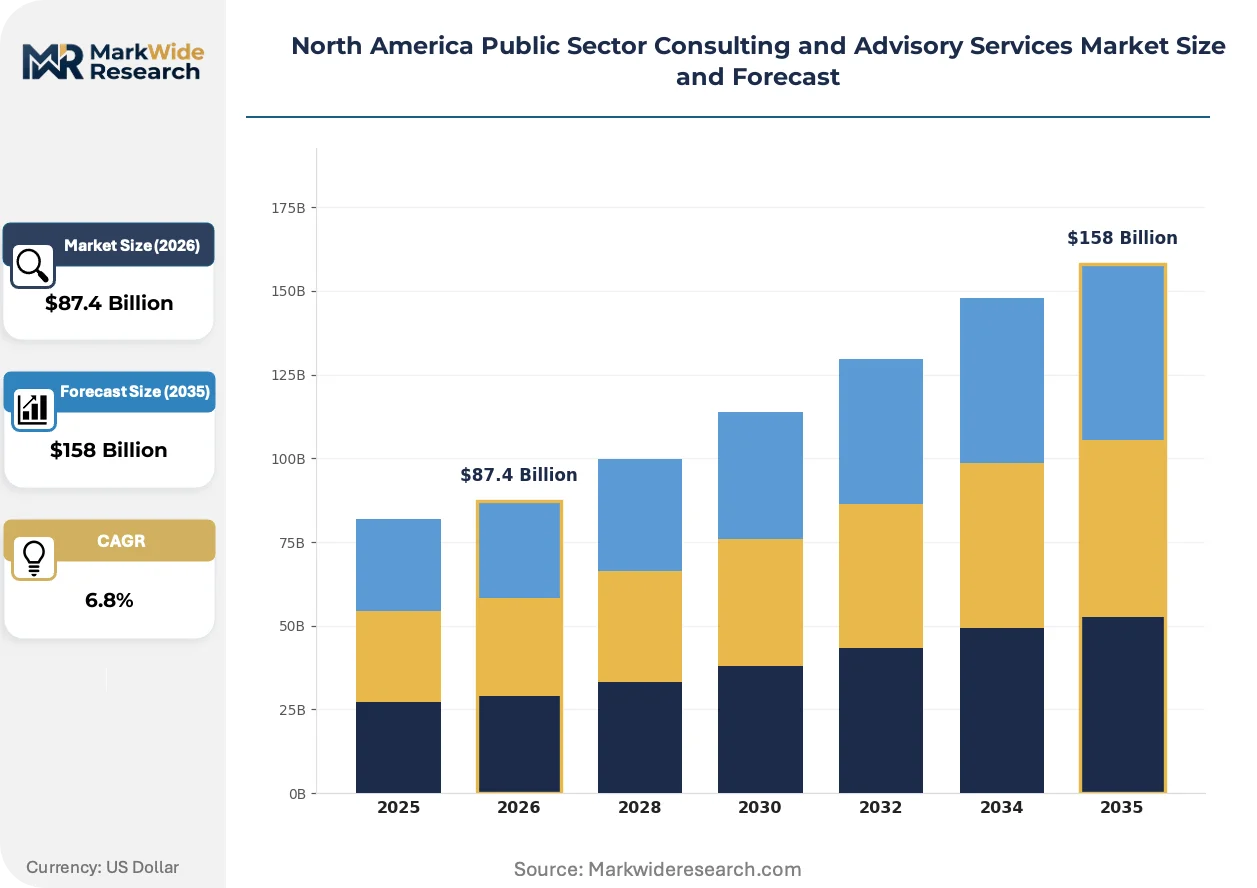
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategic Planning, Operational Improvement, Process Optimization, Change Management Client Type: Government Agencies, Non-Profit Organizations, Educational Institutions, Municipalities Engagement Model: Fixed Fee, Time and Materials, Retainer, Performance-Based Solution Type: Digital Transformation, Policy Analysis, Risk Management, Compliance Advisory |
| Companies Covered | Deloitte Consulting LLP, EY, PwC, KPMG, McKinsey & Company, Boston Consulting Group, Bain & Company, Accenture, Booz Allen Hamilton, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Public Sector Consulting and Advisory Services Market Trends and Innovations
Advisory delivery models are pivoting from episodic strategy engagements toward embedded implementation partnerships. Technology enablement and procurement reform are compressing traditional project cycles while expanding recurring revenue potential.
Generative artificial intelligence is converging with policy document automation to compress analytical production timelines. Federal health agencies and state legislative research offices pilot large-language-model tools for regulatory impact assessment and constituent services. This convergence threatens commoditization of junior analyst tasks while elevating demand for prompt engineering and output validation expertise.
The Office of Management and Budget's guidance on evidence-based policymaking is hardening performance metrics requirements for federal consulting contracts. Agencies now mandate predefined outcome indicators and third-party evaluation protocols before obligation of funds. Defense and civilian health departments have moved fastest, with transportation and environmental agencies following in subsequent fiscal cycles.
State procurement offices are unbundling strategy and implementation scopes to attract specialized boutiques alongside incumbent auditors. Competitive bidding rules in California, Texas, and New York now permit task-order competitions within broader indefinite-delivery vehicles. This fragmentation enables niche players to penetrate accounts previously dominated by full-service firms, though it also lengthens sales cycles and raises proposal costs.
North America Public Sector Consulting and Advisory Services Market Segmentation
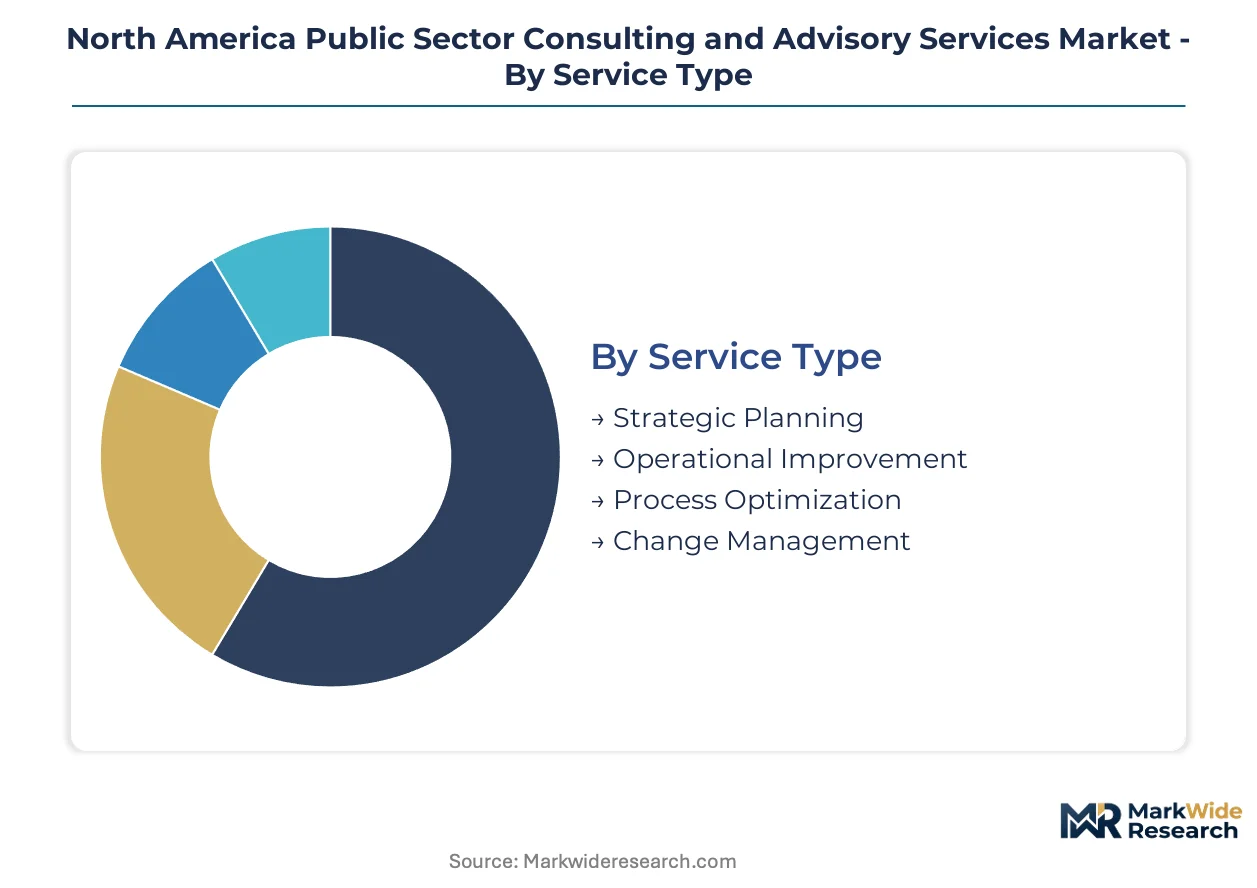
Segmentation in public sector consulting reveals how procurement rules and funding mechanisms reshape vendor selection. Each dimension exposes different competitive entry points and margin structures across federal, state, and municipal accounts.
Service Type:
Upgrade cycles vary dramatically across service lines, with strategic planning engagements tied to electoral and budgetary calendars while operational improvement work responds to fiscal stress.
- Strategic Planning:Multi-year capital allocation frameworks shape federal agency direction. State transportation departments under IIJA mandates concentrate demand here, though procurement cycles stretch 18-24 months. Fee premiums reach their peak in this segment.
- Operational Improvement:Cost reduction and service delivery optimization for constrained tax bases. Mid-sized municipalities across Texas, California, and Ontario drive volume as deferred maintenance backlogs pressure budgets.
- Process Optimization:Workflow redesign for eligibility and permitting systems. Federal health agencies and state Medicaid offices deploy these engagements to meet evidence-based policymaking mandates.
- Change Management:Stakeholder alignment and workforce transition support. Often bundled with larger transformation programs rather than procured standalone.
Volume placements concentrate in Operational Improvement; the faster expansion belongs to Strategic Planning.
Client Type:
Customer scale determines contract structure, with federal agencies favoring multi-year vehicles and municipalities seeking discrete project scopes.
- Government Agencies:Federal civilian and defense departments with active security clearance requirements. The Office of Management and Budget's outcome-linked contracting guidance reshapes how these clients structure vendor relationships.
- Non-Profit Organizations:Federally funded health and social service providers seeking compliance and program evaluation support. Federal grant conditions dictate consulting procurement patterns.
- Educational Institutions:State university systems and research institutions pursuing administrative modernization. Procurement flows through state higher education boards with distinct competitive bidding rules.
- Municipalities:City and county governments stretching property tax revenues. Canadian municipalities under Treasury Board contracting policies and U.S. cities under state procurement codes operate under divergent vendor qualification regimes.
Contract flow runs heaviest through Government Agencies; the steepest expansion trajectory sits with Municipalities.
Engagement Model:
Payment structure alignment with risk allocation separates incumbent auditors from specialized boutiques in competitive bidding.
- Fixed Fee:Defined scope and deliverable contracts with cost-accounting standard compliance overhead. Federal Acquisition Regulation complexity squeezes margins here.
- Time and Materials:Staff augmentation with hourly billing, now disfavored under evidence-based policymaking mandates. Still persists in legacy system maintenance engagements.
- Retainer:Renewable advisory relationships with recurring revenue potential. State procurement offices increasingly permit task-order competitions within these vehicles.
- Performance-Based:Outcome-linked fees tied to predefined metrics. Federal health and defense departments moved fastest into this structure, with transportation agencies following.
Revenue concentration favors Retainer structures; Performance-Based contracting climbs the fastest.
Solution Type:
Technology intensity and regulatory complexity determine which solution lines command premium positioning.
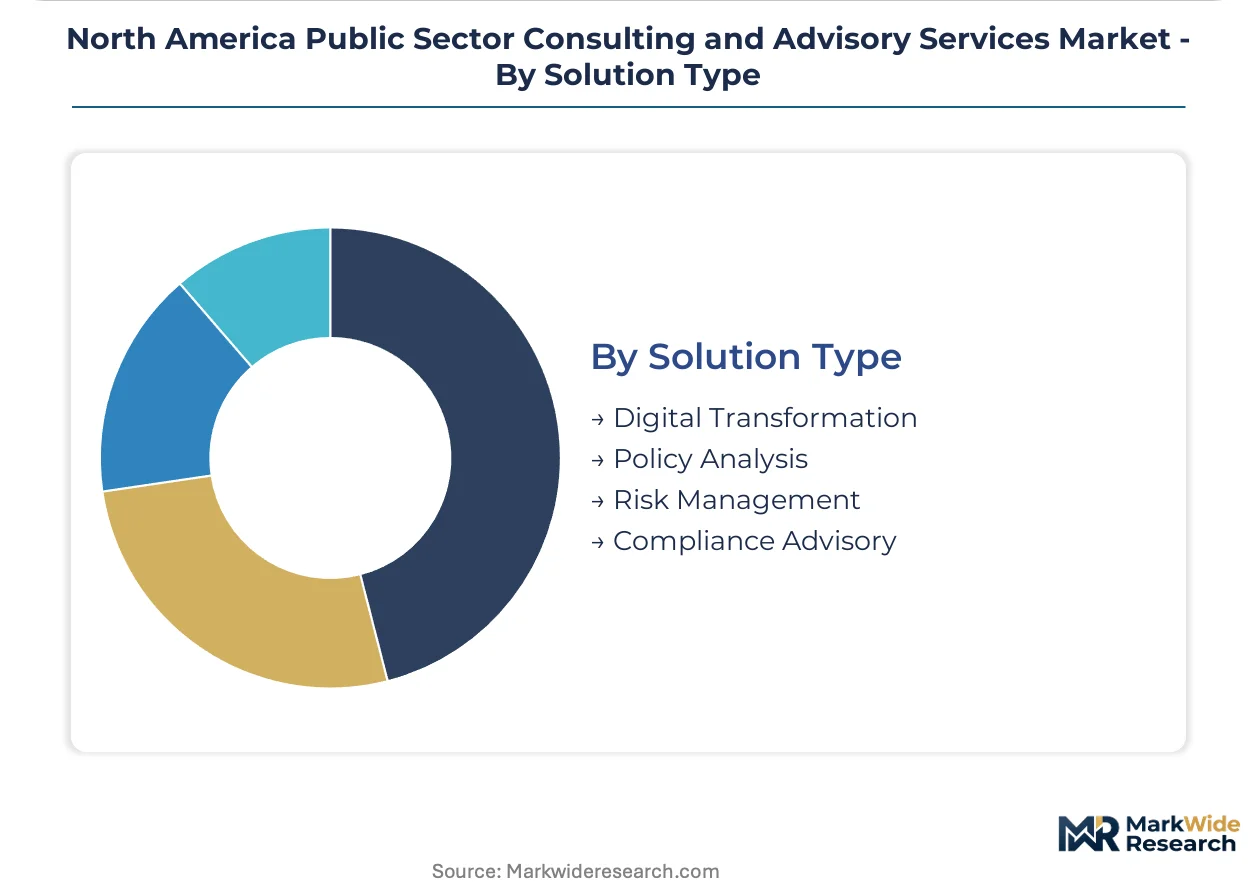
- Digital Transformation:Cloud migration, legacy modernization, and enterprise architecture. State Medicaid eligibility systems and federal health platforms drive sustained demand.
- Policy Analysis:Regulatory impact assessment and legislative research support. Generative artificial intelligence pilots in state legislative offices threaten commoditization of junior analytical tasks.
- Risk Management:Cybersecurity advisory and supply chain resilience. Security clearance bottlenecks limit vendor pool depth for sensitive federal work.
- Compliance Advisory:Federal Acquisition Regulation, Treasury Board policy, and state procurement code navigation. Often bundled with audit relationships to exploit incumbent advantages.
Advisory hours stack deepest in Digital Transformation; Policy Analysis gains share fastest as automation reshapes delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Washington D.C. and the surrounding National Capital Region concentrate the densest advisory activity, hosting the headquarters of major federal contractors and proximity to Pentagon, Capitol Hill, and executive agency procurement offices.
United States
State transportation departments under IIJA mandates drive sustained demand for program management advisory. The Office of Management and Budget's evidence-based policymaking guidance reshapes federal contracting toward outcome-linked structures. California, Texas, and New York procurement offices now permit task-order competitions within indefinite-delivery vehicles.
Canada
Provincial health authorities seek eligibility system modernization and fraud detection analytics. Treasury Board contracting policies favor incumbent auditors, raising switching costs for new advisory entrants. Toronto and Ottawa host concentrations of firms serving federal and Ontario government accounts.
Mexico
Federal infrastructure spending and state-level administrative reform create openings for operational improvement advisory. The Secretariat of Finance and Public Credit procurement frameworks increasingly emphasize performance metrics. Mexico City anchors demand for public financial management consulting.
North America Public Sector Consulting and Advisory Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across security clearance depth and federal contract vehicle access. The market structures around three tiers: full-service giants with scale across civilian and defense accounts, specialized boutiques with deep domain expertise in health or transportation, and audit-linked incumbents exploiting state procurement preferences. Consolidation pressure intensifies as agencies unbundle strategy and implementation scopes. Dominant competitive moves include security clearance pipeline investments and strategic partnerships with cloud-native technology vendors.
Within the full-service tier, Deloitte Consulting LLP and Booz Allen Hamilton occupy distinct positions shaped by scale and clearance depth respectively. EY exemplifies the audit-linked incumbent archetype competing aggressively on price in state and municipal markets. These three firms anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Deloitte Consulting LLP |
| EY |
| PwC |
| KPMG |
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Accenture |
| Booz Allen Hamilton |
| Others |
Pricing and Supply Chain Analysis
Federal civilian agencies and state Medicaid offices concentrate procurement volume under outcome-linked contracting mandates, anchoring the dominant value-based pricing model across North American public sector consulting. The Infrastructure Investment and Jobs Act's grant conditions compress vendor selection timelines while elevating performance-based fee structures over traditional time-and-materials arrangements.
Pricing Analysis
Outcome-linked fees tied to predefined metrics anchor pricing architecture for federal health and defense departments, displacing hourly billing in sensitive accounts. Price differentiation separates engagements with active security clearance requirements from commodity municipal advisory work, with federal contract vehicle access commanding substantial premiums. Cost compression in state and municipal segments intensifies as procurement offices unbundle strategy and implementation scopes to attract specialized boutiques. Mid-sized municipalities exhibit highest price sensitivity due to constrained property tax bases, while intelligence community contracts show lowest sensitivity given clearance scarcity.
Supply Chain Analysis
Regional distribution of consulting talent concentrates in the Washington D.C. National Capital Region, Toronto, and Ottawa, with satellite hubs in California, Texas, and New York state capitals. The talent pipeline draws from federal acquisition professionals, state procurement officers, and cleared personnel with domain expertise in health administration and transportation systems. Single-source vulnerability sits with security clearance bottlenecks that restrict vendor pool depth for defense and intelligence work. Distribution runs through multi-year indefinite-delivery vehicles and renewable retainer relationships rather than discrete project awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as agencies unbundle scopes and procurement reform favors incumbents with federal contract vehicle access, forcing weaker players toward niche specialization or exit.
For Market Incumbents: Extend clearance pipeline investments and deepen partnerships with cloud-native technology vendors to defend against boutique encroachment in digital transformation service lines. Exploit audit-linked relationships under state procurement codes that favor incumbent qualification while building proprietary data assets that resist commoditization from generative artificial intelligence tools. For New Entrants and Emerging Players: The gap between premium strategy boutiques and commodity implementation shops creates white-space opportunity in climate resilience planning and municipal infrastructure vulnerability assessment. Target mid-sized Ontario and Texas municipalities seeking operational improvement advisory without incumbent auditor relationships. Pursue task-order competition pathways within California and New York indefinite-delivery vehicles to bypass traditional competitive bidding barriers. For Investors and Strategic Acquirers: The window for entry favors specialized boutiques with deep domain expertise in federal health or transportation and established clearance pipelines. Long-term viability rests on advisory capabilities that resist automation through stakeholder facilitation and complex implementation oversight. Monitor federal grant condition evolution as the inflection signal—each IIJA funding tranche reshapes which service lines agencies can deploy.| Strategic Initiative | Industry Significance |
|---|---|
| Security Clearance Pipeline Investment | Active clearance holdings differentiate vendors for Pentagon and intelligence community procurement competitions. |
| Cloud-Native Technology Partnership | Alliances with hyperscalers position firms for federal interoperability standards and legacy modernization mandates. |
| Outcome-Based Contracting Capability | Evidence-based policymaking compliance enables access to Office of Management and Budget-guided federal engagements. |
| State Procurement Code Incumbency | Audit-linked qualification under Treasury Board and state competitive bidding rules reduces new entrant switching success. |
| Climate Resilience Advisory Buildout | Municipal infrastructure vulnerability assessments represent underpenetrated terrain converging engineering and policy capabilities. |
Research Methodology
Federal procurement databases, state competitive bidding records, and Treasury Board contracting disclosures formed the secondary backbone, cross-referenced with primary interviews involving federal acquisition officers, state procurement leads, municipal budget directors, and cleared consulting practice heads. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing from contractor revenue disclosures and grant obligation patterns.
Bottom-up modeling built from individual contract awards and task-order values rolled into service line and client type aggregations, while top-down approaches tested against federal spending patterns and municipal fiscal stress indicators. Segmentation dimensions spanned service type, client tier, engagement model, and solution technology intensity, with CAGRs derived from historical obligation trajectories and funding authorization schedules across the analysis window. Forecast inputs incorporated IIJA funding tranche timing, clearance pipeline expansion rates, and generative artificial intelligence adoption curves in policy document automation.
Inputs from federal procurement systems and provincial contracting registries were available through the study window; gaps in classified program spending and non-competed sole-source awards introduce uncertainty bands around defense and intelligence community estimates. Forecasts reflect assumptions about grant condition stability and clearance processing efficiency that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Field Service Management Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Europe Managed Services Market