
 Workforce Management Market | 2026-2036
Workforce Management Market Size, Share, and Industry Trends Forecast 2026-2036
Workforce Management Market Intelligence
Channel partnerships between enterprise software vendors and regional system integrators is reconfiguring how workforce management platforms reach mid-market buyers. UKG leverages its vertical integration across HR, payroll, and time-tracking to sustain platform stickiness among large healthcare and retail employers. Ceridian Dayforce anchors its competitive position through real-time continuous payroll calculation, while Paycor differentiates by targeting sub-1,000-employee businesses with bundled compliance and scheduling tools.
Workforce management encompasses integrated software systems that automate time capture, labor scheduling, absence tracking, and regulatory compliance across distributed employee populations. Core functional parameters include real-time clock synchronization, biometric or geofenced punch validation, and rule engines that enforce jurisdiction-specific overtime and break regulations. Cloud-based deployment dominates new installations due to lower capital requirements and faster multi-location rollout, though hybrid architectures retain share among organizations with legacy ERP investments or strict data residency constraints. Compliance management modules command premium pricing as GDPR, Fair Labor Standards Act, and sector-specific working-time rules multiply audit obligations. Small and medium enterprises represent the fastest-expanding end user category as vendor self-service onboarding and templated regulatory packs reduce implementation complexity.
The US Department of Labor enforces Fair Labor Standards Act record-keeping mandates that shape time-tracking accuracy requirements and drive demand for automated audit trails. E.U. GDPR and the AI Act impose algorithmic transparency and data minimization rules on predictive scheduling and workforce analytics, favoring vendors with EU-hosted infrastructure and explainable AI documentation. OSHA and state-level predictive scheduling laws in Oregon, New York, and California add overlapping compliance layers that expand module attach rates. Stakeholders must evaluate whether their platform architecture can absorb emerging right-to-disconnect regulations and algorithmic management disclosures without costly re-platforming.
Market Dynamics
The convergence of predictive analytics with biometric time-capture systems is compressing scheduling cycles from weekly to daily horizons across shift-based industries. This technological shift forces employers to reconfigure labor deployment models and compliance documentation simultaneously.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European employers must maintain auditable records for automated scheduling decisions, driving procurement of platforms with built-in explainability documentation.
- German industrial working-time documentation:Manufacturers facing skilled labor shortages require granular shift-tracking to optimize existing workforce utilization under stricter federal labor bureau oversight.
- Healthcare shift-complexity escalation:Hospital systems deploy integrated platforms to manage rotating clinical staff across emergency, surgical, and outpatient units with specialty certification requirements.
Market Restraints
- Legacy ERP integration costs:Organizations with SAP or Oracle investments face substantial middleware expenses to synchronize workforce data with existing financial systems.
- Biometric hardware supply concentration:Fingerprint and facial recognition terminals depend on semiconductor fabrication concentrated in East Asian manufacturing hubs.
- GDPR data residency requirements:Multi-national employers must maintain EU-hosted infrastructure for employee biometric data, fragmenting platform architectures.
Strategic Opportunities
- Sub-1,000-employee business segment:Self-service onboarding tools and templated compliance packs reduce implementation friction for mid-market buyers previously priced out of enterprise platforms.
- Right-to-disconnect regulatory preparation:French and Belgian labor codes are expanding off-hours communication restrictions, creating demand for automated boundary-enforcement modules.
- AI-native predictive scheduling:Machine learning demand forecasting converges with automated shift-swapping marketplaces to minimize overtime expenditure in retail and hospitality.
Industry Challenges
- Implementation specialist scarcity:Configuring jurisdiction-specific overtime rule engines requires certified consultants familiar with both platform architecture and local labor law.
- Interoperability certification delays:Payroll system APIs lack standardized data formats, prolonging integration timelines with incumbent providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workforce Management Market |
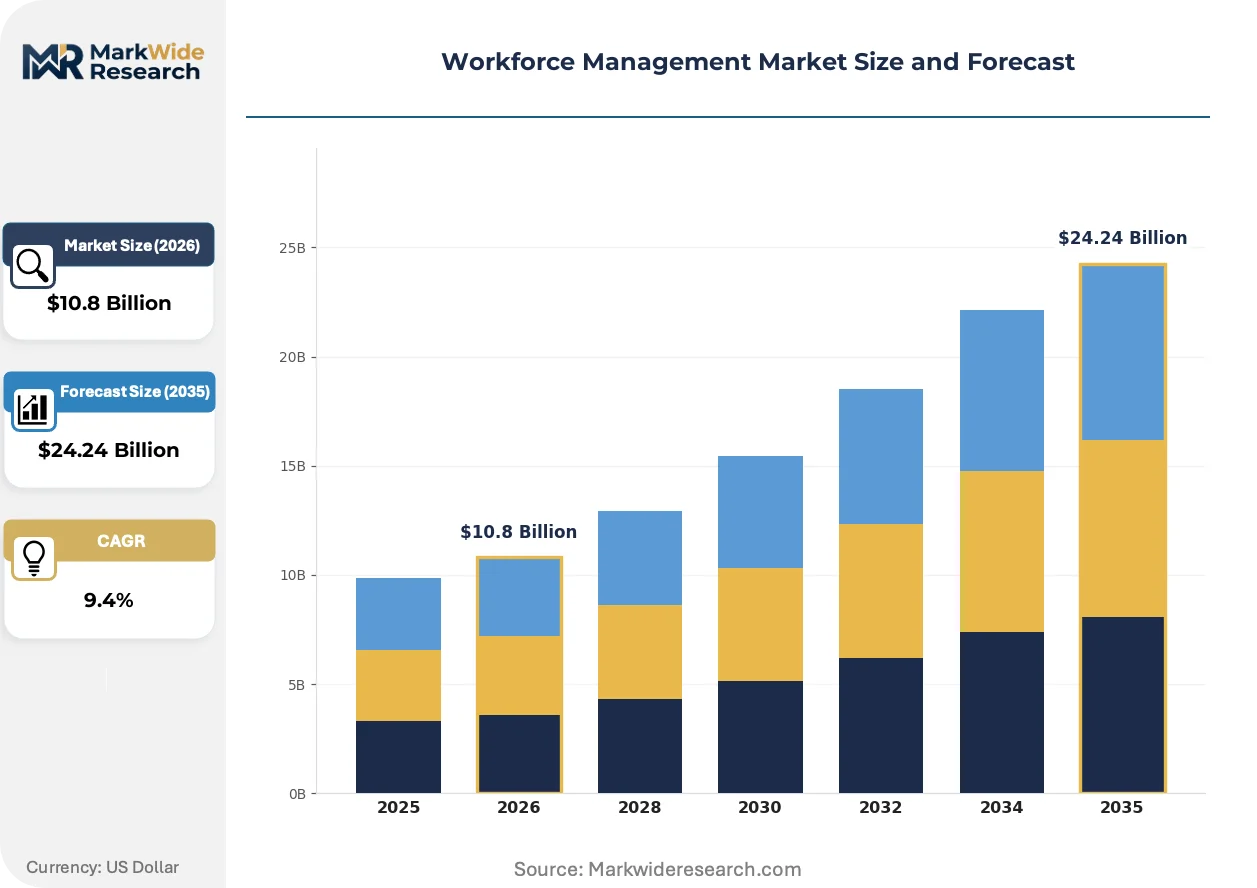
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $24.24 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Time & Attendance, Scheduling, Employee Self-Service, Leave Management, Analytics, Compliance Management Deployment Mode: Cloud-Based, On-Premise, Hybrid, Hosted, Managed Services Industry Sector: Manufacturing, Hospitality, Education, Transportation, Telecommunications, Public Sector End User Type: Large Corporations, Small & Medium Enterprises, Government Agencies, Non-Profit Organizations |
| Companies Covered | UKG, Workday, ADP, Ceridian Dayforce, Oracle, SAP, Paycor, Paychex, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workforce Management Market Strategic Shifts & Innovations
Workforce management platforms are absorbing adjacent HR technologies into unified data layers, collapsing previously separate purchasing decisions. This consolidation is altering vendor competitive boundaries and buyer evaluation criteria.
Geofenced mobile punch validation with GPS-timestamp verification is rendering obsolete stationary biometric terminals for distributed field-service and delivery workforces. Logistics and facilities management employers in North America and Western Europe have accelerated deployment to 60% of new installations. The technology is compressing hardware capital requirements while expanding coverage to previously unreachable employee populations.
OSHA record-keeping modernization proposals in the United States would mandate electronic submission of injury and illness data linked to shift-level workforce records. Manufacturing and warehouse operators face expanded audit obligations requiring timestamp correlation between production schedules and safety incidents. Heavy industry employers are pre-positioning platforms with integrated environmental health and safety modules to absorb compliance expansion.
Subscription-based platform procurement with usage-scaled pricing is displacing perpetual license models among mid-market buyers. Regional system integrators and industry-specific value-added resellers capture an expanding share of implementation and ongoing support revenue. This channel evolution is most pronounced in Germany and the United Kingdom, where specialized healthcare and retail consultancies bundle workforce platforms with vertical compliance advisory services.
Workforce Management Market Segmentation
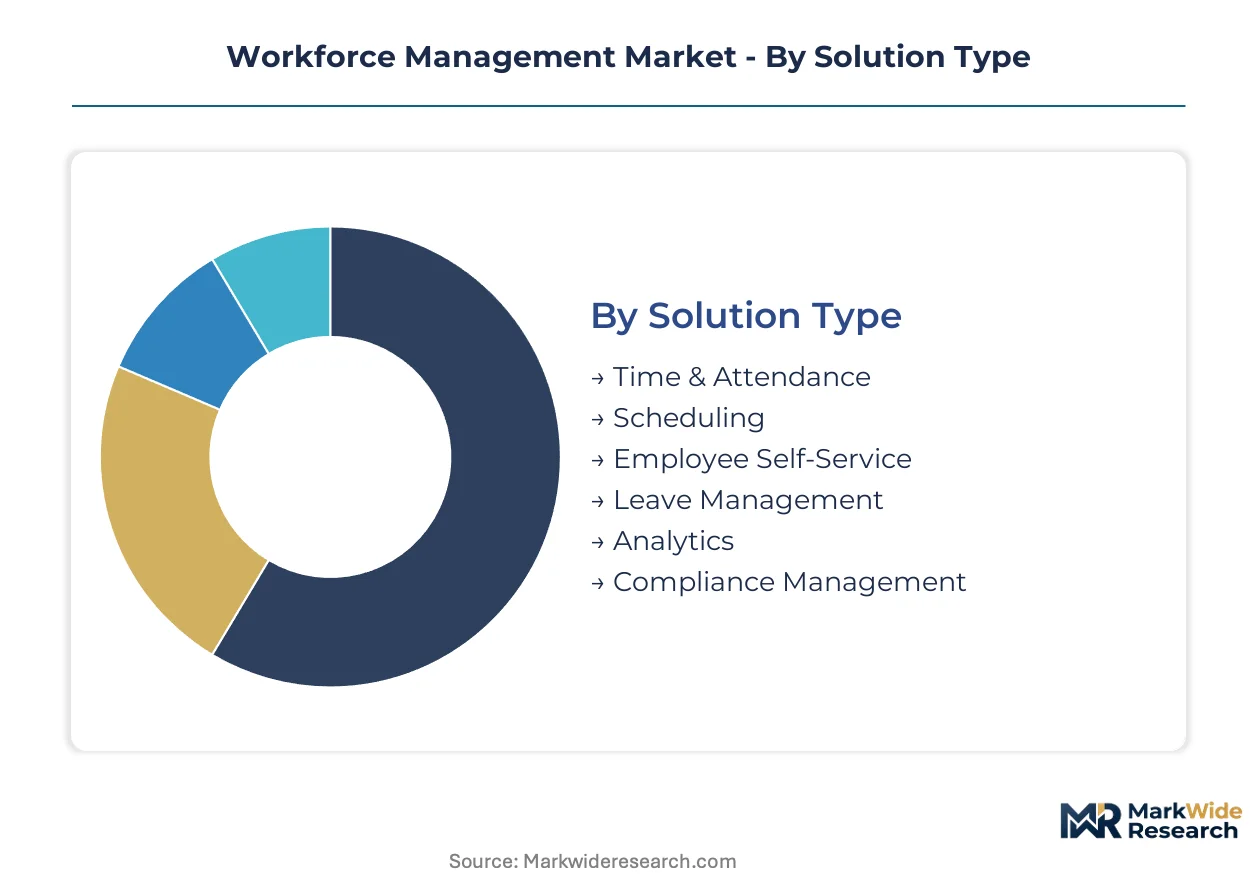
Workforce management platforms serve heterogeneous operational requirements across shift complexity, regulatory exposure, and IT maturity. Segmentation reveals where solution architecture, deployment constraints, and compliance modules concentrate commercial value.
Solution Type:
Use-case spectrum spans hourly time capture through predictive labor optimization, with compliance and analytics commanding premium module attach rates.
- Time & Attendance:Biometric punch validation and geofenced mobile clock-in form the foundational data layer for payroll integration. Manufacturing plants in Germany deploy fingerprint terminals to satisfy federal labor bureau documentation mandates under stricter working-time oversight.
- Scheduling:AI-driven shift allocation with real-time swap marketplaces compresses labor deployment cycles from weekly to daily horizons. Hospital systems across the United States manage rotating clinical staff across emergency, surgical, and outpatient units with specialty certification tracking.
- Employee Self-Service:Mobile-first interfaces enable shift bidding, time-off requests, and availability updates without supervisor intervention.
- Leave Management:Automated accrual engines enforce jurisdiction-specific sick leave, family leave, and paid time off regulations.
- Analytics:Predictive dashboards correlate labor costs with productivity metrics for operational planning.
- Compliance Management:Rule engines encode Fair Labor Standards Act, GDPR, and sector-specific working-time rules with audit trail generation.
The dominant share belongs to Time & Attendance, while Scheduling is closing the gap fastest.
Deployment Mode:
Cost tier differentiation separates capital-intensive on-premise installations from subscription-scaled cloud alternatives, with hybrid architectures serving data residency constraints.
- Cloud-Based:Multi-tenant SaaS delivery eliminates server capital expenditure and accelerates multi-location rollout. European employers favor EU-hosted infrastructure to satisfy GDPR data residency requirements for biometric employee data.
- On-Premise:Dedicated hardware deployment retains favor among organizations with legacy ERP investments or strict internal security policies. Large manufacturers in the United States maintain on-premise time clocks to synchronize with existing SAP financial systems.
- Hybrid:Split architectures localize sensitive biometric processing while centralizing analytics in cloud environments.
- Hosted:Single-tenant managed infrastructure offers customization without operational burden.
- Managed Services:Outsourced platform administration with guaranteed uptime and compliance updates.
Cloud-Based deployment holds the dominant position, though Hybrid configurations are expanding most quickly among multi-national employers.
Industry Sector:
Application intensity varies by shift complexity, union density, and regulatory audit frequency, with manufacturing and hospitality driving module sophistication.
- Manufacturing:Round-the-clock production scheduling with machine-operator certification tracking and OSHA safety correlation. German industrial employers face acute skilled labor shortages and deploy granular shift-tracking to optimize existing workforce utilization.
- Hospitality:Fluctuating demand patterns require automated labor forecasting and flexible shift-swapping marketplaces. Hotels and restaurant chains in France prepare for expanding right-to-disconnect regulations with automated off-hours communication boundaries.
- Education:Substitute teacher dispatch and hourly staff coordination across distributed campus locations.
- Transportation:Driver hour-of-service compliance with electronic logging device integration.
- Telecommunications:Field technician dispatch with GPS-timestamp validation and customer appointment correlation.
- Public Sector:Civil service rule engines with union contract enforcement and pension accrual tracking.
Manufacturing commands the largest installed base, while Hospitality is gaining share fastest through AI-native demand forecasting adoption.
End User Type:
Customer type determines implementation complexity, with large corporations demanding deep customization and mid-market buyers prioritizing rapid deployment.
- Large Corporations:Enterprise-grade platforms with multi-entity consolidation, complex overtime rule engines, and dedicated implementation specialists. Healthcare systems across the United Kingdom integrate workforce data with NHS payroll and pension administration.
- Small & Medium Enterprises:Self-service onboarding tools and templated compliance packs reduce implementation friction for buyers previously priced out of enterprise platforms. Sub-1,000-employee businesses in Germany accelerate procurement through regional system integrator bundles.
- Government Agencies:Public procurement compliance with transparency mandates and civil service labor code enforcement.
- Non-Profit Organizations:Grant-funded implementations with volunteer hour tracking and restricted fund labor allocation.
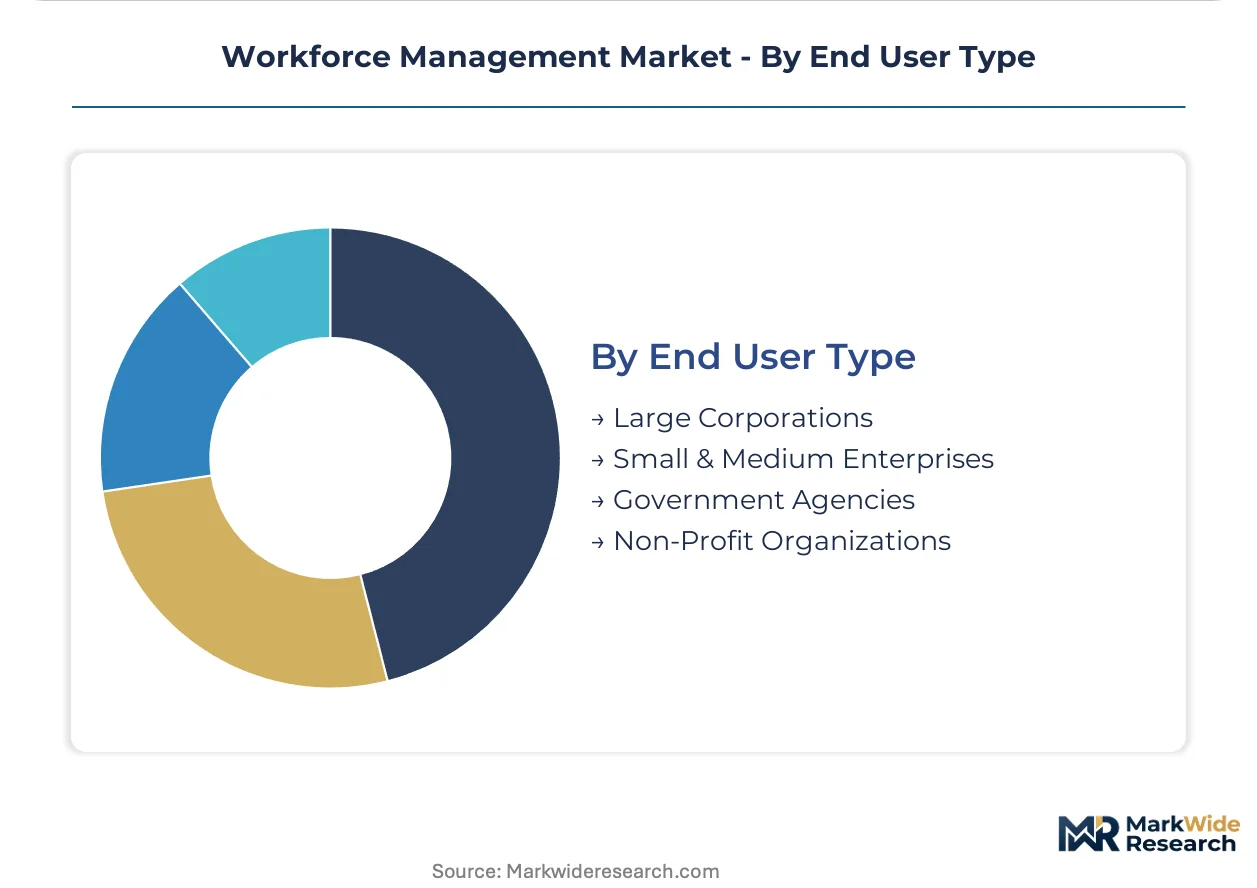
Large Corporations retain the dominant share, though Small & Medium Enterprises are climbing the fastest as vendor self-service capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA record-keeping mandates in the United States establish the regulatory baseline that shapes time-tracking accuracy requirements across North American employers. The EU AI Act and GDPR impose algorithmic transparency and data residency obligations that favor vendors with EU-hosted infrastructure. Demand concentrates in Germany, the United Kingdom, and France, where industrial and healthcare employers face acute compliance documentation pressures.
United States
Hospital systems across the United States deploy integrated platforms to manage rotating clinical staff across emergency, surgical, and outpatient units with specialty certification tracking. The Department of Labor enforces Fair Labor Standards Act record-keeping mandates that drive demand for automated audit trails. Healthcare clusters in Texas, California, and New York accelerate procurement of cloud-based scheduling systems to absorb predictive scheduling laws in Oregon and California.
Germany
Industrial manufacturers in Germany face acute skilled labor shortages and deploy granular shift-tracking to optimize existing workforce utilization under stricter federal labor bureau oversight. The EU AI Act algorithmic transparency mandates require auditable records for automated scheduling decisions, pushing employers toward platforms with built-in explainability documentation. Manufacturing concentrations in Bavaria and North Rhine-Westphalia lead adoption of biometric time-capture systems to satisfy working-time documentation rules.
United Kingdom
Healthcare systems across the United Kingdom integrate workforce data with NHS payroll and pension administration, driving demand for multi-entity consolidation capabilities. GDPR data minimization rules favor vendors with UK and EU-hosted infrastructure for employee biometric data. Regional system integrators in London and the Southeast bundle workforce platforms with vertical compliance advisory services for mid-market buyers.
France
Hotels and restaurant chains in France prepare for expanding right-to-disconnect regulations with automated off-hours communication boundary modules. The CNIL enforces GDPR compliance for predictive scheduling algorithms, requiring explainable AI documentation from workforce analytics vendors. Hospitality clusters in Paris and the Provence-Alpes-Côte d'Azur region adopt AI-native demand forecasting to minimize overtime expenditure.
Japan
Manufacturers in Japan deploy workforce management platforms to synchronize round-the-clock production scheduling with machine-operator certification tracking. METI guidelines on work-style reform push employers toward automated boundary-enforcement for overtime limitations. Industrial concentrations in the Chubu region around Nagoya and the Kansai region around Osaka lead adoption of hybrid cloud architectures to satisfy data residency preferences.
Workforce Management Market Key Industry Players
Enterprise software conglomerates and specialized workforce management vendors split the market across distinct capability layers. Consolidation pressure intensifies as platform buyers demand unified data layers collapsing previously separate HR technology purchasing decisions. Three archetypes dominate: vertically integrated HCM suites, standalone workforce specialists with deep compliance expertise, and mid-market bundlers targeting rapid deployment. Competitive moves concentrate on channel partnerships with regional system integrators and API-based ecosystem expansion to absorb adjacent HR technologies.
Within the enterprise-suite tier, UKG and Workday exemplify platform stickiness strategies anchored in unified HR, payroll, and time-tracking data layers. Ceridian Dayforce occupies a position emphasizing real-time continuous payroll calculation as a differentiation anchor. Among mid-market specialists, Paycor represents the sub-1,000-employee targeting approach with bundled compliance and scheduling tools. These three vendors illustrate how competitive positioning diverges between scale-driven consolidation plays and segment-specific bundling strategies.
| Leading Market Players |
|---|
| UKG |
| Workday |
| ADP |
| Ceridian Dayforce |
| Oracle |
| SAP |
| Paycor |
| Paychex |
| Infor |
| Others |
Cost & Logistics Intelligence
Semiconductor fabrication concentration in Taiwan and South Korea creates tariff-exposed chokepoints that simultaneously widen customization premiums for EU-hosted compliance modules and compress hardware margins for biometric terminal manufacturers.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from self-service SaaS tiers. Subscription-based SaaS dominates new procurement, with pricing stratifying across premium compliance-bundled, standard multi-tenant, and economy self-service tiers. Price differentiation hinges on GDPR certification level and vertical-specific rule engine complexity. Cost compression in the hardware tier intensifies as biometric semiconductor sourcing faces East Asian supply constraints. Small and medium enterprises exhibit highest price sensitivity, while healthcare systems absorb premium pricing for integrated payroll and pension synchronization.
Supply Chain Analysis
Upstream feedstock dependencies center on semiconductor wafers from Taiwan, South Korea, and Japan for biometric processing chips. Cloud infrastructure draws from hyperscaler data center networks across Germany, Ireland, and the Netherlands to satisfy GDPR residency mandates. Supply chain risk manifests in single-source vulnerability for facial recognition sensors concentrated in East Asian fabrication hubs. Distribution runs through regional system integrators in Germany and the United Kingdom, with value-added resellers capturing implementation and compliance advisory revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
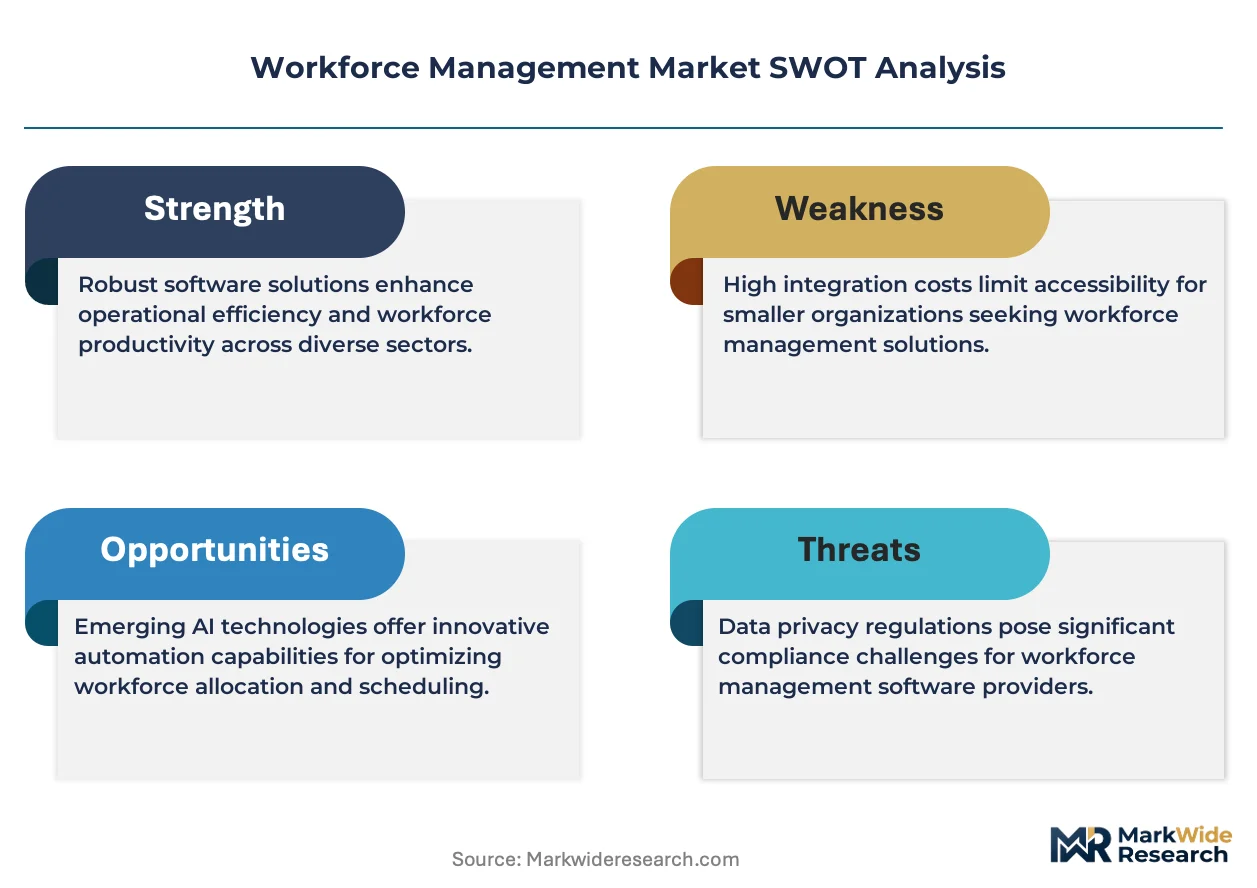
Incumbents face substitution pressure from AI-native scheduling entrants unburdened by legacy ERP integration debt, requiring defensive architecture investments to retain platform stickiness.
For Market Incumbents: Build data-layer moats through real-time payroll synchronization and NHS pension system integration. Deepen API ecosystem partnerships with regional healthcare consultancies to lock out standalone scheduling specialists. Anchor retention through vertical rule engines encoding German federal labor bureau documentation mandates. For New Entrants and Emerging Players: Pursue white-space penetration in the sub-500-employee hospitality segment across France and Belgium, where right-to-disconnect regulatory preparation outpaces incumbent module development. Target self-service onboarding tools with pre-configured GDPR compliance packs. Accelerate through channel partnerships with French hospitality industry associations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliance-specialist acquisition targets with EU-hosted infrastructure and explainable AI documentation capabilities. Long-term viability rests on algorithmic transparency certification rather than feature breadth. Monitor French CNIL enforcement patterns on predictive scheduling algorithm audits as the inflection signal for regulatory-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Hosted Infrastructure Expansion | GDPR data residency requirements favor biometric processing localization in Germany and Ireland. |
| Explainable AI Documentation Investment | EU AI Act mandates auditable scheduling decision trails for algorithmic transparency compliance. |
| Vertical Compliance Module Development | German federal labor bureau oversight drives granular shift-tracking certification requirements. |
| Regional System Integrator Partnership | UK and German healthcare consultancies bundle platforms with NHS payroll integration services. |
| Biometric Hardware Supply Diversification | Taiwan and South Korea concentration creates tariff exposure for fingerprint terminal sourcing. |
Research Approach
Cross-validation between primary interviews with workforce management vendors, hospital IT procurement officers, and German manufacturing HR directors anchors the qualitative findings against secondary validation from EU AI Act regulatory filings, GDPR enforcement actions by CNIL and UK ICO, and SEC 10-K disclosures by enterprise software conglomerates. Bottom-up segmentation modeling triangulates against top-down macroeconomic labor market indicators.
Calibration against historical adoption curves in healthcare and manufacturing verticals informs the projection framework across deployment mode, organization size, and regulatory complexity segmentation. CAGRs derive from elasticity-adjusted penetration modeling incorporating German skilled labor shortage severity and French right-to-disconnect legislative momentum. Industry-specific inputs include NHS payroll integration timelines and OSHA record-keeping modernization proposal advancement.
The forecast holds incumbent behavior within observed patterns; aggressive vertical acquisition moves by hyperscaler cloud providers would shift outcomes beyond modeled bounds. Cross-checking against EU AI Act implementation enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Shared Services Market
Enterprise Services
Supplier Management Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Europe IT Services Market