
 Multi Vendor Support Services Market | 2026-2036
Multi Vendor Support Services Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Vendor Support Services Market Intelligence
The substitution of unified, API-driven software platforms for disparate, legacy hardware monitoring tools is rebalancing the economic model for IT infrastructure maintenance. This shift allows enterprises to streamline operations under a single service contract. IBM Corporation leverages its extensive software and consulting expertise to manage complex, heterogeneous environments. Hewlett Packard Enterprise Development LP competes by specializing in support for hybrid cloud and edge computing infrastructure. Dell Technologies sustains its market position through comprehensive support offerings tied to its extensive installed base of server and storage hardware.
Multi Vendor Support Services provide a consolidated technical support framework for an organization's diverse hardware and software assets, sourced from multiple original equipment manufacturers. This model operates through a single point of contact, governed by a unified service level agreement (SLA) to simplify IT management. Hardware Support and Software Maintenance constitute the foundational service types within the market. However, higher margin growth is found in Security Management and Cloud Services, as enterprises prioritize cybersecurity and migrate workloads to distributed environments.
Service providers must navigate complex data sovereignty and privacy regulations like the EU's GDPR when managing client information across borders. In the United States, industries such as healthcare demand strict adherence to HIPAA, which governs the security of patient data on supported IT systems. The primary strategic decision for enterprise buyers now centers on balancing the cost benefits of third-party support against potential risks related to OEM warranty invalidation and access to proprietary firmware updates.
Market Dynamics
The central dynamic in the Multi Vendor Support Services market is the architectural shift from disparate hardware monitoring to unified, software-defined platforms. This transition allows enterprises to consolidate complex IT estates under a single service level agreement, rebalancing the economic model.
Growth Catalysts
- Hybrid Cloud Adoption:The enterprise-wide migration to hybrid cloud environments necessitates support services capable of managing both on-premise legacy systems and distributed cloud infrastructure, creating sustained demand for unified support models.
- Financial Sector Consolidation:The banking and finance industry's continuous drive to consolidate IT infrastructure and reduce operational overhead provides a significant catalyst for single-contract, multi vendor support services.
- Data Center Optimization:In the United States, large-scale projects aimed at optimizing data center efficiency and cost are a primary driver for engaging third-party support providers to manage heterogeneous hardware environments.
Market Restraints
- OEM Warranty Invalidation:A primary restraint is the potential for original equipment manufacturers (OEMs) to void hardware warranties if a third-party service provider performs maintenance, creating risk for enterprise buyers.
- Proprietary Firmware Access:Third-party providers often face restrictions in accessing proprietary firmware updates and diagnostic tools from OEMs, which can limit their ability to perform certain advanced support tasks.
- Data Sovereignty Regulations:Complex data privacy laws, such as the EU's GDPR, create significant compliance burdens and operational hurdles for providers managing client information across international borders.
Strategic Opportunities
- Service Portfolio Expansion:Significant opportunity exists in expanding service offerings beyond foundational hardware support into higher-margin areas like security management and specialized cloud migration services.
- Predictive Analytics Integration:The convergence of AI-powered predictive analytics with infrastructure monitoring tools presents an opportunity to offer proactive maintenance services that anticipate and prevent system failures.
- SME Market Penetration:Small and medium-sized enterprises represent an underpenetrated segment that requires sophisticated, multi vendor support but often lacks the scale to manage multiple OEM contracts directly.
Industry Challenges
- Specialized Talent Scarcity:A persistent challenge is the shortage of IT professionals with expertise across multiple OEM technologies and complex, heterogeneous environments, which constrains service delivery capacity.
- Legacy System Integration:Integrating modern, unified support platforms with clients' deeply embedded legacy IT service management (ITSM) systems presents a significant operational and technical hurdle.
- Regulatory Compliance Overhead:Maintaining continuous compliance with industry-specific regulations, such as HIPAA for healthcare data in the United States, imposes a substantial administrative and financial burden on service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Vendor Support Services Market |
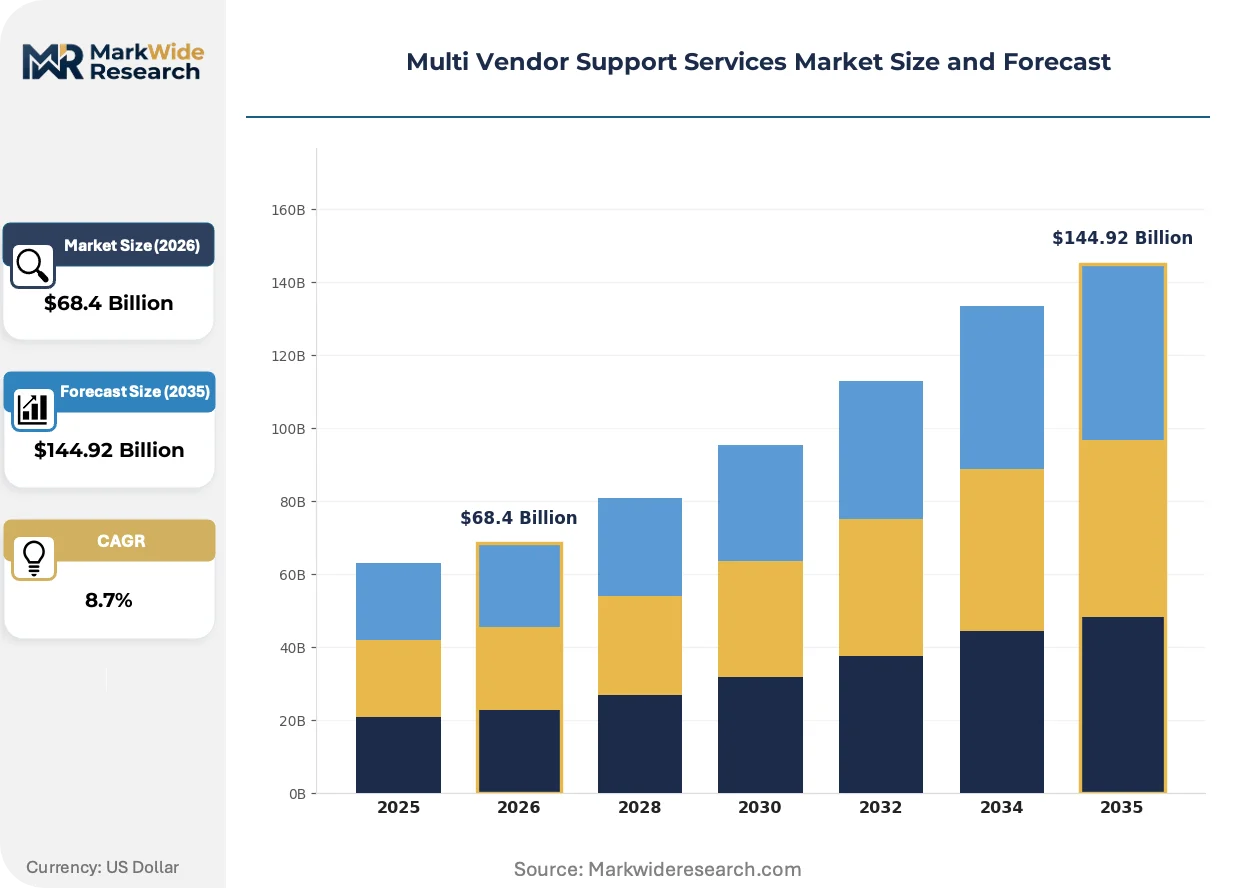
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hardware Support, Software Maintenance, Network Management, Cloud Services, Security Management End User Industry: Telecommunications, Banking & Finance, Government Agencies, Education Institutions, Manufacturing Deployment Model: On-Premise, Managed Services, Outsourced Support, Hybrid Solutions Support Offering: Technical Helpdesk, Onsite Assistance, Remote Monitoring, Incident Management, Consulting |
| Companies Covered | Dell Technologies, IBM Corporation, Hewlett Packard Enterprise Development LP, Cisco Systems, Atos SE, DXC Technology Company, Fujitsu, Hitachi Ltd., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Vendor Support Services Market Strategic Shifts & Innovations
A fundamental shift toward automated and proactive infrastructure management is redefining the market's value proposition. The focus is moving from reactive break-fix services to software-driven optimization, security, and operational continuity across complex, multi-vendor IT estates.
API-driven software platforms provide a single interface for monitoring diverse hardware and software assets from multiple OEMs. Enterprises, especially within the finance and telecommunications sectors, are adopting these tools to replace fragmented legacy monitoring systems. This technology is consolidating operational control, allowing internal IT teams to manage complex infrastructure under a single, streamlined service contract and a unified view.
The EU's General Data Protection Regulation (GDPR) imposes strict rules on the processing and cross-border transfer of personal data. This regulation compels service providers to engineer robust data governance frameworks and often requires data localization strategies for European clients. Support providers operating within the European Union are most affected, frequently redesigning service delivery architectures to guarantee data residency and full compliance.
Enterprise buying criteria are evolving beyond simple cost reduction to prioritize the quality of service level agreements (SLAs) and the provider's security posture. This change diminishes the value of basic hardware break-fix contracts in favor of integrated support that includes cybersecurity monitoring and cloud workload management. This demand-side shift is most visible within regulated industries in the United States, where adherence to frameworks like HIPAA is a critical procurement factor.
Multi Vendor Support Services Market Segmentation
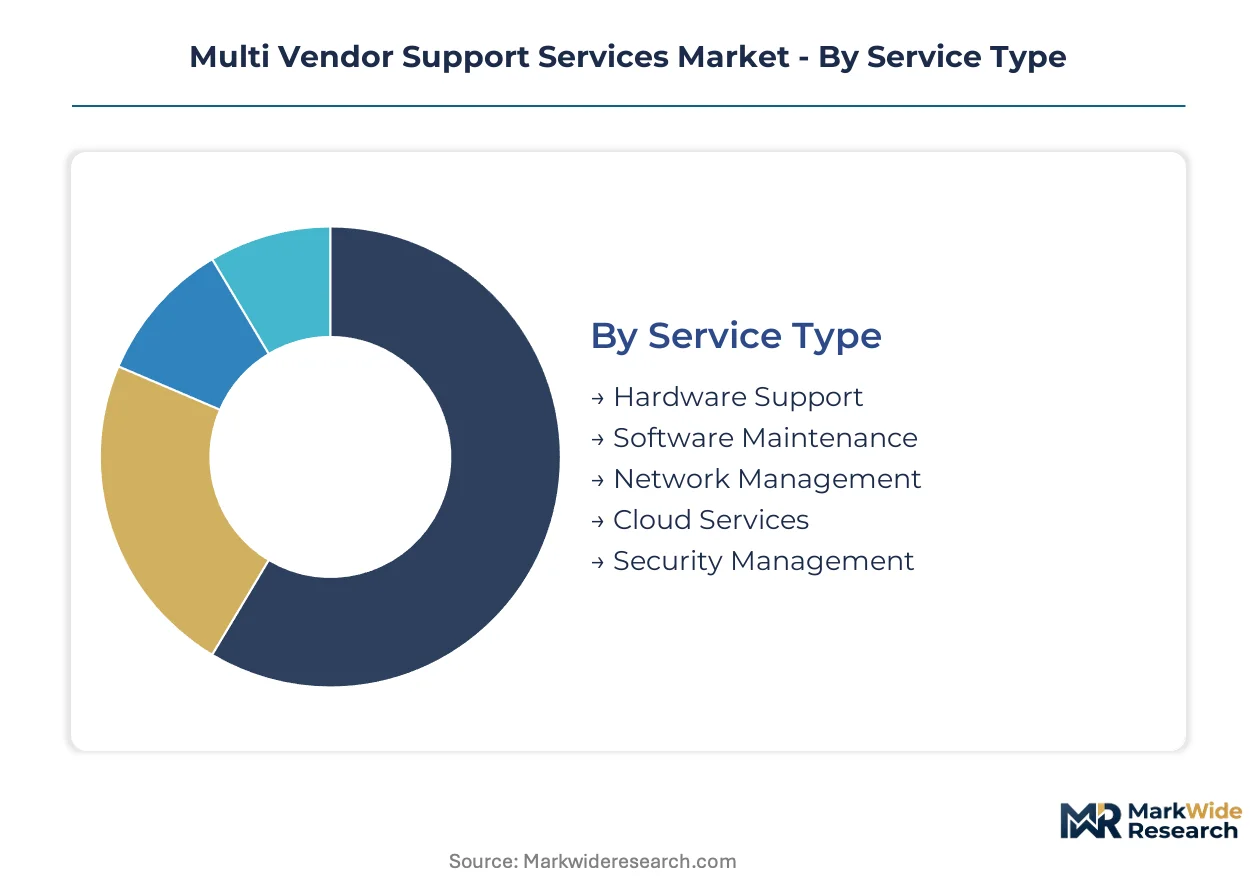
The Multi Vendor Support Services market segments highlight how organizations procure and consume unified IT support across diverse hardware and software landscapes. This segmentation dissects the various service delivery models and industry-specific demands that influence provider strategies. Understanding these categories is essential for identifying areas of concentrated value.
Service Type:
The evolution of IT infrastructure upgrade cycles directly influences the demand for specific multi vendor support service types.
- Hardware Support:Provides technical assistance and repair for physical IT components sourced from various original equipment manufacturers.
- Software Maintenance:Encompasses updates, patches, and troubleshooting for operating systems, applications, and middleware across heterogeneous environments.
- Network Management:Focuses on the monitoring, configuration, and optimization of complex network infrastructures supporting multi-vendor hardware.
- Cloud Services:These services manage and optimize workloads, infrastructure, and applications deployed across hybrid and multi-cloud environments. Demand is concentrating in the United States as enterprises migrate critical operations to distributed platforms, driven by scalability and cost efficiency.
- Security Management:This segment provides comprehensive monitoring, threat detection, and incident response across diverse IT assets and data environments. Uptake is significant within the banking and finance sector, which faces stringent regulatory requirements and escalating cyber threats.
Hardware Support sits at the top of the volume ranking, with Security Management climbing the fastest.
End User Industry:
Different end-user industries exhibit distinct operational complexities and regulatory compliance needs, shaping their multi vendor support requirements.
- Telecommunications:This industry requires support for vast and distributed network infrastructures, including legacy systems and emerging 5G technologies. Demand is strong in Europe, where telecommunication providers are modernizing networks to comply with evolving digital infrastructure mandates.
- Banking & Finance:This sector demands highly secure and compliant support for mission-critical applications and extensive data centers. The United States banking sector is consolidating IT infrastructure, driving significant demand for unified support contracts to reduce operational overhead.
- Government Agencies:These entities require secure and reliable support for diverse IT systems, often adhering to strict data sovereignty and security protocols.
- Education Institutions:Support for educational institutions focuses on managing complex academic networks, learning platforms, and administrative IT across various campuses.
- Manufacturing:This sector increasingly leverages multi vendor support for industrial control systems, IoT devices, and enterprise resource planning applications.
The banking and finance sector continues to drive substantial value, while the telecommunications industry shows consistent expansion.
Deployment Model:
The choice of deployment model reflects an organization's strategic approach to IT resource allocation and operational control.
- On-Premise:This model involves support for IT infrastructure physically located within the client's own data centers and facilities.
- Managed Services:Providers proactively monitor, maintain, and optimize client IT environments under a service-level agreement, offloading day-to-day management. Enterprises in Germany are increasingly adopting managed services for specialized IT functions to optimize internal resource allocation.
- Outsourced Support:Clients delegate specific IT support functions to a third-party provider, often for cost efficiency or specialized expertise.
- Hybrid Solutions:This model integrates support for both on-premise and cloud-based IT assets, offering flexibility and scalability across distributed environments. Adoption is particularly strong in the United States, where companies are balancing legacy systems with new cloud deployments.
Managed Services and Hybrid Solutions are rapidly gaining traction, reflecting a shift towards more flexible and comprehensive support frameworks.
Support Offering:
Distinct support offerings address varying levels of technical complexity and operational urgency within multi vendor environments.
- Technical Helpdesk:Provides first-line support for user queries and basic troubleshooting across a range of hardware and software issues.
- Onsite Assistance:Involves technicians physically present at the client's location to perform hardware repairs, installations, or complex diagnostics.
- Remote Monitoring:This offering uses software tools to continuously track the performance and health of IT assets, often leveraging AI for predictive analytics. Organizations in the United Kingdom are increasingly utilizing remote monitoring to proactively identify potential system failures and optimize uptime.
- Incident Management:Focuses on the rapid resolution of unexpected IT disruptions, restoring service operation as quickly as possible.
- Consulting:Providers offer expert advice on IT strategy, infrastructure optimization, and technology adoption, often preceding or accompanying support contracts. Demand for consulting is rising in the United States as enterprises seek guidance on navigating complex hybrid cloud migrations and cybersecurity frameworks.
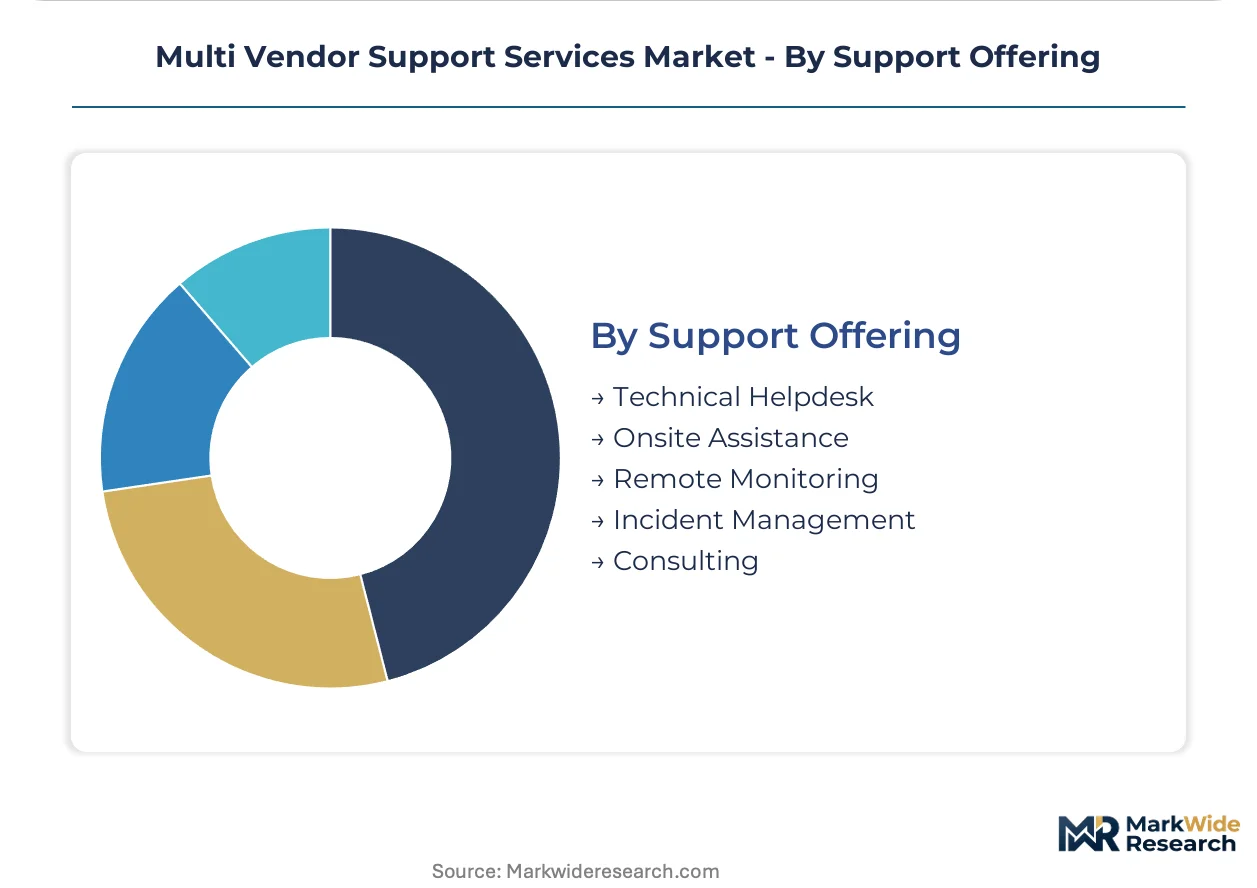
Remote Monitoring and Consulting services are demonstrating the steepest expansion trajectory, driven by proactive and strategic client needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States IT infrastructure consolidation projects and hybrid cloud migrations significantly influence the multi vendor support services market landscape. Demand concentrates in regions with high technological adoption and stringent regulatory environments. Key countries are driving innovation and service uptake across diverse industry verticals.
United States
Large-scale data center optimization and banking sector IT consolidation drive demand for unified support. Healthcare organizations adhere to HIPAA regulations, necessitating secure and compliant IT system management. Silicon Valley continues to innovate in cloud services, requiring sophisticated multi-vendor support for distributed environments.
Germany
Enterprises increasingly adopt managed services to optimize internal IT resource allocation and enhance operational efficiency. GDPR compliance mandates robust data governance frameworks for service providers managing client information. Munich's industrial sector leverages specialized IT support for advanced manufacturing and complex automation systems.
United Kingdom
Organizations increasingly utilize remote monitoring to proactively identify potential system failures and optimize uptime across diverse IT assets. UK GDPR necessitates stringent data protection measures for all multi-vendor support operations. London's financial services industry demands secure, high-availability support for critical banking and fintech infrastructure.
Japan
Telecommunications providers are modernizing networks, requiring extensive multi-vendor support for legacy and emerging technologies. Japan's APPI (Act on Protection of Personal Information) governs data privacy, impacting service delivery models. Tokyo's dense urban centers and technology hubs require sophisticated IT support for their interconnected digital ecosystems.
Multi Vendor Support Services Market Key Industry Players
Global majors compete with regional champions across service breadth and technological specialization within the multi vendor support services market. The landscape features large, diversified IT service providers alongside hardware-centric support specialists and niche cloud-focused firms. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach and capabilities.
IBM Corporation represents a diversified IT service provider, leveraging extensive software and consulting expertise to manage complex, heterogeneous environments. Hewlett Packard Enterprise Development LP exemplifies specialists in hybrid cloud and edge computing infrastructure support. Dell Technologies anchors the hardware-centric support model, tied to its extensive installed base of server and storage hardware.
| Leading Market Players |
|---|
| Dell Technologies |
| IBM Corporation |
| Hewlett Packard Enterprise Development LP |
| Cisco Systems |
| Atos SE |
| DXC Technology Company |
| Fujitsu |
| Hitachi Ltd. |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Banking and finance sector enterprises, driven by IT consolidation, typically procure multi vendor support services through long-term, value-based contracts. These agreements emphasize service level agreements and a single point of contact for complex IT estates.
Pricing Analysis
Rising labor costs for specialized IT talent directly impact service providers' ability to maintain competitive pricing for multi vendor support. Contract-based long-term agreements, often tied to comprehensive SLAs, dominate the market, with differentiation stemming from security protocols and customization for complex hybrid cloud environments. Pricing softness reflects enterprise buyers' need to balance third-party cost benefits against potential OEM warranty invalidation. Small and medium-sized enterprises exhibit higher price sensitivity than regulated industries like banking and healthcare.
Supply Chain Analysis
The reverse logistics for multi vendor support services primarily involves secure data erasure and hardware component replacement, often managed through regional service hubs. Service delivery infrastructure concentrates significantly in the United States, Europe, and Japan, reflecting high demand and regulatory complexity. The supply chain relies heavily on specialized IT talent and access to proprietary OEM diagnostic tools. A structural risk involves restrictions on accessing OEM firmware updates, limiting third-party repair capabilities, while distribution runs through direct service contracts and specialized managed service provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi vendor support services market acts as a regulatory compounder, with stringent data privacy laws like the EU's GDPR significantly shaping service delivery models and driving demand for compliant solutions. These regulations necessitate robust data governance frameworks across all client engagements.
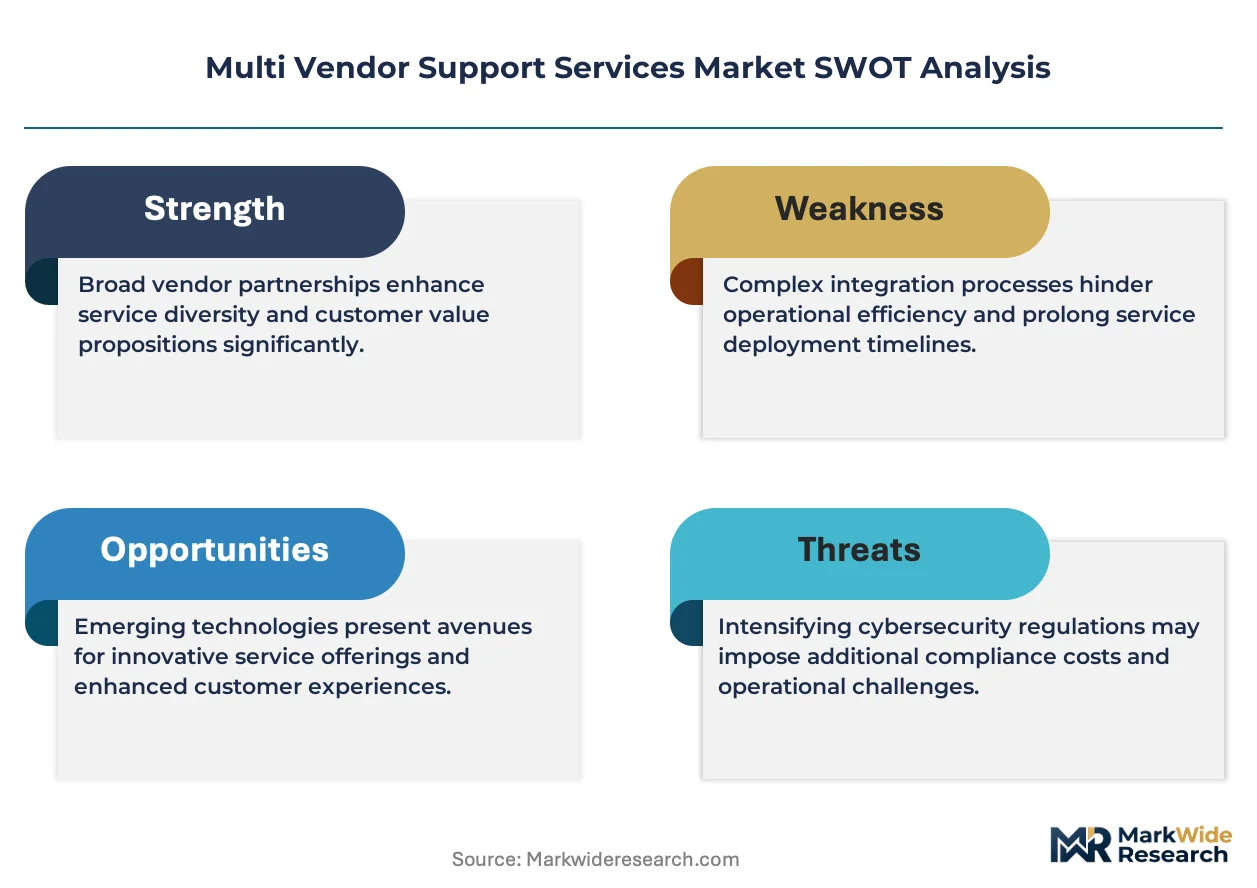
For Market Incumbents: Deploy software integration platforms to unify support for heterogeneous environments, countering OEM proprietary restrictions. Expand service portfolios beyond basic hardware support into higher-margin security management and specialized cloud services. Strategic partnerships can mitigate the specialized talent scarcity, a persistent industry challenge.
For New Entrants and Emerging Players: Online self-service portals and API-driven platforms offer a direct route to penetrate the underpenetrated small and medium-sized enterprise market. Focus on integrating AI-powered predictive analytics with infrastructure monitoring tools for proactive maintenance services. This go-to-market angle provides a differentiated value proposition, addressing system failures before they occur.
For Investors and Strategic Acquirers: Diversified IT service providers are the most active acquirers in this space, seeking to expand their capabilities. The market demonstrates strong long-term viability over the next decade, driven by enterprise hybrid cloud adoption and cybersecurity needs. Acquisition targets should include niche cloud services providers and specialized security management firms with strong compliance expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Hybrid Cloud Service Portfolio | This initiative addresses the enterprise shift towards distributed environments, particularly in the United States. |
| Integrate AI for Predictive Maintenance | AI-powered analytics enable proactive system failure prevention, optimizing uptime for UK organizations. |
| Strengthen Data Sovereignty Compliance | Adherence to regulations like GDPR ensures secure client information management for European entities. |
| Target SME Market with SaaS Solutions | Penetrating the small and medium-sized enterprise segment captures an underpenetrated demand for unified support. |
| Forge OEM Partnership Agreements | Collaborating with original equipment manufacturers mitigates warranty invalidation risks for enterprise buyers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform this analysis. Primary research involved discussions with IT procurement officers, CTOs, service delivery managers, and compliance officers across various enterprises. Secondary validation drew from corporate financial filings, technology industry reports, and regulatory body publications. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
The forecast window was anchored to historical reference periods to establish baseline market performance and growth trajectories. The analytical framework modeled market dynamics across the analysis window, segmented by service type, end-user industry, deployment model, and regional regulatory cluster. Compound annual growth rates were derived from projected enterprise IT spending and hybrid cloud adoption rates, providing a granular view of future market expansion.
The model assumes a particular technology adoption path; alternative pathways for hybrid cloud infrastructure would alter the outlook. Forecasts reflect assumptions regarding OEM policy shifts and the introduction of new data privacy regulations. Practitioners should monitor changes in OEM support policies and evolving regulatory frameworks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market