
 South-East Asia Consulting Services Market | 2026-2036
South-East Asia Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia Consulting Services Market Analytics
Partner-direct access to C-suite procurement committees is narrowing as procurement functions in large Indonesian conglomerates centralize vendor selection through formal panels. Deloitte Touche Tohmatsu Limited leverages its ASEAN network density to sustain long-term public sector mandates across infrastructure and tax modernization. Boston Consulting Group anchors its regional presence through deep specialization in financial services restructuring and sovereign wealth fund advisory.
South-East Asia consulting services encompass advisory engagements spanning strategy formulation, operational improvement, technology implementation, and organizational change management, typically delivered through structured project methodologies with defined deliverables, timelines, and knowledge transfer protocols. These services function primarily to bridge capability gaps in markets where local managerial talent pools remain shallow relative to expansion ambitions. Strategy Consulting captures the premium fee tier due to partner-level scarcity and board-level access requirements, while IT Consulting expands fastest as Vietnamese and Philippine enterprises migrate legacy systems to cloud-native architectures. Project-Based engagements dominate revenue composition, though Performance-Based contracts are gaining traction among private equity-backed portfolio companies seeking outcome-aligned fee structures.
Indonesia's Financial Services Authority and Vietnam's Ministry of Planning and Investment shape demand through mandatory restructuring protocols for distressed state enterprises and foreign investment licensing requirements that necessitate local regulatory advisory. Singapore's Personal Data Protection Commission and Thailand's National Cyber Security Agency impose cross-border data handling standards that consulting firms must embed into digital transformation roadmaps. Stakeholders should monitor how ASEAN regulatory harmonization progresses under the ASEAN Economic Community blueprints, as unified standards would reshape competitive requirements for multi-country operating licenses and practitioner certifications.
Market Dynamics
ASEAN's Digital Economy Framework Agreement is compressing procurement timelines for cross-border advisory engagements while fragmenting vendor eligibility criteria across member states.
Growth Catalysts
- DEFA data localization mandates:Singapore's Personal Data Protection Commission and Thailand's National Cyber Security Agency require consulting firms to architect compliant cross-border data flows, expanding advisory scope for digital transformation projects.
- State enterprise restructuring protocols:Indonesia's Financial Services Authority mandates external advisory for distressed SOEs, creating recurring demand for financial restructuring and operational turnaround expertise.
- Cloud migration acceleration:Vietnamese manufacturers are replacing legacy ERP systems with cloud-native architectures, requiring implementation partners with sector-specific workflow knowledge.
Market Restraints
- Partner talent scarcity:Strategy consulting engagements require board-level access that only senior partners can provide, and ASEAN-based partner pools remain shallow relative to mandate volume.
- Procurement centralization:Large Indonesian conglomerates have consolidated vendor selection through formal panels, narrowing direct C-suite access that previously accelerated deal closure.
- Regulatory fragmentation:Divergent licensing requirements across ASEAN member states force consulting firms to maintain redundant legal entities and practitioner certifications.
Strategic Opportunities
- Philippine BPO upgrade cycle:Business process outsourcing operators require workforce analytics and automation advisory as wage pressures erode cost competitiveness against Indian rivals.
- Performance-based contracting:Private equity-backed portfolio companies in Vietnam and Indonesia are piloting outcome-aligned fee structures that tie consultant compensation to measurable operational improvements.
- Green financing advisory:Singapore's transition finance taxonomy and ASEAN sustainable bond standards create demand for ESG-linked restructuring and capital-raising advisory.
Industry Challenges
- Knowledge transfer execution:Client organizations often lack managerial bandwidth to absorb methodologies, causing implementation gaps between advisory deliverables and sustained operational change.
- Multi-jurisdiction compliance:Cross-border engagements require simultaneous navigation of Indonesia's foreign investment licensing, Vietnam's state procurement rules, and Singapore's professional services regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia Consulting Services Market |
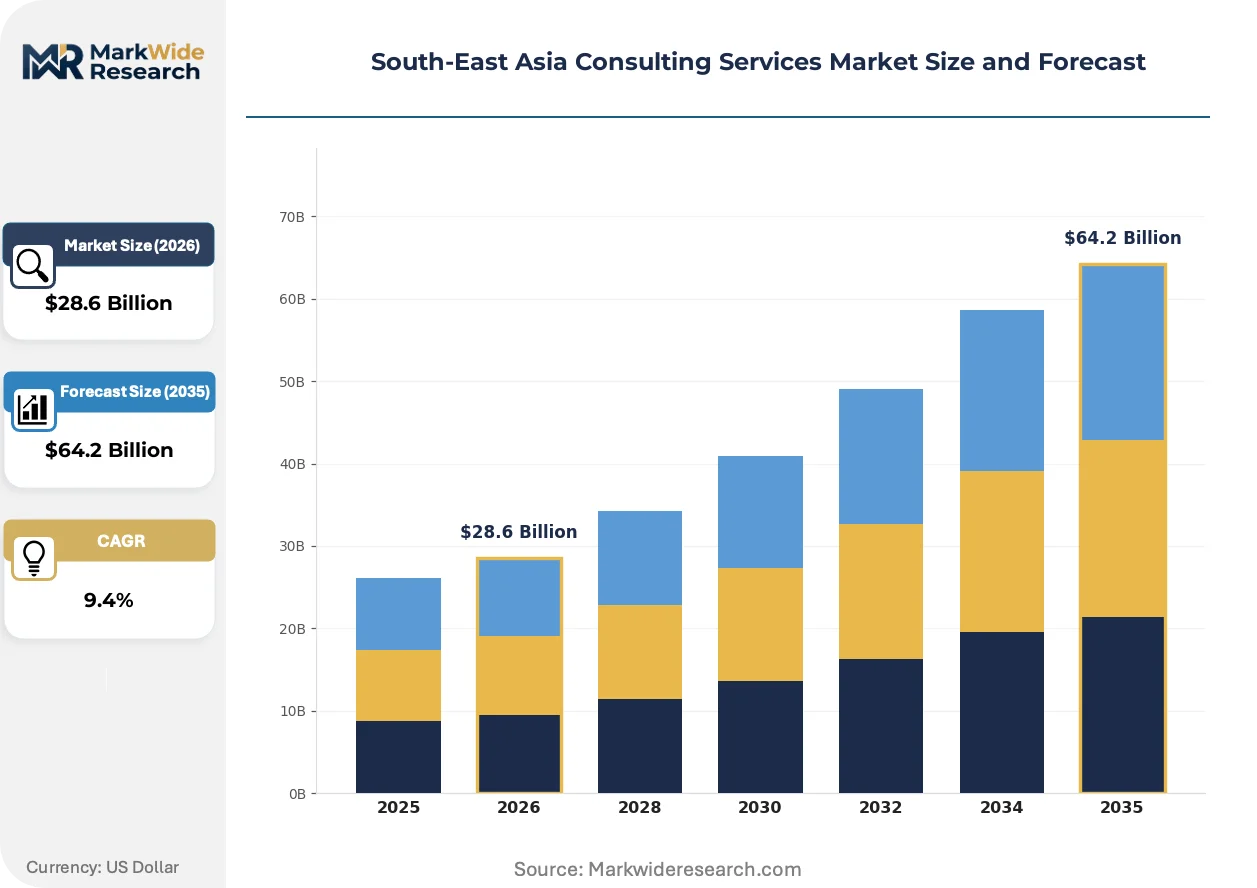
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Management Consulting, IT Consulting, HR Consulting Client Type: Private Sector, Public Sector, Startups, Nonprofits Engagement Model: Project-Based, Retainer-Based, Hourly Consulting, Performance-Based Industry Vertical: Healthcare, Manufacturing, Retail, Technology |
| Companies Covered | Ernst & Young Global Limited, Boston Consulting Group, Deloitte Touche Tohmatsu Limited, Cognizant Technology Solutions Corporation, McKinsey & Company, Accenture PLC, KPMG Consulting, Tata Consultancy Services, PricewaterhouseCoopers LLP, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia Consulting Services Market Evolving Landscape
Advisory delivery models are fragmenting as clients demand embedded implementation support rather than standalone strategy documents, compressing traditional project timelines and reshaping talent deployment patterns.
Artificial intelligence-enabled workflow automation is digitizing diagnostic and benchmarking processes that previously consumed senior consultant hours. Indonesian conglomerates and Vietnamese manufacturers are deploying these tools for rapid operational assessments. This compression is reallocating partner time toward client relationship management and complex negotiation scenarios.
Singapore's Personal Data Protection Commission has tightened cross-border data transfer consent requirements, forcing consulting firms to localize data processing infrastructure. Projects involving multi-country rollouts now require jurisdiction-specific architecture reviews. Financial services clients in Jakarta and Bangkok face the steepest compliance burdens as they modernize core banking platforms.
Buyers are unbundling strategy formulation from implementation execution, awarding separate contracts to specialized providers. Large Indonesian SOEs and Philippine conglomerates now procure diagnostic phases from strategy specialists while engaging IT consultants for systems deployment. This bifurcation is most pronounced in Jakarta and Manila, where procurement functions have gained independent authority over vendor selection.
South-East Asia Consulting Services Market Segmentation
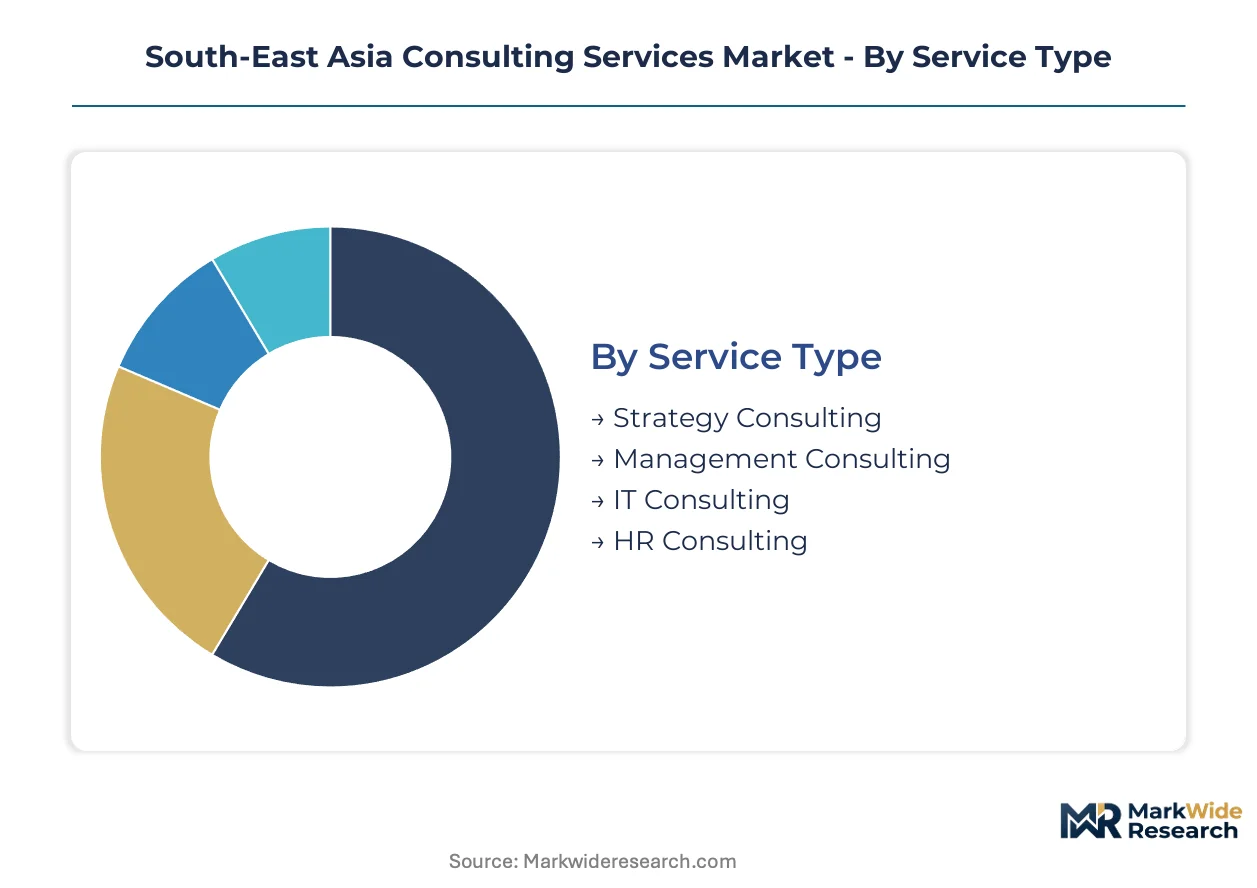
Consulting services in South-East Asia fragment across service specializations, client ownership structures, contract mechanics, and sector-specific expertise requirements. Each segmentation dimension reveals distinct procurement patterns and margin structures that shape competitive positioning across Indonesia, Vietnam, Singapore, and neighboring markets.
Service Type:
Advisory scope spans diagnostic formulation through hands-on implementation, with fee tiers reflecting partner scarcity and client access requirements.
- Strategy Consulting:Board-level advisory on market entry, portfolio restructuring, and competitive positioning mandates. Indonesian conglomerates and Vietnamese state-owned enterprises concentrate demand here, constrained by partner-level talent scarcity across ASEAN.
- IT Consulting:Cloud architecture design, ERP migration, and cybersecurity implementation. Vietnamese manufacturers and Philippine BPO operators drive volume as legacy system replacements accelerate.
- Management Consulting:Operational improvement and organizational design across supply chain and finance functions. Singapore-headquartered multinationals anchor regional demand.
- HR Consulting:Workforce analytics, executive search, and compensation benchmarking. Philippine outsourcing operators deploy these services amid wage pressure from Indian competitors.
Strategy Consulting commands the dominant share by fee value, while IT Consulting is expanding most quickly as digital transformation mandates proliferate.
Client Type:
Ownership structure dictates procurement authority, budget cycles, and compliance overlay complexity.
- Private Sector:Large Indonesian conglomerates and Singapore financial services firms with centralized procurement panels and formal vendor qualification requirements.
- Public Sector:Indonesian state-owned enterprises under Financial Services Authority restructuring mandates and Vietnamese ministries with state procurement rule constraints.
- Startups:Venture-backed technology companies in Jakarta and Ho Chi Minh City seeking rapid scaling advisory on lean operational models.
- Nonprofits:Development organizations and foundations requiring governance and impact measurement advisory, concentrated in Manila and Bangkok.
Private Sector clients generate the dominant revenue concentration, though Public Sector engagements offer longer tenures and recurring mandate structures.
Engagement Model:
Contract mechanics are shifting from fixed deliverables toward outcome-aligned compensation structures.
- Project-Based:Defined scope, timeline, and deliverable specifications with milestone-based payments. Remains the standard for Indonesian SOE restructuring and Vietnamese manufacturing upgrades.
- Performance-Based:Fee components tied to measurable operational improvements or financial outcomes. Private equity-backed portfolio companies in Vietnam and Indonesia are piloting these structures.
- Retainer-Based:Ongoing advisory access with monthly or quarterly fixed fees. Singapore financial services firms favor this for regulatory and strategic continuity.
- Hourly Consulting:Time-and-materials billing for discrete diagnostic or specialist access needs. Smaller Philippine conglomerates use this for targeted expertise.
Project-Based structures retain the dominant share, while Performance-Based contracting is gaining adoption fastest among institutional investors.
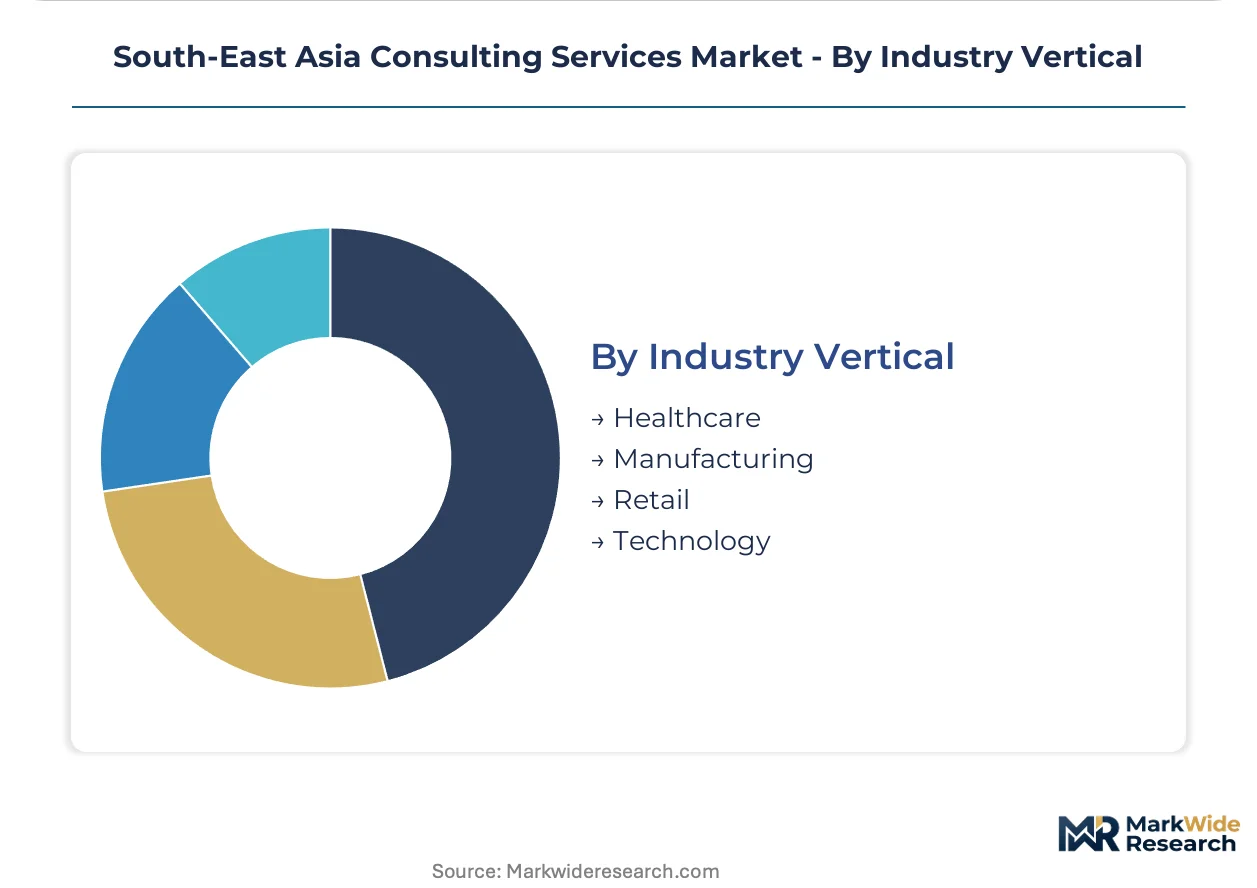
Industry Vertical:
Sector specialization requirements fragment advisory capabilities and practitioner certification demands.
- Financial Services:Regulatory compliance, digital banking transformation, and sovereign wealth fund advisory. Singapore and Jakarta anchor regional demand with strict licensing requirements.
- Manufacturing:Operational excellence, supply chain restructuring, and Industry 4.0 implementation. Vietnamese export manufacturers and Indonesian industrial conglomerates drive engagement volume.
- Healthcare:Hospital network optimization, pharmaceutical distribution, and regulatory pathway navigation. Concentrated in Thailand and Singapore with complex multi-jurisdiction compliance.
- Technology:Platform scaling, data governance, and cross-border data flow architecture. ASEAN Digital Economy Framework Agreement compliance reshapes advisory scope here.
Financial Services captures the dominant share by fee intensity, while Manufacturing is climbing fastest on Vietnam's industrial upgrade programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore commands fee premiums three times Jakarta levels for equivalent digital transformation mandates, while Vietnamese manufacturing hubs absorb advisory volume at compressed margins. This pricing asymmetry reflects talent concentration in the city-state against execution-scale opportunities in emerging markets.
Singapore
Sovereign wealth funds and private banking operations drive demand for financial restructuring advisory. The Personal Data Protection Commission enforces cross-border data transfer consent requirements that expand advisory scope for regional digital rollouts. Marina Bay financial district hosts the densest concentration of strategy consulting partner talent in ASEAN.
Indonesia
State-owned enterprise restructuring under Financial Services Authority protocols creates recurring mandates for operational turnaround specialists. Mandatory external advisory requirements for distressed SOEs institutionalize procurement through formal vendor panels. Jakarta's central business district concentrates conglomerate headquarters where procurement centralization has narrowed direct C-suite access.
Vietnam
Export manufacturers are replacing legacy ERP systems with cloud-native architectures, requiring implementation partners with sector-specific workflow knowledge. Ministry of Planning and Investment foreign investment licensing requirements necessitate local regulatory advisory for cross-border engagements. Ho Chi Minh City industrial zones anchor manufacturing upgrade programs driving IT consulting volume.
Philippines
Business process outsourcing operators require workforce analytics and automation advisory as wage pressures erode cost competitiveness against Indian rivals. Central Bank of the Philippines oversight of digital payment infrastructure creates compliance advisory demand for financial technology implementations. Metro Manila concentrates BPO headquarters where procurement functions have gained independent vendor selection authority.
Thailand
Automotive and electronics manufacturers seek supply chain restructuring advisory amid regional production relocation trends. National Cyber Security Agency cross-border data handling standards force consulting firms to localize infrastructure for multi-country projects. Bangkok's eastern corridor industrial estates host Japanese and Korean manufacturing operations requiring Industry 4.0 implementation support.
South-East Asia Consulting Services Market Competitive Landscape
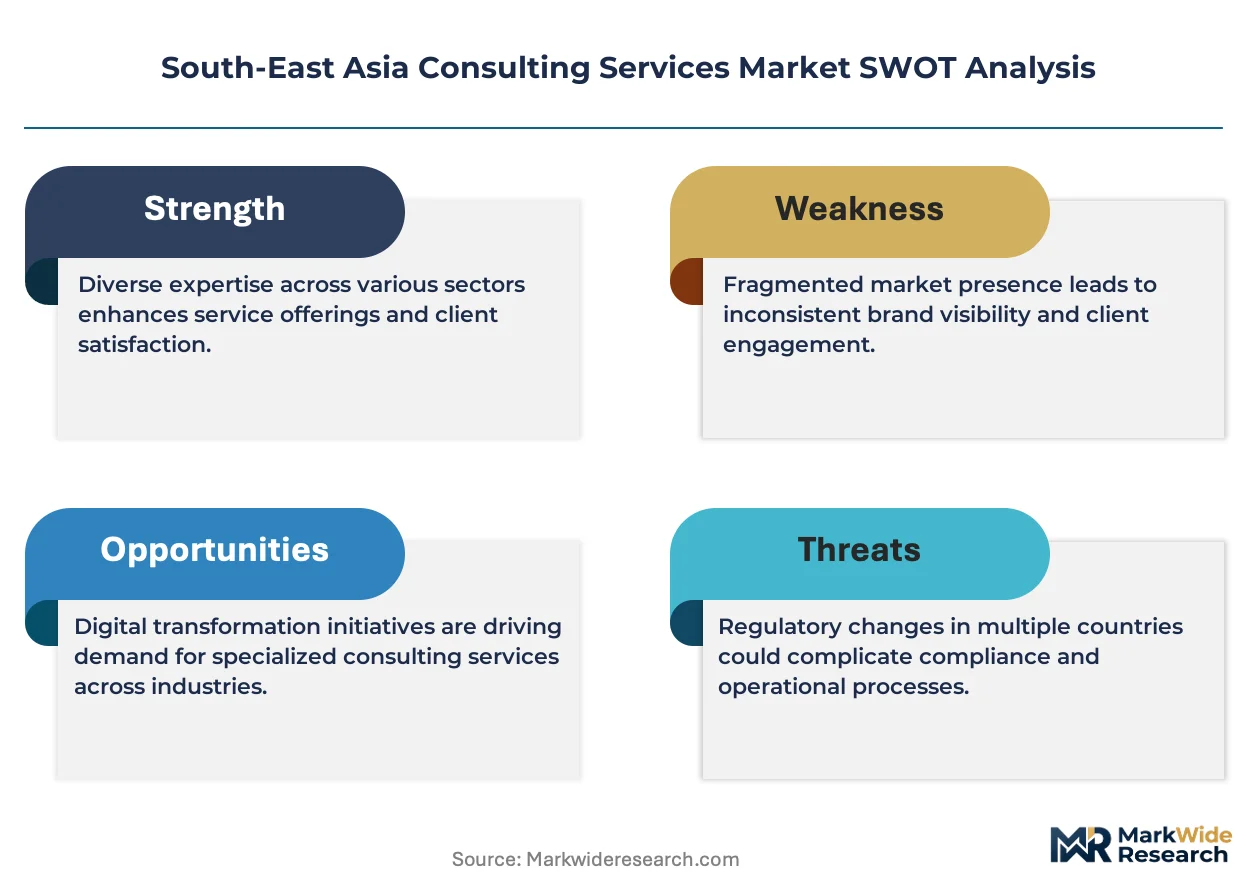
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper vertical expertise. The market structures around a consolidated top tier of global networks with ASEAN-dedicated partner pools, a fragmented mid-tier of regional boutiques, and a growing specialist tier focused on regulatory compliance and sector-specific implementation. Three archetypes dominate: global networks leveraging cross-border credential portability, regional champions exploiting local regulatory intimacy, and technology-forward boutiques embedding AI-enabled diagnostic tools. Competitive moves concentrate on talent poaching from rival partner ranks and performance-based contract structuring to differentiate from time-and-materials incumbents.
Among global network anchors, Deloitte Touche Tohmatsu Limited and Boston Consulting Group exemplify divergent specialization strategies within the same geographic footprint. Ernst & Young Global Limited occupies a position bridging assurance heritage with advisory expansion, reflecting the broader accounting-network pivot into consulting services. These three firms represent how credential portability and long-tenure public sector relationships create defensive positioning against boutique disruption.
| Leading Market Players |
|---|
| Ernst & Young Global Limited |
| Boston Consulting Group |
| Deloitte Touche Tohmatsu Limited |
| Cognizant Technology Solutions Corporation |
| McKinsey & Company |
| Accenture PLC |
| KPMG Consulting |
| Tata Consultancy Services |
| PricewaterhouseCoopers LLP |
| Others |
Value Network & Pricing Analysis
The Singapore-Jakarta air freight corridor compresses delivery timelines for partner-level talent deployment while amplifying cost differentials between strategy advisory and implementation services. This logistics dynamic concentrates premium pricing power in Singapore's Marina Bay financial district while eroding margins in Vietnamese manufacturing zones where execution-scale volume competes on cost.
Pricing Analysis
Configured-to-order advisory commands fee premiums three times standard project rates, with Strategy Consulting partners billing at board-access tiers while IT implementation compresses toward commodity levels. Price differentiation rests on certification depth—regulatory advisory for Indonesia's Financial Services Authority mandates carries scarcity premiums against generic operational improvement. Pricing pressure intensifies in Vietnamese cloud migration markets as implementation partners multiply. Private equity-backed portfolio companies exhibit lowest price sensitivity for outcome-aligned contracts, while Philippine BPO operators drive hardest bargain on workforce analytics.
Supply Chain Analysis
Tariff exposure between Singapore and Indonesia dominates supply chain risk for cross-border advisory engagements requiring physical partner presence. Talent concentration anchors in Singapore, Malaysia, and Australia, with raw capability inputs drawing from London and New York partner pools. Single-source vulnerability concentrates at senior partner level where ASEAN-based talent remains shallow relative to mandate volume. Distribution runs through formal vendor panels in Jakarta and direct C-suite relationships in Singapore's sovereign wealth funds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring retainer relationships and performance-based contracts expand faster than discrete project engagements. The shift toward embedded implementation support creates durable revenue layers beyond standalone strategy deliverables.
For Market Incumbents: Harden partner retention through equity-linked compensation structures as boutique specialists poach senior talent with outcome-based fee participation. Defend position by deepening regulatory certification moats around Indonesia's SOE restructuring protocols and Singapore's cross-border data compliance mandates. Priority investment centers on AI-enabled diagnostic tools that compress junior consultant hours and reallocate partner capacity toward relationship management. For New Entrants and Emerging Players: Establish a beachhead in Philippine BPO automation advisory where wage pressure from Indian rivals creates urgent demand for workforce analytics specialists. White-space targets include Vietnam's mid-tier manufacturers seeking cloud-native ERP implementation without premium-tier consulting overhead. Go-to-market angle should emphasize sector-specific workflow knowledge over generalist strategy credentials. For Investors and Strategic Acquirers: ASEAN Digital Economy Framework Agreement harmonization reshapes the acquisition landscape by rewarding multi-jurisdiction license holders. Long-term viability favors platforms with established regulatory intimacy across Indonesia, Vietnam, and Singapore. Acquisition target archetype: technology-forward boutiques embedding AI diagnostics with existing public sector relationships. Signal to watch is procurement centralization momentum in Jakarta conglomerates.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting | Aligns consultant compensation with measurable operational improvements for private equity portfolio companies. |
| Regulatory Certification Investment | Builds defensible positioning around Indonesia's Financial Services Authority restructuring mandates. |
| AI-Enabled Diagnostic Development | Compresses project timelines and reallocates partner time toward high-value client relationships. |
| Multi-Jurisdiction License Expansion | Captures cross-border advisory demand under ASEAN Digital Economy Framework Agreement compliance requirements. |
| Sector-Specialist Acquisition | Addresses unbundling trend where clients procure strategy and implementation from separate providers. |
Research Methodology
A spread of perspectives from strategy consulting partners, procurement directors at Indonesian conglomerates, regulatory affairs specialists, and private equity operating partners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Singapore Personal Data Protection Commission filings, Indonesia Financial Services Authority restructuring protocols, Vietnam Ministry of Planning and Investment licensing records, and ASEAN secretariat trade documentation. Bottom-up engagement sizing triangulated against top-down market reconstruction.
Demand-supply balance across service types, client ownership structures, and contract mechanics anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include service specialization, engagement model, and industry vertical with regional regulatory cluster overlays. CAGRs derived from trajectory analysis of historical mandate volumes and procurement pattern shifts. Forecast inputs incorporated partner talent pipeline constraints and procurement centralization velocity in Jakarta and Manila.
Stress conditions across regulatory harmonization pace, partner attrition rates, and performance-based contract adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on ASEAN Digital Economy Framework Agreement implementation timelines and SOE restructuring mandate continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Managed Services Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Qatar Cloud Managed Services Market