
 GCC Set-Top Box Market | 2026-2036
GCC Set-Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Set-Top Box Market Intelligence
Multi-source procurement among Gulf telecom operators is expanding as operators diversify beyond single-vendor legacy contracts. Huawei Technologies Co., Ltd leverages its end-to-end network infrastructure portfolio to anchor large-scale IPTV deployments across Saudi Arabia and the UAE. Samsung Electronics Co., Ltd competes through vertically integrated display and semiconductor supply chains that sustain cost discipline in 4K set-top production. Sagemcom SAS specializes in hybrid broadcast-broadband platforms that differentiate its offering for operators seeking unified DVB-T and OTT delivery.
A set-top box functions as a dedicated receiver-decoder unit that demodulates broadcast, broadband, or satellite signals for television display, typically incorporating conditional access modules, HDMI output interfaces, and embedded Linux or Android operating systems to enable encrypted content decryption and interactive services. The product type dimension shows hybrid units retaining volume leadership due to backward compatibility with legacy coaxial infrastructure, while OTT-native devices capture the fastest expansion as Gulf operators sunset DVB-T spectrum allocations. Within the technology segment, 4K resolution commands the dominant margin pool because premium tiering aligns with operator ARPU strategies, whereas wireless connectivity remains nascent outside high-end residential and hospitality deployments.
The UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's Communications, Space and Technology Commission enforce device certification and cybersecurity standards that shape hardware import protocols and firmware update obligations. TRAI-equivalent frameworks across Bahrain, Oman, and Kuwait mandate interoperable conditional access and data localization provisions that complicate cloud-integrated OTT architectures. Stakeholders must monitor spectrum reallocation timelines and conditional access migration requirements to align product roadmaps with operator procurement cycles.
Market Dynamics
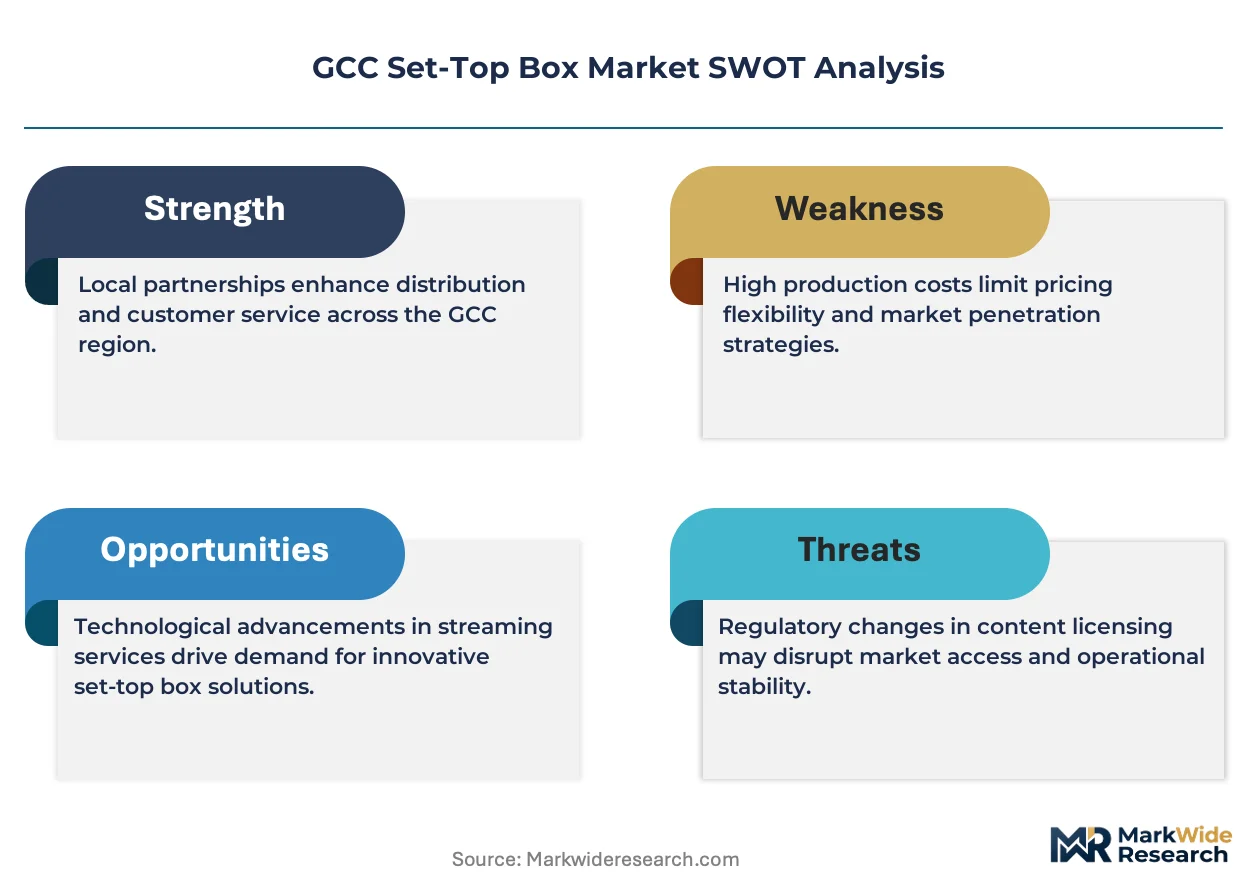
Hybrid broadcast-broadband architectures are fragmenting operator procurement patterns across Saudi Arabia and the UAE, forcing vendors to recalibrate conditional access integration and firmware localization strategies.
Growth Catalysts
- Fiber-to-the-home mandates:Gulf state telecommunications regulators are accelerating last-mile fiber deployment, expanding addressable households for IPTV-ready set-top installations.
- Smart home entertainment convergence:Residential demand in Riyadh and Jeddah corridors is pulling integrated OTT-broadcast receivers into new housing developments.
- Hospitality sector premium tiering:Dubai's hotel operators are replacing legacy coaxial systems with 4K-enabled interactive platforms to differentiate guest experience.
Market Restraints
- Semiconductor supply concentration:System-on-chip and tuner module sourcing remains concentrated among Taiwan and South Korea foundries, exposing procurement timelines to geopolitical friction.
- Conditional access migration costs:Operators face stranded asset risk in legacy DVB-T encryption hardware as Gulf regulators reallocate terrestrial spectrum.
- OTT-native substitution:Smart TV embedded streaming applications are compressing standalone set-top attach rates in premium residential segments.
Strategic Opportunities
- Oman and Bahrain penetration gaps:These markets exhibit lower IPTV household penetration than Saudi Arabia and the UAE, creating whitespace for operator infrastructure investment.
- Android TV Operator Tier licensing:Google's reduced certification burden for regional operators is accelerating custom launcher deployments.
- Cybersecurity certification mandates:Saudi Arabia's Communications, Space and Technology Commission device security frameworks are creating compliance service revenue streams for firmware developers.
Industry Challenges
- Embedded Linux talent scarcity:Gulf-based operators report difficulty recruiting kernel-level developers capable of customizing Android Open Source Project builds for regional conditional access modules.
- Multi-vendor integration complexity:Operators diversifying procurement beyond single-vendor legacy contracts face interoperability testing delays across middleware, DRM, and user interface layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Set-Top Box Market |
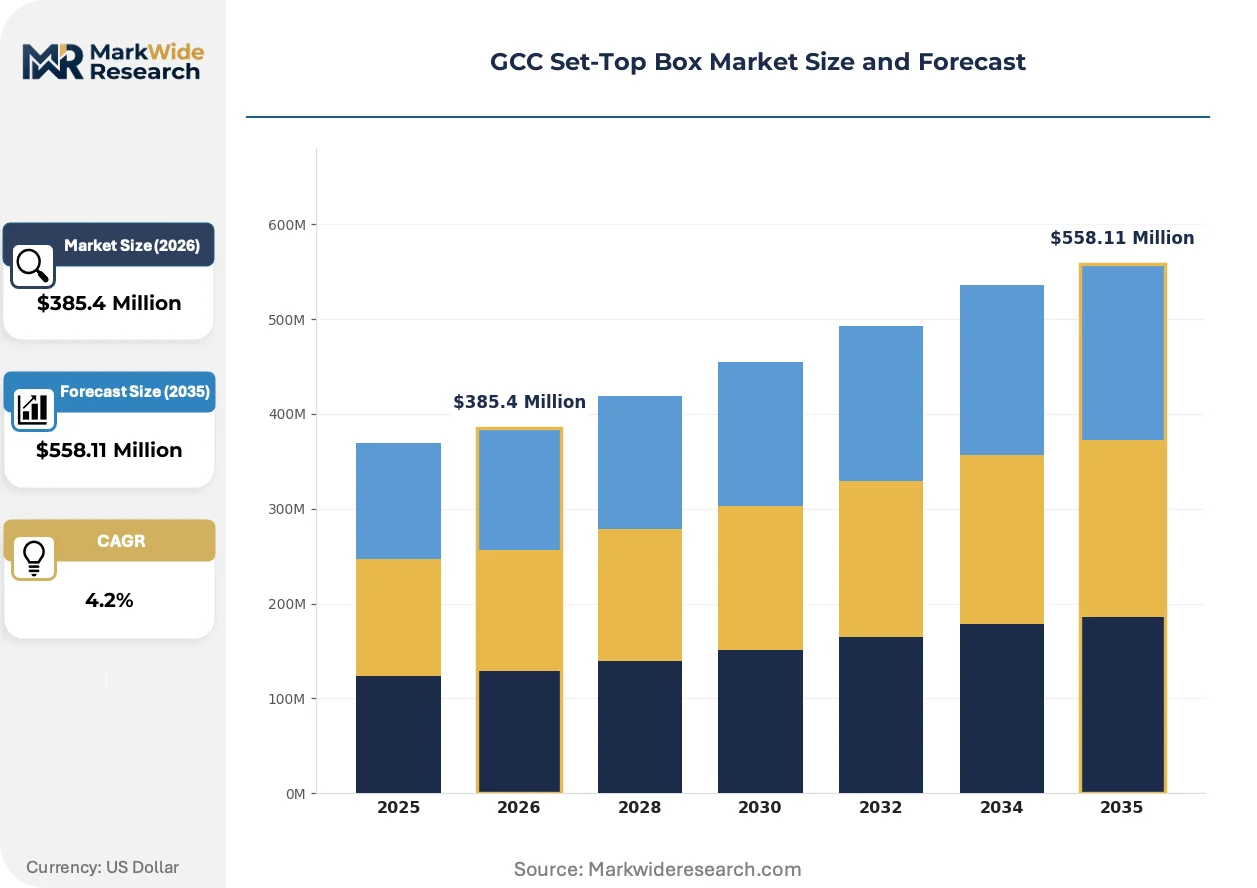
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, IPTV, DVB-T, OTT Technology: 4K, HD, Smart TV, Wireless End User: Residential, Commercial, Education, Hospitality Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Huawei Technologies Co., Ltd, CommScope Holding Company, Inc., Technicolor SA, Sagemcom SAS, HUMAX Co., Ltd, Advanced Digital Broadcast SA, Samsung Electronics Co., Ltd, EchoStar Corporation, Kaonmedia Co., Ltd, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Set-Top Box Market Strategic Shifts & Innovations
Cloud-native middleware and edge-based content delivery are compressing traditional hardware-software boundaries, reshaping how Gulf operators architect subscriber management and video quality adaptation.
Edge caching nodes positioned within ISP last-mile infrastructure are decentralizing content origination away from centralized head-ends. Saudi Telecom Company and Etisalat are deploying these nodes in Riyadh and Dubai metro rings to reduce backhaul congestion during peak viewing windows. This topology is decentralizing quality-of-service guarantees and forcing set-top firmware to handle more dynamic bitrate negotiation.
Saudi Arabia's Communications, Space and Technology Commission issued mandatory cybersecurity certification timelines requiring firmware signing and encrypted boot chains. Device manufacturers must now submit hardware to approved testing laboratories before import clearance. The compliance burden falls heaviest on smaller OTT-native vendors lacking in-house security engineering.
Direct-to-operator software licensing is displacing traditional set-top box OEM bundled middleware contracts. Etisalat and STC now negotiate Android TV and RDK licenses separately from hardware procurement, unbundling the stack. This unbundling is most visible in the UAE, where operators seek differentiation through custom user interfaces rather than commodity hardware specifications.
GCC Set-Top Box Market Segmentation
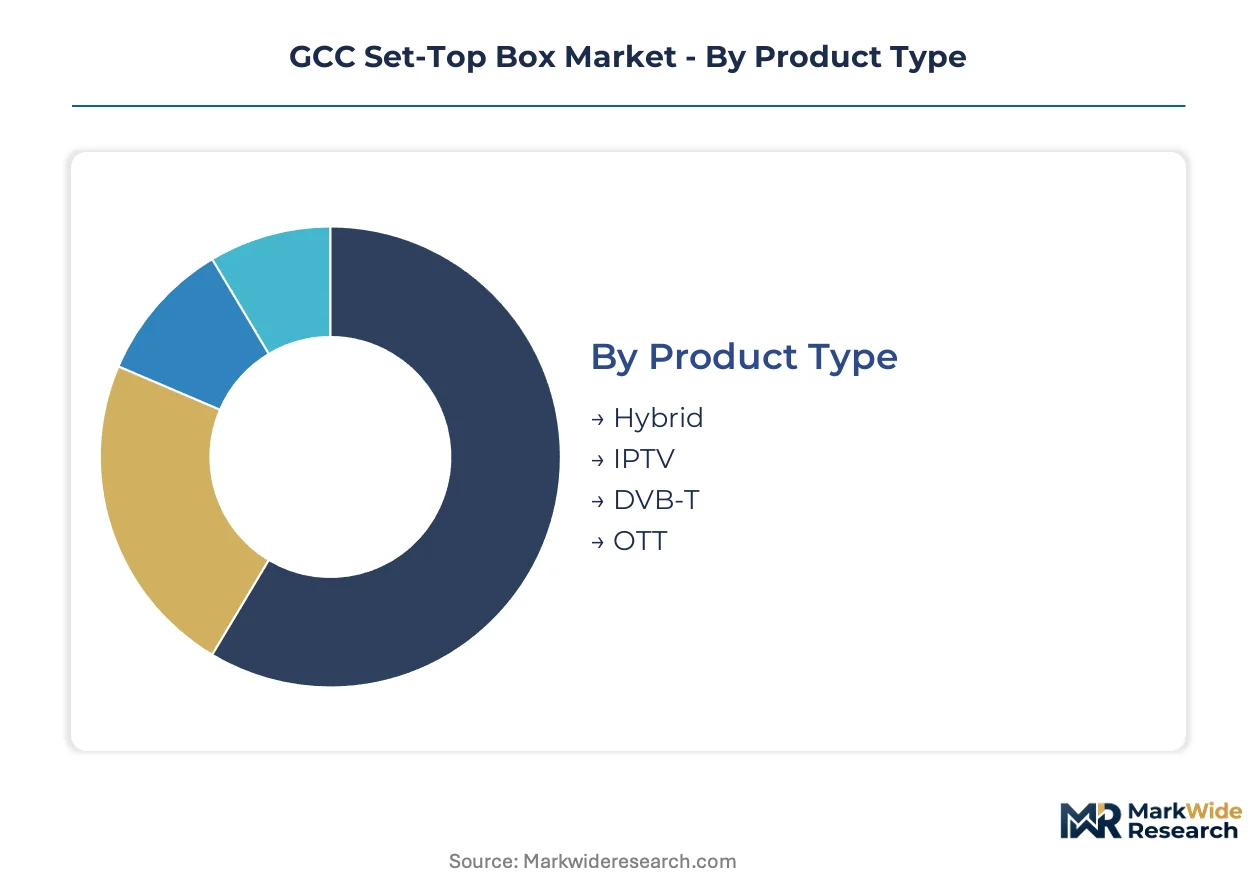
Segmentation in the GCC set-top box market reflects divergent infrastructure maturity across Gulf states and varying operator procurement strategies. Product architecture choices determine conditional access compatibility, while technology tiers align with fiber deployment timelines and hospitality upgrade cycles.
Product Type:
The customization-to-standardization spectrum spans purpose-built OTT-native devices at one extreme and backward-compatible hybrid units accommodating legacy coaxial infrastructure at the other.
- Hybrid:These units integrate DVB-T tuners with IP connectivity, enabling simultaneous broadcast and broadband reception. Demand concentrates in Saudi Arabia's secondary cities where STC and Mobily maintain coaxial plant alongside fiber overlays, driven by regulator-mandated spectrum transition timelines that prevent immediate DVB-T shutdown.
- OTT:Native IP devices eliminate broadcast tuners entirely, reducing bill-of-materials cost and enabling cloud-based conditional access. Dubai's hospitality sector and Riyadh's new residential developments are pulling these units as Etisalat and STC sunset legacy encryption systems.
- IPTV:Operator-locked devices with proprietary middleware and DRM integration dominate Saudi Telecom Company and Etisalat subscriber bases.
- DVB-T:Pure terrestrial receivers face contracting demand as Gulf regulators reallocate spectrum bands, though residual need persists in Bahrain and Oman markets with slower fiber penetration.
Most installed capacity flows through Hybrid units. Expansion is steepest in OTT-native devices as operators accelerate all-IP migration.
Technology:
Cost tiering separates premium 4K deployments in hospitality and high-end residential from HD-standard volumes in mass-market segments.
- 4K:Ultra-high-definition chipsets with HEVC decoding and HDMI 2.0 output command premium positioning. Dubai's hotel operators and Saudi luxury residential compounds specify these units to differentiate guest and tenant experiences.
- HD:1080p devices with AVC compression remain the volume workhorse across GCC mass-market IPTV subscriptions, particularly in Kuwait and Qatar where operator ARPU strategies emphasize affordability over resolution tiering.
- Smart TV:Integrated Android TV and RDK platforms enable operator-branded user interfaces and app ecosystems, with Saudi Arabia's CST cybersecurity mandates shaping firmware certification requirements.
- Wireless:Wi-Fi 6 and mesh-enabled set-tops eliminate Ethernet dependency, finding niche adoption in UAE villa developments and Saudi compound housing where structured cabling is absent.
4K resolution dominates margin capture. HD maintains volume leadership across subscriber bases.
End User:
Application context determines feature prioritization, from conditional access complexity in hospitality to simplicity in residential mass deployment.
- Residential:Household installations prioritize cost efficiency and self-installation simplicity, with Saudi Arabia's Riyadh and Jeddah corridors representing the largest addressable base as fiber-to-the-home mandates expand.
- Hospitality:Hotel and serviced apartment deployments demand centralized management, guest billing integration, and multilingual interfaces, with Dubai's tourism infrastructure driving replacement cycles.
- Commercial:Corporate and retail deployments emphasize digital signage compatibility and centralized content control.
- Education:University and training campus installations require multicast support and lecture capture integration, a smaller segment concentrated in UAE and Saudi government education initiatives.
Residential accounts for the majority of unit shipments. Hospitality delivers the highest per-unit value realization.
Distribution Channel:
Customer type and procurement scale determine channel selection, from consumer self-service to operator bulk tender processes.
- Direct Sales:Operator procurement teams negotiate directly with OEMs for subscriber equipment, representing the dominant volume path for Saudi Telecom Company, Etisalat, and Zain KSA infrastructure investments.
- Wholesalers:Regional distributors aggregate inventory for smaller operators and retail chains across Bahrain, Oman, and Kuwait markets with fragmented service provider landscapes.
- Online:E-commerce platforms serve replacement and upgrade demand from tech-forward consumers, particularly in UAE urban centers.
- Retail:Electronics stores and operator-branded outlets provide immediate fulfillment for subscriber self-installation scenarios.
Direct sales capture the largest revenue share. Online channels are gaining traction fastest among replacement purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement flows as vendors navigate divergent certification burdens across Gulf states. Compliance cost gaps between Saudi Arabia's cybersecurity mandates and Bahrain's lighter frameworks are steering initial deployment decisions toward lower-friction entry points.
Saudi Arabia
Fiber-to-the-home mandates from the Communications, Space and Technology Commission are accelerating IPTV-ready set-top installations across Riyadh and Jeddah corridors. The CST's mandatory cybersecurity certification timelines require firmware signing and encrypted boot chains for all imported devices. STC and Mobily are deploying hybrid units in secondary cities where coaxial plant overlays persist alongside fiber infrastructure.
United Arab Emirates
Dubai's hospitality sector is driving replacement cycles as hotel operators install 4K-enabled interactive platforms to differentiate guest experiences. The Telecommunications and Digital Government Regulatory Authority enforces device certification and data localization standards that complicate cloud-integrated OTT architectures. Etisalat is deploying edge caching nodes within Dubai metro rings to reduce backhaul congestion during peak viewing windows.
Oman
Lower IPTV household penetration relative to Saudi Arabia and the UAE creates whitespace for operator infrastructure investment in Muscat and Salalah corridors. The country's national telecommunications regulator mandates interoperable conditional access provisions that shape middleware procurement decisions. Omantel is expanding fiber overlays in urban centers to support hospitality and residential premium-tier deployments.
Bahrain
Fragmented service provider landscapes are pulling wholesale distribution channels for smaller operator procurement teams. The national telecommunications authority maintains lighter device certification frameworks than Saudi Arabia or the UAE, reducing compliance lead times for OTT-native vendors. Batelco and alternative operators are testing Android TV Operator Tier licensing for custom launcher differentiation.
Kuwait
Operator ARPU strategies emphasize affordability over resolution tiering, sustaining HD-standard volume demand across mass-market IPTV subscriptions. The national telecommunications regulator enforces data localization requirements that affect cloud-integrated service architectures. Zain Kuwait and Ooredoo are balancing hybrid unit procurement with gradual OTT migration timelines.
GCC Set-Top Box Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-unbundled licensing models that separate middleware from hardware procurement. Market structure exhibits moderate concentration with tiered positioning between integrated network infrastructure vendors and specialized device fabricators. Three archetypes dominate: end-to-end network suppliers, vertically integrated display-semiconductor conglomerates, and hybrid broadcast-broadband platform specialists. Competitive moves center on direct-to-operator software licensing negotiations and cybersecurity compliance service bundling.
Among Asia-Pacific-based technology conglomerates, Huawei Technologies Co., Ltd and Samsung Electronics Co., Ltd exemplify divergent strategic positioning within the supplier base. Huawei anchors large-scale IPTV deployments through end-to-end network infrastructure portfolios across Saudi Arabia and the UAE. Samsung occupies a position sustained by vertically integrated display and semiconductor supply chains. French specialist Sagemcom SAS represents the hybrid broadcast-broadband platform archetype, differentiating through unified DVB-T and OTT delivery capabilities for operators managing spectrum transition timelines.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd |
| CommScope Holding Company, Inc. |
| Technicolor SA |
| Sagemcom SAS |
| HUMAX Co., Ltd |
| Advanced Digital Broadcast SA |
| Samsung Electronics Co., Ltd |
| EchoStar Corporation |
| Kaonmedia Co., Ltd |
| Others |
Cost & Logistics Intelligence
Fiber-to-the-home mandates across Saudi Arabia and the UAE are forcing operators to consolidate procurement around IPTV-ready specifications, compressing supplier margins and pushing vendors toward volume-scale manufacturing partnerships in East Asia. This demand-side specification tightening reshapes how set-top box OEMs negotiate component sourcing and pass through semiconductor cost volatility.
Pricing Analysis
Input-cost pass-through from system-on-chip and tuner module suppliers in Taiwan and South Korea dominates pricing dynamics across the GCC set-top box market. Pricing stratifies across cybersecurity-certified premium tiers, standard HD volumes, and economy OTT-native units, with Saudi Arabia's CST device security mandates widening spreads between compliant and non-compliant hardware. Cost compression in standard HD segments is intensifying because Kuwaiti and Qatari operators prioritize affordability over resolution tiering in mass-market subscriptions. Hospitality buyers in Dubai exhibit the least price sensitivity, while residential self-install purchasers in Bahrain and Oman drive the hardest unit-cost negotiations.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan manufacturing clusters are forcing set-top box OEMs to diversify final assembly toward Vietnam and Indonesia. System-on-chip fabrication draws from Taiwan Semiconductor Manufacturing facilities, tuner modules rest on South Korean foundry output, and conditional access hardware sources from French and Dutch security specialists. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical friction around Taiwan Strait logistics threatens procurement timelines. Distribution runs through operator direct procurement teams for Saudi Telecom Company and Etisalat bulk tenders, with regional wholesalers serving fragmented Bahrain and Kuwait service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC set-top box market functions as a stable compounder anchored by regulatory-mandated infrastructure replacement cycles that ensure predictable equipment refresh demand across Gulf state telecommunications operators.
For Market Incumbents: Hedge against OTT-native substitution by deepening Android TV Operator Tier licensing capabilities and securing firmware signing authority under Saudi CST cybersecurity frameworks. Incumbents must defend hybrid unit market share through backward integration into conditional access module design, countering emerging software-unbundled entrants that separate middleware from hardware procurement. Capacity addition in Vietnamese assembly plants reduces exposure to China-based logistics disruptions. For New Entrants and Emerging Players: Launch via direct-to-operator software licensing models that bypass traditional OEM bundled middleware contracts, targeting Etisalat and STC procurement teams seeking custom user interface differentiation. Oman and Bahrain penetration gaps represent the most penetrable geographies, with lower IPTV household saturation than Saudi Arabia and the UAE. A cybersecurity compliance service bundling angle addresses Saudi Arabia's mandatory firmware certification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid broadcast-broadband platform specialists possessing unified DVB-T and OTT delivery architectures that align with Gulf regulator spectrum transition timelines. Long-term viability over the next decade hinges on software-unbundling traction and edge caching node deployment scale. The signal to watch is Android TV Operator Tier adoption velocity across Saudi Telecom Company and Etisalat procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Saudi CST device security frameworks create compliance service revenue streams for firmware developers. |
| Android TV Operator Tier Licensing | Google's reduced certification burden accelerates custom launcher deployments across UAE and Saudi operators. |
| Edge Caching Node Deployment | Etisalat and STC metro ring installations reduce backhaul congestion during peak viewing windows. |
| Direct-to-Operator Software Licensing | Unbundled middleware negotiations separate stack procurement from hardware specifications in UAE tenders. |
| Hybrid Unit Backward Compatibility | DVB-T tuner retention addresses Saudi secondary city coaxial plant overlays during fiber transition. |
Research Approach
Multiple input streams — operator procurement officer interviews, semiconductor supply chain assessments, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged set-top box OEM product managers, Gulf telecommunications regulatory affairs leads, hospitality technology procurement directors, and firmware engineering specialists. Secondary validation drew from CST cybersecurity certification timelines, TDRA device import protocols, customs and trade data for GCC electronics imports, and operator capex disclosure filings. Cross-referencing shipment volumes against fiber-to-the-home deployment schedules anchored demand-side calibration.
Historical operator procurement patterns were cross-referenced against panel input from vendor sales directors and distribution channel partners across the analysis window. Segmentation modeling incorporated product architecture, resolution tier, end-use application, and distribution channel dimensions alongside cybersecurity compliance status as an industry-specific stratifier. CAGRs were derived from reconciling bottom-up unit shipment builds with top-down addressable household expansion tied to regulator-mandated infrastructure timelines. Forecast inputs included semiconductor foundry capacity allocation disclosures and Gulf state spectrum reallocation schedules.
Several conditions sit outside the modeled scope, including unannounced geopolitical disruptions to Taiwan Strait semiconductor logistics and accelerated smart TV embedded streaming substitution rates. Forecasts reflect documented assumptions around fiber deployment pacing and conditional access migration timelines. Material deviation in regulator spectrum reallocation schedules or cybersecurity certification burden changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Network Devices Market
Network Technology
Global Internet Transit Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
MENA Wireless Routers Market
Network Technology
Mobile Backhaul Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Network Performance Monitoring Market
Network Technology
Industrial Ethernet Market
Network Technology
Global Intelligent Network Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
UK Fixed Connectivity Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Global Network Probe Market
Network Technology
Data Center Switches Market
Network Technology
Network Packet Broker Market