
 ASEAN Electric Vehicle Market | 2026-2036
ASEAN Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Electric Vehicle Market Analysis
Project finance structures tied to battery leasing and asset-light fleet ownership is tilting competitive dynamics toward capital-efficient operators. BYD Company Limited leverages its in-house battery cell production to sustain margin pressure across ASEAN price-sensitive segments. Hyundai Motor Company anchors its regional position through dedicated EV platform manufacturing in Indonesia. VinFast Auto Ltd. competes on vertical integration depth, controlling charging infrastructure deployment alongside vehicle sales in Vietnam and export markets.
ASEAN Electric Vehicles are road-certified automobiles powered by rechargeable battery packs, electric motors, and power electronics with energy densities typically exceeding 150 Wh/kg at the cell level, designed for zero-tailpipe-emission passenger and goods movement. Battery Electric configurations dominate unit economics across tropical climates where thermal management efficiency directly impacts range retention. DC Fast Charging infrastructure represents the fastest-expanding segment as commercial fleets and shared mobility operators prioritize turnaround time over residential convenience. Passenger Cars remain the volume anchor, though Two-wheelers command disproportionate policy attention in Indonesia, Vietnam, and the Philippines where motorcycle dependency shapes electrification pathways.
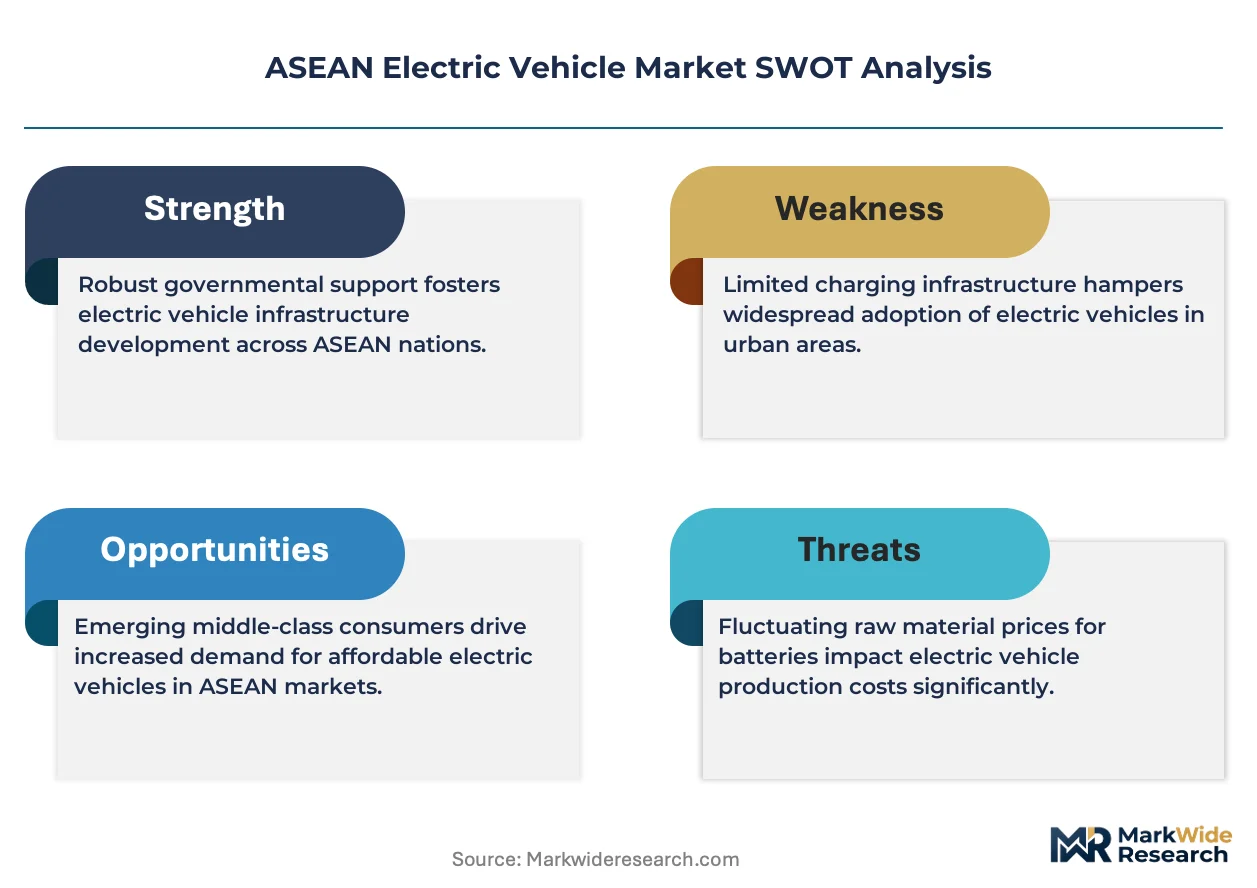
Thailand's Board of Investment, Indonesia's Ministry of Industry, and Singapore's Land Transport Authority collectively shape demand through localized incentive structures, domestic content requirements, and carbon-based vehicle taxation schemes. BIS-equivalent national standards in Indonesia and Thailand are harmonizing slowly, creating compliance complexity for multi-market manufacturers. Stakeholders must monitor regulatory divergence on battery recycling mandates and local assembly thresholds as these will determine which production configurations achieve cost-competitive market access across the six major ASEAN economies.
Market Dynamics
Fleet electrification mandates from ride-hailing operators are compressing vehicle replacement cycles and redirecting capital toward charging infrastructure partnerships across Southeast Asian urban corridors.
Growth Catalysts
- Thailand BOI EV Incentive Packages:Tax holidays and import duty exemptions for battery production facilities are attracting component manufacturers to the Eastern Economic Corridor.
- Jakarta BRT Electrification:Grid-connected bus rapid transit corridors are generating concentrated demand for heavy-duty electric buses with standardized charging protocols.
- Lithium-Ion Cell Cost Curves:Declining battery pack costs are enabling price parity for two-wheeler electrification in Vietnam and Indonesia motorcycle markets.
Market Restraints
- Charging Infrastructure Gaps:DC fast charging networks remain concentrated in Bangkok, Singapore, and Jakarta, leaving intercity corridors underserved.
- Grid Instability:Indonesia's state electricity provider PLN faces capacity constraints in Greater Jakarta that limit simultaneous fleet charging at scale.
- BIS-Equivalent Standards Divergence:Thailand's TISI and Indonesia's SNI certification requirements create compliance duplication costs for multi-market manufacturers.
Strategic Opportunities
- Philippines Motorcycle Electrification:Underpenetrated two-wheeler EV adoption in Metro Manila and Cebu presents first-mover advantages for localized assembly.
- Battery Leasing Finance Models:Asset-light fleet ownership structures reduce upfront capital barriers for commercial operators in Vietnam.
- Singapore Carbon Tax Escalation:Scheduled carbon price increases from the National Environment Agency are accelerating commercial fleet replacement timelines.
Industry Challenges
- Power Electronics Talent Scarcity:Shortages of motor control engineers and battery management system specialists constrain R&D expansion in Thailand and Indonesia.
- Recycling Mandate Uncertainty:Pending regulations on end-of-life battery recovery obligations create planning ambiguity for manufacturers investing in regional production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Electric Vehicle Market |
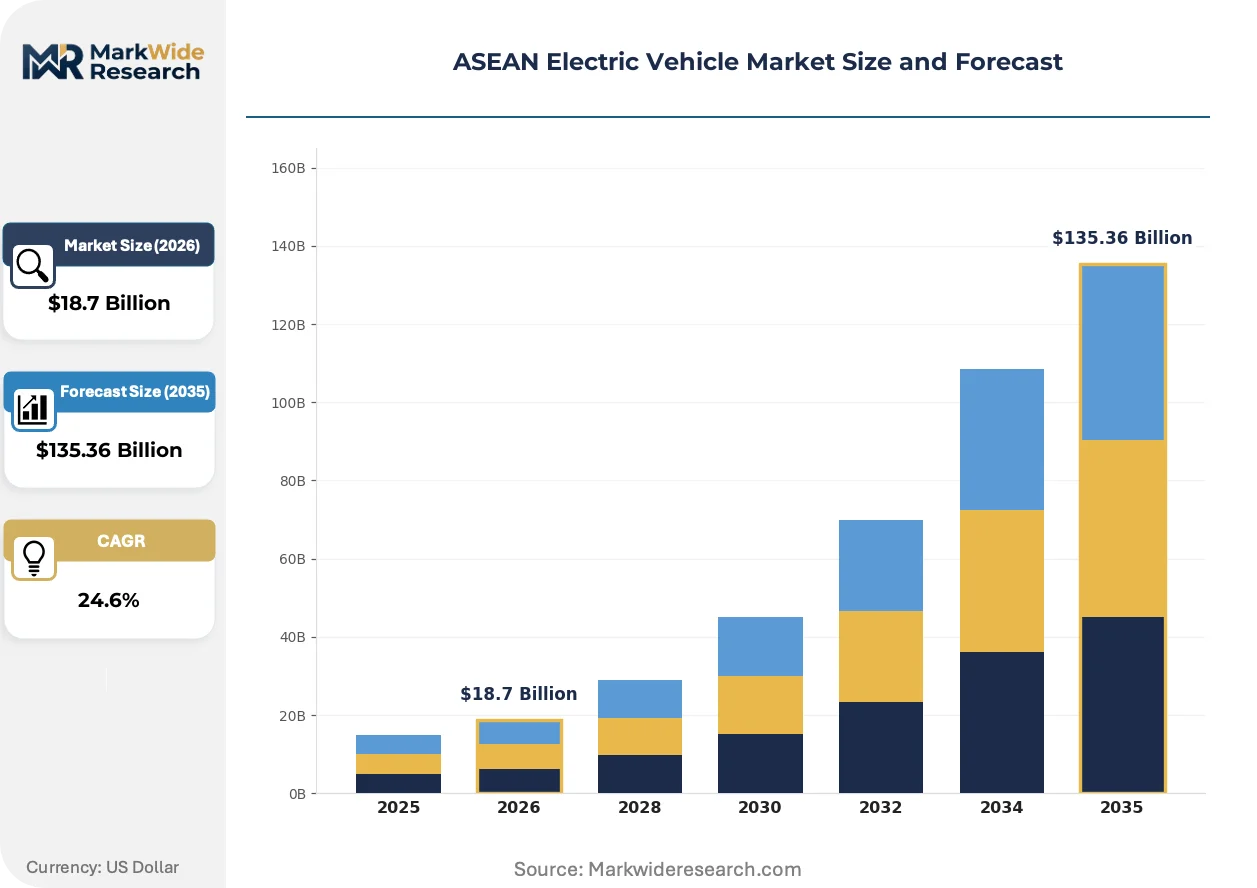
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Trucks, Two-wheelers Power Source: Battery Electric, Plug-in Hybrid, Hydrogen Fuel Cell, Others Charging Infrastructure: Level 1 Charging, Level 2 Charging, DC Fast Charging, Wireless Charging End User: Personal Use, Commercial Fleets, Public Transportation, Shared Mobility |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, BYD Company Limited, Kia Corporation, Honda Motor Co., Ltd., VinFast Auto Ltd., SAIC Motor – MG Motor, Nissan Motor Co., Ltd., Great Wall Motor Co., Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Electric Vehicle Market Emerging Trajectories
Digital integration across vehicle platforms and charging networks is redefining operational efficiency benchmarks for fleet managers and shared mobility operators.
Battery management systems with real-time thermal monitoring are digitizing predictive maintenance workflows for tropical climate operation. Commercial fleet operators in Singapore and Bangkok are deploying these systems to optimize charging schedules and extend cell cycle life. The technology is digitizing how operators balance range anxiety against asset utilization rates in high-temperature environments.
Indonesia's Ministry of Industry domestic content requirements are forcing platform-level engineering changes for market access. Local assembly thresholds for battery packs and electric motors are redirecting supplier qualification efforts toward ASEAN-based component manufacturers. Passenger car and two-wheeler segments face divergent compliance timelines, with motorcycles receiving phased implementation extensions.
Fleet procurement committees now prioritize total cost of ownership models over sticker price in vendor selection. Shared mobility operators in Jakarta and Ho Chi Minh City are unbundling vehicle acquisition from charging infrastructure and maintenance contracts. This pattern is most pronounced among ride-hailing platforms with centralized fleet management capabilities and access to project finance structures.
ASEAN Electric Vehicle Market Segmentation
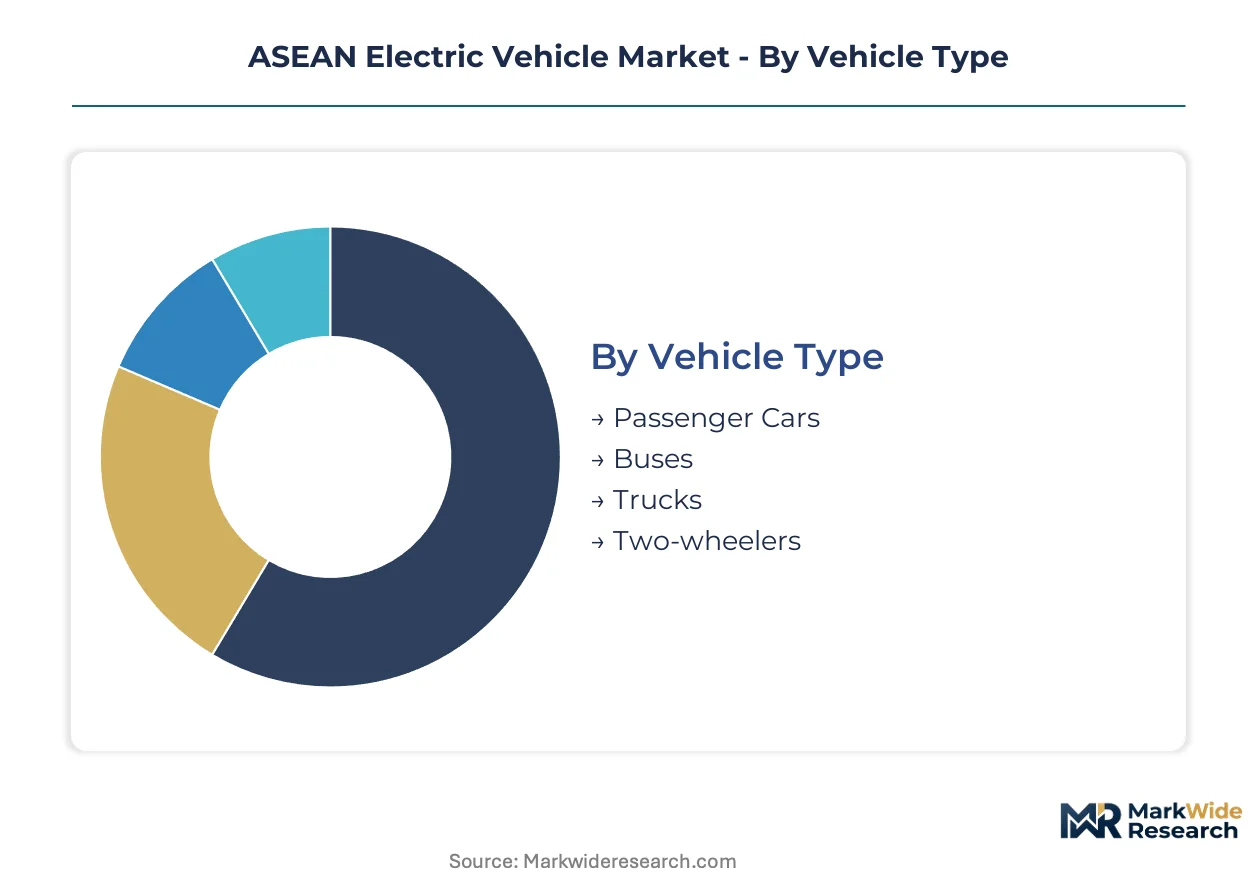
Segmentation in the ASEAN Electric Vehicle Market exposes divergent technology requirements across tropical operating conditions and regulatory incentive structures. Fleet operators and individual buyers prioritize different performance thresholds, charging speeds, and total cost of ownership models. Understanding these splits enables targeted platform engineering and infrastructure investment decisions.
Vehicle Type:
Application context determines battery sizing, thermal management architecture, and regulatory compliance pathways across ASEAN markets.
- Passenger Cars:Four-wheel battery electric configurations with liquid-cooled battery packs exceeding 150 Wh/kg energy density. Demand concentrates in Bangkok and Singapore where ride-hailing fleet mandates and carbon-based vehicle taxation accelerate replacement cycles. Thai Board of Investment incentive packages favor local assembly of battery packs and electric motors for this segment.
- Two-wheelers:Motorcycles and scooters with compact battery packs optimized for stop-start urban traffic patterns. Indonesia's Ministry of Industry domestic content requirements are reshaping supplier qualification toward ASEAN-based component manufacturers in Jakarta and Surabaya corridors where motorcycle dependency shapes electrification pathways.
- Buses:Heavy-duty electric platforms with standardized charging protocols for grid-connected bus rapid transit corridors. Fleet procurement committees in Greater Jakarta prioritize total cost of ownership models over sticker price.
- Trucks:Commercial delivery and logistics vehicles with battery capacities scaled for last-mile distribution routes. Singapore Land Transport Authority regulations on commercial fleet emissions are compressing replacement timelines for urban freight operators.
Passenger Cars commands the established base. The steepest expansion runs through Two-wheelers.
Power Source:
Cost tier positioning and infrastructure availability dictate technology adoption sequencing across price-sensitive ASEAN segments.
- Battery Electric:Zero-tailpipe-emission configurations powered by rechargeable lithium-ion battery packs with energy densities typically exceeding 150 Wh/kg at the cell level. Vietnam and Thailand manufacturing locations are capturing investment from in-house battery cell producers seeking margin protection.
- Plug-in Hybrid:Dual-powertrain systems combining internal combustion engines with electric motors and smaller battery packs. Range anxiety mitigation drives adoption in intercity corridors where DC fast charging networks remain concentrated in capital cities.
- Hydrogen Fuel Cell:Proton exchange membrane systems converting hydrogen to electricity for extended-range commercial applications. Heavy-duty bus operators in Jakarta BRT electrification programs are piloting standardized fueling protocols.
- Others:Emerging powertrain technologies including solid-state battery prototypes and alternative chemistry configurations. Research and development constraints from power electronics talent scarcity in Thailand and Indonesia limit near-term deployment.
Battery Electric captures volume leadership. The fastest technology trajectory climbs through Plug-in Hybrid as infrastructure gaps persist.
Charging Infrastructure:
Customer type and utilization intensity determine charging speed requirements and network deployment economics.
- DC Fast Charging:High-power direct current systems delivering 80% battery capacity in 30-60 minutes. Commercial fleets and shared mobility operators in Bangkok, Singapore, and Jakarta prioritize turnaround time over residential convenience, making this the fastest-expanding network segment.
- Level 2 Charging:Alternating current systems operating at 240V for overnight and workplace charging. Office park installations in Ho Chi Minh City and Metro Manila support employee fleet programs with extended dwell times.
- Level 1 Charging:Standard residential outlet charging at 120V with extended charging durations. Individual owners in underpenetrated Philippine and Indonesian markets rely on this baseline infrastructure.
- Wireless Charging:Inductive power transfer systems eliminating physical connector requirements. Singapore Land Transport Authority pilot programs are testing embedded roadway applications for autonomous shuttle corridors.
Level 2 Charging maintains installed base dominance. The steepest infrastructure buildout runs through DC Fast Charging.
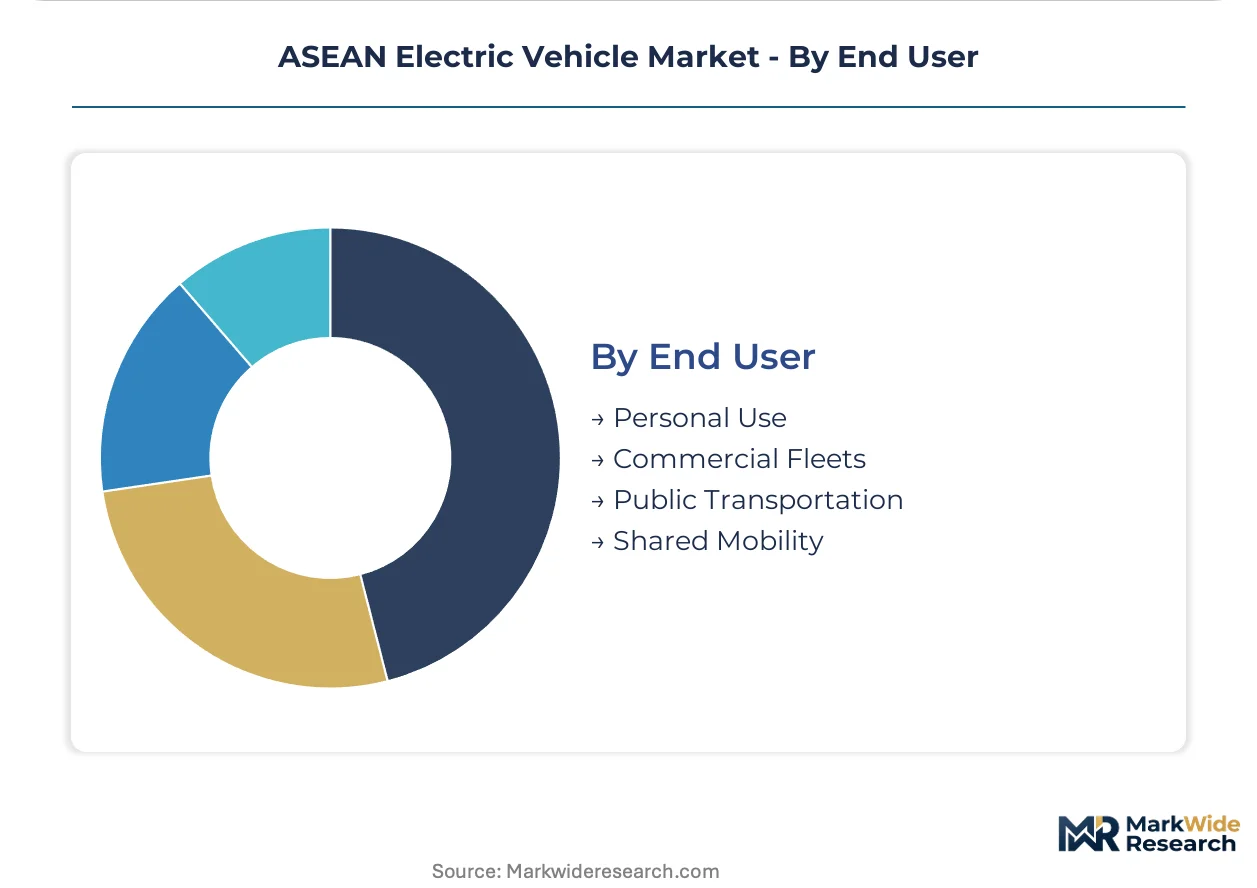
End User:
Volume concentration and procurement sophistication create divergent vendor selection criteria across buyer categories.
- Commercial Fleets:Centralized fleet management operators with access to project finance structures and asset-light ownership models. Ride-hailing platforms in Jakarta and Ho Chi Minh City unbundle vehicle acquisition from charging infrastructure and maintenance contracts.
- Shared Mobility:Car-sharing and subscription services with high asset utilization rates and predictive maintenance workflows. Battery management systems with real-time thermal monitoring digitize operational efficiency benchmarks for these operators.
- Public Transportation:State-owned and municipal bus operators with standardized procurement protocols and domestic content compliance requirements. Indonesia's Ministry of Industry local assembly thresholds redirect supplier qualification efforts.
- Personal Use:Individual consumers with sticker-price sensitivity and range anxiety constraints. Thailand's Board of Investment tax holidays and import duty exemptions are reshaping manufacturing location decisions for this price-sensitive base.
Commercial Fleets anchor current procurement volume. The sharpest demand acceleration gains through Shared Mobility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore commands pricing premiums for premium EV configurations while Indonesia anchors volume absorption at entry-level price points. This asymmetry reflects divergent regulatory frameworks and infrastructure maturity across ASEAN's six major economies. Thailand, Vietnam, and the Philippines occupy intermediate positions with distinct policy-driven acceleration pathways.
Thailand
Ride-hailing fleet mandates and carbon-based vehicle taxation compress replacement cycles in Bangkok and the Eastern Economic Corridor. Thailand's Board of Investment tax holidays and import duty exemptions for battery production facilities attract component manufacturers to Rayong and Chonburi industrial zones. Local assembly thresholds for battery packs and electric motors reshape supplier qualification toward ASEAN-based producers.
Indonesia
Motorcycle dependency in Greater Jakarta and Surabaya corridors shapes electrification pathways for two-wheeler segments. Indonesia's Ministry of Industry domestic content requirements force platform-level engineering changes with phased implementation timelines. Grid-connected bus rapid transit corridors generate concentrated demand for heavy-duty electric buses with standardized charging protocols in Jakarta.
Vietnam
Asset-light fleet ownership structures reduce upfront capital barriers for commercial operators in Ho Chi Minh City and Hanoi. Battery leasing finance models gain traction among shared mobility platforms with centralized fleet management capabilities. VinFast Auto Ltd. controls charging infrastructure deployment alongside vehicle sales, creating integrated ecosystem lock-in.
Singapore
Scheduled carbon price increases from the National Environment Agency accelerate commercial fleet replacement timelines for urban freight operators. Land Transport Authority regulations on commercial fleet emissions compress replacement cycles. Autonomous shuttle corridors pilot embedded wireless charging applications in designated zones.
Philippines
Underpenetrated two-wheeler EV adoption in Metro Manila and Cebu presents first-mover advantages for localized assembly. Level 1 charging reliance dominates individual owner behavior in underpenetrated markets. Battery pack costs approaching price parity enable motorcycle electrification pathways distinct from four-wheeler adoption curves.
ASEAN Electric Vehicle Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with captive supply relationships to assembly operations. The vendor base organizes around three strategic archetypes: in-house battery cell producers leveraging cost curves, dedicated EV platform manufacturers with regional production bases, and vertically integrated challengers controlling charging infrastructure alongside vehicle sales. Capacity expansion in ASEAN-based component manufacturing and strategic partnerships for charging infrastructure deployment represent dominant competitive moves.
Among regional platform manufacturers, Hyundai Motor Company anchors dedicated EV production in Indonesia while BYD Company Limited leverages in-house battery cell production for margin protection across price-sensitive segments. VinFast Auto Ltd. exemplifies vertical integration depth with captive charging infrastructure deployment in Vietnam and export markets.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| BYD Company Limited |
| Kia Corporation |
| Honda Motor Co., Ltd. |
| VinFast Auto Ltd. |
| SAIC Motor – MG Motor |
| Nissan Motor Co., Ltd. |
| Great Wall Motor Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Rayong and Chonburi industrial zones in Thailand's Eastern Economic Corridor concentrate battery pack and electric motor assembly capacity, granting component manufacturers downstream pricing leverage over ASEAN-based vehicle assemblers facing domestic content thresholds. This geographic concentration tightens margins for price-sensitive passenger car segments while enabling premium capture for localized two-wheeler platforms in Vietnam and Indonesia.
Pricing Analysis
Commercial fleet operators anchor pricing stratification across premium, standard, and economy tiers in the ASEAN Electric Vehicle Market. Price differentiation hinges on battery energy density certification above 150 Wh/kg and after-sales service bundling for tropical climate thermal management. Cost compression in entry-level two-wheeler segments is intensifying because lithium-ion cell cost curves enable price parity with internal combustion alternatives. Individual personal-use buyers in the Philippines and Indonesia exhibit highest price sensitivity, while Singapore-based shared mobility platforms with project finance access show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from Thailand's Board of Investment incentive recipients are reshaping supplier cash flow dynamics across the ASEAN Electric Vehicle Market supply base. Manufacturing capacity concentrates in Thailand, Indonesia, and Vietnam with component sourcing anchored in China, South Korea, and Japan for battery cells and power electronics. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare earth permanent magnets for motor assemblies. Single-source vulnerability from concentrated cathode active material processing creates structural exposure. Distribution runs through OEM-direct fleet procurement committees and regional charging infrastructure partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN Electric Vehicle Market represents high-growth disruption as ride-hailing fleet electrification mandates compress replacement cycles and battery leasing finance models displace traditional ownership structures.
For Market Incumbents: Entrench defensive positioning through captive battery cell production and dedicated EV platform manufacturing in Indonesia. BYD's in-house cell production and Hyundai's Indonesian manufacturing base demonstrate margin protection against emerging vertical integrators. Incumbents must secure charging infrastructure partnerships before shared mobility operators consolidate network access.
For New Entrants and Emerging Players: Pursue underpenetrated two-wheeler electrification in Metro Manila and Cebu where localized assembly incentives remain unclaimed. The Philippines motorcycle market offers the most penetrable entry point given minimal incumbent charging infrastructure deployment. A battery-leasing-first go-to-market angle reduces upfront capital barriers for commercial operators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated challengers controlling charging infrastructure alongside vehicle sales. Long-term viability across the projection horizon rests on ecosystem lock-in capabilities rather than standalone vehicle manufacturing. Acquisition targets should demonstrate integrated charging network deployment in Vietnam or Indonesia. The signal to watch is domestic content requirement tightening from Indonesia's Ministry of Industry and Thailand's Board of Investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell access from Korean and Chinese producers for ASEAN assembly operations. |
| Charging Infrastructure Partnership | DC fast charging network deployment in Jakarta and Bangkok locks in fleet operator loyalty. |
| Geographic Manufacturing Footprint | Indonesian production base satisfies Ministry of Industry domestic content thresholds for market access. |
| Platform Standardization | Common battery pack architecture reduces compliance costs across Thailand TISI and Indonesia SNI certification. |
| Software-Defined Vehicle Investment | Battery management systems with real-time thermal monitoring optimize tropical climate range retention. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, charging infrastructure developers, and fleet operations managers at ride-hailing platforms and refined through secondary validation. Primary fieldwork combined structured interviews with commercial fleet procurement committees in Jakarta, Bangkok, and Ho Chi Minh City with technical discussions at battery pack assembly facilities in Rayong and Bekasi. Secondary sources included vehicle production databases, IHS Markit registration data, Thailand Board of Investment incentive disclosures, Indonesia Ministry of Industry regulatory filings, and ASEAN customs trade records. Bottom-up unit economics modeling triangulated against top-down market sizing from national transport authority fleet electrification targets.
Demand-supply balance modeling across the projection horizon segmented volume by vehicle class, propulsion architecture, charging infrastructure type, and end-user category. The analytical framework incorporated battery cost curve trajectories, domestic content compliance timelines, and grid capacity constraints from state electricity providers. CAGRs were derived from installed base replacement cycles, fleet electrification mandate schedules, and infrastructure deployment pipelines. Industry-specific forecast inputs included lithium-ion cell price elasticity and thermal management efficiency degradation curves for tropical climates.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, electricity tariff structures, or carbon taxation escalation would shift the trajectory. Forecasts reflect documented assumptions on incentive continuity, certification harmonization progress, and battery recycling mandate implementation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market