
 Latin America Electric Bus Market | 2026-2036
Latin America Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Electric Bus Market Foresight
Municipal transit agencies is bifurcating from private operators as the dominant procurement archetype across Latin America. BYD Auto Co., Ltd leverages its integrated battery supply chain to dominate Santiago's Transantiago fleet renewals. Eletra anchors Brazilian production with localized assembly in São Bernardo do Campo, competing on domestic content requirements. Marcopolo specializes in body-on-chassis partnerships, extending its coachbuilding expertise into electric platforms for regional operators.
An electric bus is a battery-powered heavy-duty vehicle designed for mass transit, typically employing lithium-ion packs with 200-400 kWh capacity and regenerative braking systems to recover kinetic energy during deceleration. The vehicle serves urban and intercity routes where zero-tailpipe operation reduces particulate emissions in dense population centers. Battery technology segments reveal lithium-ion chemistry occupying the installed base while solid-state prototypes attract R&D investment for extended range in mountainous Andean corridors. Bus type segmentation shows articulated configurations leading in BRT system deployments across Bogotá and Curitiba, with minibus variants gaining traction in last-mile feeder services. Charging infrastructure segments position depot charging as the operational default, though pantograph systems are emerging for opportunity charging on high-frequency trunk routes.
Chile's Ministry of Energy electromobility strategy and Brazil's Proconve P8 standards under its national environmental council shape product homologation and fleet procurement timelines across the region. ANVISA in Brazil and the national transport secretariats in Colombia enforce safety and operational compliance for electric public transport vehicles. Stakeholders must monitor how local content rules and cross-border battery supply agreements interact with evolving subsidy frameworks in each jurisdiction.
Market Dynamics
Proconve P8 emission standards in Brazil and Chile's electromobility strategy are compressing diesel fleet replacement timelines, forcing municipal transit agencies to accelerate electrification procurement across corridor networks with existing BRT infrastructure.
Growth Catalysts
- Proconve P8 Standards:Brazil's national environmental council mandates progressive emission reductions that eliminate diesel bus eligibility for new municipal fleet contracts.
- Depot Infrastructure Pre-Positioning:Santiago, São Paulo, and Bogotá corridors possess dedicated bus lanes and charging-ready depots that reduce electric bus deployment friction.
- Lithium-Ion Cost Curves:Battery pack economics improve procurement viability for articulated BRT configurations serving high-frequency trunk routes.
Market Restraints
- Import Dependency Concentration:Battery cell supply concentrates in Asian manufacturing clusters, exposing Latin American operators to currency volatility and shipping bottlenecks.
- Local Content Thresholds:Brazilian domestic assembly requirements under ANVISA homologation rules extend procurement lead times for foreign chassis suppliers.
- Andean Altitude Derating:Lithium-ion thermal management loses efficiency above 2,500 meters, constraining range performance in mountainous Colombian and Chilean corridors.
Strategic Opportunities
- Minibus Electrification:Feeder service operators in Medellín and Curitiba represent underpenetrated demand for sub-12-meter configurations serving last-mile connectivity.
- Pantograph Opportunity Charging:High-frequency trunk routes in Santiago's Transantiago network enable route extension without depot battery scaling.
- Cross-Border Battery Agreements:Chile-Argentina lithium carbonate supply corridors create upstream integration potential for regional pack assembly.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance departments lack certified personnel for 400V+ battery system diagnostics and thermal runaway containment protocols.
- Depot Electrification Capex:Grid connection upgrades and transformer installations absorb 15-20% of total project budgets before vehicle procurement begins.
- Homologation Timeline Variability:Divergent safety testing requirements across ANVISA, Chile's Ministry of Transport, and Colombia's national secretariats create multi-jurisdiction certification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Electric Bus Market |
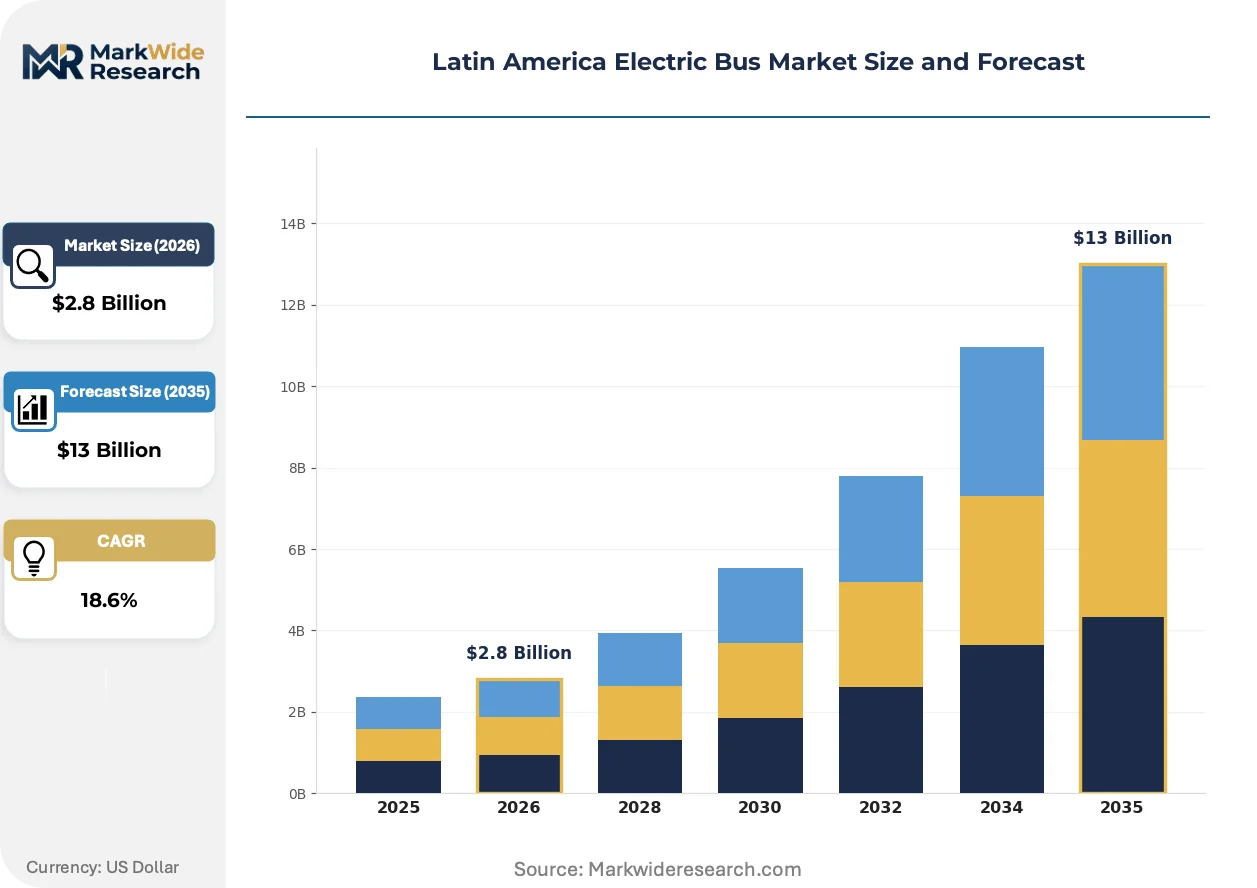
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Standard, Double-Decker, Articulated, Minibus Battery Technology: Lithium-Ion, Solid-State, Nickel-Manganese-Cobalt, Others End User: Public Transportation, Private Operators, Corporations, Educational Institutions Charging Infrastructure: Fast Chargers, Depot Charging, Pantograph, Wireless Charging |
| Companies Covered | Eletra, Zhongtong Bus Holding Co., Ltd, BYD Auto Co., Ltd, DINA, Marcopolo, Foton, King Long United Automotive Industry Co., Ltd, Volkswagen Truck & Bus, Zhengzhou Yutong Bus Co., Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Electric Bus Market Shifts & Advancements
Technology roadmaps and procurement methodologies across Latin America are diverging from established diesel-era patterns as operators confront zero-emission transition imperatives.
Battery chemistry selection is bifurcating between lithium-iron-phosphate for tropical lowland operations and nickel-manganese-cobalt variants for temperate high-altitude corridors. Municipal agencies in São Paulo and Rio de Janeiro prioritize thermal stability over energy density given ambient temperature extremes. This chemistry split is compressing supplier standardization efforts and forcing manufacturers to maintain dual certification pathways for regional tenders.
Chile's Ministry of Energy electromobility strategy mandates 100% electric public transport procurement in Santiago by 2040, with intermediate targets binding Transantiago contract renewals. The policy framework creates compliance-driven demand concentration that outpaces organic fleet turnover economics. Brazilian operators respond through accelerated Proconve P7-to-P8 transition planning, while Colombian agencies await national subsidy mechanism finalization.
Leasing structures displace direct capital purchase for municipal fleet renewals in Bogotá and São Paulo corridors. Battery-as-a-service contracts separate asset ownership from operational responsibility, transferring degradation risk to financiers. This model concentrates most visibly among articulated BRT operators facing 12-year concession obligations with performance-based availability clauses.
Latin America Electric Bus Market Segmentation
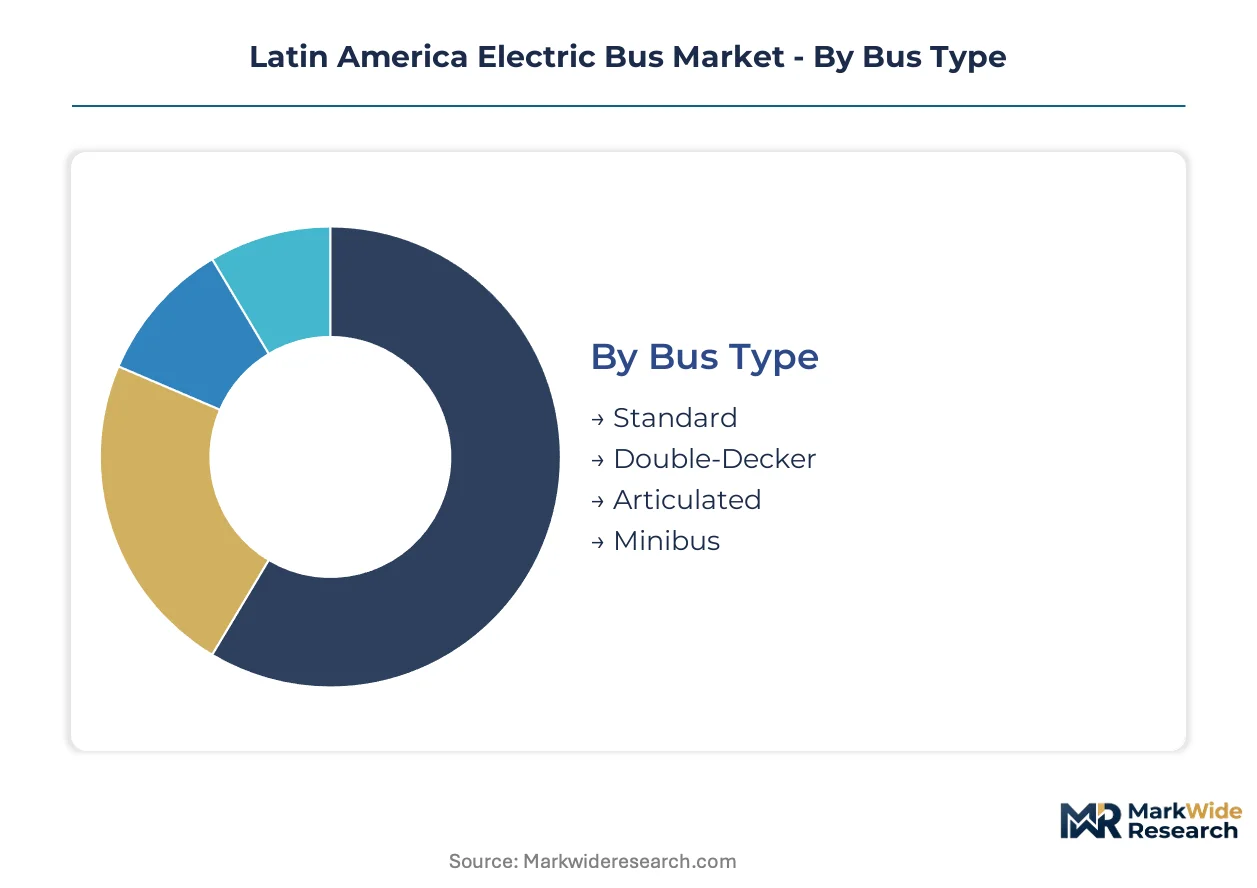
Segmentation reveals how electrification pathways diverge across Latin America's heterogeneous operating environments. Each dimension exposes distinct procurement logics, from BRT corridor scaling to last-mile feeder deployment, with regulatory pressures and infrastructure readiness filtering viable configurations.
Bus Type:
Domestic assembly in Brazil and Chile favors heavier configurations, while minibus demand concentrates in Colombian and Peruvian import markets lacking local chassis production.
- Articulated:18-meter configurations dominate Bogotá's TransMilenio and Santiago's Transantiago trunk corridors, where dedicated lanes justify the 350-450 kWh battery packs required for high-frequency service. São Paulo's Corredor Norte-Sul procurement locks in this segment as Brazil's Proconve P8 timeline accelerates.
- Minibus:7-9 meter configurations serve Medellín's Complementaria network and Curitiba's feeder lines, penetrating where depot infrastructure cannot scale for full-size fleets. Operators in secondary Colombian cities favor this segment for route flexibility and lower grid connection burdens.
- Standard:12-meter single-deck units form the replacement baseline for municipal fleets across Montevideo and Quito corridors with moderate ridership density.
- Double-Decker:Limited deployment in Santiago's high-volume corridors maximizes passenger capacity without extending bus length beyond existing platform constraints.
Articulated configurations hold the largest share; momentum sits with minibus variants as feeder electrification accelerates.
Battery Technology:
Cost tier differentiation separates premium chemistry for extreme climates from commodity options for temperate lowland operations.
- Lithium-Ion:Lithium-iron-phosphate cells dominate São Paulo and Rio de Janeiro procurements, where thermal stability above 35°C ambient temperatures outweighs energy density considerations. BYD's vertically integrated supply chain anchors this chemistry's cost position across Brazilian municipal tenders.
- Nickel-Manganese-Cobalt:NMC variants concentrate in Santiago and Bogotá high-altitude deployments, where energy density per kilogram offsets thermal derating effects above 2,500 meters. Chile's lithium carbonate proximity supports regional pack assembly cost structures.
- Solid-State:Prototype testing in Andean corridors targets extended range for mountainous routes where current lithium-ion configurations require mid-route charging infrastructure.
- Others:Sodium-ion and lithium-titanate alternatives attract pilot interest for tropical operations with extreme humidity exposure.
Lithium-ion chemistry commands installed base dominance; nickel-manganese-cobalt is climbing the fastest as altitude-specific demand intensifies.
End User:
Customer type determines financing structure, with municipal agencies accessing green bond markets unavailable to private fleet operators.
- Public Transportation:Municipal transit agencies in Santiago, São Paulo, and Bogotá drive procurement volume through BRT concession renewals with electrification mandates. Chile's Ministry of Energy binding targets and Brazil's Proconve P8 standards compress replacement timelines for this segment.
- Private Operators:Intercity carriers along Brazil's São Paulo-Rio corridor and Chile's Santiago-Valparaíso axis pilot electric coaches where toll concessions subsidize charging infrastructure.
- Corporations:Mining sector demand in Chile's Antofagasta region and Peru's Cerro de Pasco corridor targets employee shuttle electrification under Scope 3 emissions accounting pressure.
- Educational Institutions:University campuses in Mexico City and São Paulo deploy closed-loop electric shuttles with solar canopy charging, though scale remains limited.
Public transportation holds the largest share; corporate shuttle electrification is gaining share fastest as ESG reporting requirements harden.
Charging Infrastructure:
Supply concentration in Chinese and European equipment vendors shapes procurement patterns across the region's grid-constrained depot environments.
- Depot Charging:Overnight plug-in systems remain the operational default for São Paulo and Bogotá fleets, where 150-350 kW AC/DC installations absorb 15-20% of total project capital before vehicle procurement. ANVISA homologation requirements extend lead times for imported charging hardware.
- Pantograph:Overhead opportunity charging systems deploy on Santiago's Transantiago high-frequency trunk routes, enabling route extension without battery capacity scaling. ABB and Siemens infrastructure dominates this segment's vendor base.
- Fast Chargers:450 kW+ DC installations serve intercity corridor pilots where dwell time minimization outweighs equipment cost premiums.
- Wireless Charging:Inductive pilot projects in Curitiba's dedicated bus lanes test dynamic charging for continuous service operation.
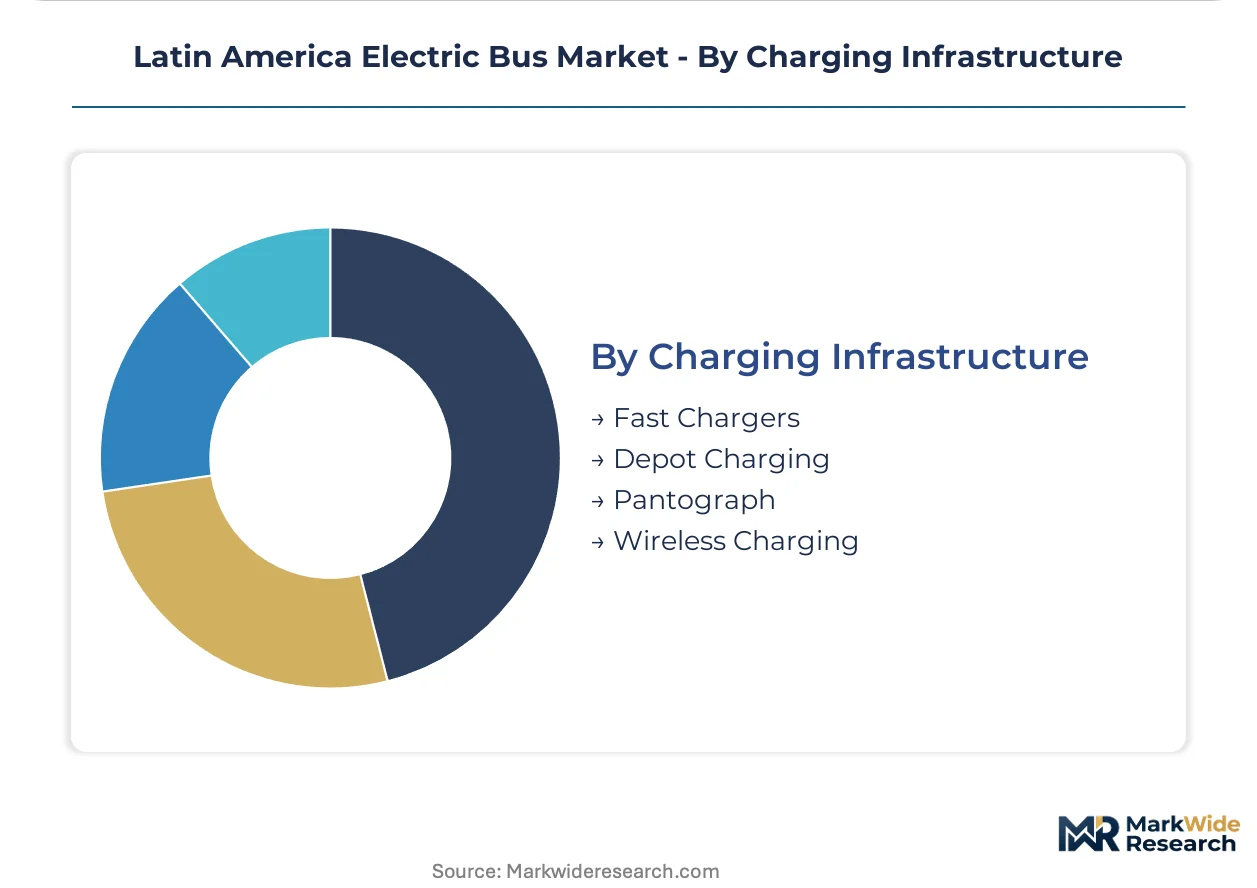
Depot charging holds the largest share; pantograph systems show steepest expansion trajectory as opportunity charging economics improve for high-frequency routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Transantiago BRT corridor anchors Chile's electrification trajectory, while Brazil's São Paulo-Rio grid interconnection underwrites depot charging scale-up across South America's two dominant markets.
Brazil
São Paulo's Corredor Norte-Sul and Rio de Janeiro's TransOeste drive articulated bus procurement volumes. ANVISA homologation rules under Brazil's national health surveillance agency enforce domestic assembly thresholds that extend lead times for foreign chassis. Eletra's São Bernardo do Campo facility concentrates production for municipal tenders under Proconve P8 compliance timelines.
Chile
Santiago's Transantiago network replacement cycles and Antofagasta mining corridor shuttle demand pull battery-electric configurations. The Ministry of Energy's electromobility strategy mandates 100% electric public transport procurement by 2040 with binding intermediate targets. BYD Auto Co., Ltd anchors fleet renewals through vertically integrated lithium-iron-phosphate supply chains serving the capital's high-frequency trunk routes.
Colombia
Bogotá's TransMilenio BRT system and Medellín's Metroplus feeder networks concentrate demand for both articulated and minibus variants. The national transport secretariat's subsidy mechanism finalization awaits presidential decree, compressing procurement timelines for municipal agencies. Curitiba's dedicated bus lanes in the Brazilian border region influence cross-border operator specifications for Andean corridor deployments.
Mexico
Mexico City's Metrobús expansion and Monterrey's Ecovía corridor pilot electric configurations where grid stability supports overnight depot charging. The Secretariat of Environment and Natural Resources' emissions standards for metropolitan zones shape fleet replacement schedules. Foton and Zhengzhou Yutong Bus Co., Ltd. position for tenders through established commercial vehicle distribution networks in the Valley of Mexico.
Argentina
Buenos Aires' Metrobus corridor and Córdoba's urban renewal programs generate procurement interest constrained by currency volatility and import financing limitations. The Secretariat of Energy's electromobility roadmap lacks binding procurement mandates, leaving fleet transitions to municipal initiative. Mendoza's wine tourism shuttle operators pilot electric minibuses for closed-loop vineyard circuits under provincial environmental incentive programs.
Latin America Electric Bus Market Competitive Landscape
Listed leaders compete with private specialists across battery chemistry integration and local content compliance. Market structure concentrates around three tiers: multinational OEMs with captive battery supply, regional assemblers meeting domestic content rules, and Chinese exporters competing on delivered cost. Strategic moves center on backward integration into lithium carbonate sourcing and partnership structures with municipal leasing platforms.
Within the regional assembler tier, Eletra and Marcopolo exemplify Brazil's domestic content compliance model, while BYD Auto Co., Ltd occupies a position as the integrated battery supplier anchoring Chilean fleet renewals. These three companies represent distinct competitive archetypes: the local assembly specialist, the body-on-chassis partnership fabricator, and the vertically integrated battery OEM.
| Leading Market Players |
|---|
| Eletra |
| Zhongtong Bus Holding Co., Ltd |
| BYD Auto Co., Ltd |
| DINA |
| Marcopolo |
| Foton |
| King Long United Automotive Industry Co., Ltd |
| Volkswagen Truck & Bus |
| Zhengzhou Yutong Bus Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term battery-as-a-service contracts lock in lithium-iron-phosphate cell access for São Paulo municipal fleets while capping per-kilometer operational costs against diesel volatility. This structure transfers degradation risk to financiers and compresses upfront capital requirements for transit agencies navigating Proconve P8 compliance timelines.
Pricing Analysis
Volume-discount tiering separates articulated BRT procurements above 100-unit thresholds from minibus feeder orders below 20 units, with the former commanding 12-15% price advantages on pack economics. Certification grade under ANVISA homologation rules adds a second differentiation layer, as domestic assembly compliance extends lead times and absorbs margin for foreign chassis suppliers. Cost compression in the minibus segment is intensifying because Colombian import markets lack local production scale, forcing operators toward Chinese exporters competing on delivered cost. Municipal transit agencies exhibit highest price sensitivity due to green bond financing constraints, while mining sector corporate shuttles prioritize availability clauses over unit economics.
Supply Chain Analysis
Port congestion at Santos and Valparaíso extends inbound logistics cycles for battery pack assemblies originating from Chinese and South Korean manufacturing clusters. Cell production concentrates in China, South Korea, and Japan, with Chilean lithium carbonate feedstock anchoring regional pack assembly cost structures. The supply chain draws from cathode active materials, electrolyte solvents, and thermal management components where single-source vulnerability persists for ceramic separator membranes. Distribution runs through municipal leasing platforms and BRT concession operators rather than direct OEM sales, concentrating procurement influence among Santiago, São Paulo, and Bogotá transit agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as charging infrastructure interoperability and battery-swapping standardization reshape vendor lock-in dynamics across Latin American corridor networks.
For Market Incumbents: Secure captive lithium carbonate offtake from Chile-Argentina salar brine operations to insulate pack cost structures against Asian cell supplier pricing power. Deepen backward integration into thermal management system production to defend margin position as depot electrification capex absorbs larger project budget shares. Reinforce ANVISA homologation expertise as a compliance barrier against emerging Chinese exporters lacking Brazilian domestic assembly pathways. For New Entrants and Emerging Players: Anchor in Medellín's Complementaria feeder network and Curitiba's last-mile corridors where minibus electrification penetration remains below articulated BRT saturation levels. Target Colombian municipal agencies awaiting national subsidy mechanism finalization, where procurement timeline compression will favor agile suppliers with shorter homologation lead times. Pursue battery-as-a-service financing partnerships to bypass capital-constrained direct purchase barriers among secondary city operators. For Investors and Strategic Acquirers: Regional pack assemblers with Chilean lithium supply integration and Brazilian ANVISA certification pathways offer the strongest acquisition target archetype for long-term viability across the 5-10 year electrification window. Monitor binding intermediate targets in Chile's Ministry of Energy electromobility strategy as the critical inflection signal for procurement volume acceleration beyond organic fleet turnover rates.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-iron-phosphate cell access for São Paulo Proconve P8 compliance timelines. |
| Domestic Assembly Expansion | Satisfies ANVISA homologation thresholds that filter foreign chassis from Brazilian municipal tenders. |
| Charging Infrastructure Partnership | Deploys pantograph opportunity charging on Santiago Transantiago high-frequency trunk routes. |
| Platform Standardization | Enables interoperability between BYD, Eletra, and Marcopolo configurations across corridor networks. |
| Backward Integration into Lithium | Captures Chilean lithium carbonate supply chain value for regional pack assembly cost advantage. |
Research Methodology
Desk research of customs trade data, national electromobility strategy filings, and ANVISA homologation records preceded structured interviews with BRT procurement directors, fleet maintenance chiefs, and battery system engineers. Primary fieldwork with Santiago Transantiago operators and São Paulo municipal transit agencies combined with secondary validation against Chile Ministry of Energy policy documents and Brazil national environmental council regulatory releases. Bottom-up unit deployment tracking across corridor networks triangulated with top-down market sizing from vehicle registration databases.
Variance-decomposition framing isolates volume, mix, and price effects across bus type, battery chemistry, and charging infrastructure segments throughout the forecast period. The analytical framework models articulated versus minibus configuration splits, lithium-iron-phosphate versus nickel-manganese-cobalt chemistry adoption curves, and depot versus pantograph charging penetration patterns. CAGRs derive from logistic diffusion curves fitted to replacement cycle data and regulatory mandate compliance schedules, with lithium-ion cost curve trajectories and grid interconnection capex ratios as key forecast inputs.
Material uncertainties — currency volatility affecting Asian cell import costs, presidential decree timing for Colombian subsidy mechanisms, and Andean altitude thermal derating effects — sit outside the modeled envelope. Forecasts reflect documented assumptions about Proconve P8 enforcement consistency and Chilean binding target adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Condenser Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market