
 Global Electric Scooters Market | 2026-2036
Global Electric Scooters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Scooters Market Analysis
The electric scooter category is decoupling into premium connected vehicles and commodity commuter models. Yadea Technology Group Co., Ltd. anchors the high-volume Chinese domestic market through manufacturing scale and in-house battery production. Gogoro Inc. differentiates via its proprietary battery-swapping network across Taipei and expanding European cities. NIU International competes on software-integrated design, commanding pricing power in European urban centers.
Electric scooters are two-wheeled personal mobility devices powered by rechargeable battery packs, typically delivering 250W to 5,000W motor output for speeds ranging from 25 km/h to over 100 km/h depending on classification. Their primary commercial purpose is replacing short-distance internal combustion trips in dense urban environments. The rental services segment dominates unit deployment volumes through city-licensed shared fleets, while the solid-state battery sub-category represents the fastest-growing technical tier due to energy density and thermal safety advantages. Foldable scooters occupy the premium personal-use margin pool where portability commands price premiums over fixed-frame alternatives.
The EU Green Deal and F-Gas Regulation are accelerating zero-emission vehicle mandates across German, French, and Dutch municipal jurisdictions. The US NHTSA and EPA coordinate on import safety standards and domestic manufacturing incentives that shape product compliance costs. India's PLI scheme and BIS certification requirements are localizing supply chains for battery and motor components. Stakeholders must monitor how subsidy phase-out timelines in European markets and battery passport traceability rules alter procurement strategies and supplier qualification criteria.
Market Dynamics
Battery-swapping infrastructure is reconfiguring how urban fleets manage energy logistics, compressing vehicle downtime from hours to minutes and shifting capital allocation from battery ownership toward network access subscriptions.
Growth Catalysts
- EU Green Deal vehicle mandates:German, French, and Dutch municipal jurisdictions are phasing out combustion-engine access in city centers, forcing commercial fleets toward zero-emission alternatives.
- Last-mile delivery electrification:Urban logistics operators are replacing van-based short-haul routes with two-wheeled electric fleets to reduce congestion charges and parking constraints.
- Lithium-ion energy density gains:Improved cathode chemistries are extending per-charge range without increasing pack weight, enabling heavier payload configurations for commercial applications.
Market Restraints
- Raw material concentration:Cobalt and lithium refining capacity concentrates in China and the Democratic Republic of Congo, exposing battery supply chains to geopolitical friction and export restriction risk.
- Charging infrastructure asymmetry:Dense Asian and Northern European cities offer outlet penetration rates that Southern European and North American suburbs cannot replicate, capping addressable market expansion.
- Fire safety certification complexity:UN 38.3 lithium battery transport regulations and evolving UL 2272 electrical system standards create multi-jurisdiction compliance costs that commodity manufacturers struggle to absorb.
Strategic Opportunities
- India PLI scheme localization:Battery and motor component production incentives are creating captive supply ecosystems for domestic brands serving price-sensitive tier-two and tier-three cities.
- Intermodal transit integration:Foldable personal scooters are penetrating park-and-ride commuter corridors in German and Swiss rail hubs where first-mile/last-mile connectivity gaps persist.
- Solid-state battery convergence:Emerging ceramic electrolyte architectures promise thermal runaway elimination and faster charging protocols, opening premium fleet segments currently blocked by safety liability concerns.
Industry Challenges
- Battery passport traceability:EU Battery Regulation due diligence requirements are forcing supply chain documentation investments that small assemblers lack capital to implement.
- Software-hardware integration talent:Connected vehicle platforms require embedded systems engineers and cloud infrastructure specialists that traditional two-wheeler manufacturers rarely employ.
- Subsidized import competition:State-backed Chinese manufacturers are dumping inventory into European markets ahead of anticipated anti-dumping tariff adjustments, compressing margin recovery timelines for local assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Scooters Market |
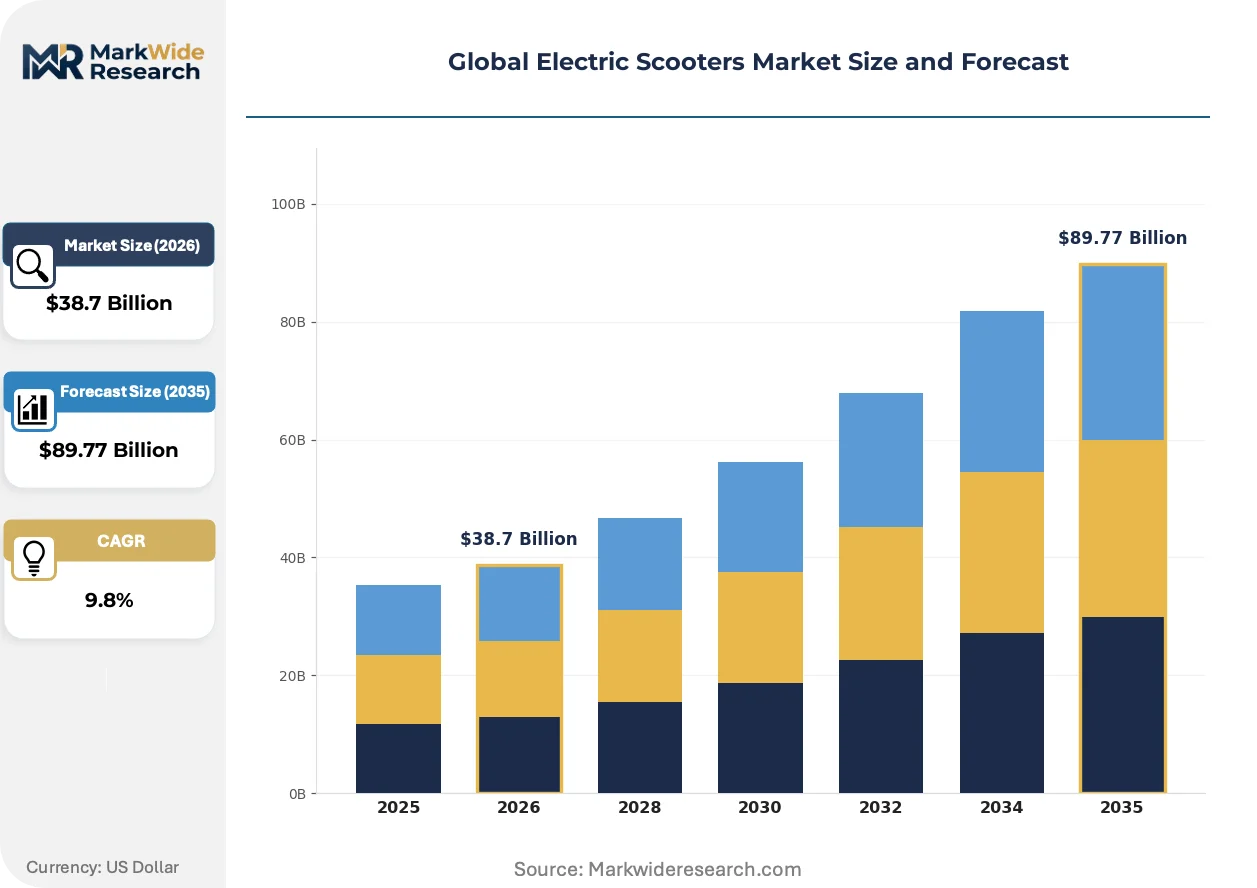
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $89.77 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kick Scooters, Self-Balancing Scooters, Foldable Scooters, Touring Scooters Battery Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Solid-State Weight Capacity: Standard, Heavy-Duty, Lightweight, Ultra-Light End User: Personal Use, Rental Services, Delivery Providers, Corporate Fleets |
| Companies Covered | Yadea Technology Group Co., Ltd., Gogoro Inc., NIU International, Ola Electric, Ather Energy, Bajaj Auto Ltd., TVS Motor Company, Honda Motor Co. Ltd., Segway-Ninebot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Scooters Market Emerging Trajectories
Intelligence layers are migrating from smartphones into vehicle firmware, enabling predictive maintenance and usage-based insurance pricing that reshape how operators monetize fleet assets.
Solid-state battery cells with ceramic electrolyte separators are electrifying thermal management architectures in premium scooter segments. Fleet operators in Taipei and Amsterdam are piloting these packs for 15-minute fast-charge cycles. The technology is electrifying competitive positioning by decoupling energy density from fire risk, allowing denser pack configurations previously blocked by liability underwriting.
REACH chemical substance restrictions and F-Gas Regulation phase-down schedules are forcing refrigerant and coolant redesigns in thermal management systems. Manufacturers are reformulating battery cooling loops to eliminate perfluorinated compounds. The regulations are compressing product development timelines most severely for mid-tier European assemblers lacking in-house chemistry capabilities.
Subscription-based battery-as-a-service models are displacing upfront pack purchases in shared mobility deployments. Operators in Singapore and Barcelona are unbundling vehicle hardware from energy access, converting capex to opex. The shift is concentrating purchasing power among network infrastructure providers and fragmenting vehicle OEM bargaining position in fleet negotiations.
Global Electric Scooters Market Segmentation
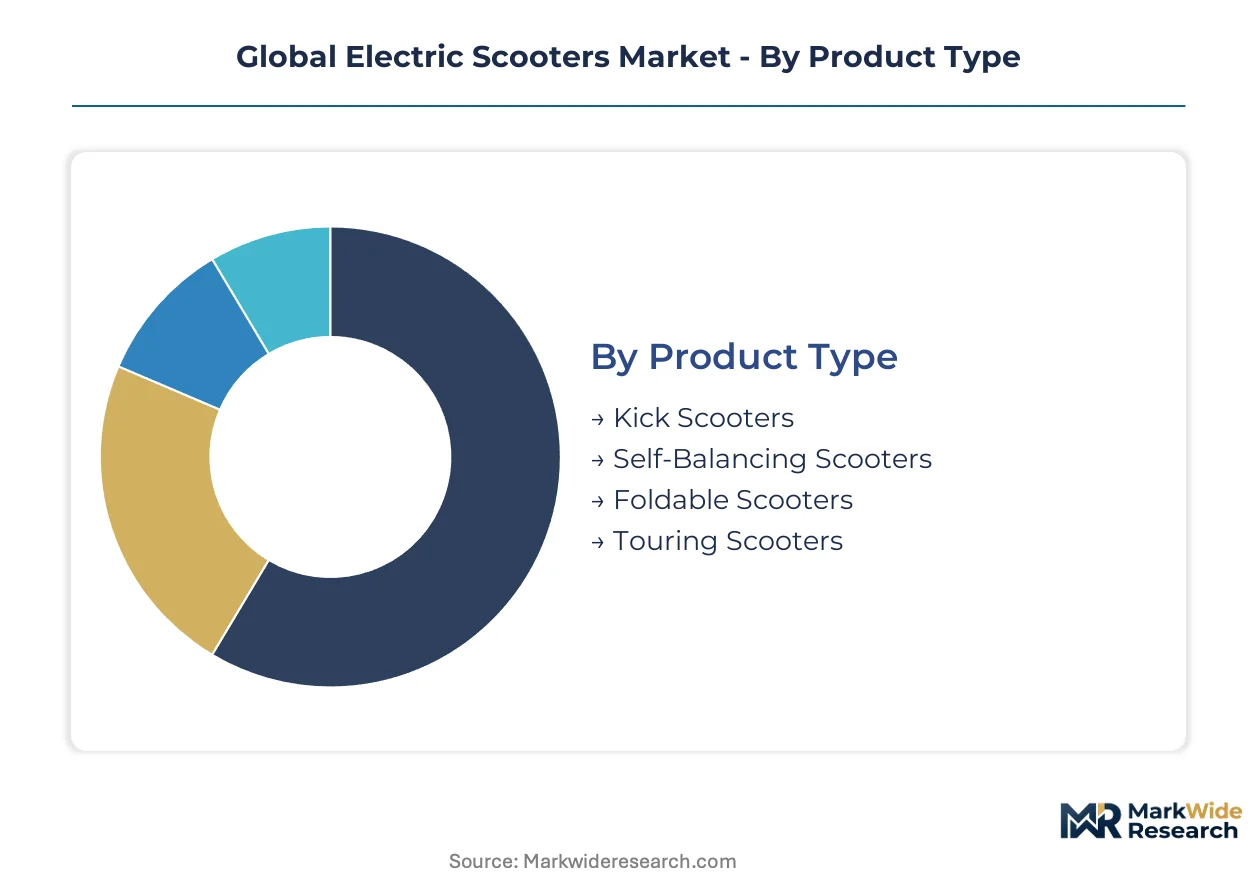
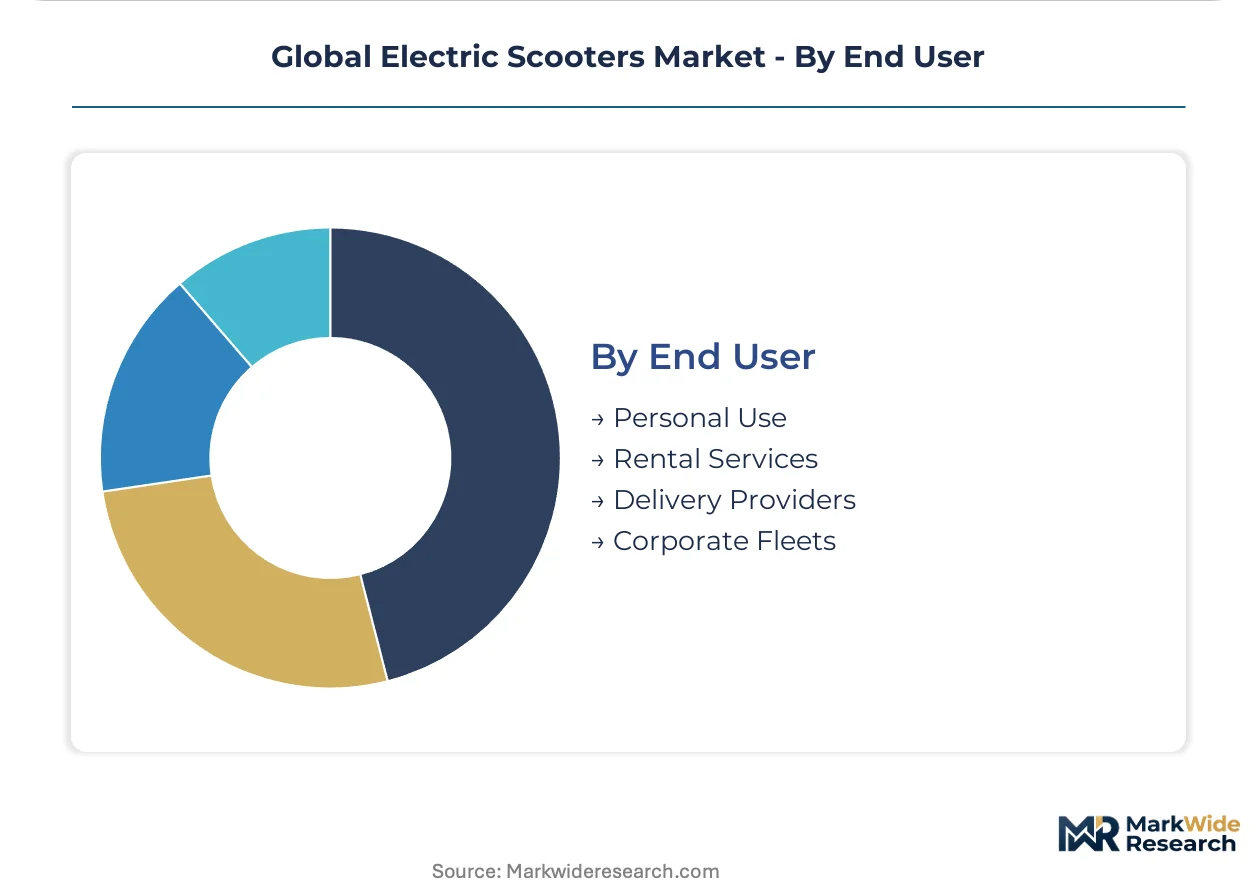
Electric scooter segmentation reveals divergent margin structures across hardware tiers and energy architectures. Fleet operators prioritize total cost of ownership metrics while personal buyers respond to portability and connectivity premiums.
Product Type:
Volume concentrates in entry-level commuter formats while premium positioning shifts toward specialized mobility solutions.
- Kick Scooters:Manual-push electric assist models dominate shared fleet deployments through mechanical simplicity and vandal resistance. Municipal licensing in Paris, Berlin, and Singapore favors these units for sidewalk compatibility regulations.
- Foldable Scooters:Collapsible frame designs command price premiums in intermodal commuter corridors. German and Swiss rail integration programs drive demand where first-mile/last-mile connectivity gaps persist.
- Self-Balancing Scooters:Two-wheeled gyroscopic platforms serve niche recreational and security patrol applications.
- Touring Scooters:Extended-range fixed-frame vehicles target suburban-to-urban distance commuters.
Today's leader: Kick Scooters. Tomorrow's challenger: Foldable Scooters.
Battery Type:
Energy chemistry stratification separates commodity replacement cycles from next-generation thermal safety investments.
- Lithium-Ion:NMC and LFP cathode architectures power 90% of current fleet volumes. Chinese cylindrical cell production from CATL and BYD supplies cost-competitive packs for mass-market assembly.
- Solid-State:Ceramic electrolyte separators eliminate thermal runaway risks while enabling 15-minute fast-charge protocols. Pilot deployments in Taipei and Amsterdam are validating fleet uptime improvements.
- Lead-Acid:Legacy flooded and AGM formats persist in price-sensitive Indian tier-three city markets.
- Nickel-Cadmium:Obsolete chemistry retained only in specialized cold-climate industrial applications.
Current procurement centers on Lithium-Ion. Solid-State chemistry climbs the fastest as liability underwriting relaxes for dense pack configurations.
Weight Capacity:
Payload specification directly determines motor sizing, frame reinforcement, and battery thermal management requirements.
- Standard:100-120 kg rated frames serve typical adult commuters across European and North American urban markets.
- Heavy-Duty:150+ kg reinforced chassis capture commercial delivery fleet specifications where cargo loads demand structural margins.
- Lightweight:Sub-15 kg total vehicle weight targets personal ownership portability priorities.
- Ultra-Light:Carbon fiber and magnesium alloy constructions occupy premium consumer segments in Japanese and South Korean metropolitan markets.
Heavy-Duty specifications expand most quickly alongside last-mile logistics electrification.
End User:
Customer type determines purchasing cadence, financing structure, and software integration depth.
- Rental Services:City-licensed shared fleets drive unit deployment volumes through B2B procurement at 10,000+ vehicle scale. Operators in Barcelona and Singapore are unbundling hardware from battery-as-a-service subscriptions.
- Delivery Providers:Food and parcel logistics operators replace van-based short-haul routes with two-wheeled electric fleets. Congestion charge avoidance in London and Amsterdam accelerates conversion timelines.
- Personal Use:Individual ownership concentrates in foldable premium segments where portability commands pricing power.
- Corporate Fleets:Facility security and campus mobility programs represent stable replacement demand with centralized maintenance contracts.
Rental Services currently anchor volume. Delivery Providers represent the steepest expansion trajectory as urban logistics electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Shanghai, Stuttgart, and Bangalore are anchoring distinct competitive advantages across the electric scooter value chain. Battery chemistry expertise concentrates in Chinese industrial corridors, while German precision manufacturing and Indian software integration capabilities shape divergent regional specializations.
China
CATL and BYD cylindrical cell production supplies cost-competitive lithium-ion packs for mass-market assembly. MIIT dual carbon goals and GB standards enforcement are accelerating combustion-engine replacement timelines in municipal fleets. Shenzhen and Dongguan manufacturing clusters dominate global export volumes through integrated motor-controller-battery supply ecosystems.
Germany
KBA type-approval requirements and EU Green Deal vehicle mandates are forcing commercial fleets toward zero-emission alternatives in Berlin, Munich, and Hamburg city centers. REACH chemical restrictions and F-Gas Regulation phase-down schedules are reformulating battery cooling loops to eliminate perfluorinated compounds. Stuttgart's automotive engineering base is migrating powertrain expertise into premium scooter thermal management systems.
India
BIS certification requirements and the PLI scheme for battery and motor components are localizing supply chains for domestic brands serving price-sensitive tier-two and tier-three cities. Bangalore and Hyderabad software talent pools are enabling connected vehicle platform development for fleet management applications. Maharashtra and Gujarat manufacturing corridors are capturing component assembly investments from Chinese and Taiwanese tier-one suppliers.
United States
NHTSA import safety standards and EPA domestic manufacturing incentives are shaping product compliance costs and nearshoring decisions. California Air Resources Board zero-emission vehicle mandates are accelerating last-mile delivery fleet conversions in Los Angeles and San Francisco metropolitan areas. Pacific Northwest battery research clusters are piloting solid-state electrolyte architectures for premium segments.
Netherlands
Amsterdam and Rotterdam congestion charge schemes are compressing conversion timelines for urban logistics operators replacing van-based short-haul routes. EU Battery Regulation due diligence requirements are forcing supply chain documentation investments that favor established assemblers with captive compliance capabilities. Eindhoven's high-tech systems integration expertise is supporting battery-swapping network infrastructure deployment.
Global Electric Scooters Market Vendor Landscape
Top-tier vendors anchor premium connected vehicle segments, while commodity manufacturers compete on manufacturing scale and in-house battery production cost positions. The vendor base stratifies across three functional tiers: integrated battery-motor producers, software-integrated design specialists, and assembly-focused regional brands. Dominant competitive moves include backward integration into cell production and geographic expansion through city-licensed fleet partnerships.
Within the scale-driven tier, Yadea Technology Group Co., Ltd. and Gogoro Inc. occupy distinct strategic positions. Yadea exemplifies high-volume Chinese domestic market anchoring through manufacturing scale advantages. Gogoro represents network infrastructure differentiation via proprietary battery-swapping deployment. NIU International sits within the software-integrated design archetype, commanding positioning in European urban centers where connectivity premiums persist. Among India-based specialists, Ola Electric and Ather Energy exemplify domestic brand development under PLI scheme localization incentives.
| Leading Market Players |
|---|
| Yadea Technology Group Co., Ltd. |
| Gogoro Inc. |
| NIU International |
| Ola Electric |
| Ather Energy |
| Bajaj Auto Ltd. |
| TVS Motor Company |
| Honda Motor Co. Ltd. |
| Segway-Ninebot |
| Others |
Supply Flow & Price Mechanics
Cobalt cathode precursor costs cascade through three distinct pricing tiers, with Chinese cylindrical cell producers feeding mass-market assemblers while European premium brands absorb REACH compliance premiums and solid-state R&D amortization into sticker prices.
Pricing Analysis
Battery-as-a-service unbundling separates hardware from energy access, with subscription models displacing upfront pack purchases in Barcelona and Singapore fleet deployments. Three-tier pricing structure across premium connected, standard fleet-grade, and economy commuter levels reflects software integration depth and thermal management certification grade. Cost compression in the economy tier intensifies because state-backed Chinese manufacturers are dumping inventory ahead of anticipated EU anti-dumping adjustments. Delivery providers exhibit highest price sensitivity due to total cost of ownership procurement criteria, while personal foldable buyers accept connectivity premiums.
Supply Chain Analysis
Lithium hydroxide and cobalt sulfate feedstock rests on Chinese refining dominance and DRC mining concentration, with cathode active material production anchored in South Korean and Japanese chemical corridors. Cylindrical cell winding equipment, ceramic electrolyte separators, and rare-earth permanent magnet motors constitute critical component dependencies. Single-source vulnerability concentrates in Chinese battery management system semiconductor fabrication. Distribution runs through Shenzhen and Dongguan export clusters for mass-market assembly, with Stuttgart and Eindhoven serving premium European fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with fleet procurement committees shifting specifications toward solid-state thermal safety and predictive maintenance connectivity as table stakes rather than premiums.
For Market Incumbents: Hedge against battery-swapping network lock-in by securing backward integration into LFP cell production and dual-certifying platforms for both EU Battery Regulation traceability and Indian BIS localization. Diversify manufacturing footprints across Maharashtra and Gujarat corridors to offset tariff exposure from Chinese component dependency. Prioritize embedded systems engineering recruitment to defend software-hardware integration margins against cloud-native entrants. For New Entrants and Emerging Players: Solid-state battery pilot deployments offer a technology-first wedge into premium fleet segments currently blocked by incumbent liability underwriting. Target German and Dutch urban logistics operators with 15-minute fast-charge value propositions. Penetrate tier-two Indian cities through PLI scheme partnerships with localized motor and controller suppliers, leveraging Bangalore software talent for fleet management platform differentiation. For Investors and Strategic Acquirers: Roll-up economics work for battery-swapping infrastructure providers because network density creates natural geographic monopolies and subscription revenue visibility. Five-to-ten year viability favors platform operators with captive energy logistics over pure-play vehicle assemblers. Watch solid-state electrolyte cost curves as the inflection signal for premium segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Network Expansion | Amsterdam and Rotterdam deployments validate 15-minute energy logistics compression. |
| Solid-State Battery Pilot Programs | Taipei fleet trials demonstrate thermal runaway elimination for dense pack configurations. |
| PLI Scheme Localization | Maharashtra and Gujarat corridors capture motor and controller assembly investments. |
| Software-Defined Vehicle Platform | NIU and Ather connected architectures command European urban connectivity premiums. |
| EU Battery Regulation Compliance | Passport traceability investments favor established assemblers with captive documentation capabilities. |
Methodological Framework
Bottom-up fleet operator procurement modeling reconciled against top-down battery cell production tracking forms the analytical core. Primary interviews with shared mobility procurement directors, Tier 1 supplier sales executives, thermal management R&D leads, and municipal licensing administrators combined with secondary validation from MIIT production databases, UN Comtrade lithium carbonate flows, EU type-approval registries, and India PLI scheme disclosure filings. Triangulation across vehicle registration data and battery pack shipment manifests ensures volume reconciliation.
Historical trendline analysis of NMC and LFP cathode cost curves, motor power density improvements, and fleet utilization rates informed projection mechanics across the analysis window. Segmentation dimensions span product architecture, energy chemistry, payload specification, and end-use procurement archetype. CAGRs derive from fitted adoption curves weighted by municipal mandate enforcement timelines and last-mile logistics electrification penetration. Solid-state electrolyte maturity and battery-swapping network density serve as scenario-weighting inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cobalt export restriction timing, EU subsidy phase-out schedules, and solid-state manufacturing yield breakthroughs. Assumptions reflect documented regulatory trajectories and disclosed supplier capacity expansions. A small set of triggers—Chinese anti-dumping tariff adjustments, India PLI scheme renewal terms, and UL 2272 standard revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Africa Electric Vehicle Market