
 Electric Pickup Truck Market | 2026-2036
Electric Pickup Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Pickup Truck Market Analysis
Fleet procurement consolidation among North American logistics operators is recalibrating volume allocation across electric pickup manufacturers. Tesla leverages its proprietary charging infrastructure to anchor fleet contracts with multi-vehicle operators. Ford Motor Company sustains commercial loyalty through its established dealer service network and F-Series brand recognition. Rivian differentiates via vertical integration into last-mile delivery configurations tailored for enterprise buyers.
An electric pickup truck is a battery-powered light-duty vehicle with a separate open cargo bed, typically offering towing capacity exceeding 3,500 kg and DC fast charging compatibility above 150 kW, designed for both commercial hauling and personal utility applications. Battery Electric Vehicles command the dominant revenue share due to zero-emission compliance advantages and declining lithium-ion cell costs. Fleet Operations represents the fastest-growing application segment as enterprise buyers prioritize total cost of ownership over upfront capital expenditure. Vehicle-to-Grid technology sits at the emerging margin pool, enabling bidirectional power flow that converts parked trucks into grid assets.
The US EPA enforces progressively stringent tailpipe emission standards that effectively mandate electrification timelines for light-duty truck categories. The IRA clean vehicle tax credits reshape demand economics by conditioning consumer rebates on domestic battery sourcing and final assembly location. NHTSA crashworthiness protocols for heavy electric vehicles impose structural design requirements that influence platform architecture decisions. Stakeholders must monitor how regulatory credit trading values and battery mineral supply agreements interact to determine viable production scale.
Market Dynamics
Fleet electrification mandates are compressing procurement timelines across North American logistics networks, forcing manufacturers to accelerate platform development while securing battery mineral supply agreements.
Growth Catalysts
- IRA Clean Vehicle Tax Credits:Domestic final assembly and battery sourcing requirements redirect manufacturing investment toward US-based production facilities.
- Last-Mile Delivery Electrification:E-commerce fulfillment networks are replacing diesel vans with electric pickups to meet municipal zero-emission delivery zones.
- Vehicle-to-Grid Integration:Bidirectional charging infrastructure is expanding into utility fleet partnerships, creating recurring revenue streams from grid stabilization services.
Market Restraints
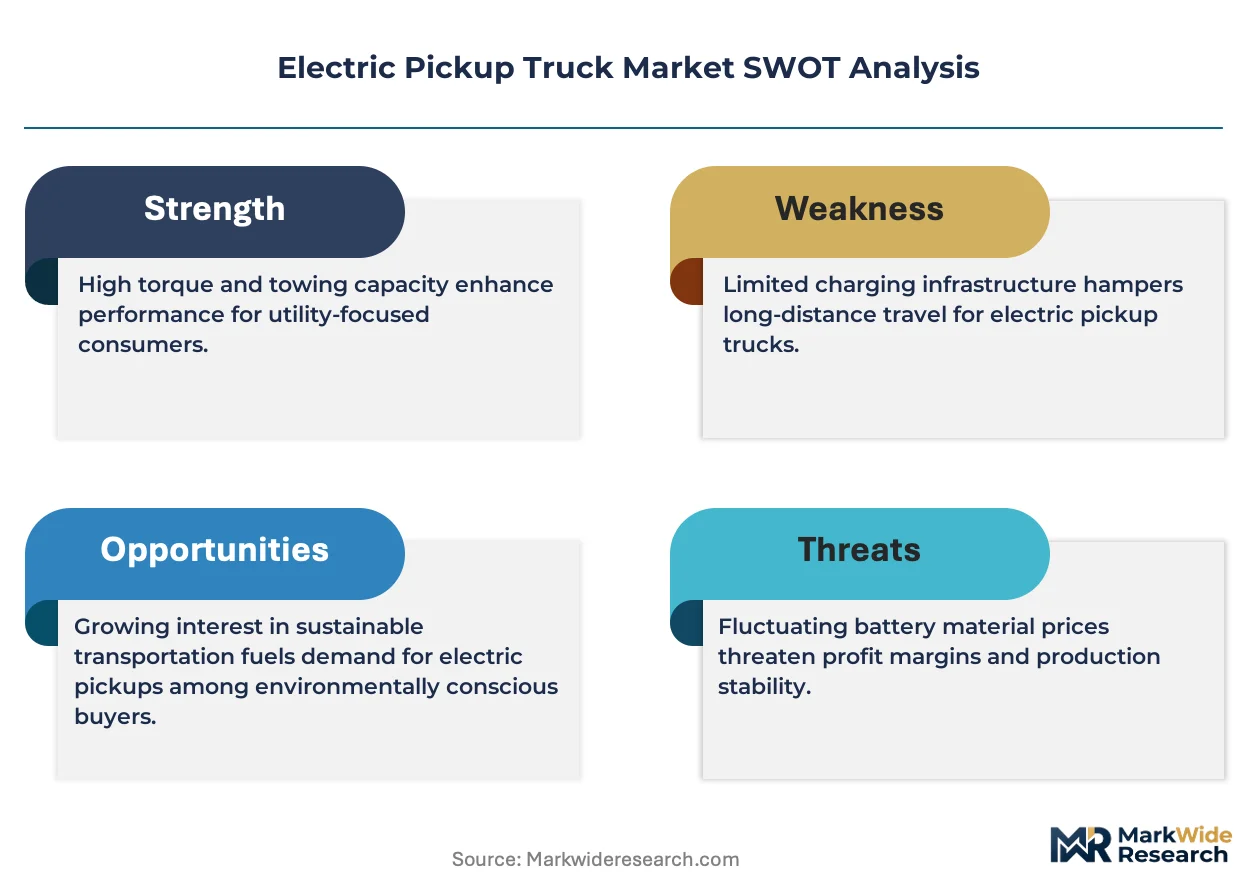
- Lithium-Ion Cell Cost Volatility:Cathode material price swings constrain OEM pricing flexibility and compress gross margins on entry-level configurations.
- Charging Infrastructure Gaps:Rural interstate corridors lack 350 kW DC fast charging density, limiting long-haul fleet deployment outside urban freight hubs.
- NHTSA Heavy EV Crashworthiness Protocols:Structural reinforcement requirements add platform weight and reduce payload capacity versus comparable ICE equivalents.
Strategic Opportunities
- Texas Commercial Corridors:Oilfield service operators are piloting electric pickups for remote site maintenance, opening fleet segments previously dominated by diesel trucks.
- Worksite Power Export:Integrated power inverters are enabling electric pickups to replace portable generators at construction and utility job sites.
- EPA Fleet Emissions Rules:Progressive light-duty truck standards create compliance credit demand that electric pickup manufacturers can monetize through trading mechanisms.
Industry Challenges
- Battery Thermal Management Engineering:OEMs face talent scarcity in electrochemical systems design and thermal runaway mitigation for extreme climate operation.
- Service Technician Certification:High-voltage safety training requirements outpace community college program expansion, creating dealer network bottlenecks.
- Platform Architecture Standardization:Competing charging connector formats and battery pack dimensions fragment supplier ecosystems and inflate component costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Pickup Truck Market |
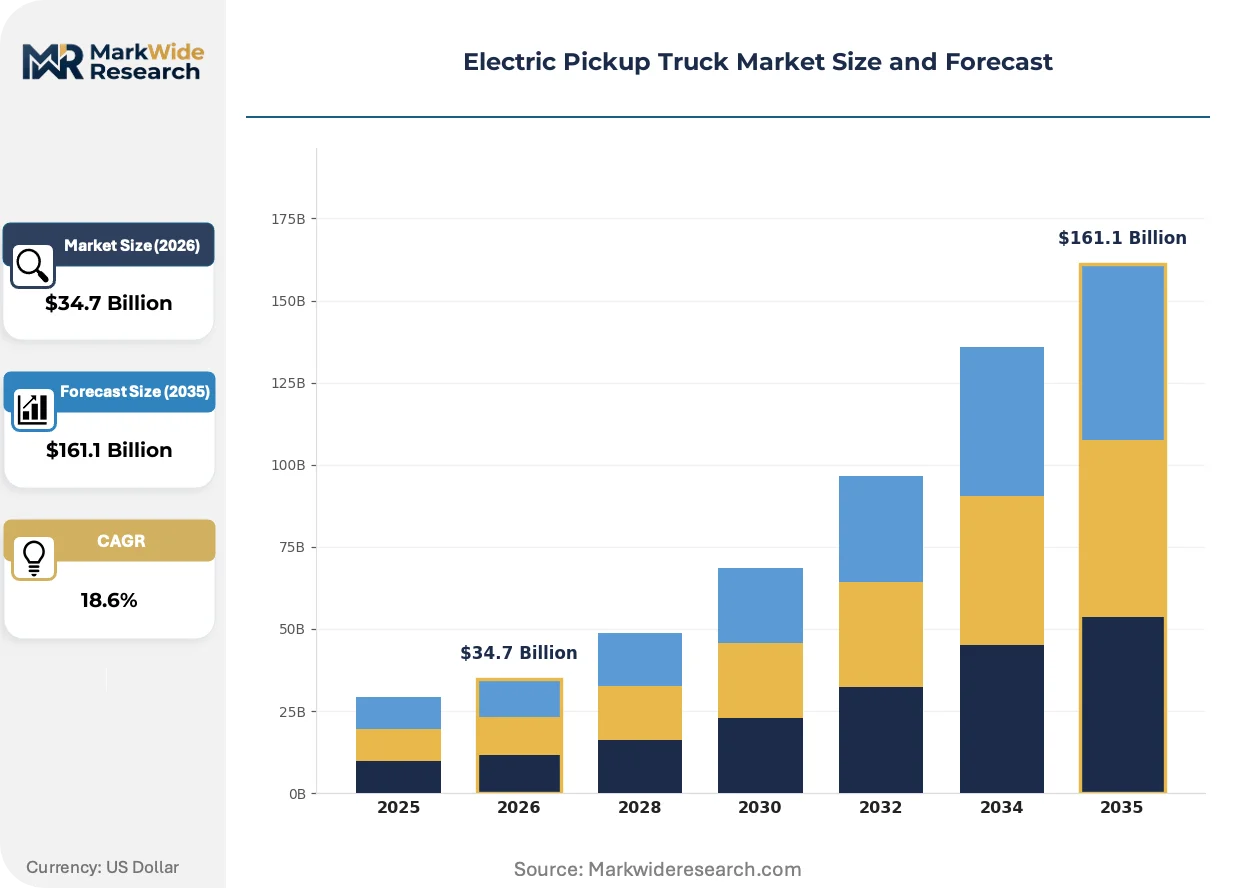
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $161.1 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicles, Extended Range Electric Vehicles, Hybrid Electric Vehicles, Plug-in Hybrid Electric Vehicles Application: Commercial Use, Personal Use, Fleet Operations, Off-Roading Technology: Fast Charging, Regenerative Braking, Vehicle-to-Grid, Autonomous Driving End User: Retail Consumers, Business Enterprises, Government Agencies, Agricultural Operators |
| Companies Covered | Ford Motor Company, Tesla, Rivian, General Motors, Chevrolet, GMC, Stellantis, Volkswagen, Hyundai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Pickup Truck Market Emerging Trajectories
Electrification is forcing convergence between automotive manufacturing and energy infrastructure, reshaping how trucks are sold, serviced, and integrated into customer operations.
Silicon carbide power electronics are replacing traditional silicon inverters to reduce energy losses during DC fast charging sessions. Fleet operators adopting 800-volt architectures are cutting charging dwell times by thirty percent on cross-country routes. This efficiency gain is expanding into total cost of ownership calculations that now favor electric platforms over diesel for high-mileage applications.
California's Advanced Clean Trucks regulation mandates escalating zero-emission sales percentages for manufacturers above specified volume thresholds. The rule forces national OEMs to allocate battery supply toward compliant configurations regardless of demand geography. Texas and Florida fleet buyers now encounter limited ICE availability as production shifts to satisfy California compliance requirements.
Enterprise buyers are consolidating vehicle procurement through direct manufacturer relationships rather than traditional dealer networks. Large logistics operators negotiate multi-year supply agreements with guaranteed pricing and priority delivery slots. This channel migration concentrates volume among manufacturers with captive financing arms and dedicated fleet sales organizations.
Electric Pickup Truck Market Segmentation
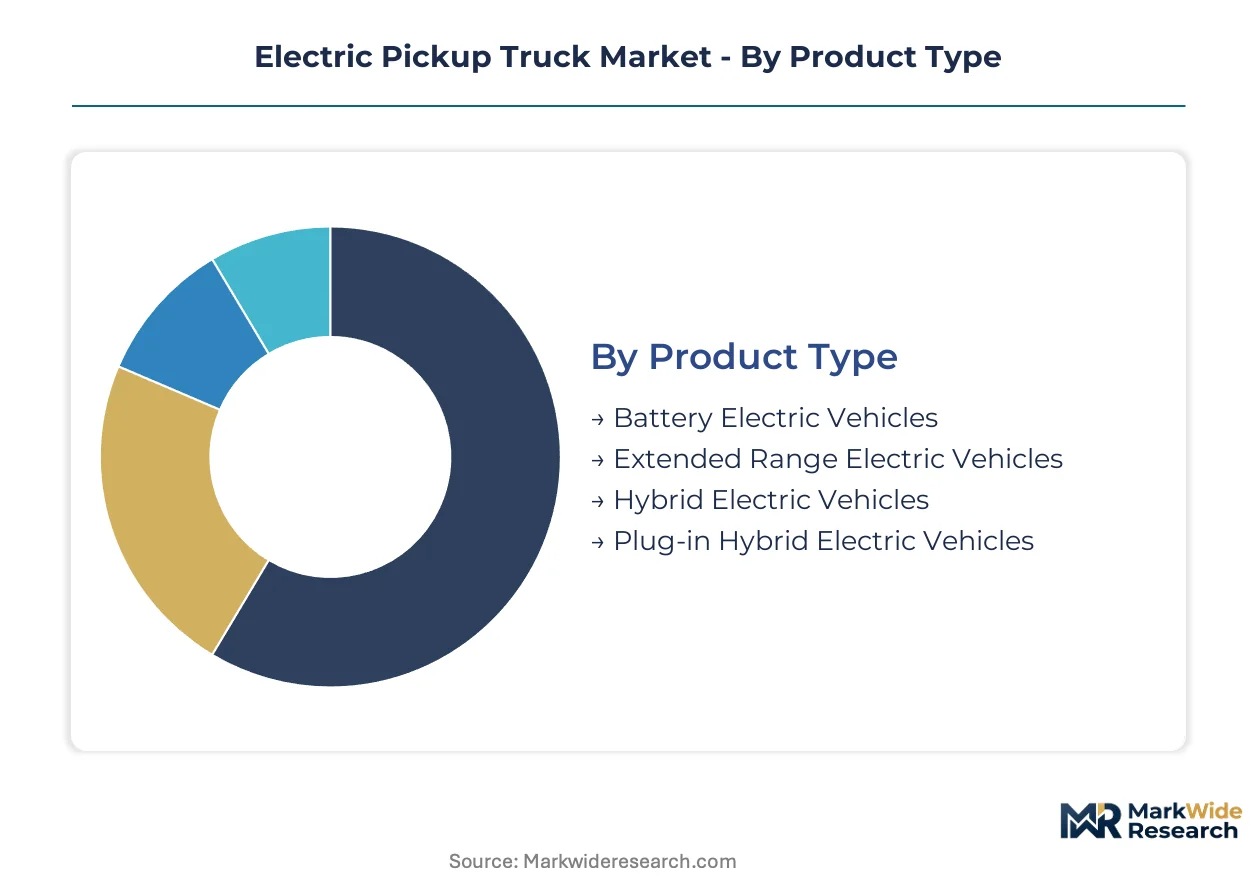
Segmentation in the electric pickup truck market reveals how battery chemistry choices, charging infrastructure access, and duty cycle requirements partition demand across divergent customer workflows. Manufacturers calibrate platform specifications to match the thermal management and payload priorities of each segment.
Product Type:
Supply concentration in lithium-ion cell manufacturing favors pure battery electric architectures, though cathode chemistry diversification is creating tiered performance categories.
- Battery Electric Vehicles:These platforms rely exclusively on lithium-ion packs with energy densities exceeding 250 Wh/kg, enabling 480 km range ratings. Fleet operators in California commercial corridors prioritize these configurations to satisfy EPA tailpipe compliance mandates and access IRA tax credit pools.
- Extended Range Electric Vehicles:Small displacement range-extender engines supplement battery packs, preserving electric drive while eliminating range anxiety on rural interstate corridors. Texas oilfield service fleets pilot these configurations where 350 kW DC fast charging density remains insufficient for pure battery electric deployment.
- Hybrid Electric Vehicles:Parallel hybrid architectures blend internal combustion with modest electric assist, offering lower upfront capital requirements for price-sensitive agricultural operators.
- Plug-in Hybrid Electric Vehicles:Larger battery packs than conventional hybrids enable 60-80 km electric-only operation, appealing to suburban retail consumers with intermittent hauling needs.
Battery Electric Vehicles absorb the bulk of installed capacity; Extended Range Electric Vehicles are expanding most quickly.
Application:
Cost tier differentiation separates heavy-duty commercial configurations from lighter personal utility specifications, with fleet procurement consolidating toward enterprise-grade platforms.
- Fleet Operations:High-mileage logistics networks prioritize total cost of ownership metrics over upfront capital expenditure, driving demand for 800-volt architectures with silicon carbide inverters. E-commerce fulfillment operators in municipal zero-emission delivery zones anchor volume concentration.
- Commercial Use:Construction and utility contractors require integrated power inverters exceeding 9.6 kW for worksite equipment operation. Bidirectional charging compatibility converts parked trucks into mobile power assets at remote job sites.
- Personal Use:Retail buyers emphasize cabin refinement and infotainment integration over payload maximization, with towing capacity requirements rarely exceeding 4,500 kg.
- Off-Roading:Specialized suspension geometries and protective underbody plating address recreational desert and rock-crawling applications, representing a niche premium segment.
Fleet Operations commands the steepest expansion trajectory; Commercial Use retains the largest revenue base.
Technology:
Volume deployment concentrates on charging speed and energy recovery systems, with emerging grid integration features capturing early-adopter enterprise contracts.
- Fast Charging:350 kW DC capability reduces dwell times to under 20 minutes for 10-80 percent state-of-charge events. Cross-country logistics operators specify this hardware to maintain diesel-competitive utilization rates.
- Regenerative Braking:Blended brake systems recover kinetic energy during deceleration, extending effective range in stop-and-go urban freight corridors.
- Vehicle-to-Grid:Bidirectional power flow enables utility fleet partnerships for grid stabilization services, creating recurring revenue streams from parked assets.
- Autonomous Driving:Level 2+ driver assistance packages with highway lane-keeping represent the current deployment frontier for personal use segments.
Fast Charging dominates current procurement specifications; Vehicle-to-Grid is gaining share fastest among municipal utility partnerships.
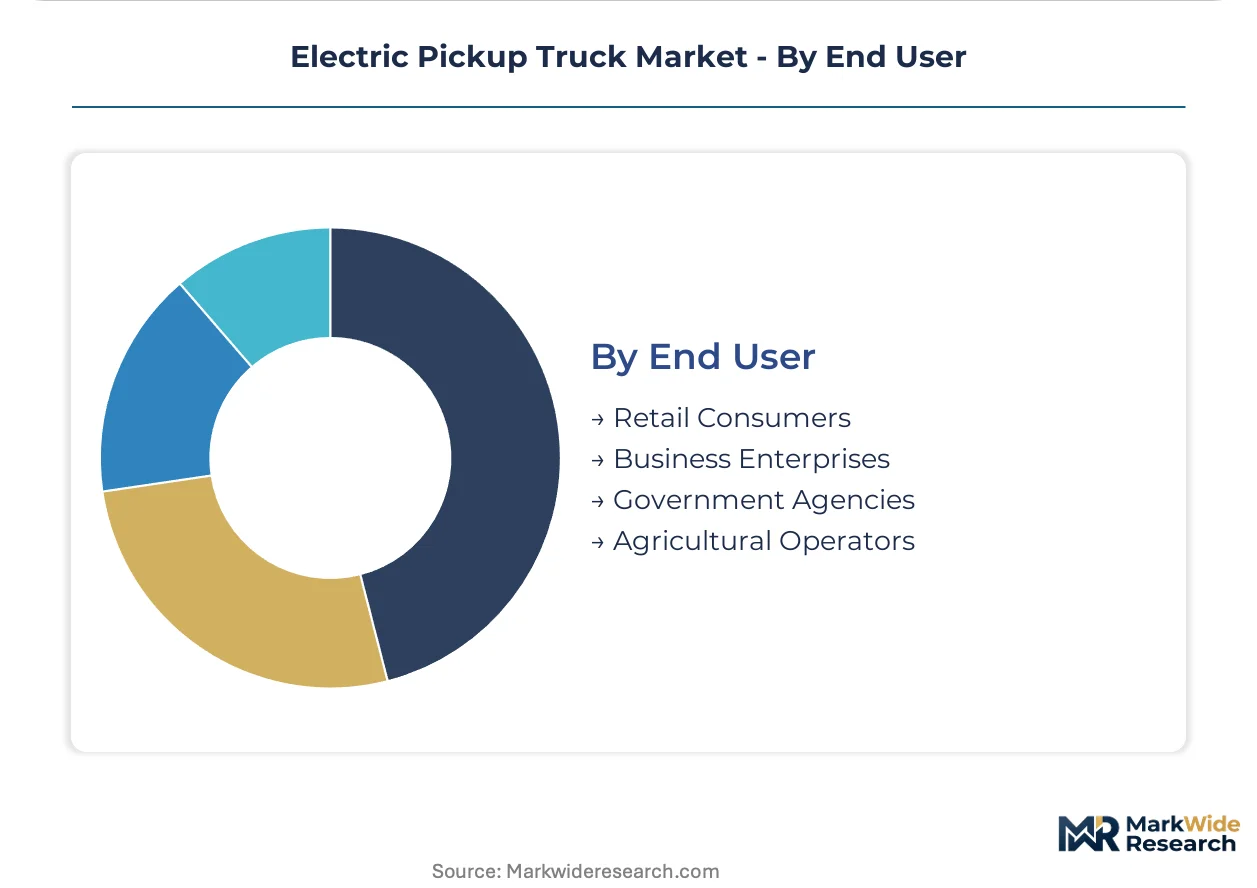
End User:
Customer type segmentation maps directly to financing structure preferences, with enterprise buyers leveraging captive manufacturer financing and government agencies requiring domestic assembly certification.
- Business Enterprises:Direct manufacturer relationships replace traditional dealer networks for large logistics operators negotiating multi-year supply agreements with guaranteed pricing and priority delivery slots.
- Government Agencies:Federal and state procurement mandates favor domestic final assembly and qualifying critical mineral sourcing under IRA domestic content requirements.
- Retail Consumers:Individual buyers access clean vehicle tax credits through dealer channels, with rebate processing complexity influencing purchase timing.
- Agricultural Operators:Rural property owners prioritize worksite power export capability and towing performance for equipment trailers over charging speed optimization.
Business Enterprises represent the largest revenue concentration; Government Agencies are climbing the fastest on procurement mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States commercial corridors concentrate electric pickup demand through fleet procurement mandates and federal tax credit structures. Texas and California anchor volume concentration, with logistics operators and oilfield service companies driving divergent configuration requirements.
United States
California's Advanced Clean Trucks regulation compels national OEMs to allocate battery supply toward zero-emission configurations. The IRA clean vehicle tax credits condition rebates on domestic final assembly and critical mineral sourcing. Dallas-Fort Worth logistics hubs are piloting electric pickups for last-mile delivery electrification.
Canada
Federal zero-emission vehicle mandates accelerate provincial fleet procurement in British Columbia and Quebec. Environment and Climate Change Canada enforces progressively stringent light-duty vehicle emissions standards. Ontario's automotive manufacturing corridor is retooling for battery electric truck production.
Germany
Commercial fleet operators prioritize total cost of ownership metrics under EU Green Deal decarbonization timelines. The KBA enforces type-approval standards for heavy electric vehicle crashworthiness and electromagnetic compatibility. Stuttgart's industrial region hosts engineering centers developing 800-volt platform architectures.
China
Dual carbon goals and NEV subsidies redirect domestic manufacturer capacity toward battery electric platforms. MIIT mandates domestic battery sourcing and energy density thresholds for new energy vehicle certification. Shenzhen's Pearl River Delta cluster supplies lithium-ion cells and power electronics to global OEMs.
Australia
Mining and agricultural operators evaluate electric pickups for remote site power export and towing applications. The country's national transport regulator imposes design rules for heavy vehicle safety and electrical system isolation. Western Australia's Pilbara region pilots electric utility vehicles for iron ore infrastructure maintenance.
Electric Pickup Truck Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated charging infrastructure and vertical integration strategies. The market structure consolidates around manufacturers with captive battery supply agreements and dedicated fleet sales organizations. Three archetypes dominate: legacy automakers with dealer network scale, pure-play EV specialists with software-defined architectures, and diversified conglomerates with component ecosystem control. Capacity expansion and strategic partnerships constitute the primary competitive vectors as manufacturers secure lithium supply and charging network access.
Within the legacy automaker tier, Ford Motor Company and General Motors represent established commercial loyalty through F-Series and Silverado brand recognition. Tesla exemplifies the pure-play EV archetype with proprietary charging infrastructure anchoring fleet contracts. Among diversified conglomerates, Stellantis occupies a position spanning multiple brand portfolios and regional market access.
| Leading Market Players |
|---|
| Ford Motor Company |
| Tesla |
| Rivian |
| General Motors |
| Chevrolet |
| GMC |
| Stellantis |
| Volkswagen |
| Hyundai |
| Others |
Supply Flow & Price Mechanics
Fleet procurement consolidation among North American logistics operators is compressing contract timelines and forcing manufacturers to absorb lithium-ion cell cost volatility into long-term pricing agreements. This demand-side pressure reshapes how OEMs structure volume discounts and captive financing terms.
Pricing Analysis
Volume concentration among enterprise fleet buyers splits pricing power toward contract-based long-term offtake structures with guaranteed delivery slots. Three-tier pricing structure across premium, standard, and economy levels separates 800-volt silicon carbide architectures from 400-volt entry configurations and hybrid electric alternatives. Cost compression in entry-level battery packs is intensifying because cathode material price swings constrain OEM flexibility. Agricultural operators exhibit highest price sensitivity due to intermittent duty cycles, while municipal utility fleets prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Freight cost inflation across Pacific shipping lanes is amplifying landed cost differentials between China-sourced lithium-ion cells and domestically assembled battery packs. Supply concentrates in China, South Korea, and Australia for lithium extraction and cathode precursor processing, with the Pearl River Delta cluster feeding power electronics and cell manufacturing. The supply chain rests on cobalt, nickel, and lithium carbonate inputs subject to commodity price volatility and export licensing restrictions. Single-source vulnerability in semiconductor-grade silicon carbide wafers threatens inverter production schedules. Distribution runs through direct manufacturer relationships for enterprise fleets and traditional dealer networks for retail consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric pickup truck market operates as a cost-of-compliance story where IRA domestic content requirements and EPA tailpipe standards erect regulatory moats favoring manufacturers with US-based battery supply agreements.
For Market Incumbents: To counter emerging pure-play EV specialists with software-defined architectures, legacy automakers should deepen backward integration into battery cell manufacturing through joint ventures with Korean cathode suppliers. Securing NHTSA crashworthiness certification ahead of regulatory phase-in dates preserves dealer network scale advantages against new entrants lacking service infrastructure. For New Entrants and Emerging Players: Capture white-space opportunity in Texas oilfield service fleets where extended-range electric configurations address charging infrastructure gaps on remote interstate corridors. Agricultural operators in the Midwest present underpenetrated demand for worksite power export capability. A direct-to-fleet sales model bypassing dealer networks accelerates contract acquisition against established OEMs. For Investors and Strategic Acquirers: The window for entry favors manufacturers with captive lithium supply agreements and 800-volt platform architectures positioned for IRA tax credit eligibility. Long-term viability hinges on vertical integration depth rather than brand heritage. Battery mineral supply agreement announcements serve as the critical signal for production scale inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium carbonate and cathode precursor flows from Australian and Chilean mining operations. |
| Platform Standardization | Reduces engineering costs across F-Series and Silverado electric variants through shared 800-volt architectures. |
| Charging Infrastructure Partnership | Expands 350 kW DC fast charging density along California-Texas freight corridors for fleet utilization. |
| Software-Defined Vehicle Investment | Enables over-the-air updates and subscription revenue streams from fleet telematics services. |
| Geographic Manufacturing Footprint | Satisfies IRA domestic assembly requirements for clean vehicle tax credit eligibility. |
Methodological Framework
SEC 10-K filings, EPA regulatory dockets, and IHS Markit vehicle registration data formed the secondary backbone, supplemented by customs records tracking lithium-ion cell imports. Primary interviews with OEM platform engineers, fleet procurement directors at logistics operators, and Tier 1 supplier executives provided forward-looking contract visibility. Bottom-up and top-down triangulation reconciled production capacity announcements against end-user demand signals.
Bottom-up modeling aggregated segment-level volume assumptions across propulsion architecture, vehicle class, and OEM tier dimensions, while top-down analysis validated aggregate market expansion against IRA incentive pool allocations. CAGRs were derived from logistic diffusion curves fitted to fleet electrification mandate timelines. Forecast inputs incorporated battery cost learning curves and charging infrastructure deployment schedules.
The model holds under stable lithium carbonate pricing and sustained IRA credit authorization; deviation in critical mineral export restrictions or NHTSA rulemaking acceleration would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market