
 Solar E-Bike Market | 2026-2036
Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Solar E-Bike Market Analytics
Multi-source photovoltaic panel procurement is decoupling from legacy single-source silicon supply arrangements among leading bicycle manufacturers. Giant Manufacturing Co. Ltd. leverages captive assembly lines in Taiwan to control solar module-to-frame integration quality. Yadea Group Holdings Ltd. anchors its cost position through vertically owned battery cell production in mainland China. Specialized Bicycle Components, Inc. differentiates via premium carbon fiber solar roof rack systems engineered for North American commuter routes.
A solar e-bike integrates photovoltaic cells into frame surfaces, roof racks, or detachable panels to supplement lithium-ion battery charge, typically generating 30-60 watts under standard irradiance to extend range by 15-40 percent. The primary commercial purpose is reducing plug-in dependency for last-mile delivery fleets and daily commuters in high-sunlight geographies. Lithium-ion battery configurations dominate unit economics due to superior energy density and cycle life versus lead-acid alternatives. Fleet operators represent the fastest-expanding end-user category as logistics providers seek to decarbonize two-wheel delivery pods without expanding charging infrastructure footprints. Aluminum frame materials sustain volume leadership through manufacturability, though carbon fiber commands margin pools in premium commuter segments.
The EPA regulates photovoltaic material disposal under universal waste rules, while the EU Green Deal's embedded carbon tariffs shape import competitiveness for Asian-manufactured solar e-bikes entering European markets. China's SAMR enforces GB standards governing solar panel output stability and electrical system interoperability with bicycle drivetrains. India's BIS certification requirements for lithium-ion cell safety create incremental compliance costs for exporters targeting South Asian fleet contracts. Stakeholders must monitor how divergent recyclability mandates across these jurisdictions reshape component sourcing decisions and aftermarket service obligations.
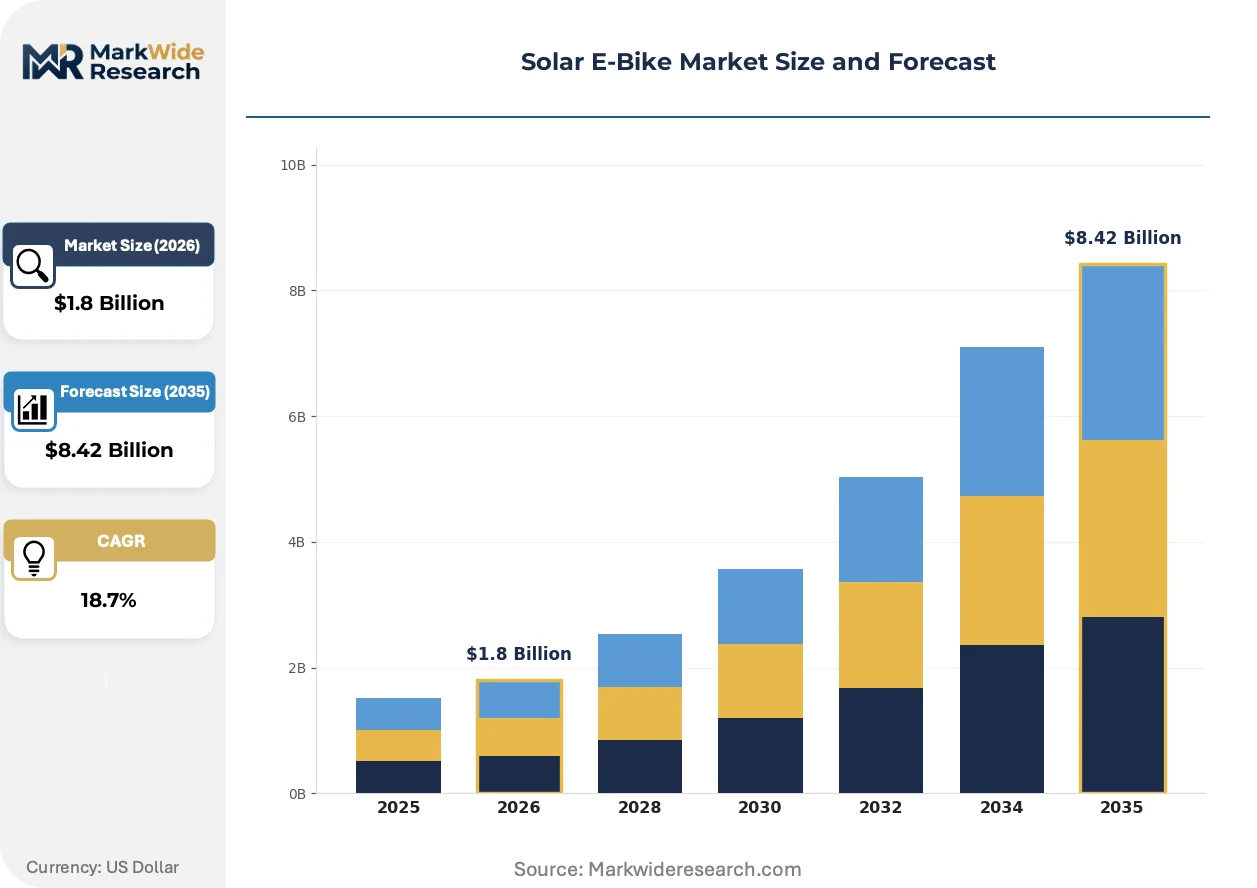
Market Dynamics
Fleet electrification mandates in urban logistics networks are compressing procurement cycles for solar-assisted two-wheelers as operators seek to decouple last-mile delivery costs from grid electricity price volatility.
Growth Catalysts
- EU Green Deal embedded carbon tariffs:Import duties tied to production emissions are accelerating European manufacturing investments for solar e-bike assembly, favoring regional producers over distant exporters.
- Last-mile delivery fleet decarbonization:Logistics providers operating dense urban routes are replacing conventional e-bikes with solar-assisted units to reduce charging infrastructure footprint and extend daily range.
- Perovskite-silicon tandem cells:Higher conversion efficiency in next-generation photovoltaic materials is expanding viable operating hours for solar charging in temperate climates previously considered marginal.
Market Restraints
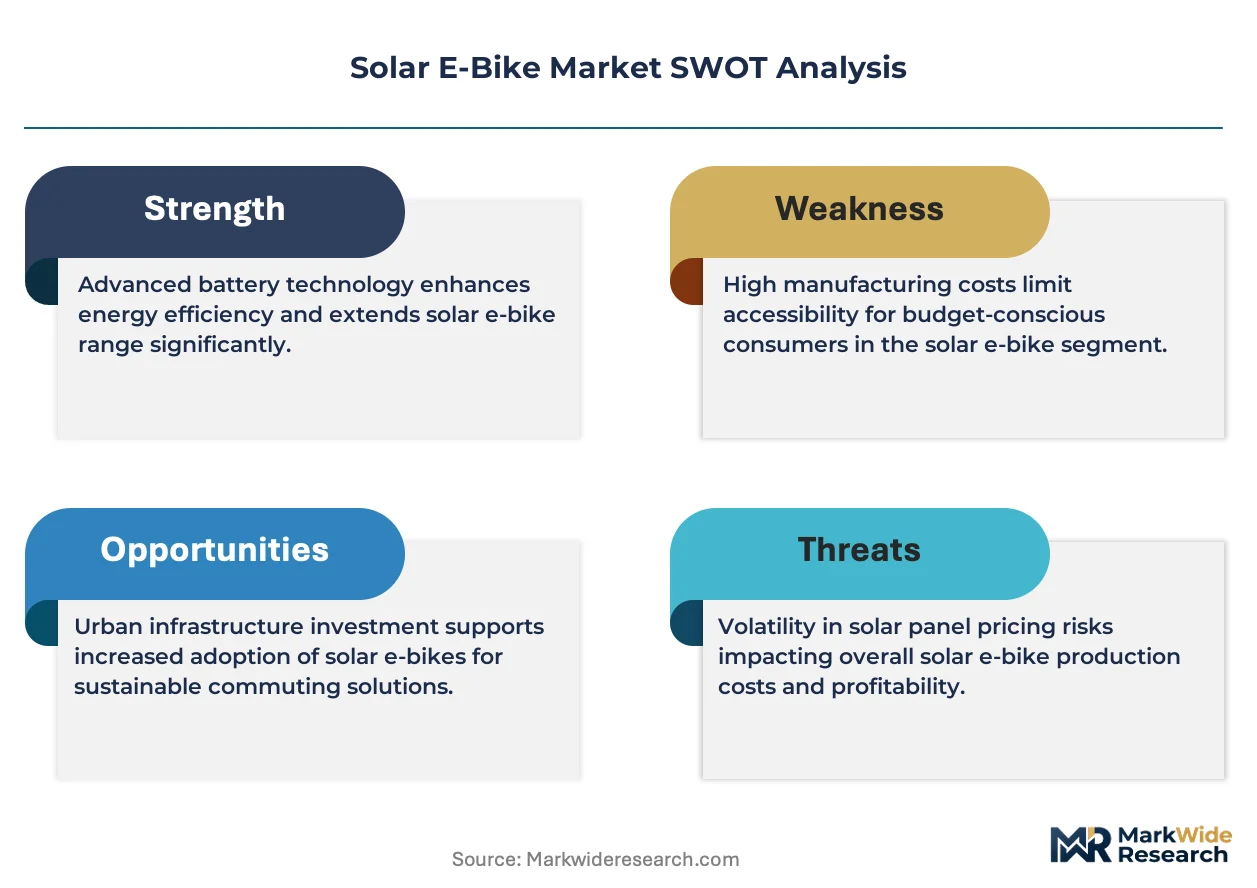
- Lithium carbonate price volatility:Battery cell input costs swing with mining output from Chile and Australia, compressing assembler margins and destabilizing long-term fleet procurement contracts.
- Photovoltaic wafer supply concentration:Polysilicon refining and ingot slicing capacity clusters in Xinjiang and Inner Mongolia, creating single-source vulnerability for solar module procurement.
- Intermittent irradiance dependency:Northern European and Pacific Northwest operating environments yield insufficient solar capture for meaningful range extension, limiting addressable market geography.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic battery production incentives are lowering landed costs for solar e-bike assemblers targeting South Asian fleet contracts.
- Vehicle-to-grid integration:Bi-directional charging hardware convergence with solar capture systems creates new revenue streams from grid stabilization services in markets with dynamic electricity pricing.
- Subscription-based fleet-as-a-service models:Third-party logistics providers are outsourcing entire two-wheel delivery pod operations, shifting capital burden from fleet operators to specialized asset managers.
Industry Challenges
- Photovoltaic-electrical system interoperability certification:China's SAMR GB standards and India's BIS requirements impose divergent testing protocols, fragmenting product development roadmaps and extending time-to-market.
- Composite frame repair technician scarcity:Carbon fiber solar roof rack damage requires specialized bonding expertise that conventional bicycle service networks lack, creating aftermarket service gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar E-Bike Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Frame Material: Aluminum, Carbon Fiber, Steel, Titanium Charging Method: Solar Charging, Standard Plug-in, Regenerative Braking, Hybrid End User: Commuters, Recreational Users, Delivery Services, Fleet Operators |
| Companies Covered | Yamaha Motor Company, Pedego Electric Bikes, Giant Manufacturing Co. Ltd., Yadea Group Holdings Ltd., Accell Group N.V., Trek Bicycle Corporation, Merida Industry Co. Ltd, Hi Power Cycles, Specialized Bicycle Components, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar E-Bike Market Evolving Landscape
Photovoltaic integration architectures are diversifying beyond frame-embedded cells toward modular, detachable systems that decouple solar generation from bicycle design constraints.
Flexible thin-film solar laminates are expanding into curved frame tubes and handlebar fairings previously inaccessible to rigid crystalline panels. German municipal bike-sharing operators are piloting these systems across Berlin and Munich fleets to reduce depot charging frequency. The technology is expanding into premium commuter segments where weight reduction justifies higher module cost per watt.
China's GB standards for solar panel output stability are tightening electrical system interoperability requirements with bicycle drivetrains. Assemblers must now certify combined photovoltaic-battery-controller packages as integrated units rather than discrete components. European importers are responding by establishing captive testing facilities in Shenzhen to accelerate compliance timelines.
Direct procurement relationships between logistics operators and photovoltaic module suppliers are displacing traditional tiered distribution channels. Large fleet buyers now negotiate solar cell supply agreements separately from bicycle frame contracts, unbundling what were previously integrated vendor relationships. This pattern is most visible in the Netherlands, where PostNL and similar operators maintain dedicated renewable energy procurement teams.
Solar E-Bike Market Segmentation
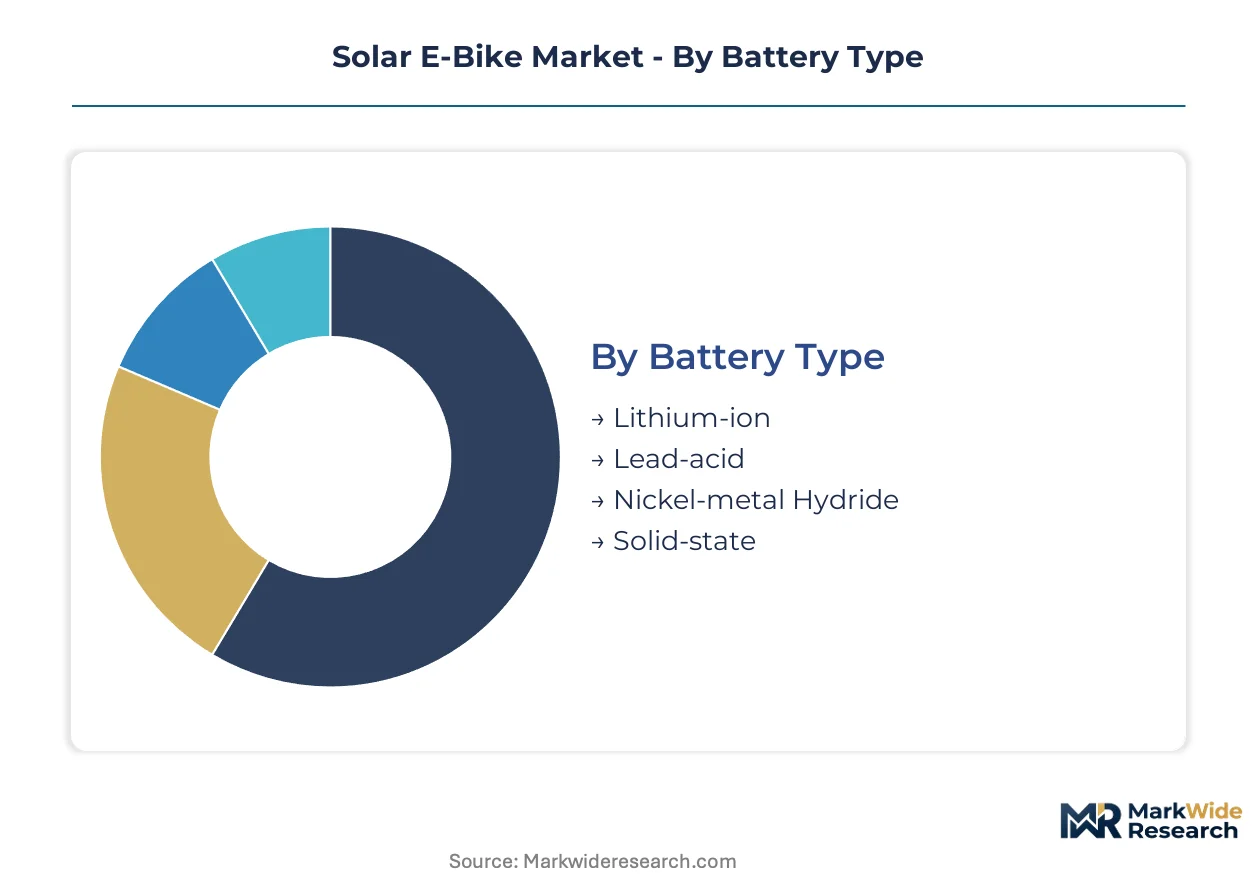
Solar e-bike segmentation reveals divergent technology bets across battery chemistry and frame architecture. Procurement patterns split sharply between cost-optimized fleet specifications and premium commuter configurations where solar range extension commands price premiums.
Battery Type:
Volume leadership sits with mature lithium-ion architectures, while solid-state prototypes target premium displacement.
- Lithium-ion:Dominates unit economics through superior energy density and cycle life. Fleet operators in Germany and the Netherlands specify these cells for daily delivery routes exceeding 80 kilometers, though lithium carbonate price swings from Chilean and Australian mining output compress assembler margins.
- Solid-state:Next-generation electrolyte architectures promise enhanced thermal stability and faster charge acceptance. Early pilots by Japanese automotive suppliers target premium commuter segments where safety certification and energy density justify prototype pricing.
- Lead-acid:Retains residual share in price-sensitive South Asian markets with minimal regulatory pressure on battery disposal.
- Nickel-metal Hydride:Niche presence in cold-climate applications where temperature tolerance exceeds lithium-ion performance floors.
Today's leader: Lithium-ion. Tomorrow's challenger: Solid-state.
Frame Material:
Manufacturability drives aluminum dominance, yet margin pools concentrate in carbon fiber solar integration.
- Aluminum:Extrusion and welding efficiencies sustain volume leadership across fleet procurement. Chinese assemblers leverage mature supply chains in Guangdong and Zhejiang provinces to deliver sub-$800 unit costs for logistics operators.
- Carbon Fiber:Premium commuter segments absorb higher material costs for weight reduction and photovoltaic roof rack compatibility. Specialized bonding requirements for solar panel mounting create aftermarket service scarcity that constrains fleet adoption.
- Steel:Utility cycling applications in emerging markets prioritize impact resistance over mass reduction.
- Titanium:Ultra-premium artisan production serves enthusiast collectors with minimal solar integration due to fabrication complexity.
Aluminum captures fleet volume. Carbon fiber claims margin concentration.
Charging Method:
Solar-assisted architectures are climbing fastest as depot infrastructure constraints bite.
- Solar Charging:Photovoltaic integration extends daily range 15-40 percent under standard irradiance. German municipal bike-sharing programs in Berlin and Munich pilot frame-embedded and roof-rack configurations to reduce charging frequency.
- Hybrid:Combines plug-in base charging with supplemental solar capture. Dutch logistics operators favor this architecture for routes spanning high-variability weather corridors.
- Standard Plug-in:Remains baseline for residential commuters with reliable grid access.
- Regenerative Braking:Kinetic recovery systems add marginal range extension in stop-start urban environments.
Plug-in holds installed base. Solar-assisted gains share fastest.
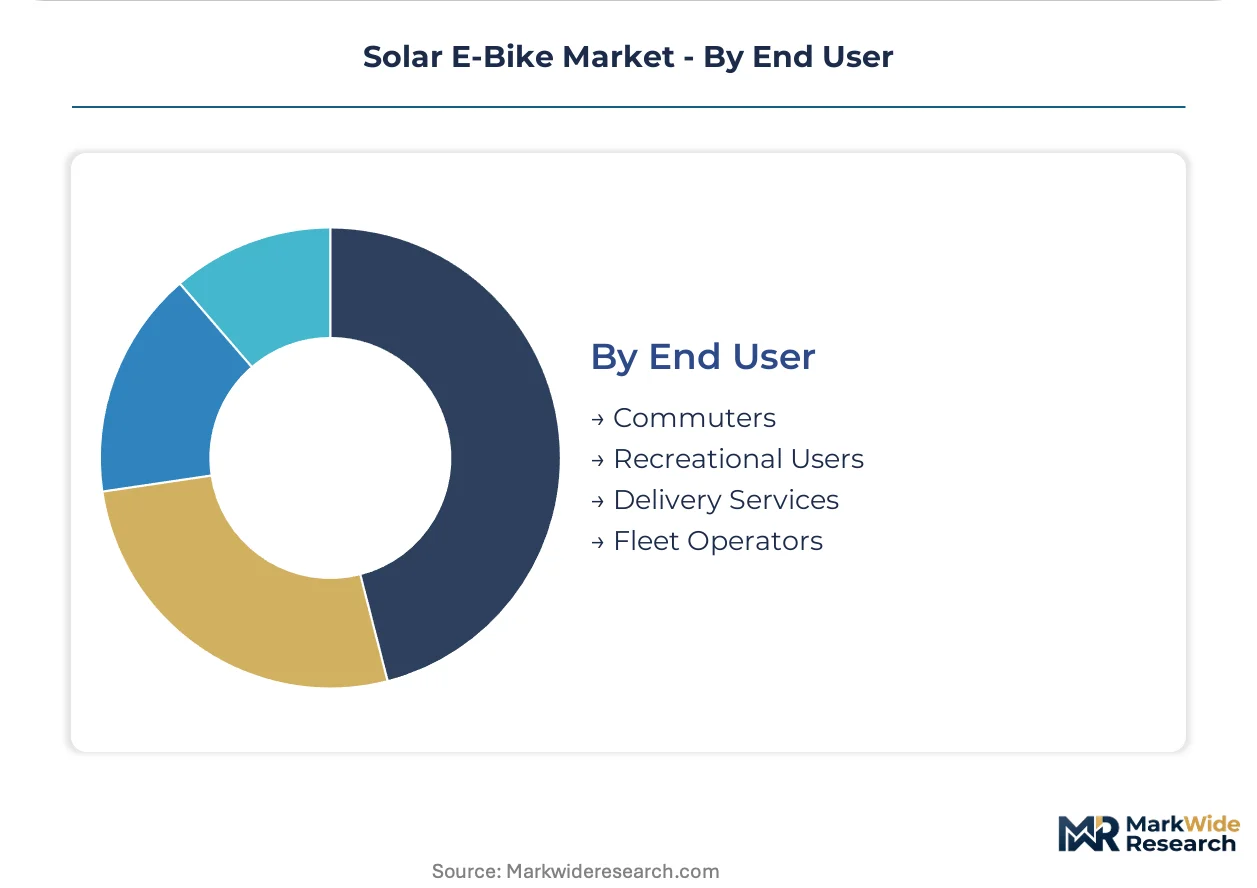
End User:
Fleet procurement cycles compress as logistics decarbonization mandates harden.
- Fleet Operators:Third-party logistics providers and municipal bike-sharing programs drive fastest-expanding demand. India's PLI scheme for advanced chemistry cells lowers landed costs for assemblers targeting South Asian delivery pod contracts.
- Commuters:Daily urban riders in high-sunlight geographies absorb premium pricing for solar range extension. North American markets show particular appetite for carbon fiber solar roof rack systems.
- Delivery Services:Last-mile operators decouple from grid electricity price volatility through solar supplementation.
- Recreational Users:Weekend and touring cyclists prioritize battery capacity over solar integration due to intermittent usage patterns.
Fleet operators anchor volume expansion. Commuters defend premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors photovoltaic module assembly for bicycle integration, with Shenzhen and Dongguan clusters supplying frame-embedded solar cells to European and North American assemblers. Fleet procurement contracts from German logistics operators and Dutch bike-sharing programs drive cross-border component flows. Regulatory divergence across import markets shapes regional manufacturing investment patterns.
Germany
Municipal bike-sharing programs in Berlin and Munich accelerate solar-assisted fleet renewals through commuter subsidy schemes. The EU Green Deal's embedded carbon tariffs favor regional assembly over distant imports. Baden-Württemberg's precision engineering clusters supply photovoltaic mounting hardware to domestic bicycle manufacturers.
China
Vertically integrated battery cell production in Jiangsu and Zhejiang provinces compresses landed costs for export-bound solar e-bike assemblers. SAMR's tightening GB standards for solar panel output stability and electrical system interoperability extend product certification timelines. The Pearl River Delta concentration of aluminum extrusion capacity supports sub-$800 fleet unit production.
Netherlands
PostNL and urban logistics operators negotiate direct photovoltaic supply agreements separate from bicycle frame contracts. The country's dynamic electricity pricing environment stimulates vehicle-to-grid integration pilots for bi-directional solar capture systems. Randstad metropolitan depots serve as testbeds for hybrid charging architectures spanning high-variability weather corridors.
India
The PLI scheme for advanced chemistry cells reduces input costs for assemblers targeting South Asian delivery pod contracts. BIS certification requirements for lithium-ion cell safety create incremental compliance burdens for exporters. Maharashtra's emerging EV component clusters attract solar e-bike battery pack assembly investments.
United States
North American commuter demand concentrates in premium carbon fiber solar roof rack configurations for suburban route profiles. EPA universal waste rules govern photovoltaic material disposal obligations for fleet operators. California's municipal procurement preferences for decarbonized last-mile logistics stimulate pilot deployments among regional delivery services.
Solar E-Bike Market Competitive Landscape
Global majors compete with regional champions across photovoltaic integration architectures and battery supply chain control. The vendor base splits between scale-driven Asian assemblers leveraging captive cell production and European specialists commanding premium positioning through carbon fiber solar mounting systems. Three archetypes dominate: vertically integrated battery producers, modular solar component specialists, and premium frame-integrated system engineers. Competitive moves concentrate on backward integration into photovoltaic wafer supply and geographic expansion through localized assembly investments.
Among Taiwan-based manufacturers, Giant Manufacturing Co. Ltd. exemplifies captive assembly line control over solar module-to-frame integration quality. Chinese producers Yadea Group Holdings Ltd. and specialized component engineers like Specialized Bicycle Components, Inc. occupy distinct tier positions—Yadea through upstream battery cell ownership and Specialized through premium carbon fiber solar roof rack engineering for North American commuter routes. These three anchors represent divergent strategic bets on cost compression versus performance differentiation.
| Leading Market Players |
|---|
| Yamaha Motor Company |
| Pedego Electric Bikes |
| Giant Manufacturing Co. Ltd. |
| Yadea Group Holdings Ltd. |
| Accell Group N.V. |
| Trek Bicycle Corporation |
| Merida Industry Co. Ltd |
| Hi Power Cycles |
| Specialized Bicycle Components, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap assemblers in Taiwan and Zhejiang province exercise disciplined pricing power through captive photovoltaic module assembly lines, while sovereign-backed battery producers in mainland China compress lithium-ion cell costs to capture fleet procurement volumes. This ownership bifurcation splits pricing discipline between premium carbon fiber commuter configurations and sub-$800 aluminum fleet units.
Pricing Analysis
Input-cost pass-through from lithium carbonate mining volatility in Chile and Australia compresses assembler margins unevenly across battery chemistry tiers. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber solar roof rack systems from aluminum frame-embedded configurations and basic plug-in alternatives. Pricing pressure stems from polysilicon wafer supply concentration in Xinjiang, with fleet operators exhibiting highest price sensitivity and North American commuters absorbing premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet buyer demand, while tiered distribution serves fragmented commuter retail. Photovoltaic wafer refining clusters in Xinjiang and Inner Mongolia, battery cell production in Jiangsu and Zhejiang, and aluminum extrusion capacity in Guangdong province anchor geographic supply concentration. Polysilicon supply draws from single-source vulnerability in western China, with distribution running through Shenzhen export hubs to European assembly partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's embedded carbon tariffs compound procurement urgency for decarbonized last-mile logistics, accelerating fleet renewal cycles beyond baseline replacement demand.
For Market Incumbents: Acquire photovoltaic wafer slicing capacity to secure polysilicon supply against Xinjiang concentration risk. Defensive consolidation demands backward integration into battery cell production and carbon fiber bonding technician certification networks to close aftermarket service gaps threatening premium commuter retention. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cells opens a window for South Asian fleet contract penetration at landed cost advantages. White-space targets include Maharashtra battery pack assembly and Dutch vehicle-to-grid integration pilots, with direct procurement team cultivation as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among modular solar component specialists lacking frame integration capabilities. Long-term viability over the medium-term projection horizon favors acquisition targets with captive GB standard certification and European assembly footprints. Monitor lithium carbonate futures contract backwardation as the inflection signal for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Wafer Backward Integration | Secures polysilicon supply against Xinjiang single-source vulnerability for tier-one assemblers. |
| GB Standard Certification Investment | Accelerates SAMR compliance timelines for integrated photovoltaic-battery-controller packages. |
| Carbon Fiber Bonding Technician Certification | Closes aftermarket service gaps for solar roof rack damage repair in premium commuter segments. |
| Vehicle-to-Grid Hardware Convergence | Unlocks bi-directional charging revenue streams from Dutch dynamic electricity pricing environments. |
| Direct Photovoltaic Supply Agreements | Displaces tiered distribution for Netherlands logistics operators negotiating separate solar cell contracts. |
Research Methodology
Direct dialogue with fleet procurement managers, photovoltaic module engineers, battery cell R&D directors, and municipal bike-sharing program operators grounded qualitative insights in operational reality. Secondary validation drew from SAMR GB standard filings, EU Green Deal tariff schedules, India's PLI scheme disclosures, and lithium carbonate mining output data from Chile and Australia. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates.
Segment-level outputs across battery chemistry, frame architecture, charging method, and end-user category fed into analytical framework spanning the projection horizon. CAGRs derived from regression against fleet electrification mandate adoption curves and solar irradiance-adjusted range extension coefficients. Perovskite-silicon tandem cell efficiency trajectories and embedded carbon tariff phase-in schedules served as industry-specific forecast inputs.
Revisions become necessary when lithium carbonate price volatility exceeds historical bands or when SAMR tightens electrical system interoperability requirements beyond current certification timelines. Forecasts reflect documented assumptions regarding polysilicon supply continuity and fleet procurement cycle compression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Electric Vehicle Control Unit Market