
 Russia Third-Party Logistics (3PL) Market | 2026-2036
Russia Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Third-Party Logistics (3PL) Market Insights
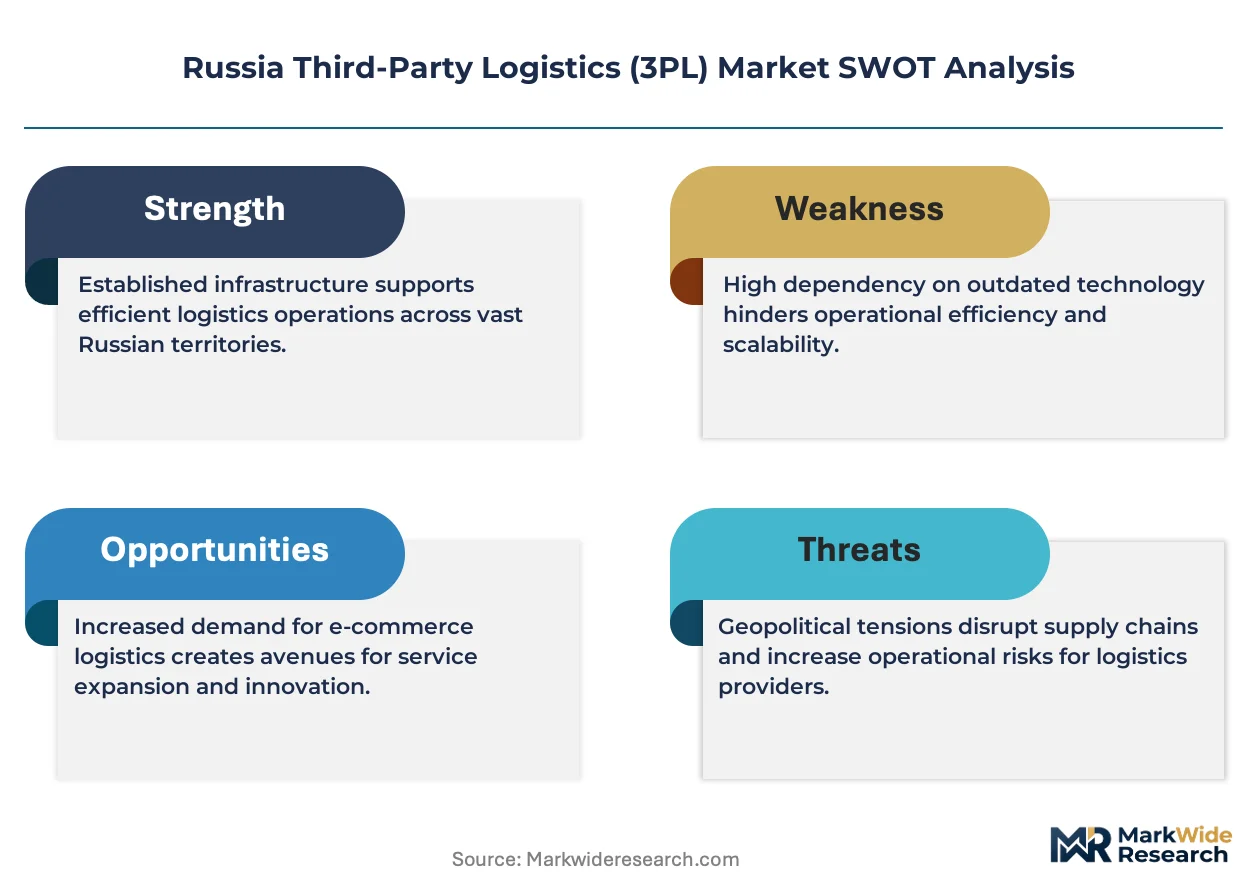
Sanctions compliance architecture is decoupling Western-owned 3PL assets from Russian operational control, forcing domestic capacity rebuilding. RZD Logistics leverages its rail network dominance to anchor intermodal freight corridors across the Eurasian landbridge. DHL Supply Chain sustains limited pharmaceutical cold-chain operations through third-country routing structures. Eurosib competes aggressively in eastbound container flows, while DB Schenker navigates contractual wind-downs without full asset liquidation.
Russia Third-Party Logistics denotes outsourced supply chain management where external providers assume responsibility for transportation, warehousing, inventory control, and freight forwarding under contracted service level agreements; these operations typically integrate warehouse management systems with route optimization algorithms to coordinate multi-modal cargo movements across vast territorial distances. The primary commercial purpose centers on reducing capital fixedness for shippers while achieving economies of scale in distribution density. Transportation and freight forwarding services occupy the largest revenue share given Russia's continental geography and sparse infrastructure nodes, though warehousing is gaining structural weight as e-commerce fulfillment demands multi-client deployment models with shorter delivery radii. Pharmaceutical end users represent a premium-margin segment where temperature-validated storage and serialization tracking create compliance barriers that filter out smaller operators.
Russia's Federal Customs Service and the Eurasian Economic Commission's technical regulations jointly determine cross-border clearance protocols and vehicle certification standards for international freight movements. The national transport regulator enforces driver hour limits and axle load restrictions that directly constrain fleet utilization rates and route economics. Stakeholders must monitor how sanctions-evasion enforcement in third jurisdictions reshapes permissible payment and insurance channels for Russian cargo flows.
Market Dynamics
Sanctions architecture is fragmenting Russia's 3PL infrastructure into parallel domestic and rerouted international systems, forcing asset restructuring and carrier substitution at every corridor node.
Growth Catalysts
- E-commerce fulfillment density:Ozon and Wildberries are consolidating last-mile networks around Moscow fulfillment centers, pulling warehouse investment into multi-client facilities with sub-24-hour delivery radii.
- Eurasian Economic Commission technical regulations:Unified customs procedures across Belarus, Kazakhstan, Armenia and Kyrgyzstan are compressing cross-border clearance times for consolidated freight.
- Pharmaceutical serialization mandates:Russia's national track-and-trace system for medicines is mandating temperature-validated 3PL partnerships that filter out uncertified warehouse operators.
Market Restraints
- Western insurance and payment channel exclusion:SWIFT restrictions and reinsurance withdrawal are forcing Russian freight operators into costly third-country correspondent banking structures.
- Railcar and container equipment shortages:Domestic production cannot replace sanctioned Western chassis and refrigerated units, constraining intermodal capacity expansion.
- Driver hour enforcement under Federal Transport Agency rules:Strict tachograph compliance is capping fleet utilization rates below theoretical maximums on long-haul corridors.
Strategic Opportunities
- Siberian and Far Eastern warehouse development:Underpenetrated regions east of the Urals offer first-mover positioning for cold-chain and bulk commodity storage serving Asian export routes.
- Digital freight platform integration:Convergence of telematics, warehouse management systems and blockchain documentation is enabling real-time cargo visibility across multi-modal chains.
- Import substitution manufacturing clusters:Relocated production from European Russia to Central Federal District industrial parks is generating contract logistics demand for inbound parts and outbound finished goods.
Industry Challenges
- Warehouse management system integration with legacy Soviet-era infrastructure:Many regional distribution centers lack automated sortation and real-time inventory tracking, requiring expensive retrofitting.
- Cold-chain qualification timelines:Pharmaceutical and food safety certifications from Russia's Federal Service for Surveillance in Healthcare demand 12-18 month validation periods that delay facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Third-Party Logistics (3PL) Market |
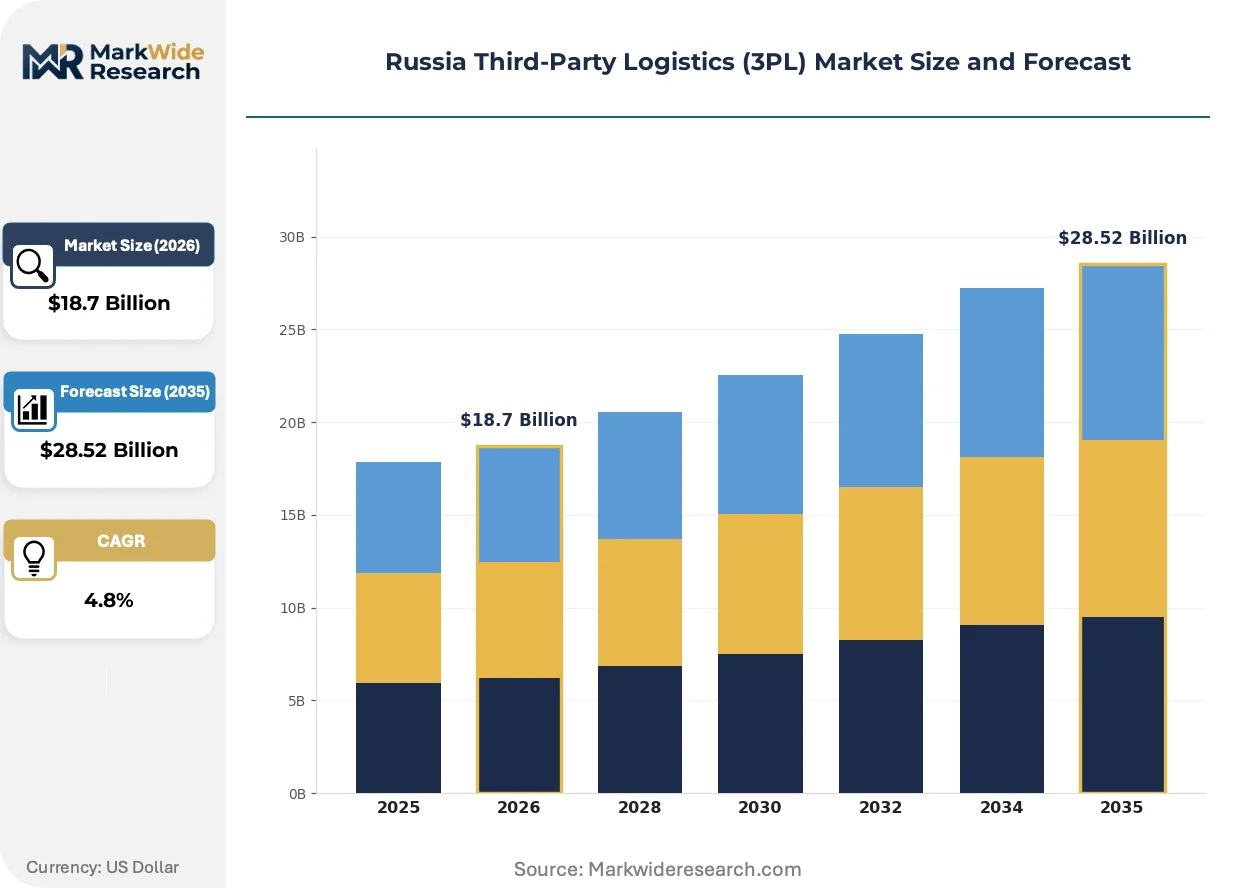
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding End User: Retail, Manufacturing, Automotive, Pharmaceuticals Deployment Model: Single Client, Multi-Client, Dedicated, Hybrid Technology: Warehouse Management Systems, Route Optimization, Tracking Systems, Inventory Management |
| Companies Covered | DHL Supply Chain, Kuehne + Nagel, DB Schenker, RZD Logistics, Eurosib, DP World, FM Logistics, Nienshants Logistics, STS Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Third-Party Logistics (3PL) Market Trends and Innovations
Digital infrastructure investment is outpacing physical asset expansion as Russian 3PL operators prioritize visibility software over warehouse square footage to maintain service continuity under sanctions pressure.
Autonomous mobile robotics is automating pallet movement and picking workflows in Moscow-region fulfillment centers. Ozon and Yandex Market are deploying AMR fleets at scale to offset labor scarcity in high-turnover warehouse roles. This automation is compressing order cycle times from dock-to-stock while reducing dependency on seasonal workforce surges.
Russia's Federal Customs Service is implementing risk-based inspection algorithms that pre-clear low-risk consignments while targeting higher-scored shipments for physical examination. The Eurasian Economic Commission's advance cargo information requirements are forcing freight forwarders to restructure documentation workflows. Pharmaceutical and electronics importers face the steepest compliance adaptation costs as serialization and origin-verification mandates tighten.
Shippers are unbundling transportation from warehousing contracts to maintain operational flexibility under volatile sanctions conditions. Large retail chains are fragmenting 3PL relationships across multiple domestic carriers rather than consolidating with single providers. This pattern is most pronounced in consumer electronics and automotive parts distribution, where buyers maintain parallel routing options through Central Asia and Caucasus corridor alternatives.
Russia Third-Party Logistics (3PL) Market Segmentation
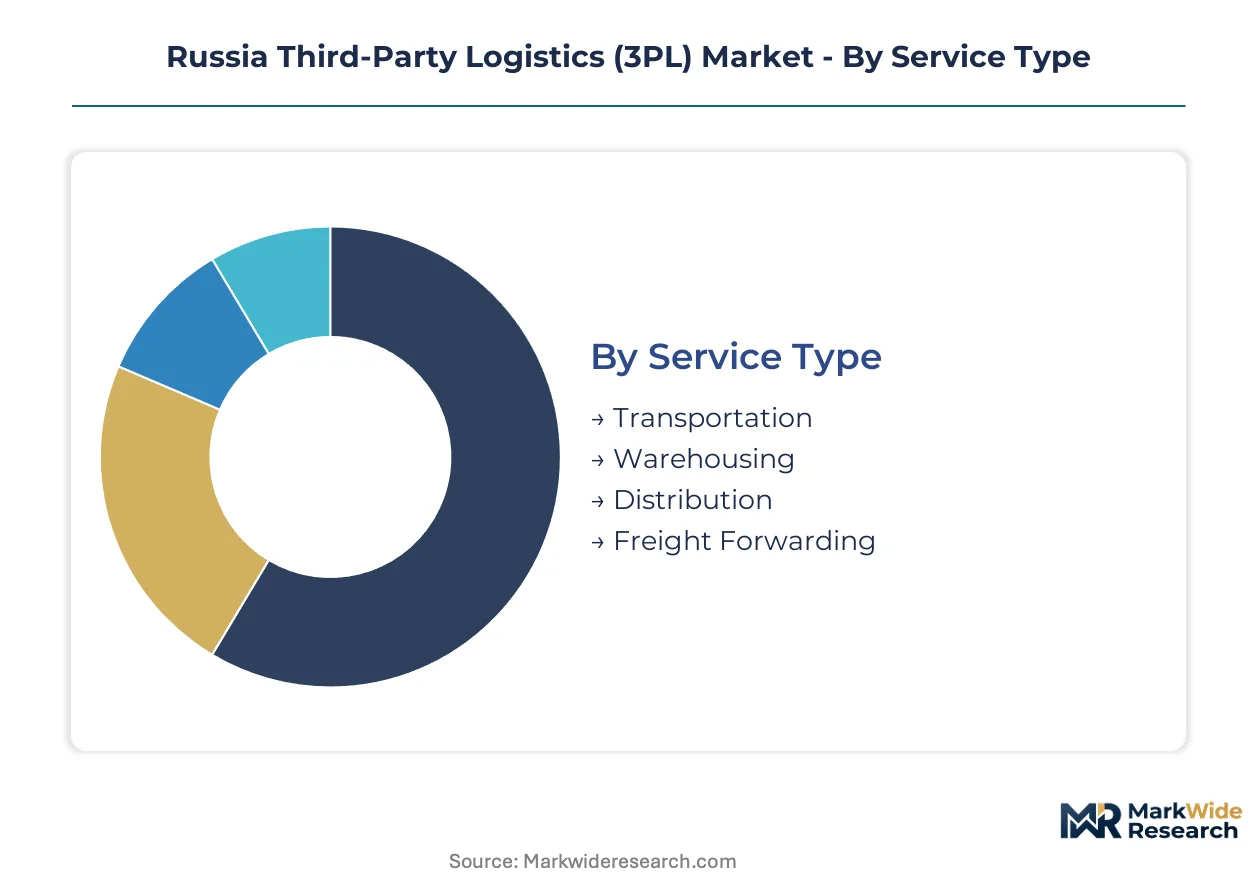
Russia's 3PL market fragments across service capabilities, end-user requirements, and technology sophistication levels. Each segmentation dimension reveals distinct competitive dynamics shaped by sanctions pressure and domestic capacity rebuilding.
Service Type:
Transportation services concentrate revenue in Russia's 3PL sector due to continental distances and sparse infrastructure nodes between industrial centers.
- Transportation:Road and rail freight movements dominate revenue given Russia's territorial scale. Demand clusters along the Moscow-St. Petersburg corridor and eastbound routes toward the Chinese border, where RZD Logistics anchors intermodal capacity.
- Warehousing:Multi-client fulfillment centers with automated sortation are gaining structural weight as Ozon and Wildberries consolidate last-mile networks around Moscow facilities with sub-24-hour delivery radii.
- Distribution:Last-mile delivery networks integrate cross-docking facilities with courier fleets. Regional operators compete on coverage density in the Central Federal District where consumer purchasing power concentrates.
- Freight Forwarding:Customs brokerage and documentation services face restructuring as Western operators withdraw and domestic players absorb cross-border volumes through third-country routing.
Today's leader: Transportation. Tomorrow's challenger: Warehousing.
End User:
End-user segmentation reveals diverging margin profiles, with pharmaceutical and automotive clients demanding certified capabilities that filter out smaller operators.
- Retail:E-commerce fulfillment drives warehouse investment as marketplace operators outsource distribution networks. Ozon and Wildberries pull logistics spend toward multi-client facilities with automated picking workflows.
- Manufacturing:Import substitution production relocated to Central Federal District industrial parks generates contract logistics demand for inbound parts coordination and outbound finished goods distribution.
- Automotive:Just-in-sequence delivery requirements and serialization tracking create compliance barriers. Domestic assemblers maintain parallel supplier routing options through Central Asia corridor alternatives.
- Pharmaceuticals:Temperature-validated storage and Russia's national track-and-trace system mandate partnerships with certified 3PL operators. Federal Service for Surveillance in Healthcare validation periods extend 12-18 months.
Pharmaceuticals command premium pricing tiers. Retail offers volume scale expansion.
Deployment Model:
Deployment configuration determines capital intensity and operational flexibility under volatile sanctions conditions.
- Single Client:Dedicated facilities serve one shipper under long-term contracts. Automotive and pharmaceutical manufacturers favor this model for proprietary inventory control and compliance isolation.
- Multi-Client:Shared warehousing spreads fixed costs across shippers. E-commerce fulfillment centers deploy this model to achieve delivery density in Moscow-region corridors.
- Dedicated:Exclusive resource allocation for high-volume accounts. Large retail chains fragment relationships across multiple domestic carriers rather than consolidating with single providers.
- Hybrid:Mixed structures combining dedicated transportation with shared warehousing. Shippers unbundle contracts to maintain routing flexibility through Central Asia and Caucasus alternatives.
Multi-client models scale fastest. Dedicated structures defend margin stability.
Technology:
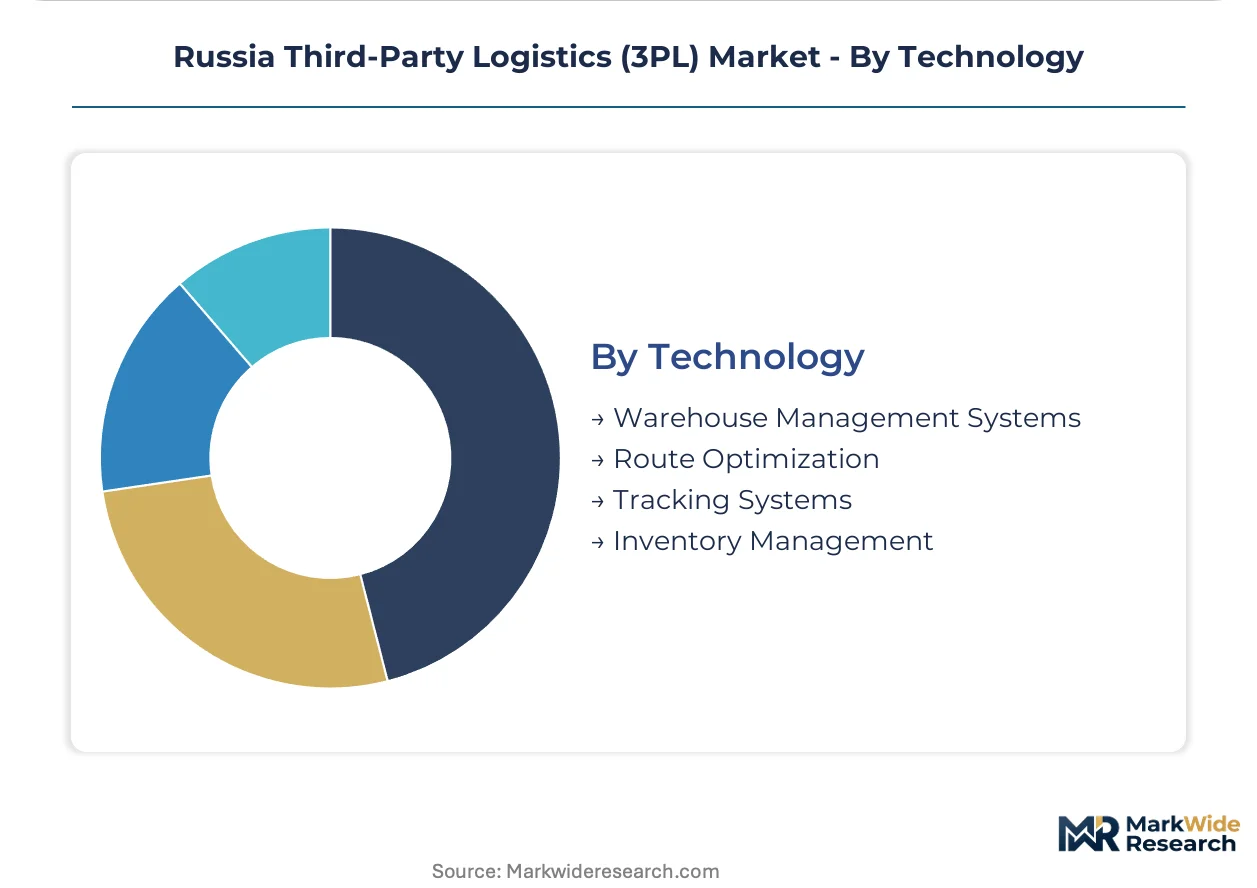
Technology segmentation tracks digital infrastructure investment priorities as operators prioritize visibility software over physical asset expansion.
- Warehouse Management Systems:Real-time inventory tracking and automated sortation integration. Many regional distribution centers require expensive retrofitting of legacy Soviet-era infrastructure.
- Route Optimization:Algorithmic load consolidation and dynamic routing adjustments. Federal Transport Agency tachograph compliance constrains theoretical fleet utilization on long-haul corridors.
- Tracking Systems:Telematics and blockchain documentation enable cargo visibility across multi-modal chains. Convergence with customs risk-based inspection algorithms accelerates clearance workflows.
- Inventory Management:Demand forecasting and safety stock optimization. Pharmaceutical serialization mandates filter out uncertified warehouse operators lacking serialization tracking capabilities.
Warehouse Management Systems anchor current investment. Tracking Systems gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics talent concentrates disproportionately in Moscow and the Central Federal District, where transport corridor density and warehouse automation expertise anchor national 3PL capacity development.
Central Federal District
E-commerce fulfillment demand from Ozon and Wildberries drives multi-client warehouse construction around Moscow fulfillment centers with sub-24-hour delivery radii. The Federal Customs Service enforces advance cargo information requirements that compress clearance timelines for consolidated freight. The Moscow-St. Petersburg transport corridor anchors intermodal rail-road terminals where RZD Logistics maintains dominant positioning.
Volga Federal District
Automotive manufacturing clusters in Tatarstan and Samara Oblast generate contract logistics demand for just-in-sequence parts delivery to domestic assembly plants. Federal Transport Agency tachograph compliance rules cap fleet utilization on long-haul routes connecting the region to Central Russia. Kazan and Nizhny Novgorod serve as distribution hubs for eastbound container flows toward the Chinese border.
Siberian Federal District
Bulk commodity export routes to Asian markets pull cold-chain and container storage investment into Novosibirsk and Krasnoyarsk logistics parks. Eurasian Economic Commission technical regulations standardize customs procedures across Kazakhstan border crossings. The Trans-Siberian Railway corridor anchors intermodal terminals where domestic operators replace sanctioned Western chassis capacity.
Far Eastern Federal District
Port congestion at Vladivostok and Vostochny drives demand for bonded warehousing and customs brokerage services handling rerouted container traffic. Russia's Federal Service for Surveillance in Healthcare mandates 12-18 month validation periods for pharmaceutical storage facilities that filter out uncertified operators. The Primorsky Krai region offers first-mover positioning for temperature-controlled storage serving Asian export markets.
Northwestern Federal District
St. Petersburg's Baltic Sea port infrastructure handles diversified cargo flows as shippers unbundle transportation from warehousing contracts to maintain routing flexibility. The Eurasian Economic Commission's unified vehicle certification standards constrain cross-border fleet interoperability with European Union member states. The region's industrial parks generate inbound parts coordination demand for import substitution manufacturing relocated from European Russia.
Russia Third-Party Logistics (3PL) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Russia's fragmented 3PL infrastructure, where sanctions-induced asset restructuring has decoupled Western-owned operations from domestic control. Market structure tilts toward rail-anchored intermodal operators and e-commerce-integrated fulfillment platforms rather than traditional freight forwarding networks. Three archetypes dominate: state-linked rail logistics entities, marketplace-captive fulfillment operators, and rerouted international providers maintaining limited pharmaceutical cold-chain presence. Capacity expansion through domestic equipment substitution and multi-client warehouse development represents the dominant competitive trajectory, while strategic partnerships with Central Asian corridor operators enable third-country routing continuity.
Among internationally originated providers maintaining limited Russian operational footprints, DHL Supply Chain and Kuehne + Nagel exemplify the rerouted pharmaceutical cold-chain archetype through third-country banking and insurance structures. RZD Logistics anchors the state-linked rail dominance model, leveraging its network control across Eurasian landbridge corridors. These three entities occupy distinct positioning tiers: the international limited-presence segment, the domestic rail-anchored infrastructure layer, and the emerging marketplace-integrated fulfillment tier where Ozon and Wildberries drive captive capacity development.
| Leading Market Players |
|---|
| DHL Supply Chain |
| Kuehne + Nagel |
| DB Schenker |
| RZD Logistics |
| Eurosib |
| DP World |
| FM Logistics |
| Nienshants Logistics |
| STS Logistics |
| Others |
Pricing and Supply Chain Analysis
E-commerce fulfillment mandates from Ozon and Wildberries are compressing delivery radii and forcing warehouse operators toward multi-client automation investments that reshape cost recovery models across Moscow-region facilities.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture as shippers fragment contracts across transportation and warehousing to preserve routing flexibility. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and geographic delivery cost. Cost compression in standard tiers intensifies because domestic equipment substitution raises capital recovery burdens. Retail e-commerce buyers exhibit highest price sensitivity while pharmaceutical manufacturers accept premium tiers for temperature-validated compliance.
Supply Chain Analysis
Railcar and container equipment supply rests on domestic Russian manufacturers and Chinese producers as Western chassis sources remain sanctioned. Critical inputs include refrigerated units, intermodal containers, and telematics hardware. Single-source vulnerability concentrates in specialized cold-chain equipment where domestic production lags certification requirements. Distribution runs through RZD Logistics rail terminals and fragmented road carrier networks with Moscow-region cross-docking facilities anchoring downstream flow consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's 3PL market functions as a stable compounder anchored by irreversible e-commerce fulfillment outsourcing that locks in multi-year warehouse demand regardless of macro volatility.
For Market Incumbents: Acquire automated sortation assets in Moscow-region fulfillment centers to defend density advantages against emerging regional challengers. Backward integration into domestic railcar leasing pools offsets equipment shortage risks from sanctioned Western suppliers. Secure Federal Service for Surveillance in Healthcare certifications ahead of pharmaceutical serialization mandate expansion. For New Entrants and Emerging Players: Siberian bulk commodity exporters represent an underserved buyer archetype lacking temperature-controlled storage infrastructure for Asian export routes. Cold-chain qualification in Novosibirsk and Krasnoyarsk logistics parks captures first-mover positioning before RZD Logistics extends dedicated capacity. Partner with Kazakhstan-based freight forwarders to offer seamless Eurasian Economic Commission customs clearance as a bundled value proposition. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic rail-anchored operators controlling intermodal terminal access across the Trans-Siberian corridor. Long-term viability hinges on equipment localization progress and Central Asian corridor routing continuity. Watch for Federal Transport Agency enforcement intensity on driver hour limits as a fleet utilization inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Client Warehouse Automation | Ozon and Wildberries consolidation drives automated picking investment to compress dock-to-stock cycle times. |
| Domestic Railcar Fleet Expansion | RZD Logistics equipment substitution reduces dependency on sanctioned Western refrigerated chassis suppliers. |
| Pharmaceutical Cold-Chain Certification | Federal Service for Surveillance in Healthcare validation filters out uncertified competitors in premium-margin storage. |
| Central Asian Corridor Partnership | Eurasian Economic Commission unified customs procedures enable third-country routing continuity for international freight. |
| Digital Freight Platform Integration | Telematics and blockchain documentation convergence supports real-time visibility across fragmented multi-modal chains. |
Research Methodology
Direct dialogue with logistics operations directors, e-commerce supply chain managers, rail terminal planners, and customs brokerage executives grounded qualitative findings in operational reality. Secondary validation drew from Federal Customs Service regulatory filings, RZD Logistics capacity disclosures, Eurasian Economic Commission technical regulation updates, and trade flow databases. Bottom-up facility-level capacity assessments triangulated against top-down national freight volume estimates to anchor projection integrity.
Bottom-up modeling of warehouse square footage, railcar fleet capacity, and cross-border throughput volumes converged with top-down national logistics spend estimates across the projection horizon. Segmentation dimensions included service type, end-user industry, deployment model, and technology sophistication tier. CAGRs were derived from fitted trend extrapolation adjusted for sanctions-induced supply constraints. Forecast inputs incorporated e-commerce fulfillment density curves and pharmaceutical serialization compliance timelines.
Underlying measurement precision varies by segment; transportation and warehousing services carry tighter precision than emerging digital freight platforms where adoption curves remain uncertain. Forecasts reflect documented assumptions about equipment localization progress and corridor routing stability. Sanctions enforcement intensity in third jurisdictions and Federal Transport Agency regulatory adjustments constitute primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Brazil 3PL Market