
 Turkey Courier Express and Parcel (CEP) Market | 2026-2036
Turkey Courier Express and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Courier Express and Parcel (CEP) Market Insights
Recycled corrugated fiber is decoupling last-mile packaging economics from virgin pulp price volatility across Turkish CEP operations. Aras Kargo sustains competitive density through its franchise network spanning Anatolian secondary cities. MNG Kargo differentiates via temperature-controlled pharmaceutical logistics, a niche where regulatory compliance creates service premiums. HepsiJet leverages its captive e-commerce traffic from Hepsiburada to occupy Istanbul's same-day corridor with dedicated rider fleets.
Courier Express and Parcel services constitute integrated logistics solutions encompassing pickup, sortation, line-haul transport, and last-mile delivery of documents and merchandise within defined time windows, typically measured through service-level agreements specifying delivery commitments between four and seventy-two hours. The sector's primary commercial purpose centers on enabling time-definite inventory movement for retailers, manufacturers, and individual consignors operating within Turkey's $100 billion-plus e-commerce ecosystem. Same-day and next-day delivery modes command premium rate structures while absorbing disproportionate operational investment in urban micro-fulfillment nodes. E-commerce customer segments generate volume concentration that subsidizes network density, whereas enterprise accounts yield higher per-shipment margins through contracted lane commitments and integrated warehouse services.
Turkey's Ministry of Transport and Infrastructure oversees CEP operator licensing through postal service regulations that mandate nationwide coverage obligations and service quality benchmarks. The country's central bank, under the Banking Regulation and Supervision Agency framework, shapes digital payment penetration that directly enables cash-on-delivery decline and prepaid parcel growth. Stakeholders must monitor how customs automation investments at Kapikule and Habur border gates reshape cross-border parcel throughput economics relative to domestic lane profitability.
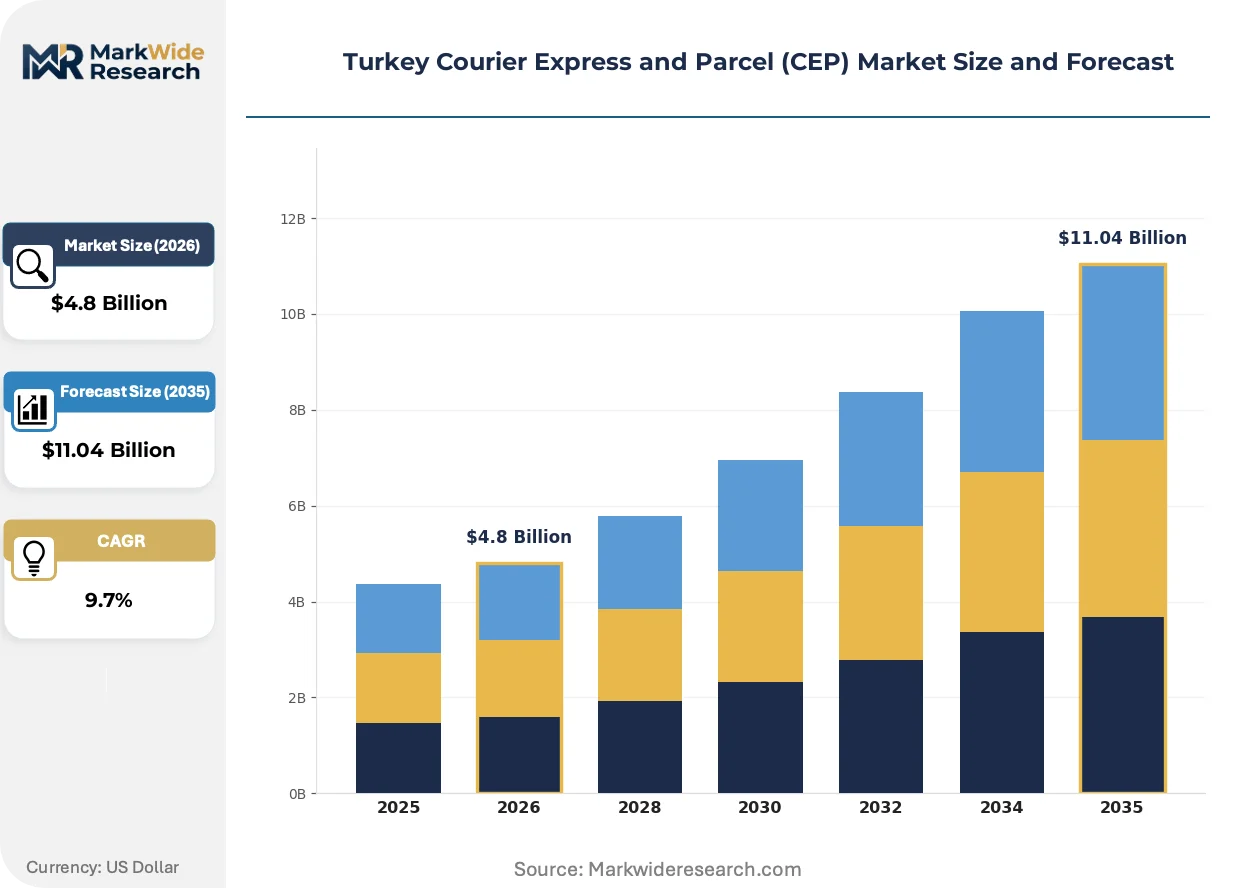
Market Dynamics
E-commerce parcel volumes in Istanbul and Ankara are compressing delivery windows while Turkey's customs modernization reforms at Kapikule and Habur border gates reshape cross-border throughput economics relative to domestic lane profitability.
Growth Catalysts
- Customs Automation:Turkey's Ministry of Transport and Infrastructure mandates nationwide coverage obligations that accelerate clearance velocity for cross-border e-commerce parcels entering through European gateway corridors.
- Digital Payment Penetration:The Banking Regulation and Supervision Agency framework enables cash-on-delivery decline, shifting merchant economics toward prepaid parcel models with lower failed-delivery rates.
- Marmara Region Density:Population concentration in Istanbul's metropolitan zone creates optimal last-mile unit economics for same-day and next-day service commitments.
Market Restraints
- Fuel Cost Volatility:Diesel price fluctuations directly compress margins on long-haul line-haul routes connecting Anatolian secondary cities to Marmara sortation hubs.
- Franchise Network Coordination:Asset-light expansion through third-party operators in eastern provinces creates service quality variance that complicates SLA standardization.
- Address Infrastructure Gaps:Incomplete postal coding in rural Anatolia forces manual sortation interventions that slow automated hub throughput.
Strategic Opportunities
- Temperature-Controlled Pharma:Regulatory compliance requirements for pharmaceutical cold chain create service premiums in a niche with contracted lane commitments and integrated warehouse services.
- Micro-Fulfillment Nodes:Urban real estate conversion in Istanbul's peripheral districts enables rider fleet densification for sub-two-hour delivery windows.
- Recycled Corrugated Fiber:Virgin pulp price volatility creates arbitrage for operators decoupling packaging economics through circular material sourcing.
Industry Challenges
- Rider Retention and Training:High turnover in Istanbul's gig delivery workforce forces continuous recruitment investment and erodes route-learning efficiency.
- Hub Automation Capex:Sortation robotics deployment requires capital commitments that strain mid-tier operators competing against integrated e-commerce captive fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Courier Express and Parcel (CEP) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same Day Delivery, Next Day Delivery, Scheduled Delivery, Standard Delivery Delivery Mode: Ground, Air, Maritime, Drone Customer Type: Individuals, Small Businesses, E-commerce, Enterprises Package Size: Small, Medium, Large, Oversized |
| Companies Covered | DHL Group, FedEx, Aras Kargo, MNG Kargo, HepsiJet, Yurtici Kargo, United Parcel Service, Ekol Logistics, PTT Kargo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Courier Express and Parcel (CEP) Market Trends and Innovations
Delivery network architecture is fragmenting toward distributed fulfillment models while regulatory pressure on packaging waste and customs transparency accelerates operational adaptation across Turkish CEP operations.
Dynamic route optimization algorithms using real-time traffic and demand signals are decentralizing dispatch authority from central hubs to zone-based rider fleet managers. Third-party logistics providers in Istanbul's same-day corridor adopt these systems to compress delivery windows without proportional vehicle count expansion. The structural consequence is decentralizing hub-and-spoke economics toward hyperlocal zone profitability.
Turkey's Ministry of Transport and Infrastructure postal service regulations now mandate service quality benchmarks with public reporting requirements. This transparency obligation forces operators to invest in track-and-trace infrastructure that exceeds baseline customer expectations. Temperature-controlled pharmaceutical segments face the steepest compliance cost escalation as audit frequency intensifies.
Merchant procurement of delivery services is fragmenting from annual volume contracts toward modular service stacking. E-commerce platforms in Ankara and Izmir now unbundle same-day, next-day, and economy tiers across multiple providers rather than consolidating with single operators. This behavior shift is most visible in fashion and electronics verticals where delivery speed directly correlates with cart completion rates.
Turkey Courier Express and Parcel (CEP) Market Segmentation
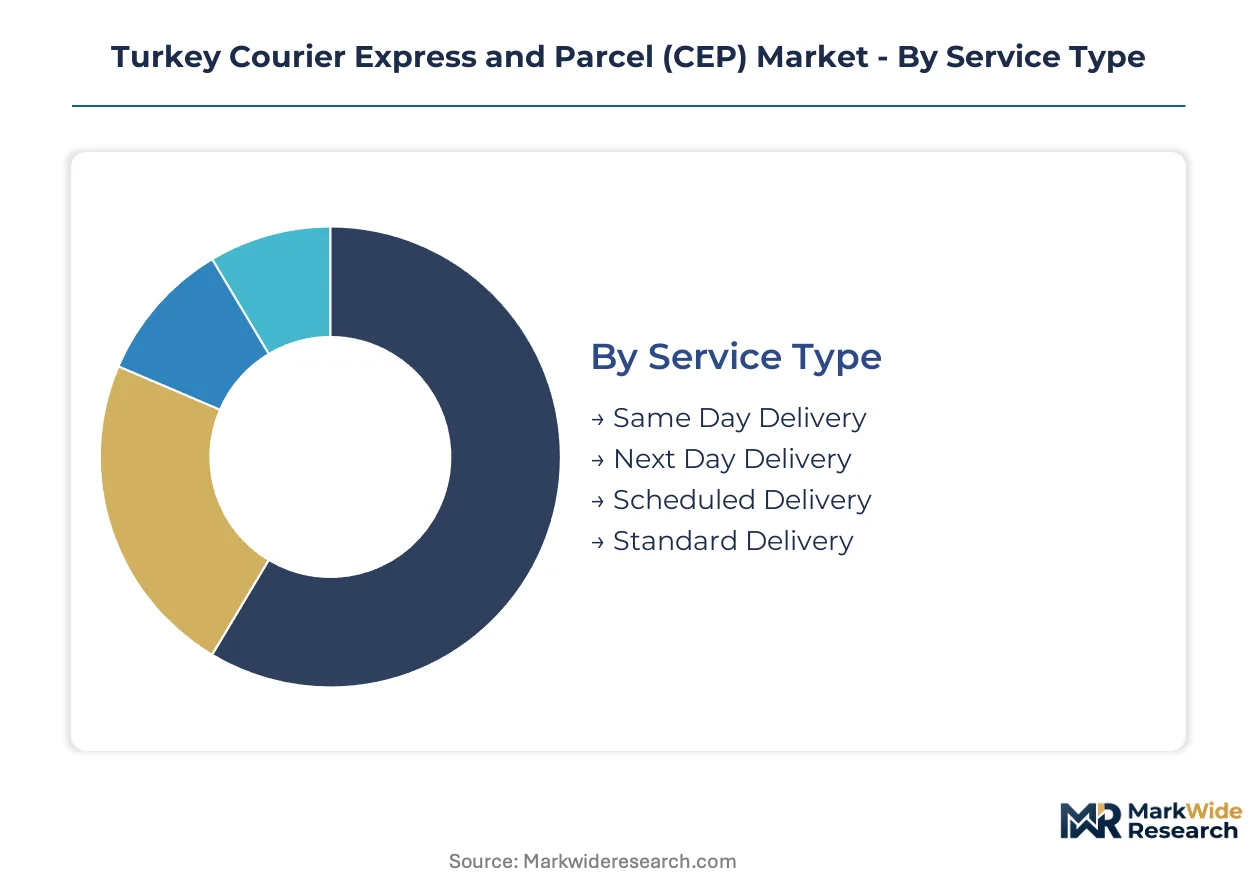
Turkey's CEP market fragments across service velocity tiers, transport infrastructure, customer scale, and parcel dimensions. Each segmentation axis reveals distinct margin structures and capital intensity requirements that shape operator portfolio strategy.
Service Type:
Standalone premium services command dedicated rider fleets and urban micro-fulfillment nodes, while embedded economy tiers leverage existing network density.
- Same Day Delivery:Sub-four-hour fulfillment windows require zone-based rider pooling and real-time dispatch algorithms. Istanbul's fashion and electronics merchants absorb premium pricing for cart completion optimization, though rider retention costs erode unit economics.
- Next Day Delivery:Overnight line-haul connections between Marmara sortation hubs and Anatolian cities balance speed with consolidated volume. Ankara-based e-commerce platforms anchor demand for this mid-tier velocity band.
- Scheduled Delivery:Appointment-based windows reduce failed-delivery rates for bulky goods requiring recipient presence. Appliance retailers in Izmir leverage this for white-glove installation coordination.
- Standard Delivery:Two-to-four-day windows maximize line-haul asset utilization across Turkey's east-west corridor. Rural Anatolian coverage obligations under postal regulations embed this tier in universal service mandates.
Volume placements concentrate in Standard Delivery; the faster expansion belongs to Same Day Delivery.
Delivery Mode:
Cost tier stratification separates capital-heavy air networks from asset-light ground operations, with emerging modalities disrupting last-mile economics.
- Ground:Diesel-powered fleet networks dominate domestic lane economics, connecting Istanbul's peripheral fulfillment zones to metropolitan micro-hubs. Fuel price volatility directly compresses margins on long-haul Anatolian routes.
- Air:Cargo belly capacity on Turkish carriers enables next-day coverage to eastern provinces unreachable by overnight road transport. Cross-border e-commerce parcels from European gateway corridors absorb premium air freight rates.
- Maritime:Roll-on/roll-on ferry services across the Marmara Sea and Aegean link Istanbul with Izmir and Bursa for non-urgent bulk movements. Automotive parts manufacturers exploit this for scheduled replenishment cycles.
- Drone:Regulatory frameworks under Turkey's Ministry of Transport and Infrastructure currently restrict beyond-visual-line-of-sight operations to pilot zones. Island and mountainous terrain applications in the Aegean region await operational clearance.
Ground transport captures dominant volume share; air freight claims the steepest expansion trajectory.
Customer Type:
Application concentration varies sharply between individual consignors seeking convenience and enterprise accounts demanding integrated warehouse services.
- Individuals:Document and gift parcel volumes spike during Ramadan and year-end holidays, with cash-on-delivery persistence in eastern provinces.
- Small Businesses:Artisan and specialty food producers in Gaziantep and Bursa utilize scheduled delivery for perishable export consolidation.
- E-commerce:Hepsiburada and Trendyol captive traffic subsidizes network density through predictable daily volume commitments.
- Enterprises:Contracted lane commitments from automotive and pharmaceutical manufacturers yield higher per-shipment margins through integrated value-added services.
E-commerce platforms drive volume concentration; enterprise accounts deliver superior margin realization.
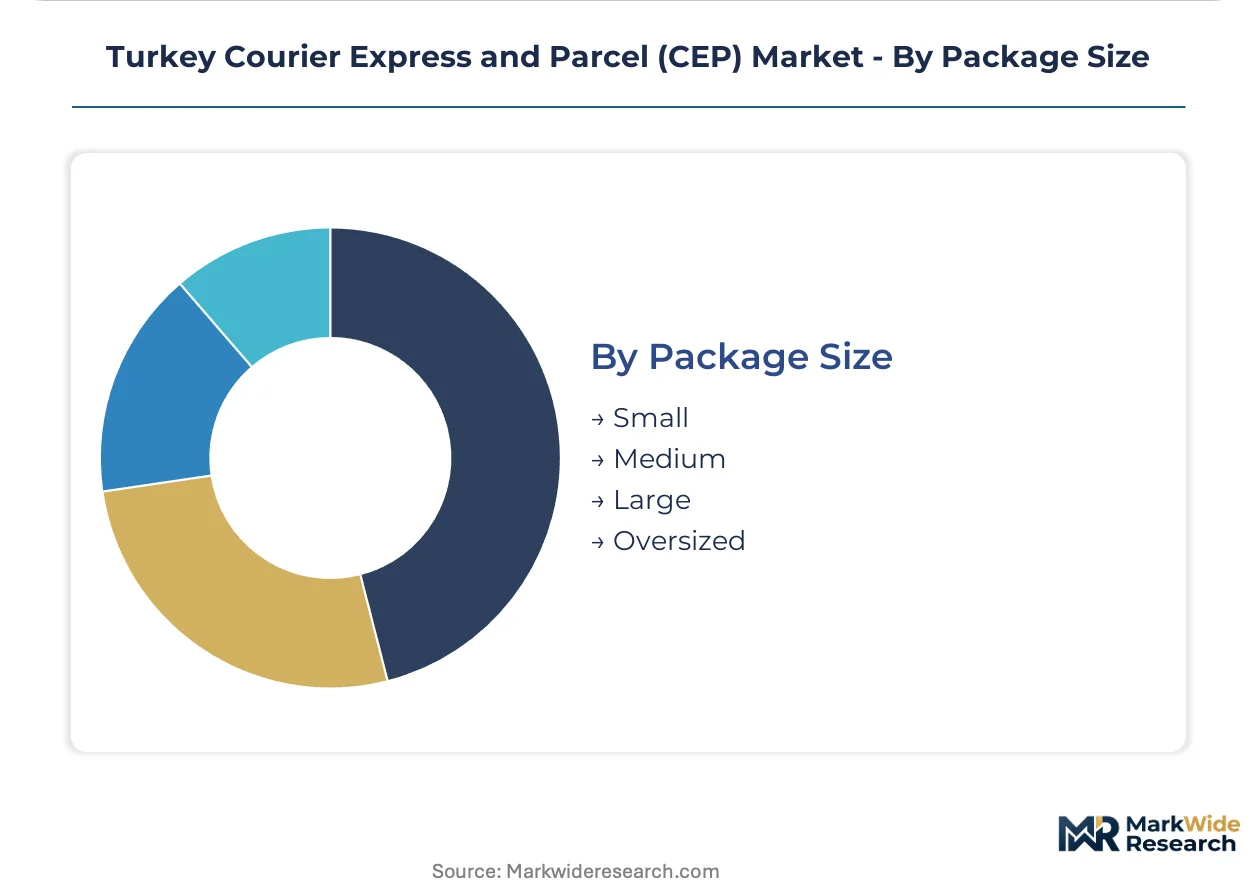
Package Size:
Handling infrastructure and vehicle fleet composition segment sharply by dimensional weight bands and sortation automation compatibility.
- Small:Smartphone-accessory and pharmaceutical parcels fit automated sortation infrastructure, enabling hub throughput maximization.
- Medium:Apparel and consumer electronics dominate Istanbul-Ankara corridor volumes, matching standard van cargo configurations.
- Large:Furniture and appliance deliveries require two-person crews and liftgate equipment, constraining route density.
- Oversized:Industrial machinery and construction materials bypass parcel hubs entirely, moving through dedicated less-than-truckload networks.
Medium parcels anchor daily volume; small-format e-commerce consignments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce parcel volumes concentrate in Turkey's Marmara region, where Istanbul's metropolitan density generates optimal last-mile unit economics for same-day and next-day service commitments.
Marmara Region
Fashion and electronics merchants in Istanbul absorb premium pricing for sub-four-hour fulfillment windows. Turkey's Ministry of Transport and Infrastructure mandates nationwide coverage obligations that accelerate network investment in peripheral districts. Micro-fulfillment nodes in Gebze and Tuzla enable rider fleet densification for compressed delivery commitments.
Central Anatolia
Ankara-based e-commerce platforms anchor demand for overnight line-haul connections to Marmara sortation hubs. The central bank's digital payment penetration frameworks enable cash-on-delivery decline in the capital corridor. Pharmaceutical logistics clusters in Sincan leverage temperature-controlled infrastructure for regulatory compliance premiums.
Aegean Region
Izmir's appliance retailers utilize scheduled delivery windows for white-glove installation coordination. Customs automation investments at Çeşme and Kuşadası ports reshape cross-border parcel throughput for specialty food exporters. Automotive parts manufacturers exploit roll-on/roll-on ferry services for scheduled replenishment cycles.
Mediterranean Region
Antalya's tourism-driven gift parcel volumes spike during seasonal peaks, with cash-on-delivery persistence in surrounding provinces. The Banking Regulation and Supervision Agency framework shifts merchant economics toward prepaid models in urban coastal zones. Perishable export consolidation from Alanya and Mersin utilizes scheduled delivery for European market access.
Southeastern Anatolia
Artisan producers in Gaziantep leverage scheduled delivery for specialty food export consolidation to Gulf markets. Address infrastructure gaps in rural provinces force manual sortation interventions that slow automated hub throughput. Franchise network expansion through third-party operators creates service quality variance in cross-border corridor economics.
Turkey Courier Express and Parcel (CEP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated e-commerce captives and independent logistics providers occupying distinct competitive tiers. The vendor base concentrates around three strategic archetypes: global integrators with cross-border infrastructure, domestic franchise networks with Anatolian density, and captive fleets serving single e-commerce platforms. Consolidation pressures favor operators with automated sortation capacity and pharmaceutical cold chain certification. M&A activity targets last-mile density in Istanbul's same-day corridor, while strategic partnerships secure micro-fulfillment real estate in peripheral districts.
Within the domestic franchise tier, Aras Kargo and MNG Kargo exemplify network-based competition through Anatolian secondary city coverage. HepsiJet occupies a position as the captive fleet archetype, leveraging dedicated rider infrastructure for Istanbul's premium velocity band. Global integrators DHL Group and FedEx anchor cross-border service premiums through European gateway corridor access.
| Leading Market Players |
|---|
| DHL Group |
| FedEx |
| Aras Kargo |
| MNG Kargo |
| HepsiJet |
| Yurtici Kargo |
| United Parcel Service |
| Ekol Logistics |
| PTT Kargo |
| Others |
Pricing and Supply Chain Analysis
E-commerce merchants in Istanbul and Ankara anchor demand concentration that forces three-tier pricing stratification across premium, standard, and economy service levels. Turkey's Ministry of Transport and Infrastructure mandates nationwide coverage obligations that embed cross-subsidization into rate structures, with urban density subsidizing rural delivery economics.
Pricing Analysis
Volume placements concentrate in standard delivery tiers while margin realization clusters in same-day and next-day commitments. Pricing stratifies across premium velocity, standard overnight, and economy deferred tiers based on service-level agreement stringency and zone-based density. Cost compression in long-haul Anatolian lanes is intensifying because diesel price volatility directly erodes line-haul margins. Small businesses and individual consignors in eastern provinces exhibit highest price sensitivity, whereas pharmaceutical enterprises absorb premium rates for temperature-controlled compliance.
Supply Chain Analysis
Turkey's postal service regulations mandating nationwide coverage reshape fleet asset deployment toward domestic manufacturing and local rider workforce development. Sortation robotics and last-mile vehicle fleets draw from Germany, China, and South Korea for automation hardware and electric drivetrain components. Single-source vulnerability concentrates in automated hub equipment where European suppliers dominate high-throughput sortation systems. Distribution feeds from Marmara fulfillment zones through overnight line-haul to Anatolian secondary cities, with franchise partners handling terminal delivery in peripheral provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Last-mile rider capacity constraints in Istanbul's same-day corridor prop pricing power for operators with dedicated fleet density. Hub automation bottlenecks limit throughput expansion for mid-tier competitors.
For Market Incumbents: Acquire automated sortation capacity in Marmara hub zones to defend against integrated e-commerce captive fleets. Secure pharmaceutical cold chain certification to capture regulatory compliance premiums in temperature-controlled logistics. Consolidate franchise network quality through direct operating partnerships in eastern Anatolian provinces where service variance erodes brand equity. For New Entrants and Emerging Players: Launch via scheduled delivery specialization for bulky goods requiring white-glove installation coordination in Izmir and Ankara corridors. Target pharmaceutical logistics niches where contracted lane commitments yield higher per-shipment margins than commodity parcel economics. Exploit micro-fulfillment real estate conversion in Istanbul's peripheral districts for sub-two-hour delivery windows. For Investors and Strategic Acquirers: The window for entry favors automated hub operators with pharmaceutical certification and last-mile density in the Marmara region. Mid-term viability hinges on consolidation plays capturing Istanbul's same-day corridor infrastructure. Monitor customs automation completion at Kapikule and Habur border gates as inflection indicator for cross-border parcel throughput economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Hub Deployment | Sortation robotics at Marmara facilities accelerate clearance velocity for e-commerce parcel volumes. |
| Pharmaceutical Cold Chain Certification | Temperature-controlled compliance creates service premiums in regulatory-audited logistics segments. |
| Micro-Fulfillment Node Expansion | Urban real estate conversion in Gebze and Tuzla enables rider fleet densification. |
| Franchise Network Consolidation | Direct operating partnerships in eastern provinces reduce service quality variance. |
| Cross-Border Customs Integration | Kapikule and Habur automation investments reshape European gateway corridor economics. |
Research Methodology
Trade customs databases, operator licensing records, and e-commerce platform disclosures formed the secondary backbone for volume and routing analysis. Primary interviews with logistics operations directors, franchise network managers, pharmaceutical supply chain leads, and Turkey's Ministry of Transport and Infrastructure officials validated service tier economics and regulatory compliance costs. Bottom-up parcel volume modeling and top-down market sizing triangulated across these inputs.
Historical trendline analysis of service velocity adoption and lane density metrics established baseline growth patterns across the projection horizon. The analytical framework segmented by delivery mode, customer type, package size, and regional corridor to isolate margin structures. CAGRs derived from volume elasticity models incorporating digital payment penetration and customs automation timelines. Forecast inputs included rider fleet expansion rates and automated hub deployment schedules.
The model assumes a particular technology adoption path for sortation automation and electric fleet conversion; alternative pathways for drone delivery regulatory clearance would alter the outlook for island and mountainous terrain applications. Forecasts reflect assumptions about customs modernization completion and fuel price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market