
 India Freight and Logistics Market | 2026-2036
India Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
India Freight and Logistics Market Foresight
Compressed natural gas is consolidating share in fleet economics across Indian road freight, displacing diesel in mid-mile operations. Delhivery leverages proprietary routing algorithms to sustain delivery density in tier-two cities. Transport Corporation of India anchors intermodal capacity through its rail-road container network. Blue Dart Express dominates time-definite air cargo between metropolitan distribution hubs.
India freight and logistics encompasses the physical movement, storage, and information management of goods across domestic and international supply chains, typically operating across temperature bands from ambient to controlled cold-chain environments between minus 25 and plus 25 degrees Celsius. Its primary purpose is to reduce inventory carrying costs while ensuring product integrity from origin to consumption. Road transportation leads service-type revenue due to last-mile indispensability, while warehousing commands margin concentration as automated fulfillment centers replace conventional godowns. E-commerce end-users represent the fastest-growing demand pool, outpacing traditional manufacturing offtake.
The Ministry of Road Transport and Highways mandates vehicle tracking and emission norms that reshape fleet procurement decisions across interstate corridors. BIS certification for logistics infrastructure equipment and the CEA's cold-chain standards determine market access for temperature-controlled service providers. RBI's trade finance regulations influence working capital structures for freight forwarders handling import-export documentation. Stakeholders must monitor how GST e-invoice integration with logistics platforms alters compliance costs and competitive differentiation.
Market Dynamics
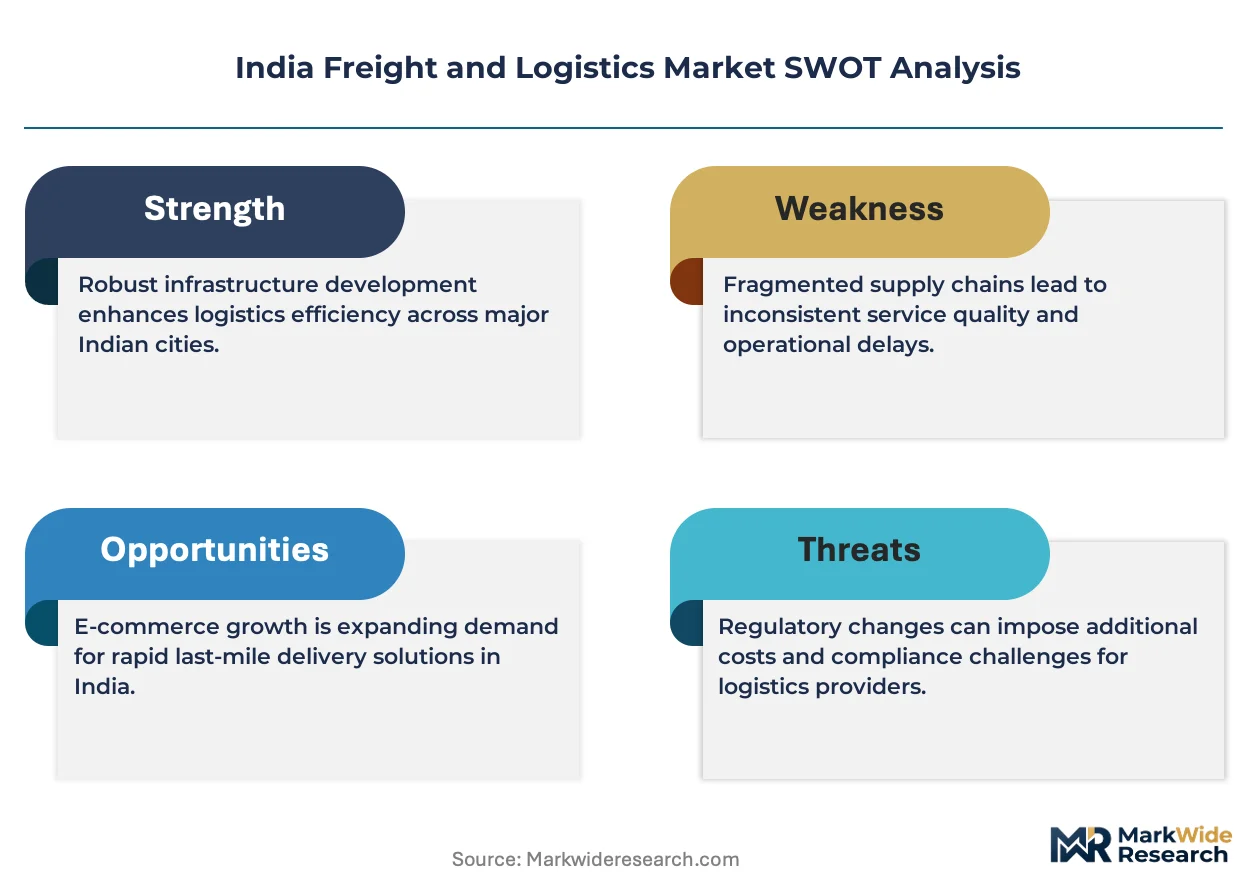
India's freight and logistics sector is undergoing structural compression as e-commerce fulfillment density forces asset-light network models to compete with capital-heavy infrastructure plays across tier-two and tier-three urban corridors.
Growth Catalysts
- PLI scheme for logistics infrastructure:The government's production-linked incentive framework accelerates cold-chain investments, drawing private capital into temperature-controlled warehousing and reefer fleet expansion.
- E-commerce fulfillment networks:Online retail platforms are driving last-mile delivery node proliferation, creating demand for micro-warehousing and hyperlocal distribution infrastructure.
- Maharashtra's Mumbai-Pune industrial corridor:Manufacturing concentration along this belt generates sustained freight volumes, anchoring intermodal rail-road terminal development and dedicated freight corridors.
Market Restraints
- Diesel price volatility:Fuel constitutes the largest variable cost component for road freight operators, compressing margins during upward price cycles and limiting fleet modernization.
- Land acquisition bottlenecks:Greenfield warehousing projects face multi-year clearance timelines across state jurisdictions, constraining automated fulfillment center rollout.
- Interstate permit fragmentation:State-level commercial vehicle taxation and entry regulations create compliance friction, elevating administrative overhead for national fleet operators.
Strategic Opportunities
- North-eastern hinterland connectivity:Underpenetrated Assam and Manipur corridors offer first-mover advantages for cold-chain operators serving agricultural export zones.
- GST e-invoice integration:Mandatory electronic invoicing linkage with logistics platforms creates compliance-as-a-service revenue streams for technology-enabled freight forwarders.
- Compressed natural gas fleet conversion:Convergence of CNG infrastructure rollout and emission norm tightening enables mid-mile operators to capture fuel cost arbitrage against diesel competitors.
Industry Challenges
- Telematics integration complexity:Fleet operators struggle to harmonize legacy vehicle tracking hardware with Ministry of Road Transport and Highways mandate specifications.
- Reefer technician scarcity:Temperature-controlled equipment maintenance requires specialized skill sets that vocational training pipelines have failed to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Freight and Logistics Market |
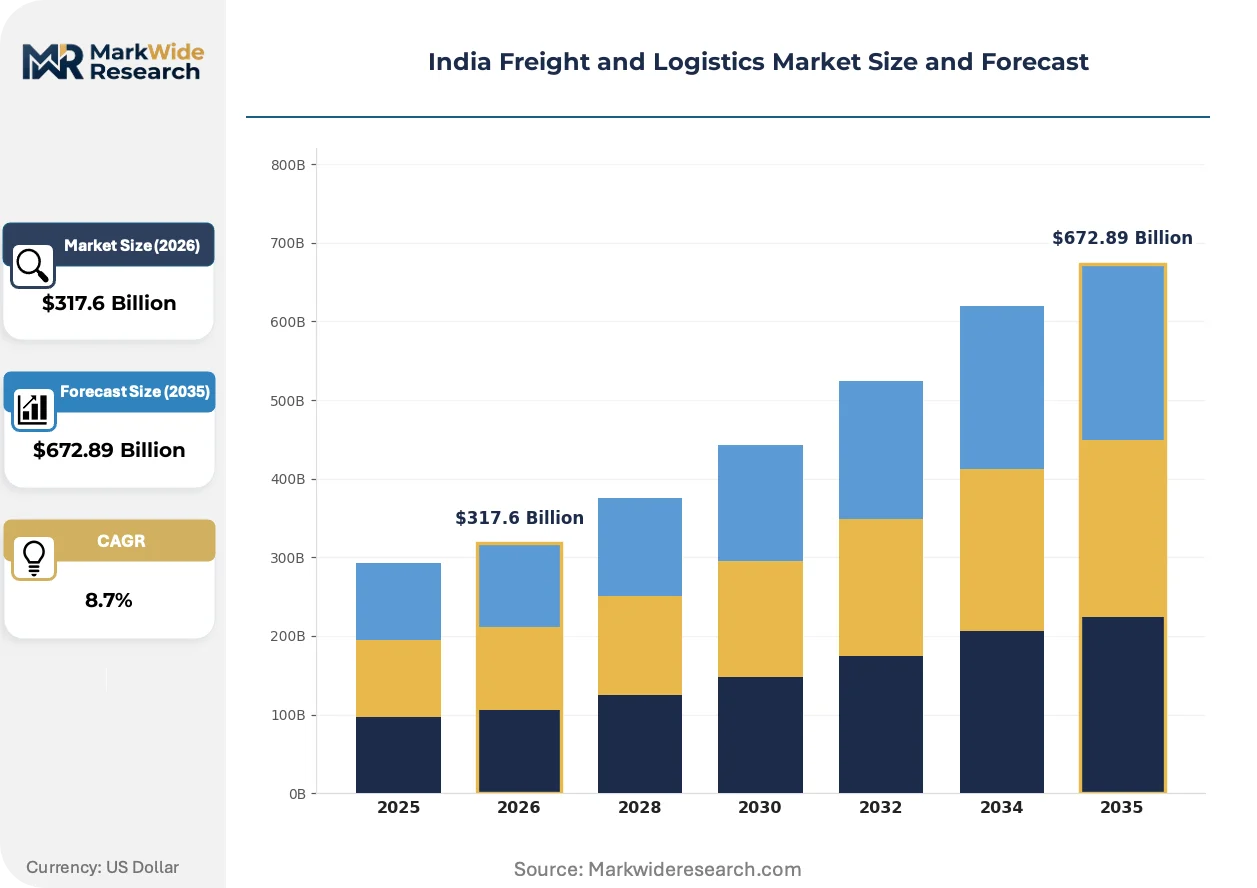
| Market Size in 2026 | $317.6 Billion |
| Market Size in 2035 | $672.89 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Value-Added Services, Freight Forwarding Mode: Road, Rail, Air, Sea End User: Manufacturing, Retail, E-Commerce, Agriculture Technology: IoT, AI, Blockchain, Automation |
| Companies Covered | Blue Dart Express, Transport Corporation of India (TCI), Delhivery, Gati Ltd, VRL Logistics, DTDC Express, Xpressbees, Container Corporation of India (CONCOR), Allcargo Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Freight and Logistics Market Shifts & Advancements
Digital freight matching platforms are rewiring how cargo owners contract capacity, collapsing traditional broker hierarchies while exposing latent truck utilization inefficiencies across India's fragmented carrier base.
Blockchain-enabled documentation is decentralizing trust architecture in multi-party supply chains. Exporters and customs brokers adopt distributed ledger systems to compress bill-of-lading verification cycles. The technology is decentralizing documentation authority away from centralized freight forwarders toward consignor-consignee direct verification.
BIS certification requirements for logistics infrastructure equipment are tightening quality benchmarks. The standards mandate structural load specifications for warehousing racking systems and material handling equipment. Temperature-controlled service providers face accelerated compliance timelines as CEA cold-chain standards integrate with FSSAI food safety protocols.
Shippers are consolidating vendor relationships around integrated logistics service providers capable of spanning first-mile collection through last-mile delivery. Traditional single-mode carriers lose share to operators offering unified road-rail-air quotes. Pharmaceutical and electronics manufacturers in Gujarat and Karnataka drive this consolidation most aggressively.
India Freight and Logistics Market Segmentation
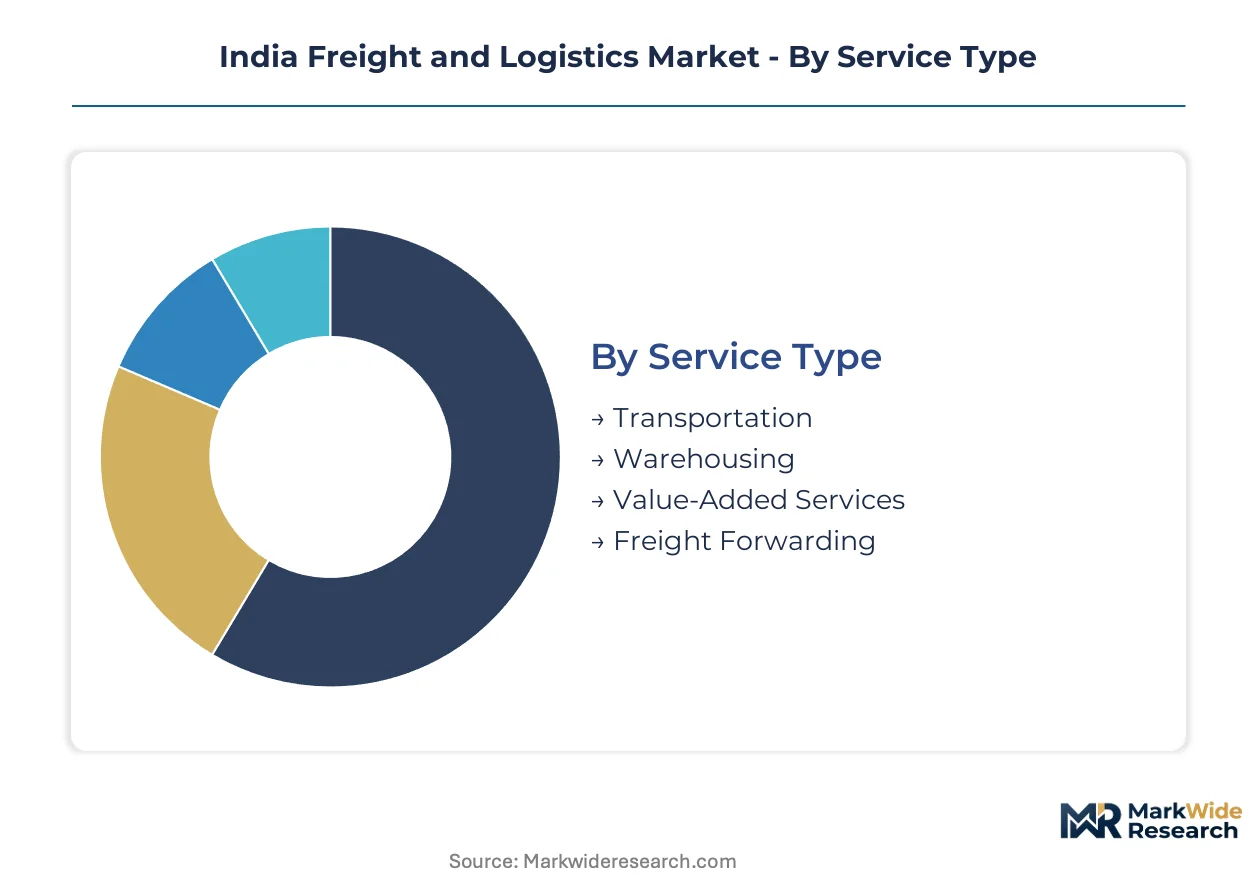
India freight and logistics segmentation reveals how service delivery models, infrastructure modes, and digital capabilities stratify competitive positioning across domestic supply chains. Understanding these divides exposes where capital deployment concentrates and where technology-enabled challengers displace conventional operators.
Service Type:
Technical sophistication and asset intensity differentiate service tiers, with automation penetration determining margin capture across fulfillment networks.
- Transportation:Fleet-based cargo movement spans owned and contracted vehicle networks, with CNG conversion and telematics integration reshaping cost structures. Road freight dominates Maharashtra's Mumbai-Pune corridor, though diesel price volatility compresses operator margins during upward cycles.
- Warehousing:Automated fulfillment centers with AS/RS systems and WMS platforms are displacing conventional godowns in tier-one cities. Land acquisition bottlenecks across state jurisdictions constrain greenfield rollout timelines for temperature-controlled facilities.
- Value-Added Services:Packaging, labeling, and quality inspection functions bundle with core logistics contracts. Pharmaceutical manufacturers in Gujarat drive demand for serialization-compliant kitting operations.
- Freight Forwarding:Documentation and customs brokerage services face compression from blockchain-enabled consignor-consignee direct verification. RBI trade finance regulations shape working capital structures for import-export handlers.
Transportation leads on scale; warehousing leads on momentum.
Mode:
Cost per ton-kilometer and delivery velocity requirements segment modal selection across industrial corridors.
- Road:Last-mile indispensability sustains revenue leadership despite fuel cost exposure. Delhivery's proprietary routing algorithms optimize delivery density in tier-two urban clusters.
- Rail:Dedicated freight corridors and containerization drive intermodal economics. Transport Corporation of India anchors capacity through rail-road terminal networks.
- Air:Time-definite cargo commands premium pricing between metropolitan distribution hubs. Temperature-sensitive pharmaceuticals and electronics sustain demand concentration.
- Sea:Coastal shipping and container terminals handle bulk commodity flows. Jawaharlal Nehru Port Trust volumes reflect manufacturing export intensity from western India.
Road maintains volume dominance; air captures the steepest expansion trajectory from e-commerce express requirements.
End User:
Inventory velocity requirements and fulfillment complexity stratify demand across sectoral value chains.
- Manufacturing:Just-in-time component delivery and inbound supply chain management dominate service specifications. Automotive clusters in Tamil Nadu and Haryana generate sustained freight volumes.
- Retail:Traditional distribution networks face disintermediation from direct-to-store replenishment models. Modern trade expansion drives cold-chain requirements for FMCG categories.
- E-Commerce:Same-day and next-day delivery promises force micro-warehousing node proliferation. Hyperlocal distribution infrastructure is expanding most quickly across tier-two and tier-three urban corridors.
- Agriculture:Perishable commodity movement requires temperature-controlled reefer capacity. PLI scheme incentives accelerate cold-chain investments for horticultural export zones.
Manufacturing anchors volume; e-commerce gains share fastest from fulfillment density imperatives.
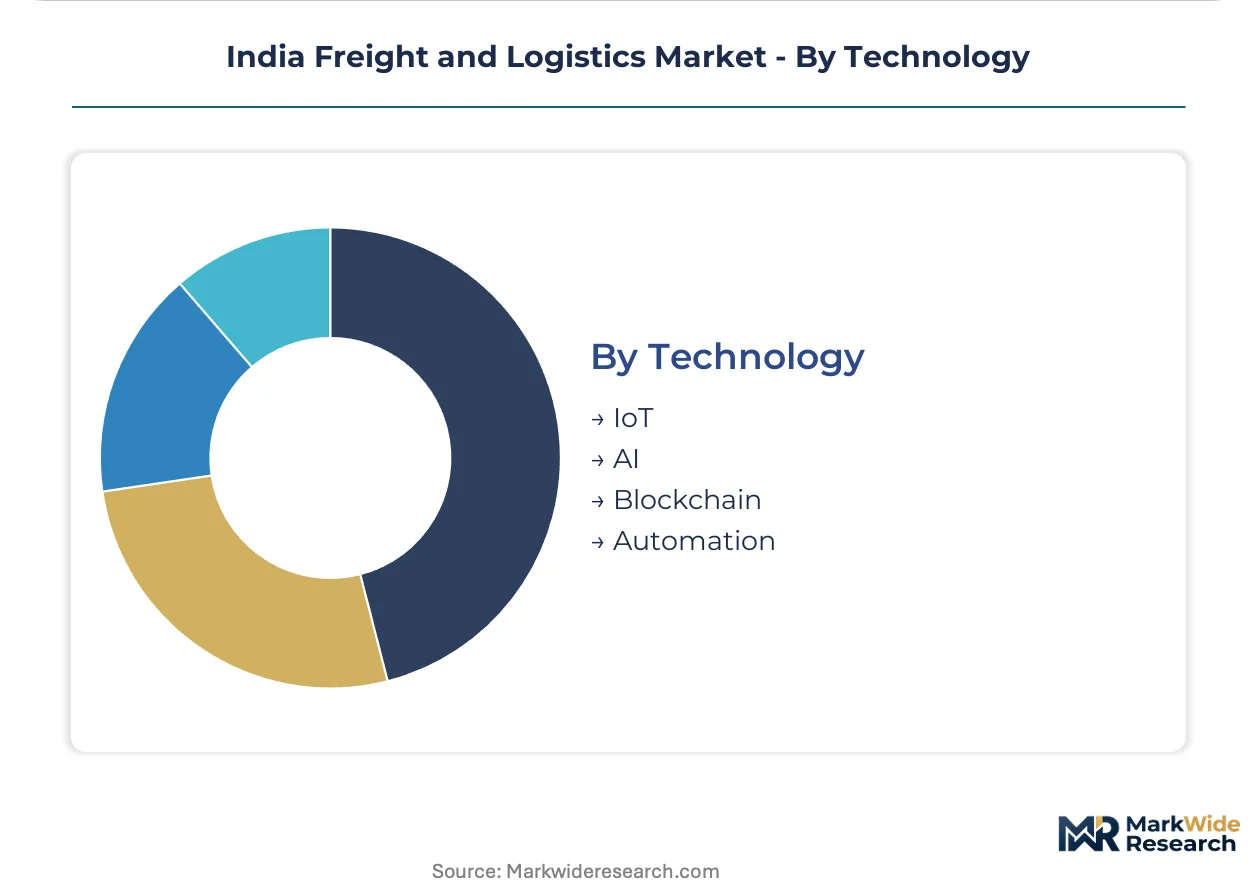
Technology:
Digital adoption maturity separates asset-heavy infrastructure plays from platform-enabled network orchestrators.
- IoT:Vehicle tracking and environmental sensors enable real-time cargo visibility. Ministry of Road Transport and Highways mandates reshape fleet procurement toward telematics-compliant hardware.
- AI:Predictive routing and demand forecasting algorithms optimize network utilization. Machine learning models compress empty-mile ratios across fragmented carrier bases.
- Blockchain:Distributed ledger systems decentralize documentation authority in multi-party supply chains. Bill-of-lading verification cycles compress through consignor-consignee direct validation.
- Automation:Robotics and autonomous systems penetrate sorting and material handling operations. BIS certification requirements tighten quality benchmarks for warehousing equipment.
IoT leads on deployment scale; AI leads on investment momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Mumbai-Pune industrial corridor anchors freight volume concentration, generating sustained demand for intermodal rail-road terminals and automated warehousing across western India.
Maharashtra
Automotive manufacturing clusters and pharmaceutical export zones drive temperature-controlled logistics demand. The state's industrial policy incentivizes multi-modal logistics parks along the Delhi-Mumbai Industrial Corridor. Mumbai-Pune Expressway freight density supports dedicated cold-chain infrastructure for FMCG distribution.
Gujarat
Petrochemical complexes and pharmaceutical formulation hubs generate bulk chemical and time-definite air cargo volumes. Gujarat Maritime Board regulations streamline port-centric logistics zone development. Mundra Port's container terminal expansion anchors coastal shipping integration with hinterland road networks.
Karnataka
Electronics manufacturing and e-commerce fulfillment centers concentrate around Bengaluru's Whitefield corridor. The state's EV policy mandates charging infrastructure at logistics parks, reshaping fleet procurement. Hoskote industrial area hosts automated sortation facilities serving same-day delivery networks.
Tamil Nadu
Automotive component clusters and textile export zones sustain high-velocity freight corridors. Tamil Nadu Industrial Development Corporation land allotment policies prioritize logistics park adjacency to manufacturing estates. Sriperumbudur-Oragadam belt concentrates contract logistics providers serving just-in-time assembly lines.
Telangana
Pharmaceutical bulk drug manufacturing and food processing units drive reefer capacity deployment. Telangana State Industrial Infrastructure Corporation develops pharma-specific logistics parks with ambient-to-frozen temperature bands. Shamshabad airport cargo terminal expansion supports temperature-sensitive pharmaceutical exports.
India Freight and Logistics Market Competitive Landscape
Global express majors compete with regional champions across last-mile density and intermodal integration. The market structures around three tiers: asset-heavy integrated operators, technology-enabled platform networks, and specialized single-mode carriers. Strategic archetypes include rail-road intermodal specialists, e-commerce-native fulfillment networks, and time-definite air cargo operators. Competitive moves concentrate on proprietary routing algorithm development and automated sortation infrastructure deployment.
Within the integrated logistics tier, Transport Corporation of India and Container Corporation of India represent capital-intensive infrastructure plays with rail-road terminal networks. Delhivery occupies a position exemplifying technology-native platform models that compress delivery density through machine learning-based route optimization. Blue Dart Express anchors the time-definite express segment, reflecting premium-service positioning across metropolitan distribution hubs.
| Leading Market Players |
|---|
| Blue Dart Express |
| Transport Corporation of India (TCI) |
| Delhivery |
| Gati Ltd |
| VRL Logistics |
| DTDC Express |
| Xpressbees |
| Container Corporation of India (CONCOR) |
| Allcargo Logistics |
| Others |
Supply & Pricing Matrix
E-commerce fulfillment platforms concentrate procurement power across tier-two and tier-three corridors, forcing contract-based long-term offtake structures with volume-scaled rebates over spot-market transactions. Diesel price volatility feeds directly into road freight rate negotiations, while PLI scheme subsidies compress cold-chain warehousing premiums in Maharashtra and Gujarat.
Pricing Analysis
Diesel and CNG cost pass-through dominates road freight pricing, with fuel surcharges adjusting monthly against benchmark price indices. Three-tier pricing structure across premium, standard, and economy levels separates time-definite air cargo from deferred rail-road intermodal and unscheduled spot trucking. Price differentiation hinges on delivery velocity guarantees and temperature-band certification under CEA cold-chain standards. Pricing pressure stems from telematics mandate compliance costs compressing fleet operator margins, with e-commerce platforms exhibiting highest price sensitivity due to fulfillment density imperatives.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for logistics infrastructure reshape sourcing toward Indian-manufactured reefer units and AS/RS warehousing equipment. Fleet asset procurement draws from domestic commercial vehicle assembly plants in Tamil Nadu and Maharashtra, while telematics hardware imports rest on Chinese and Taiwanese semiconductor supply chains. Single-source vulnerability concentrates in refrigerated compressor units sourced from German and Japanese OEMs. Distribution runs through hub-and-spoke networks anchored at Mumbai-Pune and Delhi-Mumbai Industrial Corridor nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India freight and logistics functions as a geographic-arbitrage play, with CNG infrastructure density gaps between western corridor states and north-eastern hinterlands creating 15-20% fuel cost differentials for mid-mile operators.
For Market Incumbents: Extend automated sortation capacity into Hoskote and Sriperumbudur corridors to capture e-commerce fulfillment density before platform-native challengers consolidate tier-two market share. Backward integration into captive CNG dispensing infrastructure at owned logistics parks defends margin position against diesel price volatility. Secure BIS certification for material handling equipment ahead of tightened quality benchmark enforcement. For New Entrants and Emerging Players: Cold-chain operators represent the most penetrable white-space target, with Assam and Manipur agricultural export zones offering first-mover advantages under PLI scheme incentives. Micro-warehousing node proliferation across tier-three urban corridors enables hyperlocal delivery network entry without competing against Delhivery's algorithmic density. Partner with state industrial development corporations for land-allocation priority in pharma-specific logistics parks. For Investors and Strategic Acquirers: E-commerce platforms and pharmaceutical manufacturers are the most active acquirers in this space, consolidating vendor relationships around integrated logistics service providers. Long-term viability centers on technology-enabled network orchestrators with proprietary routing algorithms and intermodal rail-road terminal access. Watch GST e-invoice integration penetration rates as the inflection signal for compliance-as-a-service revenue scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CNG Fleet Conversion | Captures fuel cost arbitrage against diesel competitors under tightening emission norms. |
| Automated Fulfillment Center Deployment | Displaces conventional godowns in tier-one cities with AS/RS and WMS platforms. |
| Rail-Road Intermodal Expansion | Anchors capacity through dedicated freight corridors along Mumbai-Pune belt. |
| Cold-Chain Infrastructure Investment | Accelerates reefer fleet expansion under PLI scheme temperature-controlled warehousing incentives. |
| Proprietary Routing Algorithm Development | Optimizes delivery density in tier-two urban clusters against fragmented carrier bases. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations managers, warehouse automation engineers, e-commerce supply chain directors, cold-chain compliance officers, and state logistics park developers with secondary validation. Bottom-up triangulation against customs records, Ministry of Road Transport and Highways vehicle registration databases, RBI trade finance disclosures, and BIS certification filings anchored volume estimates. Top-down cross-checks against PLI scheme disbursement data and state industrial policy documents refined segment allocations.
Segment-weighting approaches distributed value across service type, mode, end user, and technology dimensions, with transportation, warehousing, and value-added services receiving differential growth coefficients. Mode-specific ton-kilometer economics and delivery velocity premiums shaped modal share projections across the analysis window. CAGRs derived from logistic curve fitting against historical freight volume correlations with manufacturing PMI and e-commerce gross merchandise value trajectories. Forecast inputs incorporated diesel-CNG price spread scenarios and telematics mandate compliance timelines.
Revisions become necessary when fuel subsidy regimes shift, interstate permit fragmentation resolves through GST harmonization, or cold-chain technician training pipeline scaling accelerates. Forecasts reflect documented assumptions regarding PLI scheme continuity and dedicated freight corridor completion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Japan E-Commerce Logistics Market