
 United Arab Emirates Freight and Logistics Market | 2026-2036
United Arab Emirates Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Freight and Logistics Market Analytics
Software-defined freight visibility is shifting contract structures from per-shipment billing to subscription-based platform access. DP World leverages its port-to-door infrastructure to anchor integrated supply chain offerings across the Gulf. Aramex specializes in last-mile density across secondary UAE emirates, while Kuehne + Nagel competes through pharmaceutical cold-chain certification.
Freight and logistics encompasses the physical movement, storage, and information coordination of goods across multimodal networks, typically measured by ton-kilometers, dwell time, and order-fulfillment accuracy, serving as the operational backbone of trade-dependent economies. Road freight dominates intra-GCC volume due to flexible scheduling and border infrastructure investment, while air freight captures premium perishables and aerospace components through Dubai's cargo terminal capacity. E-tracking adoption within the technology dimension is accelerating fastest among 3PL providers seeking real-time customs pre-clearance.
MOHAP regulates pharmaceutical logistics standards for temperature integrity, while the UAE's customs authority enforces AEO certification for supply chain security compliance, collectively raising operational thresholds for cross-border operators. The country's NIS2-aligned cybersecurity framework for critical infrastructure extends to port operating systems and warehouse management platforms. Stakeholders must weigh localization requirements against scale economics as federal procurement rules tighten domestic content obligations.
Market Dynamics
Federal procurement rules under the National In-Country Value program are redirecting logistics spend toward domestic operators, compressing margins for foreign incumbents while elevating local 3PL capacity.
Growth Catalysts
- E-commerce fulfillment networks:Platform operators are expanding warehouse footprints across Dubai South and Abu Dhabi's KEZAD zones, creating sustained demand for bonded storage and last-mile density.
- MOHAP pharmaceutical standards:Temperature integrity mandates for biologics and vaccines are pulling investment into certified cold-chain infrastructure across the Emirates.
- Jebel Ali corridor concentration:DP World's port-to-door integration anchors multimodal throughput, drawing regional transshipment volume away from competing Gulf hubs.
Market Restraints
- Fuel cost volatility:Diesel price swings directly compress road freight margins, with no hedging mechanisms available to mid-tier fleet operators.
- Specialized asset concentration:Pharmaceutical cold-chain certification capacity clusters with three integrated providers, creating bottleneck risk for generic 3PL entrants.
- Skilled technician scarcity:Warehouse automation deployment outpaces training pipeline output for mechatronics and WMS integration specialists.
Strategic Opportunities
- Secondary emirate penetration:Ras Al Khaimah and Fujairah lack dedicated e-commerce fulfillment nodes, presenting first-mover advantage for platform-built distribution.
- Cybersecurity compliance services:NIS2-aligned port and warehouse system mandates create adjacent revenue streams for IT-integrated logistics providers.
- Subscription visibility platforms:Software-defined freight tracking is expanding into long-term contracts, displacing per-shipment billing across petrochemical and retail verticals.
Industry Challenges
- AEO certification timelines:UAE customs authority security compliance reviews stretch 14-18 months, delaying market entry for cross-border operators.
- Legacy WMS integration:Port operating system upgrades require synchronization with decade-old warehouse management platforms, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Freight and Logistics Market |
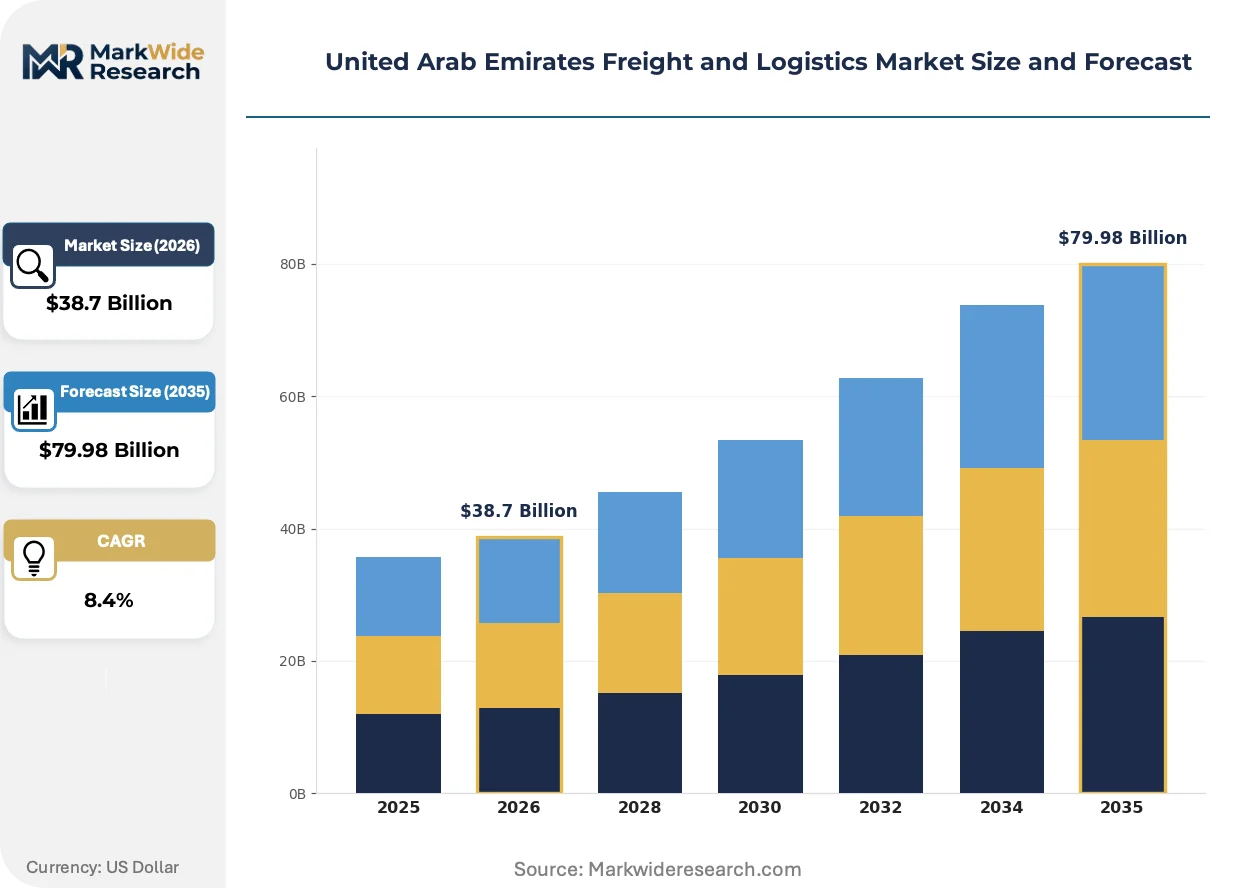
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Air Freight, Sea Freight, Rail Freight End User: Retail, Automotive, E-Commerce, Manufacturing Solution: 3PL, Supply Chain Management, Freight Forwarding, Last Mile Delivery Technology: E-Tracking, Warehouse Management System, IoT Solutions, Blockchain |
| Companies Covered | Al-Futtaim Logistics, Agility, DP World, Emirates Logistics, FedEx, Aramex, Kuehne + Nagel, GAC, DHL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Freight and Logistics Market Evolving Landscape
Digital freight platforms and regulatory compliance automation are compressing traditional brokerage functions while elevating real-time visibility to contract-critical status.
Blockchain-enabled documentation is expanding into trade finance and customs pre-clearance workflows. Major freight forwarders in the Emirates are piloting distributed ledger systems for bill-of-lading verification, cutting document processing from days to hours. This technology is expanding into letter-of-credit settlement, compressing working capital cycles for commodity traders.
MOHAP's pharmaceutical logistics standards now mandate continuous temperature monitoring with auditable data retention. Cold-chain operators must deploy IoT sensor networks with 99.9% uptime guarantees, raising technical barriers to biologics handling. Pharmaceutical distributors are responding by consolidating warehousing into purpose-built facilities in Dubai Healthcare City and Abu Dhabi's Masdar zone.
Subscription-based platform access is displacing transaction-based brokerage across enterprise shippers. Retail and automotive verticals now procure freight visibility as annual software licenses rather than per-container fees. This shift is most visible among Dubai-based trading houses managing high-frequency GCC cross-border movements.
United Arab Emirates Freight and Logistics Market Segmentation
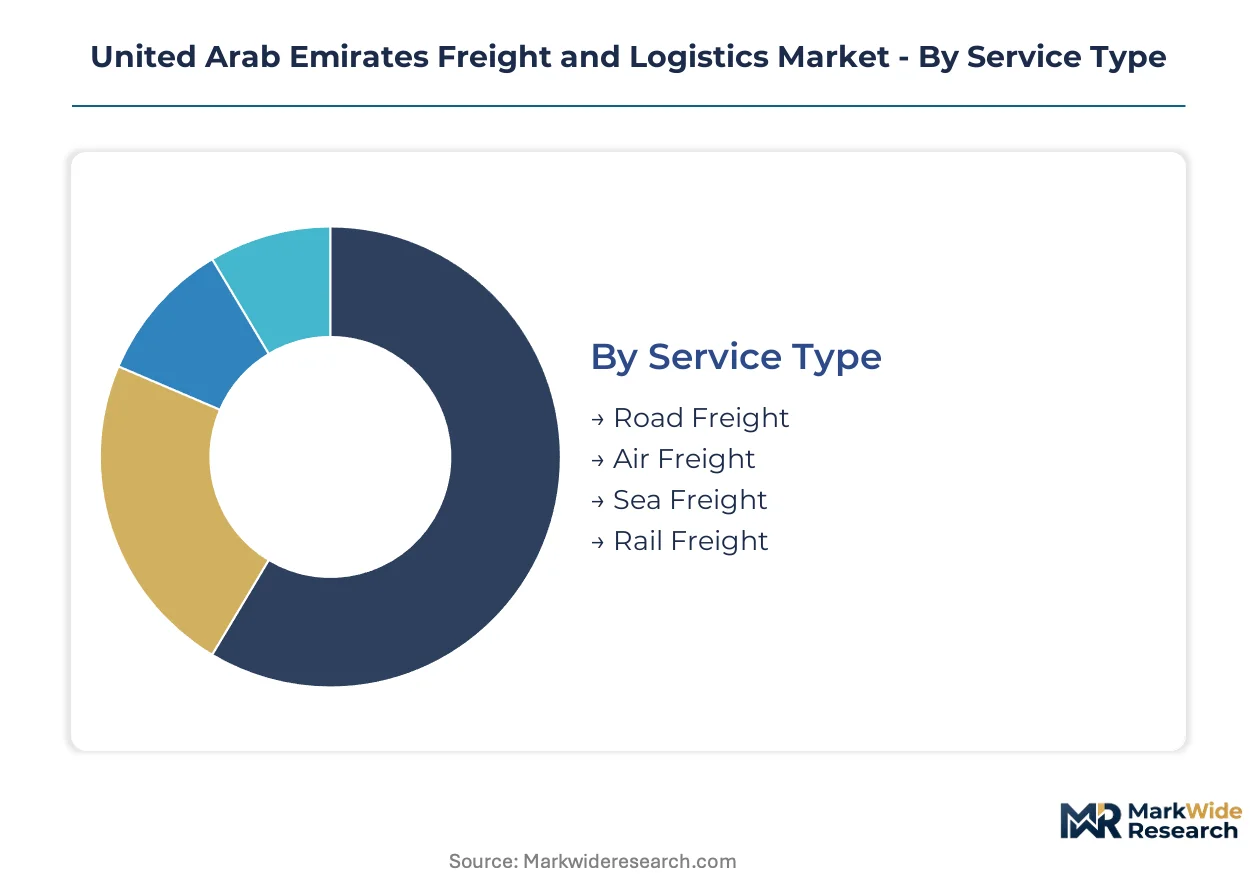
Segmentation across the Emirates reflects the tension between federal procurement localization and the specialized certification requirements of high-value verticals. Each dimension carries distinct regulatory and operational burdens that shape vendor selection and contract structures.
Service Type:
Road freight and air freight carry the heaviest compliance loads, with AEO certification and MOHAP pharmaceutical standards respectively governing operational access.
- Road Freight:Diesel-powered fleet operations dominate intra-GCC volume through flexible scheduling and border infrastructure investment. Demand concentrates in Dubai's Jebel Ali corridor and Abu Dhabi's Khalifa Industrial Zone, where last-mile density requirements from e-commerce platforms sustain margin recovery despite fuel cost volatility.
- Air Freight:Temperature-controlled cargo terminals at Dubai International capture premium perishables, aerospace components, and biologics requiring continuous cold-chain integrity. MOHAP mandates for pharmaceutical logistics pull investment into certified handling infrastructure, elevating technical barriers for generic operators.
- Sea Freight:Container throughput through Jebel Ali anchors regional transshipment volume, with DP World's port-to-door integration displacing competing Gulf hubs.
- Rail Freight:Etihad Rail network expansion connects industrial zones across the northern emirates, though last-mile road transfers remain necessary for final delivery.
Road freight sits at the top of the volume ranking, with air freight climbing the fastest on pharmaceutical and e-commerce premium demand.
End User:
Cost tier stratification separates capital-intensive manufacturing logistics from high-velocity retail and e-commerce fulfillment.
- Retail:Department store and hypermarket chains procure bonded storage and distribution through long-term 3PL contracts, with inventory velocity determining warehouse location strategy between Dubai South and Abu Dhabi's KEZAD zones.
- E-Commerce:Platform operators are expanding fulfillment networks across secondary emirates, creating sustained demand for same-day delivery density and returns processing infrastructure. Subscription-based visibility platforms now displace per-shipment billing across major trading houses.
- Automotive:Finished vehicle logistics and parts distribution require specialized handling equipment and dealer network synchronization, with Jebel Ali serving as the primary import gateway.
- Manufacturing:Just-in-time component delivery for industrial operations in KIZAD and Dubai Industrial City depends on synchronized multimodal scheduling with minimal safety stock.
E-commerce sits at the top of the volume ranking, with retail climbing fastest on post-pandemic omnichannel fulfillment requirements.
Solution:
Customer type divides between enterprise shippers seeking integrated control and mid-market operators purchasing modular capabilities.
- 3PL:Third-party logistics providers offer outsourced warehousing, transportation, and inventory management under multi-year contracts, with National In-Country Value procurement rules redirecting spend toward domestic operators.
- Freight Forwarding:International forwarders compete through customs brokerage expertise and carrier rate negotiation, with AEO certification timelines stretching 14-18 months for new market entrants.
- Supply Chain Management:End-to-end visibility and planning platforms integrate demand forecasting with inventory positioning, requiring WMS-TMS synchronization that inflates implementation costs.
- Last Mile Delivery:Dense courier networks across secondary emirates address final-leg fragmentation, with Aramex specializing in coverage gaps outside Dubai and Abu Dhabi metropolitan zones.
3PL sits at the top of the volume ranking, with supply chain management gaining share fastest on software-defined platform adoption.
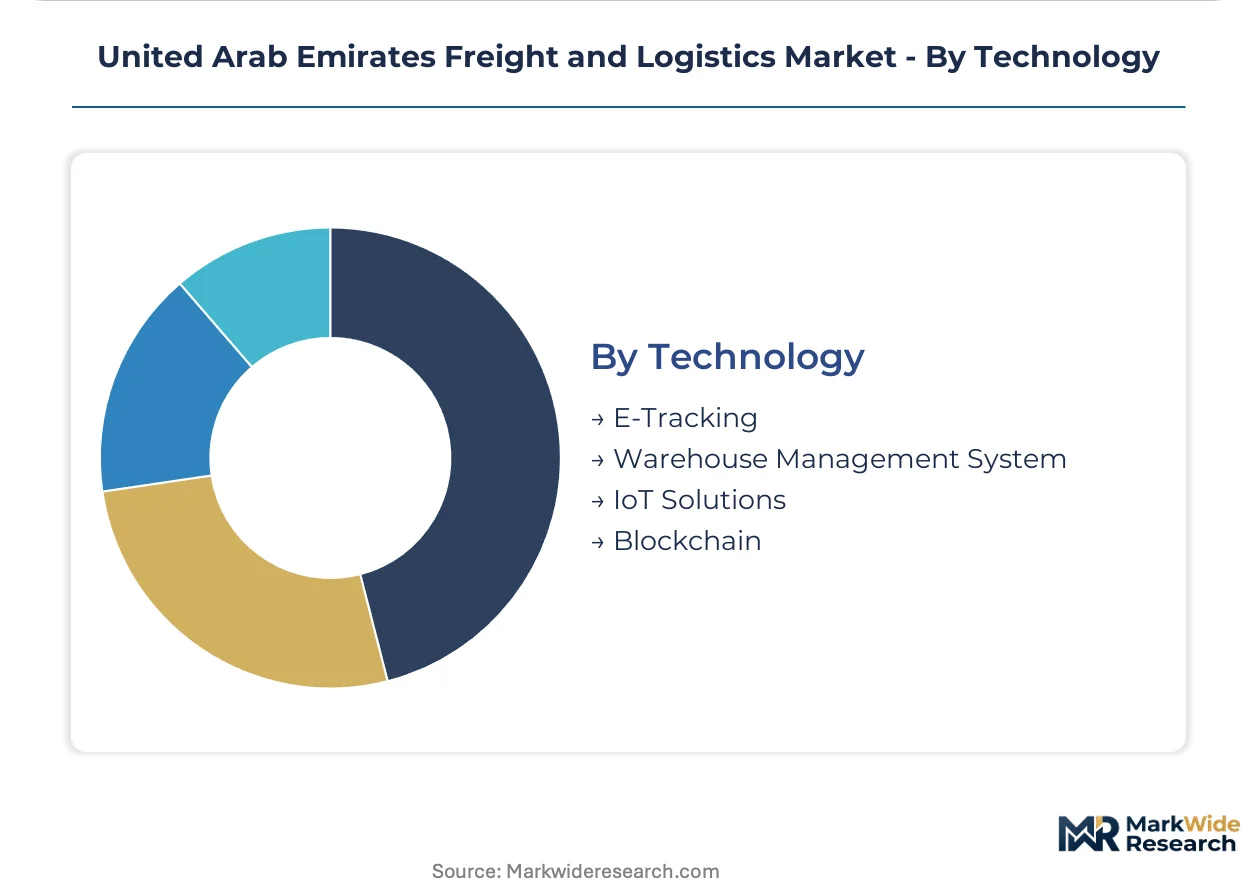
Technology:
Maturity stage separates established tracking infrastructure from emerging distributed ledger and automation systems.
- E-Tracking:Real-time shipment visibility via GPS and cellular networks enables customs pre-clearance and exception management, with adoption accelerating fastest among providers seeking competitive differentiation.
- Warehouse Management System:Legacy platform upgrades require synchronization with decade-old port operating systems, creating integration bottlenecks that inflate deployment timelines and costs.
- IoT Solutions:Sensor networks for temperature, humidity, and shock monitoring support MOHAP pharmaceutical compliance with 99.9% uptime guarantees.
- Blockchain:Distributed ledger pilots for bill-of-lading verification cut document processing from days to hours, expanding into trade finance and letter-of-credit settlement workflows.
E-tracking sits at the top of the volume ranking, with blockchain expanding most quickly on trade finance automation pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
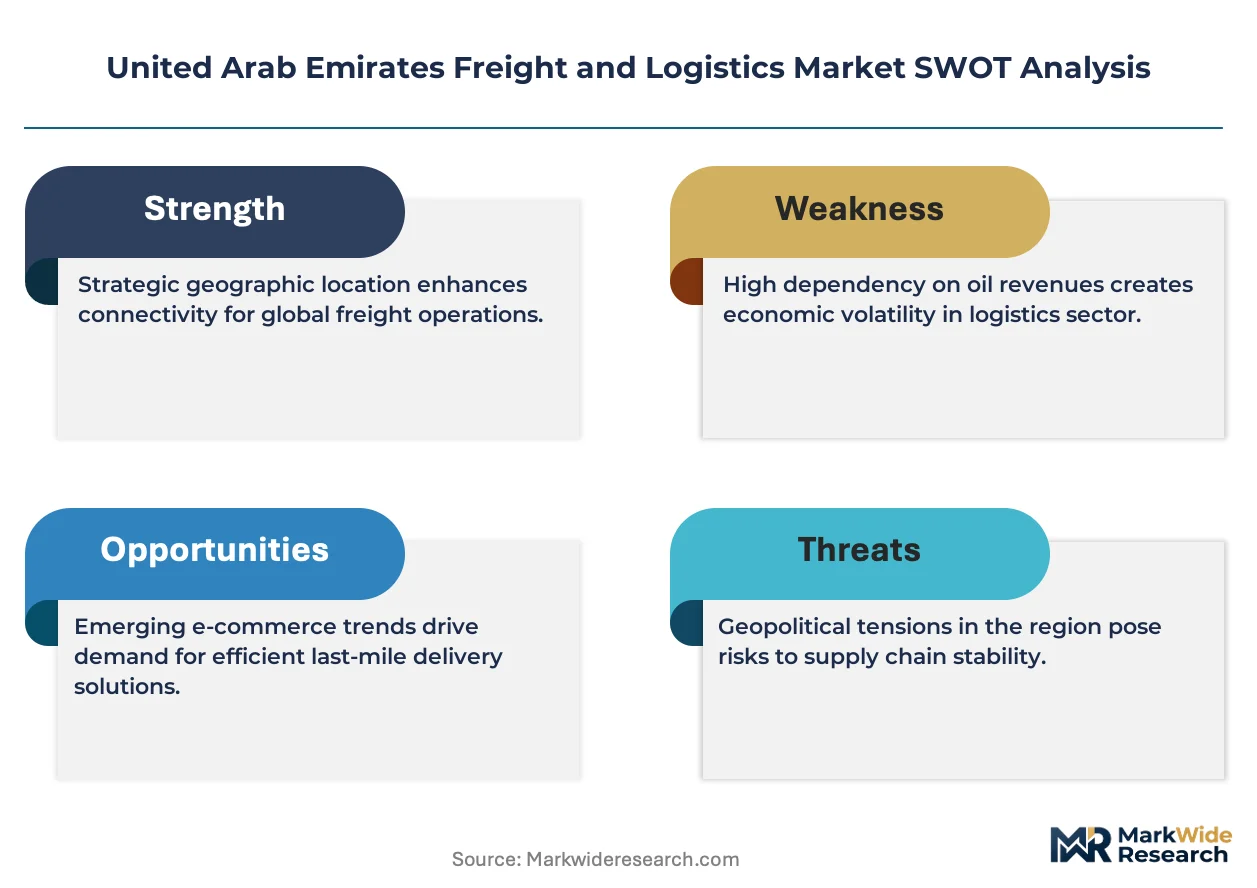
While Saudi Arabia channels logistics investment through giga-project corridors, the UAE concentrates freight capacity in free-zone clusters with deeper multimodal integration.
Dubai
Jebel Ali Port anchors container throughput across the Gulf, with DP World's port-to-door infrastructure drawing transshipment volume from competing hubs. The emirate's customs authority enforces AEO certification for supply chain security compliance. Dubai South and Jebel Ali Free Zone concentrate bonded warehousing and e-commerce fulfillment nodes for platform operators expanding same-day delivery networks.
Abu Dhabi
Khalifa Industrial Zone and KEZAD Group host manufacturing logistics for industrial operations requiring just-in-time component delivery. MOHAP pharmaceutical standards mandate temperature integrity infrastructure, pulling cold-chain investment into Masdar and healthcare city zones. The emirate's National In-Country Value procurement rules redirect federal logistics spend toward domestic operators.
Sharjah
Hamriyah Free Zone and Sharjah Airport International Free Zone serve as cost-competitive alternatives to Dubai's premium logistics real estate. Secondary e-commerce fulfillment demand is accelerating warehouse absorption rates. The emirate's industrial zones connect to Etihad Rail corridors linking northern production centers to Abu Dhabi and Dubai gateway ports.
Northern Emirates
Ras Al Khaimah and Fujairah lack dedicated platform-built distribution nodes, creating first-mover gaps for e-commerce fulfillment penetration. Fujairah's port infrastructure handles bulk commodities and oil logistics distinct from containerized trade. Aramex maintains last-mile density across these secondary markets where metropolitan courier networks remain underdeveloped.
United Arab Emirates Freight and Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated port operators commanding premium positioning against modular service providers. The vendor base organizes around three archetypes: global forwarders with pharmaceutical certification, regional 3PLs with federal procurement alignment, and port-anchored end-to-end integrators. Competitive moves concentrate on AEO certification acquisition and warehouse automation deployment.
Among UAE-based logistics operators, Al-Futtaim Logistics and Emirates Logistics exemplify domestic capacity built to capture National In-Country Value procurement redirection. DP World anchors the integrated infrastructure tier through its Jebel Ali port-to-door control. Global forwarders including Kuehne + Nagel occupy specialized certification positions for temperature-controlled pharmaceutical verticals.
| Leading Market Players |
|---|
| Al-Futtaim Logistics |
| Agility |
| DP World |
| Emirates Logistics |
| FedEx |
| Aramex |
| Kuehne + Nagel |
| GAC |
| DHL |
| Others |
Value Network & Pricing Analysis
Diesel benchmark fluctuations cascade through UAE road freight operations, compressing margins for mid-tier fleet operators while elevating subscription-based visibility platforms that insulate buyers from per-shipment volatility. Federal procurement localization under the National In-Country Value program redirects contract awards toward domestic operators, fragmenting pricing power across integrated and modular service tiers.
Pricing Analysis
Capacity additions in Dubai South and Abu Dhabi's KEZAD zones are reshaping price floors for bonded warehousing and last-mile fulfillment. Three-tier pricing structure across premium, standard, and economy levels separates AEO-certified integrated providers from generic 3PLs and unbonded last-mile couriers. Cost compression in standard-tier road freight is intensifying because diesel price volatility lacks hedging mechanisms for mid-tier fleets. E-commerce platforms exhibit lowest price sensitivity due to subscription platform adoption, while generic commodity traders face acute margin pressure.
Supply Chain Analysis
Freight cost differentials between Jebel Ali port throughput and secondary emirate road transfers concentrate supply chain control with DP World's integrated infrastructure. Manufacturing inputs for automotive and aerospace components draw from Germany, Japan, and China, while pharmaceutical cold-chain equipment sources from Switzerland and the United States. Single-source vulnerability clusters with three integrated cold-chain providers holding MOHAP certification. Distribution runs through free-zone clusters with multimodal handoffs to Etihad Rail corridors and final-mile road networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE freight and logistics operates as a late-cycle quality story where pharmaceutical cold-chain certification and cybersecurity compliance separate viable operators from margin-compressed generics. Demand is shifting toward premium specifications as MOHAP temperature integrity mandates and NIS2-aligned port system requirements elevate technical barriers.
For Market Incumbents: Deepen AEO certification coverage across secondary emirate facilities before federal procurement rules tighten domestic content obligations. Acquire warehouse automation capabilities to offset skilled technician scarcity that outpaces training pipeline output. Anchor subscription visibility platforms to long-term contracts with Dubai-based trading houses managing high-frequency GCC movements. For New Entrants and Emerging Players: Secondary emirate e-commerce fulfillment presents the most penetrable white-space target, with Ras Al Khaimah and Fujairah lacking platform-built distribution nodes. Target cybersecurity compliance services for NIS2-aligned port and warehouse system mandates as an adjacent revenue stream. Pursue pharmaceutical cold-chain certification through partnership with existing MOHAP-approved facility operators rather than greenfield investment. For Investors and Strategic Acquirers: Consolidation pressure builds where National In-Country Value procurement redirects federal logistics spend toward domestic operators with scale. Long-term viability favors vertically integrated port-to-door specialists over modular brokerage functions displaced by software-defined platforms. Watch AEO certification acquisition timelines as an inflection indicator for cross-border operator market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AEO Certification Acquisition | UAE customs authority security compliance unlocks federal procurement eligibility and cross-border operator status. |
| Cold-Chain Infrastructure Investment | MOHAP pharmaceutical standards pull capital into Dubai Healthcare City and Masdar zone certified facilities. |
| Subscription Platform Deployment | Software-defined freight visibility displaces per-shipment billing across petrochemical and retail verticals. |
| Secondary Emirate Fulfillment Buildout | First-mover warehouse positioning in Ras Al Khaimah and Fujairah captures underserved e-commerce demand. |
| Cybersecurity Compliance Services | NIS2-aligned mandates for port operating systems create adjacent revenue for IT-integrated logistics providers. |
Research Methodology
Multiple input streams — primary interviews with 3PL operations directors, customs brokerage managers, and pharmaceutical logistics specialists, alongside secondary validation — were reconciled to construct segment-level demand estimates. Customs trade databases, UAE federal procurement disclosures, MOHAP certification registries, and port throughput statistics anchored quantitative sizing. Bottom-up facility capacity modeling and top-down trade flow triangulation cross-checked volume projections.
Data-stream reconciliation across service type, end user, solution, and technology dimensions enabled granular CAGR derivation without single-source dependency. Segmentation modeling incorporated freight mode, certification tier, and free-zone location as structural variables. Forecast inputs included e-commerce fulfillment network expansion timelines, Etihad Rail corridor completion schedules, and pharmaceutical cold-chain capacity additions.
Inputs from UAE customs authority AEO certification databases and MOHAP pharmaceutical facility registries were available through the study window; gaps in real-time diesel price hedging instrument data introduce uncertainty bands around road freight margin projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Tanker Shipping Market