
 Asia Pacific Sea Freight Forwarding Market | 2026-2036
Asia Pacific Sea Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sea Freight Forwarding Market Insights
Alternative fuels, particularly methanol and ammonia blends, are rebalancing bunker cost structures across Asia Pacific liner networks. Kuehne + Nagel leverages its Singapore hub to control reefer cargo flows between Australia and Northeast Asia. Sinotrans Limited anchors inland-to-port connectivity through its Yangtze River barge network. Yusen Logistics differentiates via automotive parts consolidation centers in Thailand and Indonesia.
Asia Pacific sea freight forwarding encompasses the coordination of ocean cargo movement, customs brokerage, and multimodal interface management, typically operating through twenty-foot equivalent unit (TEU) and forty-foot equivalent unit (FEU) container standards with vessel capacities exceeding 24,000 TEU on major east-west strings. Its primary commercial purpose is to reduce shipper logistics costs while ensuring predictable transit times across archipelagic and continental supply chains. Full Container Load services dominate trans-Pacific revenue pools due to manufacturing export density from Chinese and Vietnamese ports. Less Than Container Load offerings capture faster growth among small and medium enterprises entering cross-border e-commerce. Reefer shipping commands premium positioning as Australian agricultural exports and Southeast Asian seafood production expand temperature-controlled volume.
IMO 2023 carbon intensity indicators and the EU's extension of emissions trading to maritime imports reshape vessel deployment economics on Asia-Europe lanes. China's Ministry of Transport enforces domestic green port standards that filter equipment procurement decisions at Shanghai and Ningbo terminals. Australia's Maritime Safety Authority mandates biosecurity pre-clearance protocols that add documentation layers for breakbulk agricultural machinery. Stakeholders must weigh fuel transition capex against route profitability as regulatory compliance costs redistribute across carrier and forwarder contracts.
Market Dynamics
Electronics manufacturing relocation from China to Vietnam and Indonesia is compressing traditional port hierarchies while forcing freight forwarders to rebuild inland distribution networks around Ho Chi Minh City and Batam-Bintan corridors.
Growth Catalysts
- IMO Carbon Intensity Indicators:The International Maritime Organization's vessel efficiency standards are accelerating fleet renewal investments across Asia Pacific carrier networks.
- Reefer cargo expansion:Australian agricultural exporters and Southeast Asian seafood producers are scaling temperature-controlled container volumes on east-west strings.
- Batam-Bintan industrial zone:Indonesia's bonded manufacturing corridor is generating new Less Than Container Load consolidation demand from small and medium enterprises.
Market Restraints
- Bunker fuel volatility:Methanol and ammonia blend availability constraints are creating cost unpredictability for carriers retrofitting vessels.
- Terminal concentration risk:Shanghai and Ningbo container handling dominance creates single-point vulnerability for trans-Pacific routing.
- Biosecurity documentation burden:Australia's Maritime Safety Authority pre-clearance protocols add processing friction for breakbulk agricultural machinery.
Strategic Opportunities
- Vietnam manufacturing corridor:The Ho Chi Minh City–Da Nang logistics belt remains underpenetrated for specialized automotive parts consolidation.
- China's green port standards:The Ministry of Transport domestic equipment procurement mandates create retrofit service openings for terminal technology providers.
- E-commerce cross-border flows:Small and medium enterprise digital export growth is expanding addressable market for flexible LCL offerings.
Industry Challenges
- Reefer technician scarcity:Temperature-controlled cargo maintenance expertise gaps constrain service expansion in Indonesian archipelago routes.
- Multimodal integration complexity:Yangtze River barge-to-ocean vessel coordination requires legacy system overhauls at inland ports.
- EU emissions trading adaptation:Maritime import coverage extension demands new contract pricing mechanisms for Asia-Europe lane forwarders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sea Freight Forwarding Market |
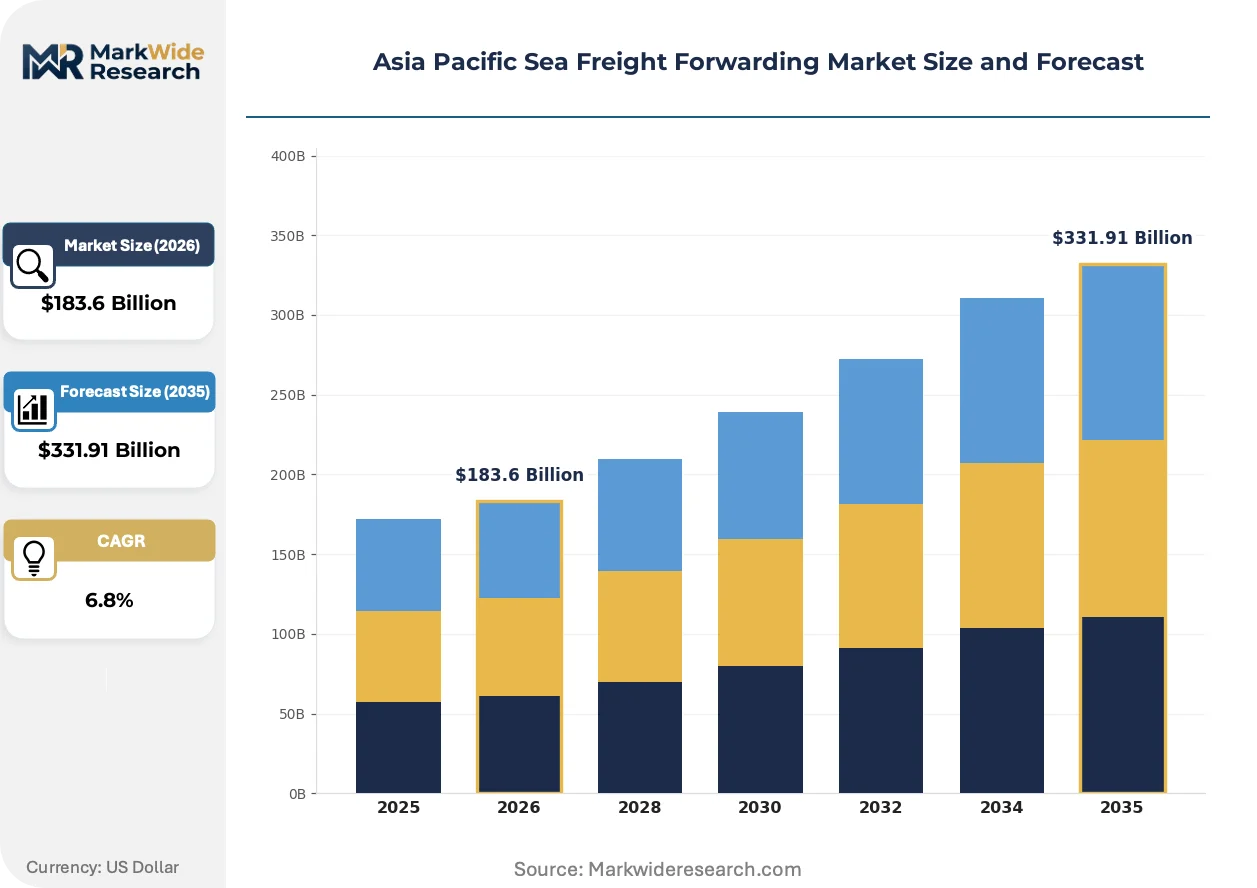
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Container Load, Less Than Container Load, Non-Vessel Operating Common Carrier, Freight Brokerage End User: Manufacturers, Retailers, Wholesalers, E-commerce Shipping Mode: Reefer, Dry Cargo, Bulk Shipping, Breakbulk Pricing Model: Fixed Rate, Variable Rate, Volume-Based, Subscription |
| Companies Covered | DHL Group, Kuehne + Nagel, DB Schenker, Sinotrans Limited, Nippon Express, Yusen Logistics, Kerry Logistics, DSV, Expeditors International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sea Freight Forwarding Market Trends and Innovations
Digital freight platforms and alternative fuel transitions are compressing traditional forwarding margins while opening new service layers around carbon accounting and multimodal optimization.
Methanol dual-fuel engine retrofits are electrifying vessel deployment economics on Asia-Europe lanes. Japanese and Korean shipyards are contracting container line orders for methanol-capable newbuilds at accelerated pace. This propulsion shift is electrifying bunker procurement strategies as carriers hedge between conventional low-sulfur fuel and green methanol supply commitments.
China's Ministry of Transport green port standards are reshaping terminal equipment procurement decisions at Shanghai and Ningbo. Domestic emissions thresholds now filter crane and yard tractor purchasing, forcing state-owned port operators into accelerated electrification timelines. Reefer handling facilities face the steepest compliance costs due to auxiliary power unit replacement requirements.
Small and medium enterprise shippers are unbundling traditional forwarding service packages in favor of modular digital procurement. Platform-based rate comparison tools are displacing long-term contract relationships in Southeast Asian cross-border e-commerce channels. This behavioral shift concentrates most visibly among Indonesian and Vietnamese electronics exporters selling into European consumer markets.
Asia Pacific Sea Freight Forwarding Market Segmentation
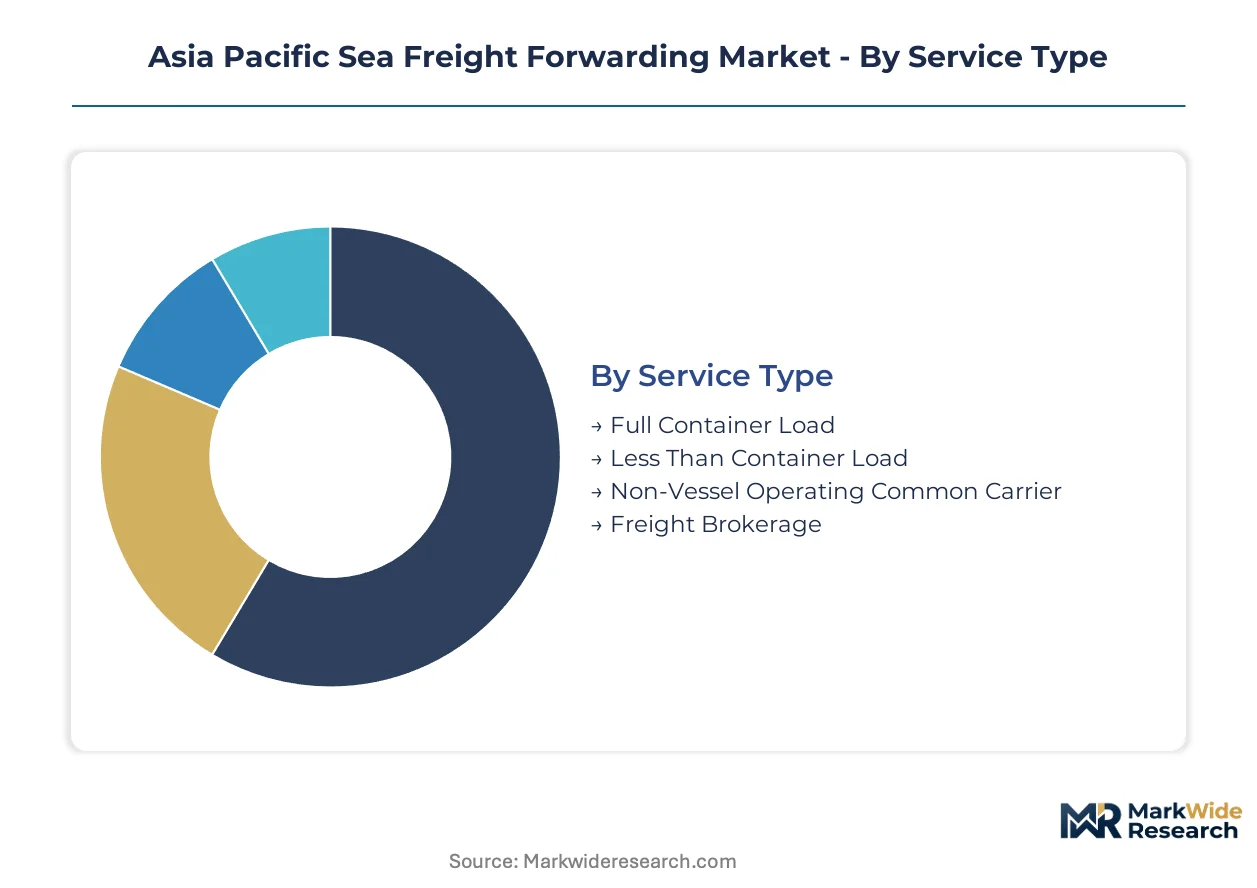
Sea freight forwarding segmentation in Asia Pacific reflects divergent infrastructure requirements across manufacturing corridors and the pressure of regulatory compliance on contract structures. Service differentiation increasingly hinges on temperature-controlled capabilities and digital platform integration rather than traditional port-to-port coverage alone.
Service Type:
Upgrade cycles in forwarding service procurement are shortening as shippers replace legacy annual contracts with modular, digitally enabled arrangements that separate physical movement from customs and financing layers.
- Full Container Load:Dedicated container allocation for single-shipper cargo dominates trans-Pacific revenue pools, particularly for Vietnamese electronics exporters and Australian mining equipment suppliers seeking predictable slot commitments on Shanghai–Los Angeles strings. Manufacturing relocation from China to Ho Chi Minh City and Batam is compressing traditional FCL contract durations as shippers demand quarterly rate renegotiation.
- Less Than Container Load:Consolidated multi-shipper containers capture expanding share among Indonesian and Vietnamese SMEs entering European e-commerce channels. Platform-based procurement tools are displacing traditional forwarder relationships in this segment, with Batam-Bintan industrial zone generators driving fastest volume expansion.
- Non-Vessel Operating Common Carrier:Intermediary operators lease vessel capacity and sell slots under their own bill of lading, enabling smaller forwarders to compete on Asia-Europe lanes without fleet ownership.
- Freight Brokerage:Transactional matching services connect spot cargo with available capacity, concentrating in intra-ASEAN corridors where vessel utilization fluctuates seasonally.
Full Container Load sits at the top of the volume ranking, with Less Than Container Load climbing the fastest.
End User:
Cost tier differentiation across end-user categories shapes forwarder staffing models, with high-touch account management reserved for integrated manufacturers while self-service platforms capture transactional retail and e-commerce flows.
- Manufacturers:Electronics, automotive parts, and machinery producers in Vietnam and Indonesia anchor demand for scheduled sailing reliability and inland distribution integration. IMO carbon intensity regulations are forcing these shippers to requalify carrier partners based on vessel efficiency ratings rather than rate alone.
- Retailers:Department store and supermarket chains source seasonal consumer goods through long-term contracts with built-in volume flexibility clauses.
- Wholesalers:Intermediate distributors aggregate fragmented agricultural and industrial machinery demand across Indonesian archipelago routes.
- E-commerce:Cross-border digital sellers generate fastest-growing demand for LCL consolidation and last-mile deconsolidation services in Ho Chi Minh City–Da Nang logistics belt.
Manufacturers command the highest contract values, though e-commerce is expanding most quickly as a customer acquisition target.
Shipping Mode:
Application-specific equipment requirements drive margin stratification, with temperature-controlled and project cargo commanding premium positioning over standardized dry container movement.
- Reefer:Temperature-controlled containers maintain precise cold chains for Australian beef and dairy exports to Northeast Asia, plus Southeast Asian seafood production bound for European markets. Technician scarcity across Indonesian routes constrains service expansion despite premium rate structures.
- Dry Cargo:Standardized container movement of manufactured goods and consumer products constitutes baseline forwarding volume across all major Asia Pacific strings.
- Bulk Shipping:Unpacked commodity cargoes including coal, iron ore, and grains move under specialized charter arrangements outside standard container networks.
- Breakbulk:Oversized machinery and project cargo requiring individual handling faces Australia's Maritime Safety Authority biosecurity pre-clearance documentation burdens that add processing friction.
Dry Cargo retains volume leadership, while Reefer offers the steepest expansion trajectory on agricultural export growth.
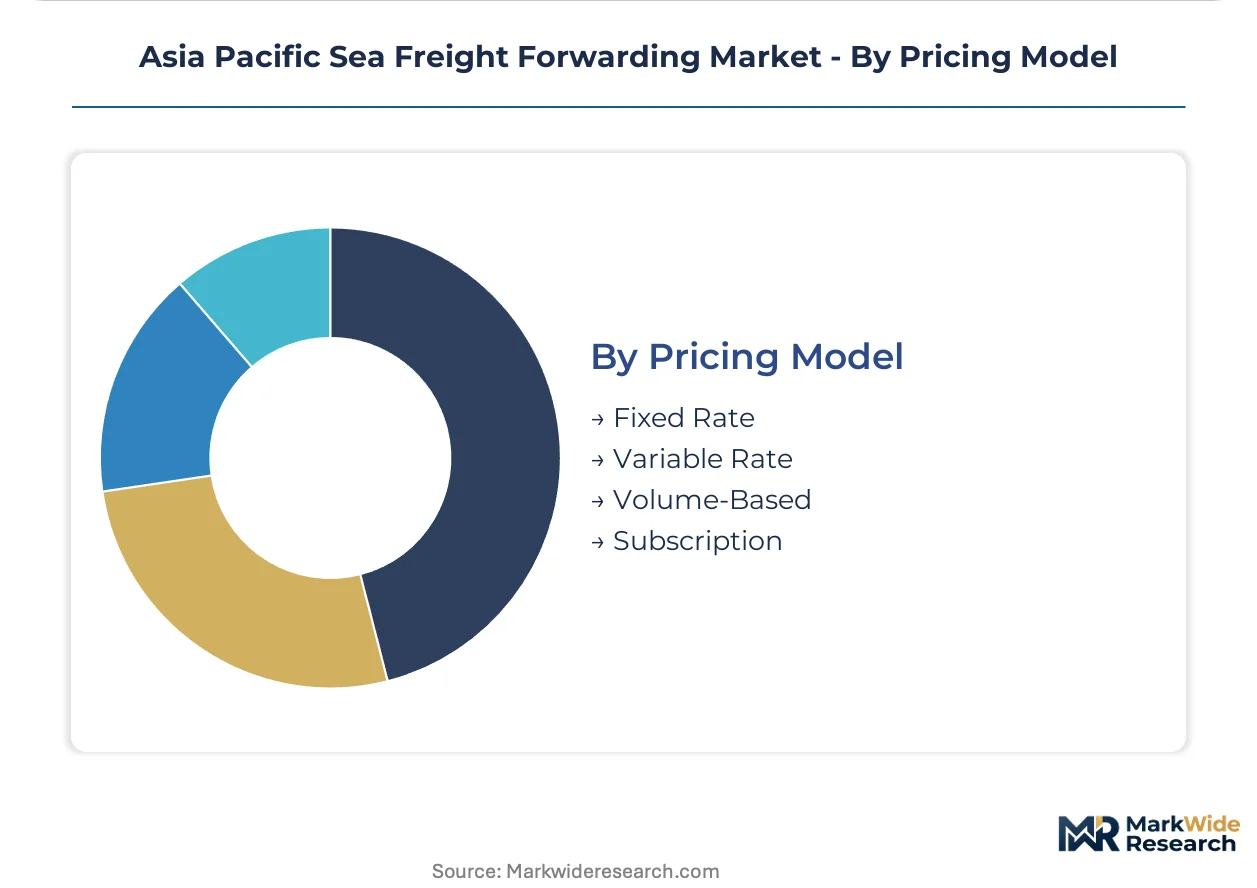
Pricing Model:
Customer sophistication and contract scale determine pricing architecture selection, with large manufacturers negotiating complex index-linked structures while smaller shippers accept platform-quoted spot rates.
- Fixed Rate:Locked pricing across contract durations protects budget certainty for Australian agricultural exporters and Japanese automotive manufacturers with predictable shipment schedules.
- Variable Rate:Bunker adjustment factor-linked pricing transfers fuel cost volatility to shippers, concentrating in trans-Pacific lanes where low-sulfur fuel differentials fluctuate widely.
- Volume-Based:Tiered rate discounts reward committed throughput, favored by Vietnamese electronics manufacturers with steady production flows.
- Subscription:Flat monthly fees for unlimited access within defined corridors are gaining traction among Southeast Asian e-commerce platforms with irregular but high-frequency shipment patterns.
Variable Rate structures dominate contract value, with Subscription models gaining share fastest among digital-native shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ho Chi Minh City–Da Nang logistics belt anchors freight forwarding demand expansion as electronics manufacturing relocates from China. Vietnam's bonded industrial zones and Indonesia's Batam-Bintan corridor are compressing traditional port hierarchies across Southeast Asia. Australia's agricultural export infrastructure and Northeast Asian reefer networks complete the regional demand map.
China
Shanghai and Ningbo terminals handle the densest container volumes on trans-Pacific strings. The Ministry of Transport enforces green port standards that filter crane and yard tractor procurement at state-owned facilities. Yangtze River barge networks feed these megaports from inland manufacturing clusters around Chongqing and Wuhan.
Vietnam
Electronics exporters in Bac Ninh and Hai Phong are shortening FCL contract durations to quarterly renegotiation cycles. Vietnam's customs modernization program accelerates clearance velocity at Lach Huyen deepwater port. The Ho Chi Minh City–Da Nang belt remains underpenetrated for automotive parts consolidation despite manufacturing density.
Indonesia
SME digital sellers in the Batam-Bintan industrial zone drive fastest LCL consolidation growth. Indonesia's bonded manufacturing corridor generates platform-based procurement demand from cross-border e-commerce channels. Reefer technician scarcity across archipelago routes constrains temperature-controlled service expansion despite premium rate structures.
Australia
Beef and dairy exporters scale temperature-controlled volumes on east-west strings to Northeast Asia. The Maritime Safety Authority mandates biosecurity pre-clearance protocols that add documentation friction for breakbulk agricultural machinery. Port Botany and Melbourne reefer terminals face auxiliary power unit replacement costs under emissions thresholds.
Singapore
The city-state's hub status controls reefer cargo flows between Australia and Northeast Asia. Maritime and Port Authority regulations align with IMO carbon intensity indicators while preserving transshipment competitiveness. Tuas mega-port development consolidates intra-ASEAN feeder connections and long-haul liner calls.
Asia Pacific Sea Freight Forwarding Market Competitive Landscape
Capacity expansion dominates the current landscape as forwarders retrofit service networks around Vietnam and Indonesia manufacturing corridors. The vendor base clusters into three tiers: integrated global networks, regional specialists with inland connectivity, and platform-native digital entrants. Strategic archetypes include reefer-differentiated operators, automotive parts consolidators, and Yangtze River barge integrators. M&A activity and multimodal partnership formation represent the two dominant competitive vectors reshaping contract structures.
Among integrated global networks, Kuehne + Nagel and DSV exemplify hub-and-spoke architectures with Singapore and Shanghai control towers. Sinotrans Limited anchors the regional specialist tier through its Yangtze River barge-to-ocean coordination capabilities. Yusen Logistics occupies a position within automotive-focused consolidation, reflecting Thailand and Indonesia parts center density. These three archetypes represent divergent responses to IMO regulatory compliance and manufacturing relocation pressures.
| Leading Market Players |
|---|
| DHL Group |
| Kuehne + Nagel |
| DB Schenker |
| Sinotrans Limited |
| Nippon Express |
| Yusen Logistics |
| Kerry Logistics |
| DSV |
| Expeditors International |
| Others |
Pricing and Supply Chain Analysis
Vietnamese electronics manufacturers anchor contract negotiation leverage through quarterly FCL rate renegotiation cycles that compress forwarder margins while rewarding volume commitment with bunker-adjusted flexibility.
Pricing Analysis
Bunker adjustment factor-linked pricing transfers low-sulfur fuel volatility to shippers on trans-Pacific lanes. Three-tier pricing structure across premium, standard, and economy levels separates reefer cargo with technician support from dry container baseline and spot brokerage. Cost compression in LCL segments is intensifying because platform-based procurement tools displace traditional forwarder relationships. E-commerce SMEs exhibit highest price sensitivity; Australian agricultural exporters with predictable schedules show lowest.
Supply Chain Analysis
Regional distribution centers in Singapore and Shanghai orchestrate hub-and-spoke feeder connections across Southeast Asian manufacturing corridors. Supply concentrates in China, Vietnam, and Indonesia for electronics and automotive parts production. Container manufacturing, vessel charter capacity, and reefer equipment availability constitute critical input dependencies. Single-source vulnerability at Shanghai-Ningbo terminal pairs creates chokepoint exposure. Distribution runs through bonded zone consolidation at Batam-Bintan and Ho Chi Minh City–Da Nang belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
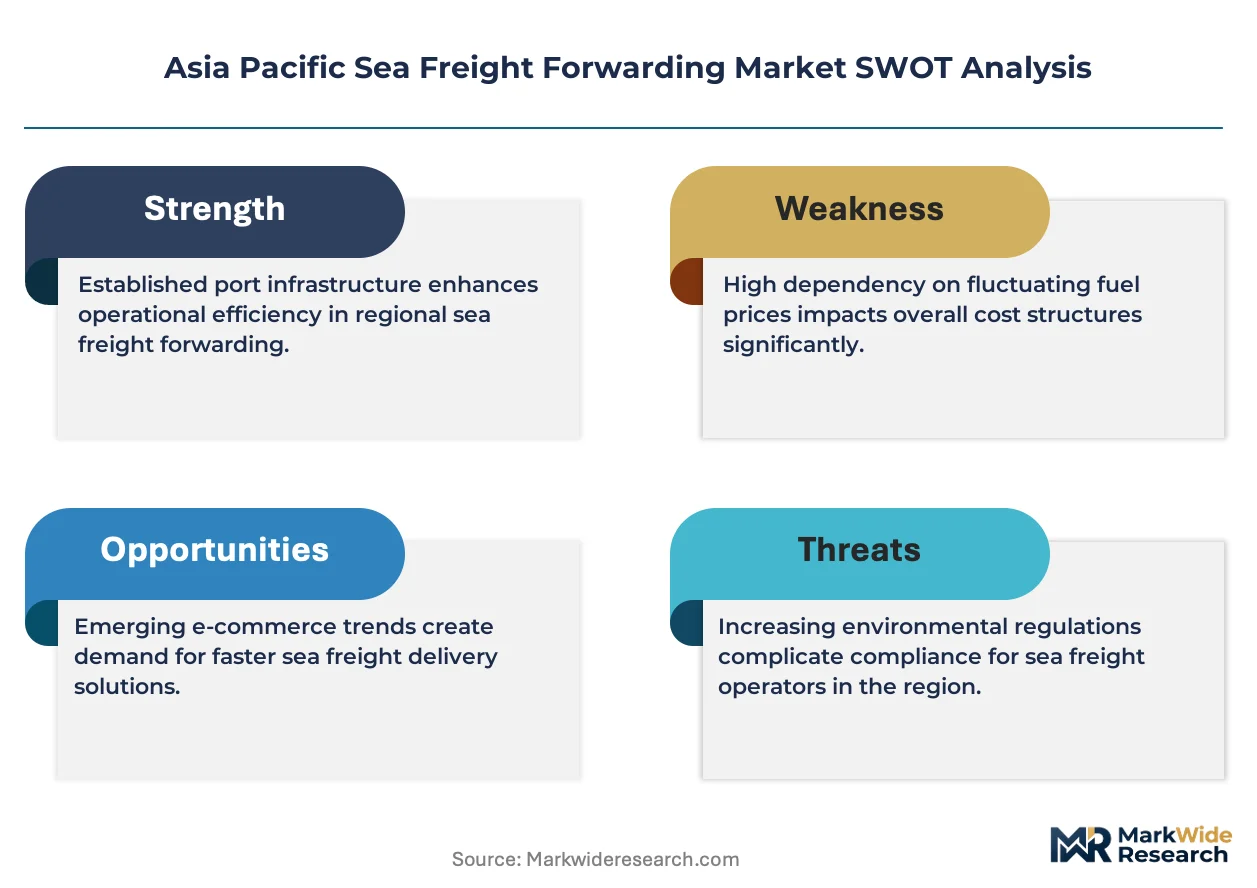
Asia Pacific sea freight forwarding operates as a late-cycle quality story where IMO carbon intensity compliance and reefer cargo expansion drive demand toward premium vessel efficiency ratings and temperature-controlled service capabilities.
For Market Incumbents: Cement hub-and-spoke control tower dominance by deepening Yangtze River barge-to-ocean coordination and Singapore reefer transshipment capacity. Invest in methanol dual-fuel carrier partnerships before EU emissions trading adaptation forces contract repricing. Platform-native digital entrants threaten traditional SME relationships; defend through modular service unbundling with self-service rate tools. For New Entrants and Emerging Players: Enter via automotive parts consolidation centers in the underpenetrated Ho Chi Minh City–Da Nang logistics belt, where electronics manufacturing density lacks specialized forwarder coverage. Target Indonesian archipelago reefer routes where technician scarcity constrains incumbent expansion. Lead with subscription pricing for cross-border e-commerce platforms with irregular high-frequency shipment patterns. For Investors and Strategic Acquirers: Integrated logistics conglomerates with existing port terminal interests are the most active acquirer in this space, seeking multimodal forwarders with inland barge networks. Long-term viability hinges on fuel transition capex recovery through carbon-accounting-enabled contract structures. Watch for IMO enforcement variance across flag registries as inflection signal for carrier compliance cost redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Methanol Dual-Fuel Fleet Retrofit | IMO carbon intensity indicators force carrier capital deployment toward alternative propulsion or penalty exposure. |
| Reefer Technician Training Programs | Australian beef and Southeast Asian seafood export growth outpaces qualified maintenance workforce availability. |
| Platform-Based LCL Procurement | Indonesian and Vietnamese SME digital sellers displace annual contracts with modular spot-rate comparison tools. |
| Batam-Bintan Bonded Zone Expansion | Indonesia's industrial corridor generates fastest consolidation demand from cross-border e-commerce channels. |
| Green Port Equipment Procurement | China's Ministry of Transport domestic emissions thresholds accelerate crane and yard tractor electrification timelines. |
Research Methodology
Direct dialogue with carrier network planners, freight forwarder operations directors, terminal equipment procurement managers, and customs brokerage specialists grounded qualitative findings in operational reality. Secondary validation drew from IMO regulatory filings, Ministry of Transport green port standards, Australian Maritime Safety Authority biosecurity protocols, and ASEAN customs modernization documentation. Bottom-up volume modeling across TEU movements and top-down macroeconomic triangulation ensured cross-verified outputs.
Segmented projections across service type, end user, shipping mode, and pricing model dimensions fed into analytical framework outputs over the projection horizon. CAGRs were derived from manufacturing relocation velocity, regulatory compliance cost pass-through assumptions, and reefer cargo expansion trajectories. Vessel capacity deployment schedules and alternative fuel availability constraints served as industry-specific forecast inputs.
The model holds under steady IMO enforcement and gradual manufacturing corridor migration; deviation in bunker fuel volatility or carbon border adjustment acceleration would shift carrier contract pricing power. Forecasts reflect documented assumptions around fleet renewal timelines and port electrification compliance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Sweden Freight and Logistics Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Egypt 3PL Market