
 US International Courier, Express, and Parcel (CEP) Market | 2026-2036
US International Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
US International Courier, Express, and Parcel (CEP) Market Insights
Market Context
Subscription-based logistics software is recalibrating what shippers purchase, bundling predictive analytics with capacity guarantees rather than selling discrete delivery transactions. United Parcel Service leverages its integrated ground-air network to anchor premium express services across North American trade lanes. FedEx Corporation competes through specialized healthcare cold-chain infrastructure that sustains temperature-sensitive pharmaceutical shipments. DHL Group differentiates its international footprint by controlling customs brokerage capabilities that expedite cross-border clearance.
Technical Definition and Segment Structure
The US International Courier, Express, and Parcel sector encompasses time-definite transportation of documents, parcels, and freight across national boundaries, utilizing multimodal networks with defined service-level agreements specifying transit windows, tracking granularity, and liability frameworks. Its primary commercial purpose is enabling just-inventory replenishment and direct-to-consumer fulfillment for businesses operating distributed supply chains. Express delivery commands premium pricing due to guaranteed time-definite commitments, while same-day delivery represents the fastest-growing service tier as urban density and micro-fulfillment investments expand addressable corridors. Last-mile delivery absorbs disproportionate operational cost within the delivery mode matrix, though air freight retains margin concentration for intercontinental urgent shipments.
Regulatory Framework and Outlook
FAA regulations governing unmanned aircraft systems for commercial package delivery are reshaping last-mile infrastructure investment timelines and operational design approval requirements. CBP customs modernization programs and TSA cargo screening mandates directly shape market access thresholds and compliance cost structures for international parcel flows. NHTSA hours-of-service rules for commercial drivers constrain ground network capacity planning during peak seasonal surges. Stakeholders must monitor how evolving EPA emissions standards for commercial vehicle fleets interact with state-level zero-emission corridor mandates to determine powertrain transition pacing and capital deployment sequencing.
Market Dynamics
Cross-border e-commerce volume from small and medium enterprises is compressing traditional parcel aggregation models while forcing carriers to reconfigure customs clearance workflows for lower-value, higher-velocity shipments.
Growth Catalysts
- Drone delivery authorization:FAA unmanned aircraft system regulations for commercial package delivery are creating new last-mile infrastructure categories and operational design approval pathways for urban corridors.
- Healthcare cold-chain expansion:Temperature-sensitive pharmaceutical distribution requirements are pulling specialized express capacity into biopharma supply chains with stringent chain-of-custody protocols.
- Texas corridor concentration:Demand clustering along the Dallas-Fort Worth to Houston axis is driving dedicated air freight capacity deployment and ground network densification.
Market Restraints
- Pilot labor scarcity:FAA certification timelines and training pipeline constraints limit air crew availability during peak seasonal surges.
- Ground network cost rigidity:NHTSA hours-of-service regulations constrain driver utilization rates and prevent elastic capacity scaling.
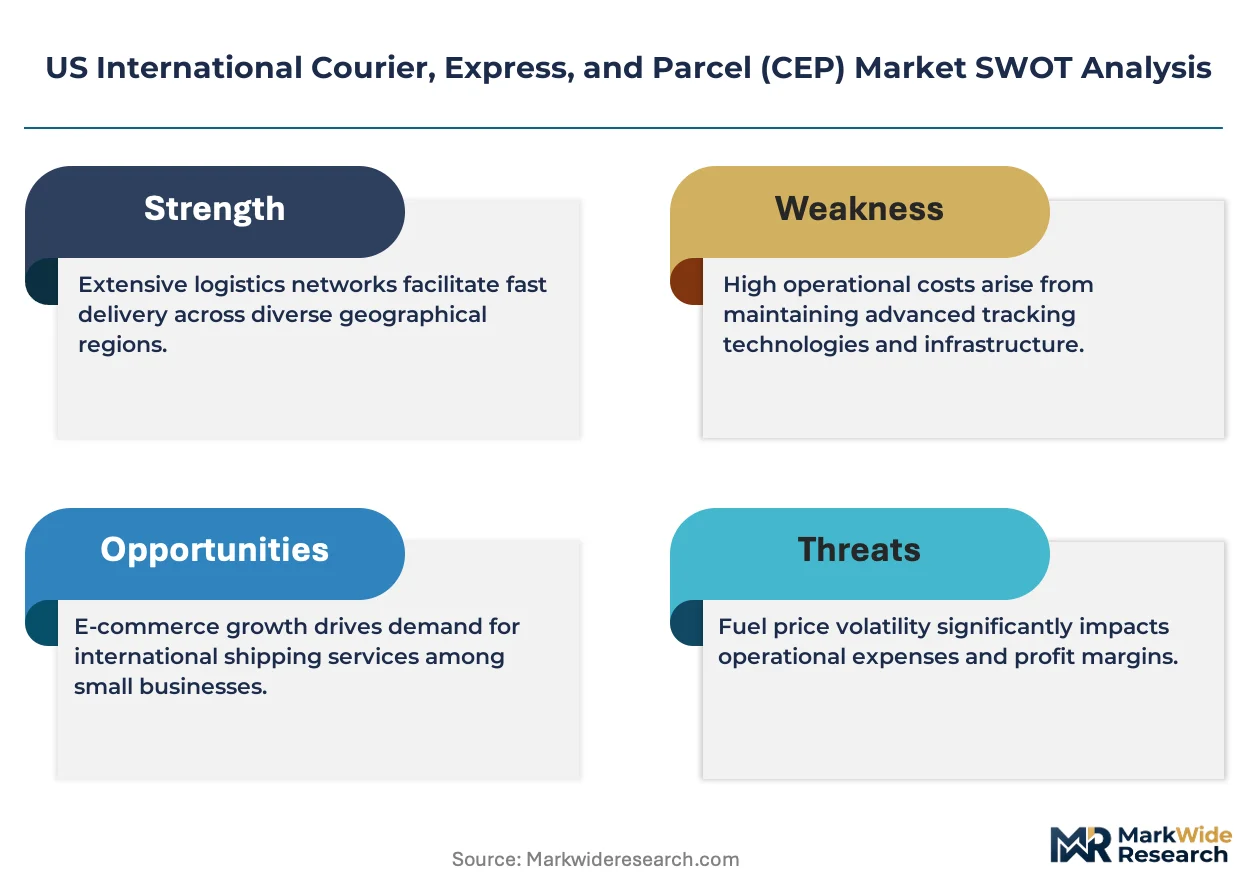
- Jet fuel price volatility:Aviation kerosene cost swings transmit directly to express service margins with limited short-term hedging effectiveness.
Strategic Opportunities
- Micro-fulfillment penetration:Urban density zones in Chicago and Los Angeles support same-day delivery radius expansion through distributed inventory positioning.
- Customs brokerage integration:CBP modernization programs reward carriers with in-house clearance capabilities versus third-party broker dependency.
- Electric fleet transition:EPA emissions standards alignment with California zero-emission corridor mandates creates first-mover advantage in sustainable last-mile branding.
Industry Challenges
- Legacy warehouse management integration:Micro-fulfillment robotics require API synchronization with existing inventory systems that lack real-time data architecture.
- Drone pilot certification bottlenecks:FAA Part 107 remote operator licensing throughput limits commercial rollout velocity for autonomous delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US International Courier, Express, and Parcel (CEP) Market |
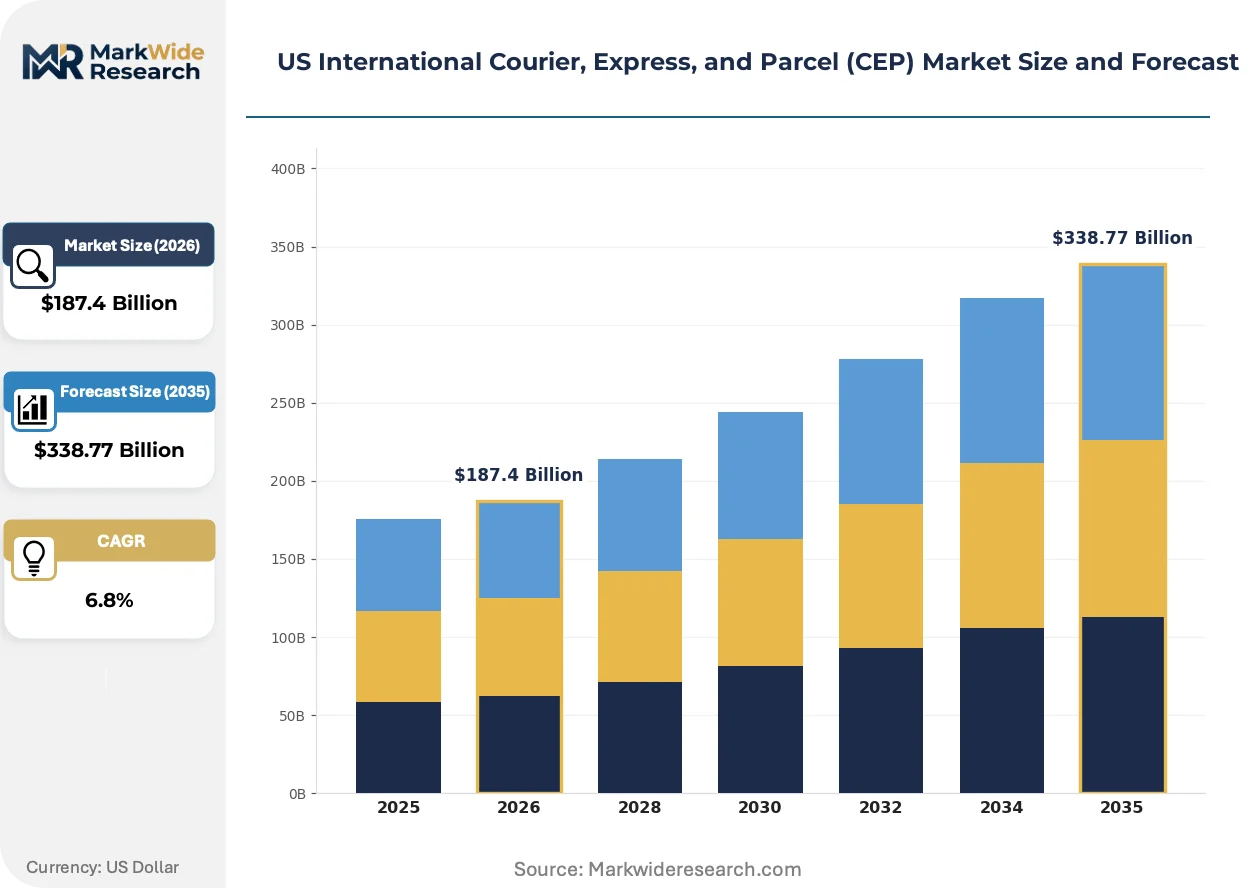
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same-Day Delivery, Next-Day Delivery End User: E-commerce, Retail, Healthcare, Automotive Delivery Mode: Air Freight, Ground Freight, Sea Freight, Last-Mile Delivery Package Type: Documents, Parcels, Pallets, Freight |
| Companies Covered | United Parcel Service, FedEx Corporation, DHL Group, Aramex, United States Postal Service, SF Express, Averitt Express, TForce Logistics, Canada Post Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US International Courier, Express, and Parcel (CEP) Market Trends and Innovations
Subscription-based logistics software is displacing transactional freight purchasing across shipper procurement functions, embedding predictive analytics and capacity guarantees into recurring revenue relationships.
Autonomous sorting robotics is modularizing parcel handling workflows in regional distribution facilities. E-commerce fulfillment centers in Phoenix and Atlanta are deploying these systems at accelerated replacement cycles. The technology is modularizing facility design standards away from fixed conveyor infrastructure toward reconfigurable cell-based processing.
FAA unmanned aircraft system regulations for beyond-visual-line-of-sight operations are compressing drone delivery pilot program timelines. Commercial operators must secure operational design approvals for specific urban air mobility corridors. The Texas corridor linking Dallas-Fort Worth to Houston faces the most complex airspace coordination requirements and is driving early standard-setting.
Direct-to-consumer fulfillment is fragmenting traditional wholesale distribution channels for cross-border retail. Small and medium enterprises in apparel and electronics are bypassing importer intermediaries to control customs clearance and last-mile branding. This pattern concentrates in California and New York metro areas with established international logistics infrastructure.
US International Courier, Express, and Parcel (CEP) Market Segmentation
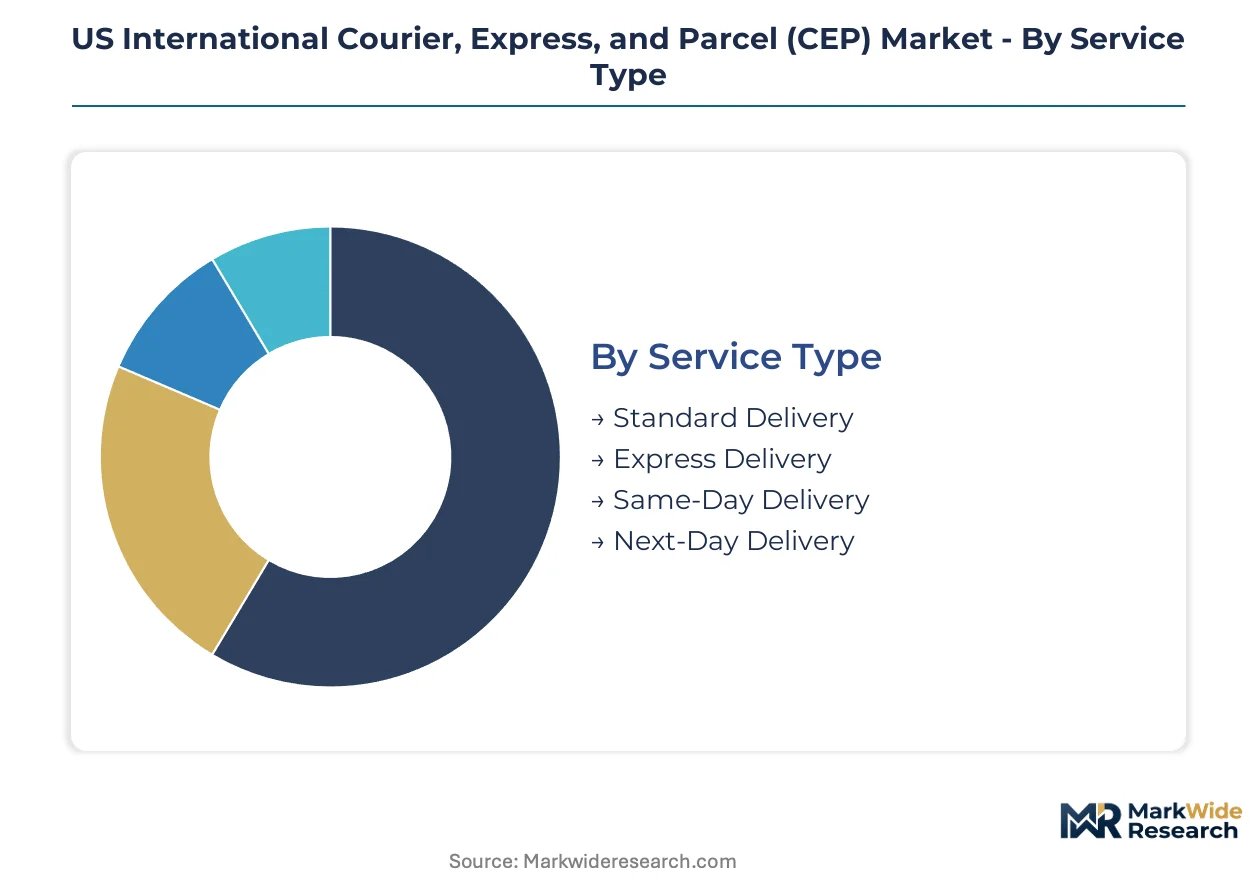
Segmentation in the US International CEP market determines which regulatory frameworks apply to carrier operations and which infrastructure investments yield priority returns. Service tiers face distinct FAA, TSA, and CBP compliance burdens that reshape capital allocation and network design.
Service Type:
FAA Part 135 certification requirements for air cargo operations concentrate on express and same-day tiers, while standard delivery operates under less stringent Part 121 commercial airline frameworks. Ground-only services fall under NHTSA commercial vehicle regulations without aviation oversight.
- Standard Delivery:Non-time-definite ground transportation with transit windows extending beyond 72 hours. Demand concentrates in Texas corridor B2B replenishment where cost sensitivity outweighs velocity requirements, constrained by NHTSA driver hour limits during peak seasons.
- Express Delivery:Time-definite multimodal service with guaranteed delivery windows between 24-72 hours utilizing integrated ground-air networks. Healthcare cold-chain shipments in California and New York metro areas drive premium capacity allocation, pulled by FDA temperature compliance mandates.
- Same-Day Delivery:Urban corridor service completing pickup-to-delivery within single operating windows. Micro-fulfillment centers in Chicago and Los Angeles support radius expansion, though FAA drone authorization bottlenecks constrain autonomous last-mile rollout velocity.
- Next-Day Delivery:Overnight service leveraging dedicated air freight capacity and early-morning ground distribution. E-commerce subscription models in Dallas-Fort Worth and Houston anchor volume, compressed by pilot labor scarcity during holiday surges.
Standard Delivery sits at the top of the volume ranking, with Same-Day Delivery climbing the fastest.
End User:
Customer type determines customs clearance complexity and last-mile density requirements. Healthcare and automotive shippers demand chain-of-custody documentation that general merchandise flows rarely require.
- E-commerce:Direct-to-consumer parcel flows from small and medium enterprises bypassing traditional wholesale channels. Cross-border volume concentrates in California and New York customs districts, forcing CBP modernization program alignment.
- Healthcare:Temperature-sensitive pharmaceutical and biologics distribution with FDA-validated cold-chain protocols. Express carriers compete through specialized infrastructure investments, differentiated by continuous monitoring capabilities.
- Retail:Omnichannel inventory replenishment and returns management across distributed store networks. Seasonal volatility in Texas corridor demand strains ground network elasticity under NHTSA hour-of-service caps.
- Automotive:Just-in-time component shipments with production line synchronization requirements. Time-definite express services command premium positioning for critical assembly plant inputs.
E-commerce generates the highest shipment volume, while Healthcare shows the steepest expansion trajectory.
Delivery Mode:
Modal selection dictates which federal agencies exercise primary oversight and which emissions standards govern fleet procurement. Air and ground modes face divergent EPA and FAA regulatory timelines.
- Air Freight:Intercontinental and domestic express capacity utilizing freighter aircraft and commercial belly cargo. Jet fuel price volatility transmits directly to margins, limiting short-term hedging effectiveness for urgent pharmaceutical shipments.
- Ground Freight:Long-haul trucking and intermodal rail connecting distribution facilities. EPA commercial vehicle emissions standards interact with California zero-emission corridor mandates to determine powertrain transition pacing.
- Sea Freight:Containerized ocean transport for non-urgent international parcel aggregation. Cost advantage erodes for small and medium enterprise volumes requiring expedited customs clearance.
- Last-Mile Delivery:Final delivery segment from local distribution to recipient address. FAA unmanned aircraft system regulations are compressing drone pilot program timelines for urban air mobility corridors.
Ground Freight handles the greatest tonnage, with Last-Mile Delivery gaining share fastest.
Package Type:
Physical characteristics determine handling infrastructure requirements and liability frameworks. Document flows face lighter TSA screening protocols than dense parcel freight.
- Documents:Lightweight paper-based shipments including contracts, visas, and legal filings. Digital substitution pressures volume in traditional express corridors, though regulatory notarization requirements sustain certain flows.
- Parcels:Individual packages under dimensional weight thresholds dominating e-commerce fulfillment. Autonomous sorting robotics in Phoenix and Atlanta facilities modularize handling workflows for this category.
- Pallets:Unitized freight shipments requiring forklift-capable infrastructure throughout the network. LTL consolidation economics favor ground freight modes over air express alternatives.
- Freight:Heavy or oversized shipments exceeding standard parcel dimensions. Customs brokerage integration becomes critical for cross-border clearance efficiency.
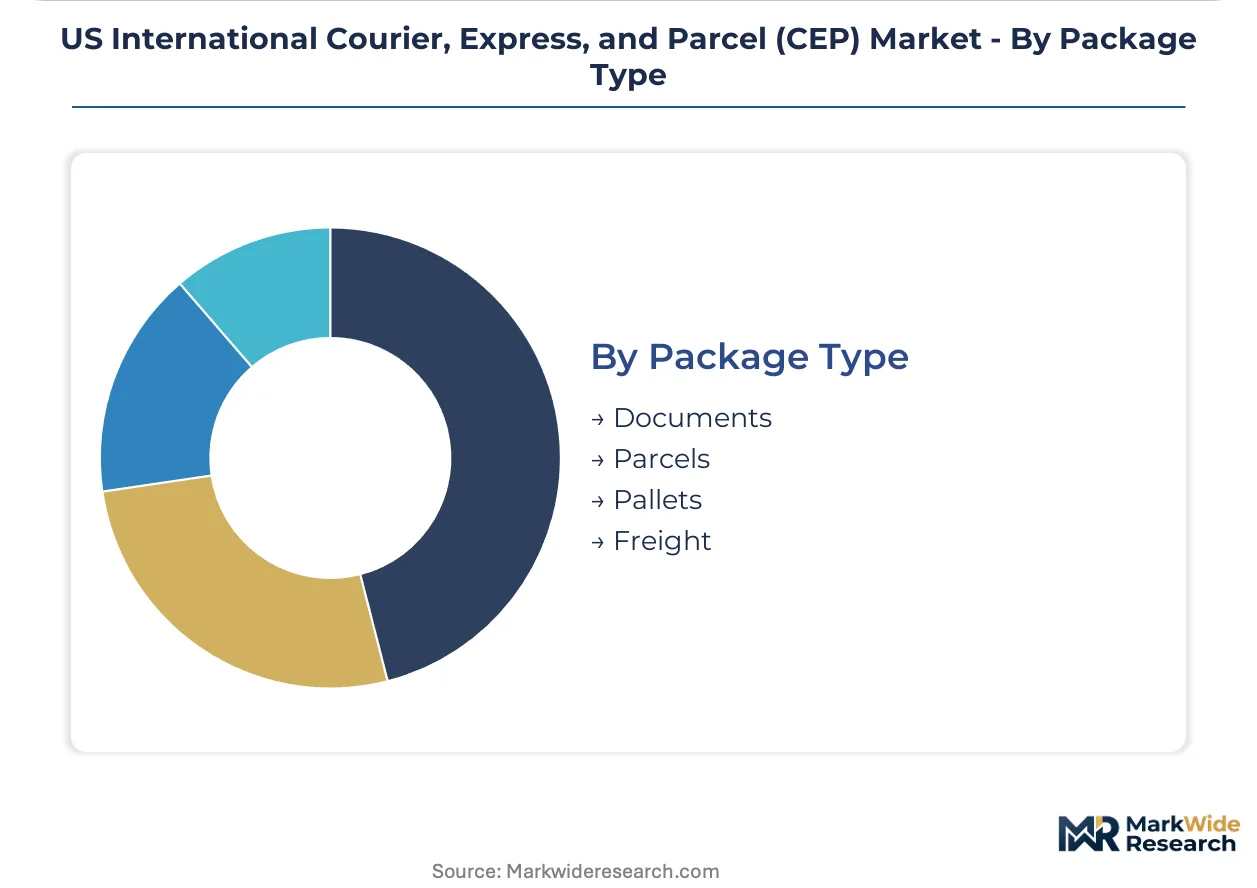
Parcels lead shipment counts, with Freight expanding most quickly on cross-border SME adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where logistics infrastructure deploys, as carriers route volume through jurisdictions with streamlined customs modernization programs and permissive unmanned aircraft system frameworks. Cost-of-compliance gaps between states are accelerating network densification in corridors with favorable FAA operational design approval pathways.
California
Healthcare cold-chain demand from San Diego biotech clusters and Los Angeles e-commerce fulfillment centers is pulling specialized express capacity into the state. FDA temperature compliance mandates for pharmaceutical distribution interact with CARB zero-emission corridor requirements to determine electric fleet procurement sequencing. The Inland Empire logistics sprawl anchors cross-border parcel aggregation for Asia-Pacific trade lanes.
Texas
The Dallas-Fort Worth to Houston corridor concentrates the fastest-growing express volume in the nation, driven by energy sector procurement and Mexican manufacturing integration. FAA unmanned aircraft system regulations for beyond-visual-line-of-sight operations face complex airspace coordination requirements here, compressing drone delivery pilot timelines. Houston's port complex and DFW's air freight hub create multimodal density unmatched elsewhere.
New York Metro
Direct-to-consumer fulfillment from small and medium enterprises in apparel and electronics bypasses traditional wholesale channels through JFK customs district infrastructure. CBP modernization programs reward carriers with in-house clearance capabilities versus third-party broker dependency. Brooklyn and Queens micro-fulfillment centers support same-day delivery radius expansion constrained by urban airspace restrictions.
Illinois
Chicago's central location anchors ground network consolidation for Midwest manufacturing replenishment and returns management. NHTSA hours-of-service regulations constrain driver utilization rates during peak seasonal surges, preventing elastic capacity scaling. O'Hare International Airport's cargo infrastructure supports pharmaceutical express flows with FDA-validated chain-of-custody protocols.
Georgia
Atlanta's autonomous sorting robotics deployment at accelerated replacement cycles is modularizing parcel handling workflows for e-commerce volume. EPA commercial vehicle emissions standards interact with state-level fleet transition incentives to determine powertrain deployment pacing. The Savannah port corridor supports sea freight aggregation for non-urgent international parcel flows requiring expedited customs clearance.
US International Courier, Express, and Parcel (CEP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated network operators commanding premium positioning in time-definite express tiers while regional ground carriers capture cost-sensitive standard delivery volumes. The market structure concentrates around three strategic archetypes: multimodal integrators with captive air fleets, specialized healthcare cold-chain operators, and last-mile-focused ground networks. Dominant competitive moves include customs brokerage capability integration and micro-fulfillment infrastructure densification in urban corridors.
Among integrated network operators, United Parcel Service, FedEx Corporation, and DHL Group occupy positions that exemplify the multimodal archetype, each representing distinct geographic origin and regulatory navigation strategies. United Parcel Service anchors North American ground-air integration, FedEx Corporation exemplifies specialized pharmaceutical infrastructure investment, and DHL Group represents European-originated customs brokerage control. These three entities collectively illustrate how carrier scale translates into operational design approval access and CBP modernization program alignment.
| Leading Market Players |
|---|
| United Parcel Service |
| FedEx Corporation |
| DHL Group |
| Aramex |
| United States Postal Service |
| SF Express |
| Averitt Express |
| TForce Logistics |
| Canada Post Corporation |
| Others |
Pricing and Supply Chain Analysis
E-commerce subscription models from Dallas-Fort Worth and Houston are compressing per-unit margins while demanding guaranteed capacity blocks, forcing carriers to restructure cost allocation across ground-air networks and shift pricing toward bundled analytics-plus-delivery contracts.
Pricing Analysis
Direct-to-OEM discounts anchor enterprise logistics procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by transit velocity and customs clearance bundling. Jet fuel cost volatility transmits directly to express margins, intensifying price erosion in next-day tiers where hedging effectiveness remains limited. Small and medium enterprises exhibit highest price sensitivity, while healthcare cold-chain shippers absorb premium positioning for FDA-validated chain-of-custody protocols.
Supply Chain Analysis
Domestic-content mandates under CBP modernization programs are reshaping customs brokerage sourcing toward in-house clearance capabilities versus third-party dependency. Aircraft manufacturing draws from USA, France, and Brazil for freighter and belly-cargo capacity, while ground fleet procurement rests on EPA emissions standards alignment with California zero-emission corridor requirements. Single-source vulnerability concentrates in pilot labor pipelines constrained by FAA certification timelines. Distribution runs through multimodal hubs anchored by DFW air freight infrastructure and Houston port complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas corridor demand clustering against California emissions compliance costs creates geographic-arbitrage positioning for carriers routing volume through jurisdictions with streamlined FAA operational design approval pathways.
For Market Incumbents: Deepen micro-fulfillment densification in Chicago and Los Angeles urban zones to defend same-day radius expansion against autonomous delivery entrants. Anchor customs brokerage integration under CBP modernization programs to lock cross-border SME volume. Prioritize electric fleet procurement sequencing aligned with EPA standards to capture sustainable last-mile branding premium.
For New Entrants and Emerging Players: Enter via healthcare cold-chain specialization targeting FDA-validated temperature compliance gaps in San Diego biotech clusters. White-space concentration exists in drone delivery pilot programs for Dallas-Fort Worth to Houston corridors facing complex airspace coordination requirements. Pursue operational design approval partnerships with established Part 135 certificate holders to bypass FAA certification bottlenecks.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized healthcare logistics operators controlling continuous monitoring infrastructure for pharmaceutical distribution. Long-term viability centers on carriers with integrated customs clearance capabilities and captive air-ground network density. Monitor FAA beyond-visual-line-of-sight authorization timelines as inflection indicator for autonomous last-mile valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage Integration | CBP modernization programs reward in-house clearance with expedited cross-border SME volume capture. |
| Micro-Fulfillment Network Expansion | Chicago and Los Angeles density zones enable same-day radius growth through distributed inventory positioning. |
| Electric Fleet Transition | EPA alignment with California zero-emission corridors creates first-mover advantage in sustainable branding. |
| Drone Delivery Authorization | FAA Part 107 operational design approvals unlock autonomous last-mile infrastructure in Texas corridor airspace. |
| Healthcare Cold-Chain Infrastructure | FDA-validated temperature protocols differentiate express capacity for San Diego biotech cluster demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics procurement officers, airline cargo operations directors, customs brokerage managers, and e-commerce supply chain planners with secondary validation against FAA regulatory filings, CBP modernization program documentation, EPA emissions standards, and carrier SEC disclosures. Bottom-up shipment volume modeling triangulated with top-down market sizing across service tiers.
Segment-weighting approaches distributed value projections across express, same-day, next-day, and standard delivery tiers, with end-use splits for e-commerce, healthcare, retail, and automotive verticals. Delivery mode segmentation incorporated air freight, ground freight, sea freight, and last-mile dynamics. CAGRs derived from elasticity modeling against cross-border SME adoption curves and healthcare cold-chain expansion rates, with jet fuel price volatility and pilot labor scarcity as scenario inputs.
Inputs from carrier operational disclosures and regulatory agency publications were available through the study window; gaps in real-time drone delivery pilot program data introduce uncertainty bands around autonomous last-mile penetration assumptions. Forecasts reflect documented elasticity parameters and scenario-weighted regulatory timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Unit Load Device Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Qatar Freight and Logistics Market