
 US Remote Patient Monitoring and Care Market | 2026-2036
US Remote Patient Monitoring and Care Market Size, Share, and Industry Trends Forecast 2026-2036
US Remote Patient Monitoring and Care Market Analytics
Medicare Advantage plans and large integrated delivery networks is redrawing procurement priorities across the US Remote Patient Monitoring and Care landscape. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor continuous glucose monitoring within hospital-at-home programs. Medtronic competes through its diversified cardiac and diabetes device portfolio, while Dexcom specializes in real-time glucose telemetry for payer-contracted population health contracts.
Remote patient monitoring and care encompasses connected hardware, software platforms, and clinical workflows that collect, transmit, and analyze patient physiologic data outside traditional care facilities, typically operating through FDA-cleared Class II medical devices with 510(k) clearance pathways and cloud-based data architectures meeting HIPAA security requirements. Wearable devices and remote monitoring systems generate the dominant revenue pools, though artificial intelligence and data analytics segments attract disproportionate R&D investment as predictive algorithms reshape clinical decision support. Cloud platforms occupy a maturing infrastructure layer where margin compression from hyperscaler competition is forcing vendors toward vertical application stacks.
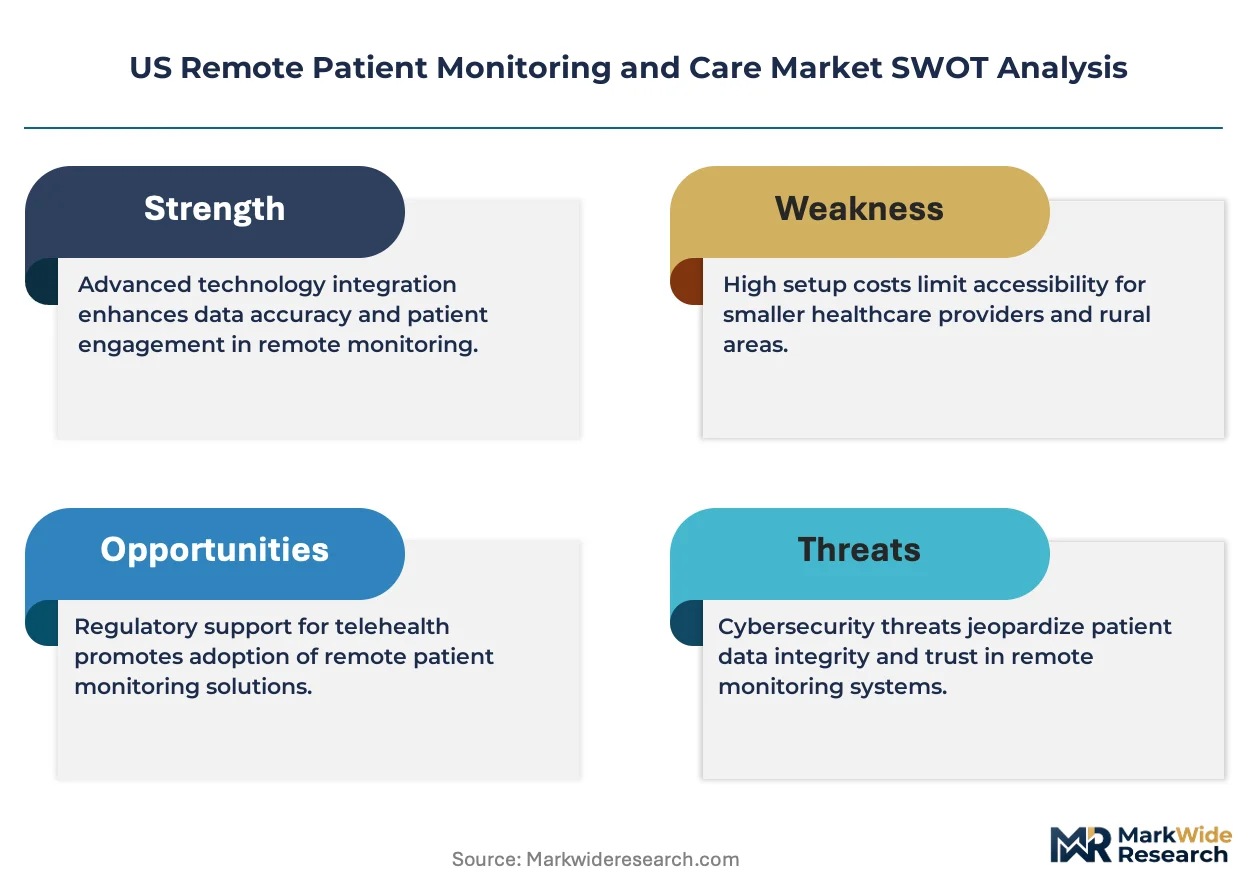
FDA 510(k) clearance requirements and HIPAA security rule compliance constitute the foundational regulatory architecture governing device approval and data exchange, while CMS reimbursement codes for remote physiologic monitoring and remote therapeutic monitoring directly determine provider adoption economics and vendor go-to-market viability. State-level telehealth licensing variations and corporate practice of medicine doctrines create additional friction for multi-state platform deployment. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classification and CMS value-based care program integration timelines to anticipate reimbursement cliff risks and competitive positioning requirements.
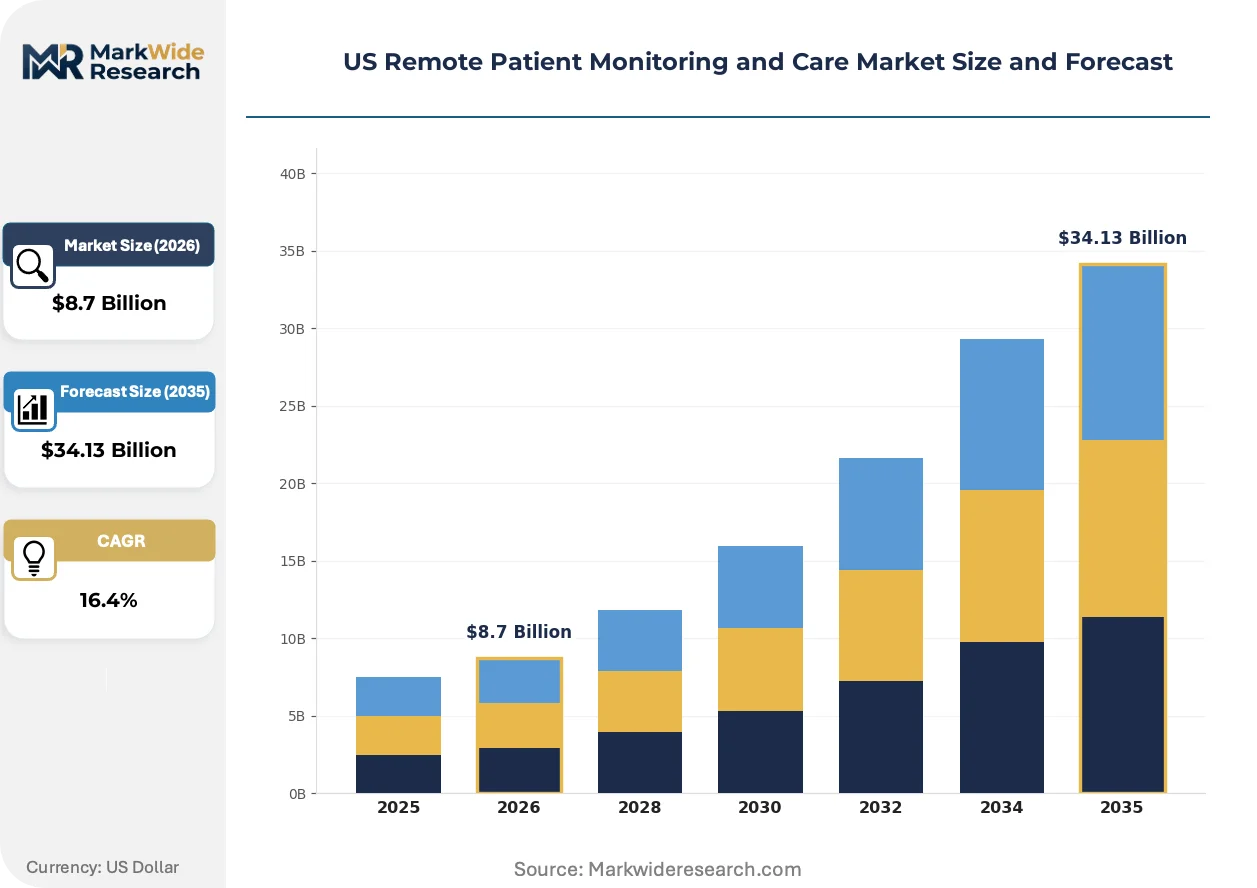
Market Dynamics
CMS reimbursement expansion for remote physiologic monitoring is redrawing provider economics and procurement priorities across hospital systems and Medicare Advantage plans. The shift from fee-for-service to value-based care contracts is forcing integrated delivery networks to prioritize connected monitoring platforms that reduce acute utilization.
Growth Catalysts
- CMS RPM Reimbursement Codes:Medicare reimbursement for remote physiologic monitoring and remote therapeutic monitoring creates direct revenue streams for physician practices and hospital outpatient departments.
- Texas and Florida Medicare Advantage Concentration:Large integrated delivery networks in these states are accelerating hospital-at-home program deployments with embedded RPM infrastructure.
- Continuous Glucose Telemetry:Real-time glucose data transmission enables automated insulin dosing protocols and reduces endocrinology appointment burden.
Market Restraints
- HIPAA Security Rule Compliance Costs:Cloud platform vendors face escalating cybersecurity infrastructure investments to maintain Business Associate Agreement eligibility with covered entities.
- FDA 510(k) Clearance Timelines:Software-as-a-medical-device classification uncertainty extends regulatory review periods for algorithm-driven clinical decision support features.
- Smartphone-Dependent Patient Populations:Elderly Medicare beneficiaries with limited digital literacy or device access create adherence gaps in connected care protocols.
Strategic Opportunities
- California Medicaid Expansion:Medi-Cal managed care plans represent underpenetrated demand for maternal health and pediatric asthma remote monitoring programs.
- Artificial Intelligence Convergence:Predictive algorithms integrating continuous vital sign streams with electronic health record data enable early deterioration detection in skilled nursing facilities.
- Direct-to-Employer Contracting:Self-insured employers in manufacturing and logistics sectors are bypassing traditional payers to procure occupational health monitoring directly.
Industry Challenges
- Interoperability Standards Fragmentation:HL7 FHIR implementation variability across electronic health record vendors complicates bidirectional data exchange architecture.
- Clinical Workflow Integration:Nursing staff in hospital-at-home programs require retraining on remote triage protocols and escalation thresholds that differ from inpatient protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Remote Patient Monitoring and Care Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Remote Monitoring Systems, Cloud Platforms End User: Patients, Healthcare Providers, Caregivers, Payers Technology: Telehealth Solutions, IoT Devices, Artificial Intelligence, Data Analytics Application: Chronic Disease Management, Post-Acute Care, Preventive Care, Emergency Response |
| Companies Covered | Abbott Laboratories, Medtronic, Dexcom, Koninklijke Philips, Boston Scientific, GE Healthcare, Johnson & Johnson, Baxter International, BIOTRONIK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Remote Patient Monitoring and Care Market Evolving Landscape
Wearable sensor form factors and reimbursement policy evolution are compressing device development cycles and reshaping how providers contract for population health management. The convergence of continuous monitoring hardware with automated care coordination software is creating new platform economics.
Patch-based electrocardiogram monitors are replacing Holter devices for ambulatory arrhythmia detection in cardiology practices. Medicare Advantage plans in Florida are deploying these devices for post-discharge monitoring of heart failure patients. The technology is miniaturizing to sub-wearable formats that enable multi-week adhesion without patient intervention.
CMS has finalized expanded billing guidelines for remote therapeutic monitoring of musculoskeletal and respiratory conditions, extending reimbursement beyond traditional physiologic parameters. Physician practices in Texas are restructuring care teams to capture these new revenue codes. Pulmonary rehabilitation programs represent the most affected segment, with forced adoption of connected spirometry and activity tracking.
Hospital systems are unbundling device procurement from clinical service contracts, creating direct purchasing relationships with RPM platform vendors. Large integrated delivery networks in California are negotiating enterprise-wide agreements that span inpatient, outpatient, and home-based care settings. This behavior is most visible in academic medical centers with captive Medicare Advantage plans seeking to control total cost of care.
US Remote Patient Monitoring and Care Market Segmentation
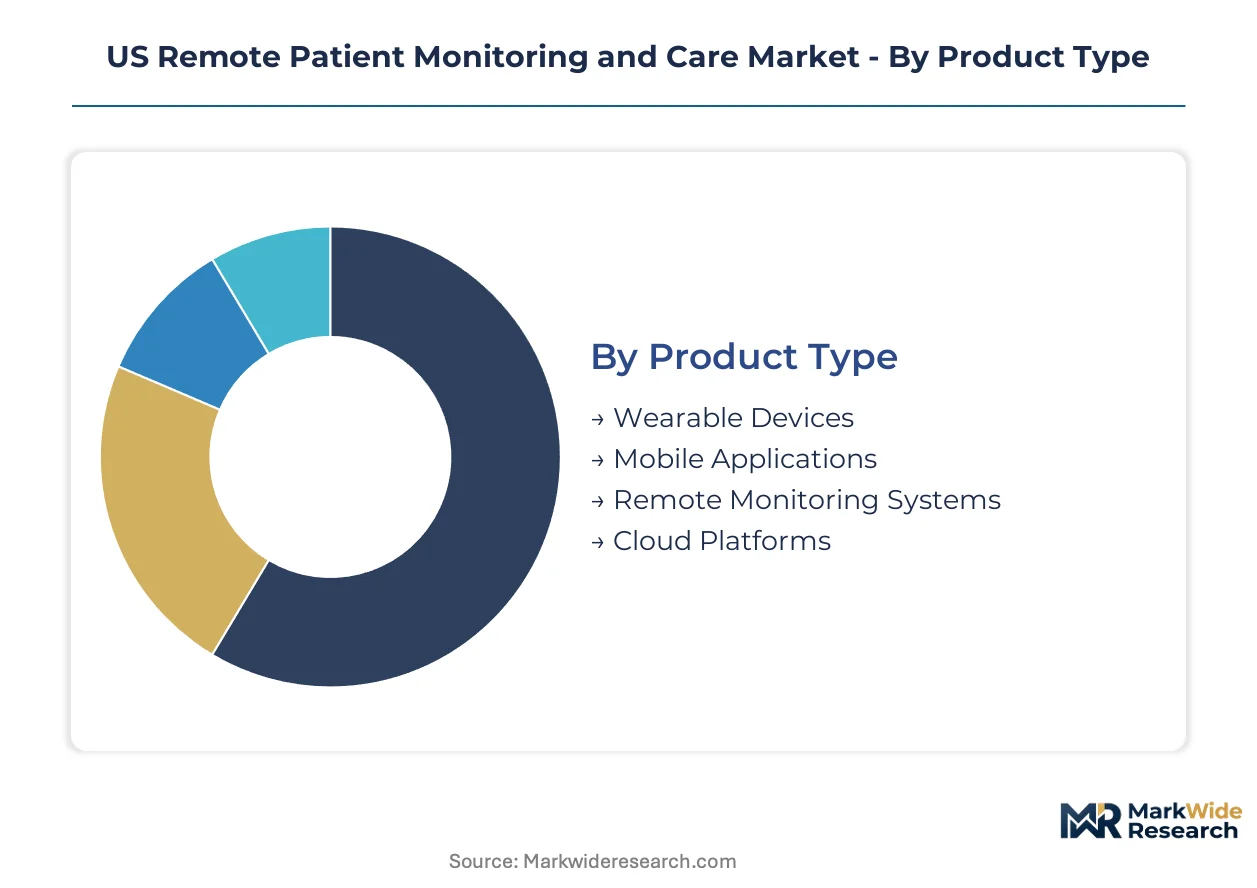
Segmentation in the US Remote Patient Monitoring and Care Market reveals how procurement channels fragment across hardware vendors, software platforms, and clinical service providers. Understanding these divisions exposes where margin pools concentrate and which technology stacks hospital systems prioritize for integration.
Product Type:
Wearable Devices and Remote Monitoring Systems flow through medical device distributors and direct hospital procurement, while Cloud Platforms and Mobile Applications route through enterprise software vendors and health system IT departments.
- Wearable Devices:Continuous physiologic sensors include continuous glucose monitors, pulse oximeters, and blood pressure cuffs with Bluetooth telemetry. Texas and Florida Medicare Advantage plans are driving procurement of multi-parameter wristbands for hospital-at-home programs facing readmission penalties.
- Remote Monitoring Systems:Hub-based architectures aggregate data from multiple peripherals and transmit to clinical dashboards via cellular or WiFi. Large integrated delivery networks in California negotiate enterprise licenses spanning inpatient discharge through skilled nursing facility transitions.
- Mobile Applications:Patient-facing software interfaces for symptom reporting and medication adherence. HIPAA-compliant messaging modules are required for CMS reimbursement eligibility.
- Cloud Platforms:Infrastructure-as-a-service layers hosting data storage, analytics engines, and EHR integration middleware. AWS and Azure dominance is compressing vendor margins and forcing vertical application specialization.
By volume, Wearable Devices leads. By growth pace, Cloud Platforms is climbing the fastest as health systems consolidate vendor relationships.
End User:
Cost tier segmentation separates enterprise contracts with health systems from direct-to-consumer subscriptions and payer-sponsored population health programs.
- Healthcare Providers:Physician practices and hospital outpatient departments purchasing RPM infrastructure to capture CMS reimbursement codes. Cardiology and endocrinology departments show highest adoption velocity due to clear clinical protocols and established billing pathways.
- Payers:Medicare Advantage plans and self-insured employers contracting for population health management. Florida Blues plans and California Medi-Cal managed care organizations are embedding RPM into value-based care contracts with downside risk.
- Patients:Direct-purchasers of consumer-grade monitoring devices, typically smartphone-dependent populations with chronic conditions seeking care continuity between visits.
- Caregivers:Family members and home health aides accessing proxy dashboards for elderly or disabled patients. This segment depends on simplified interfaces and alert escalation protocols.
By revenue concentration, Healthcare Providers dominates procurement. By contract expansion rate, Payers is gaining share fastest as risk-bearing entities internalize monitoring infrastructure.
Technology:
Maturity curves separate established telehealth modalities from emerging AI layers attracting venture deployment and regulatory uncertainty.
- Telehealth Solutions:Synchronous video consultation platforms and asynchronous store-and-forward diagnostic imaging. State licensing variations create deployment friction for multi-state provider groups.
- IoT Devices:Connected medical peripherals with embedded sensors and wireless transmission protocols. FDA 510(k) clearance pathways govern device classification and software update requirements.
- Artificial Intelligence:Predictive algorithms for deterioration detection and automated triage prioritization. FDA software-as-a-medical-device guidance remains unresolved for machine learning-based clinical decision support.
- Data Analytics:Population health dashboards and risk stratification engines integrating RPM feeds with claims data. HL7 FHIR implementation variability complicates bidirectional EHR exchange architecture.
By installed base, Telehealth Solutions leads. By investment velocity, Artificial Intelligence shows the steepest expansion trajectory as vendors race to differentiate beyond hardware commoditization.
Application:
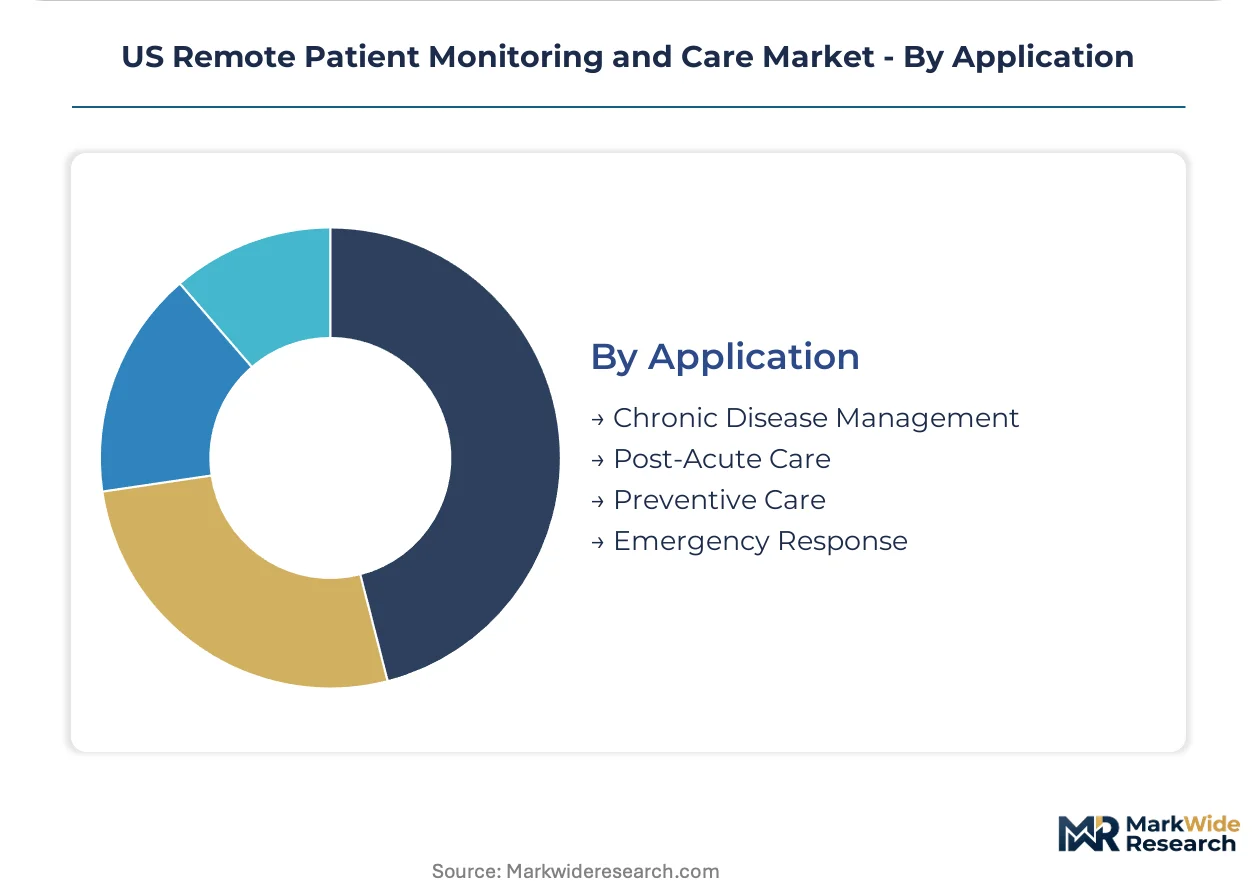
Clinical use case segmentation maps to reimbursement code availability and outcome measurement feasibility across acute and longitudinal care settings.
- Chronic Disease Management:Longitudinal monitoring of diabetes, heart failure, and hypertension with automated care plan adjustments. CMS remote physiologic monitoring codes directly reimburse physician time for data review and care coordination.
- Post-Acute Care:Transition monitoring from hospital to home or skilled nursing facility. Texas hospital systems are deploying these programs to reduce penalty exposure under CMS Hospital Readmissions Reduction Program.
- Preventive Care:Wellness monitoring and early intervention for at-risk populations. Maternal health and pediatric asthma programs in California Medi-Cal represent underpenetrated demand.
- Emergency Response:Acute event detection and automated emergency services dispatch. Fall detection and arrhythmia alert systems serve elderly populations living independently.
By reimbursement capture, Chronic Disease Management leads. By program launch velocity, Post-Acute Care is expanding most quickly as hospital-at-home waivers become permanent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and Medicare Advantage plans concentrate procurement authority in Texas, Florida, and California, with integrated delivery networks in these states driving platform standardization across inpatient and home-based care settings.
Texas
Large integrated delivery networks in Dallas-Fort Worth and Houston are deploying hospital-at-home programs with embedded remote monitoring infrastructure to reduce CMS readmission penalties. Texas Medicaid managed care expansion supports maternal health remote monitoring pilots in the Rio Grande Valley. San Antonio's military health cluster is testing veteran-centric connected care protocols through VA partnerships.
Florida
Medicare Advantage plans in Miami-Dade and Tampa Bay are accelerating post-discharge cardiac monitoring contracts with cardiology practices. Florida's Agency for Health Care Administration has streamlined telehealth licensing for multi-state provider groups operating hospital-at-home programs. Orlando's health technology corridor hosts vendor pilot programs for senior living facility integration.
California
Academic medical centers in Los Angeles and San Francisco are negotiating enterprise-wide RPM agreements spanning inpatient discharge through skilled nursing transitions. Medi-Cal managed care expansion in the Central Valley is creating demand for pediatric asthma and maternal health monitoring programs. San Diego's biotech cluster is driving sensor miniaturization for patch-based vital sign monitoring.
New York Metro
Health systems in Manhattan and Brooklyn are restructuring care teams to capture CMS remote therapeutic monitoring codes for musculoskeletal rehabilitation. New York State's telehealth parity laws mandate reimbursement equivalence for remote physiologic monitoring services. The Hudson Valley corridor is emerging as a testing ground for caregiver-facing proxy dashboard deployments.
Greater Boston
Research hospitals in Cambridge and Boston are piloting FDA software-as-a-medical-device pathways for predictive deterioration algorithms. Massachusetts Health Policy Commission value-based care contracts incentivize integrated delivery networks to internalize remote monitoring infrastructure. The Route 128 corridor concentrates venture-backed RPM analytics vendors serving national health systems.
US Remote Patient Monitoring and Care Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with established FDA clearance pathways and hospital contracting relationships. Market structure concentrates around three to five integrated device-platform vendors capable of spanning hardware, software, and clinical service layers. Strategic archetypes include continuous monitoring specialists, diversified cardiac-diabetes portfolio holders, and hub-based system integrators. Competitive moves center on enterprise licensing expansion and vertical integration into cloud analytics layers.
Within the diversified device tier, Abbott Laboratories, Medtronic, and Dexcom occupy positions as archetype anchors for continuous glucose monitoring and cardiac telemetry integration. Abbott represents the ecosystem-play model with FreeStyle Libre anchoring hospital-at-home programs. Medtronic exemplifies the diversified portfolio approach spanning cardiac rhythm management and diabetes device platforms. Dexcom sits within the real-time telemetry specialization vector for payer-contracted population health deployments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Dexcom |
| Koninklijke Philips |
| Boston Scientific |
| GE Healthcare |
| Johnson & Johnson |
| Baxter International |
| BIOTRONIK |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day sensor procurement lead times concentrate pricing power with FDA-cleared device manufacturers while cloud platform vendors face margin compression from AWS and Azure hyperscaler competition. Hospital systems exploit this bifurcation by unbundling hardware procurement from clinical service contracts.
Pricing Analysis
Next-generation patch-based electrocardiogram monitors command premium positioning against legacy Holter devices and unvalidated consumer wearables. Three-tier pricing structure across FDA-cleared Class II devices, CE-marked equivalents, and unregulated consumer sensors reflects certification-grade differentiation. Cost compression in cloud infrastructure tiers stems from hyperscaler price wars forcing vertical application specialization. Medicare Advantage plans exhibit highest price sensitivity due to capitated reimbursement exposure, while academic medical centers prioritize clinical integration over unit cost.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes tether domestic distribution to Asia-Pacific sensor manufacturing clusters. Semiconductor fabrication for continuous glucose monitoring ASICs rests on Taiwan and South Korea foundry capacity, with MEMS sensor substrates sourced from Japanese specialty chemical suppliers. Single-source vulnerability concentrates in FDA-registered contract manufacturing organizations handling sterile adhesive patch production. Distribution runs through medical device distributors for hospital procurement and direct SaaS licensing for health system IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from clinical workflow integration and care coordination software expands faster than hardware unit sales, transforming procurement economics toward service-attach models. Platform vendors capturing downstream clinical service contracts achieve stickier enterprise relationships than device-only suppliers.
For Market Incumbents: Consolidate enterprise licensing relationships across Texas and Florida Medicare Advantage networks before emerging AI-native vendors achieve FDA software-as-a-medical-device clearance. Defend against cloud hyperscalers by deepening vertical clinical application stacks beyond infrastructure layers. Prioritize backward integration into sensor manufacturing to secure supply continuity.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for predicate-device glucose monitoring submissions open white-space entry in California Medi-Cal maternal health programs. Target underpenetrated pediatric asthma remote monitoring within Central Valley managed care plans. Deploy direct-to-employer occupational health contracting to bypass established payer-channel gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized healthcare sensor divisions. Five-to-ten-year viability hinges on reimbursement code expansion sustaining provider adoption economics. Monitor CMS value-based care program integration timelines as inflection signal for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened clearance timelines capture CMS reimbursement windows before competitive saturation. |
| Hospital System Partnership Expansion | Enterprise agreements with Texas and Florida IDNs lock in multi-year platform commitments. |
| Software Companion Development | AI-driven triage algorithms differentiate beyond commoditized sensor hardware. |
| Reimbursement Strategy Investment | Remote therapeutic monitoring code capture restructures physician practice economics. |
| Geographic Manufacturing Footprint | Domestic sterile patch production reduces port congestion exposure and FDA inspection risk. |
Research Methodology
Desk research of FDA 510(k) clearance databases, CMS reimbursement code filings, and hospital procurement contract disclosures preceded structured interviews with biomedical engineers, GPO contracts managers, Medicare Advantage plan medical directors, and remote monitoring platform product executives. Bottom-up triangulation across device shipment volumes and top-down validation against health system IT spending surveys anchored market sizing. Secondary sources included hospital procurement databases, GPO contract repositories, and CMS Medicare claims extracts.
Variance decomposition across product type, end user, technology maturity, and application use case dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion modeling of provider adoption curves, segmented by reimbursement code availability and clinical workflow integration feasibility. Forecast inputs incorporated Medicare Advantage penetration rates and FDA software-as-a-medical-device guidance evolution.
Decision-makers should treat outputs as directional under assumptions of sustained CMS reimbursement expansion and HIPAA compliance cost trajectories; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Remote Electrocardiogram Monitoring Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Heart Beat Monitor and Sensor Market