
 Bone Cement Mixers Market | 2026-2036
Bone Cement Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Cement Mixers Market Outlook
German orthopedic device manufacturing is consolidating as vacuum-mixing technology becomes standard for hip and knee arthroplasty. Stryker leverages its integrated trauma and reconstruction portfolio to control distribution channels across North American hospital systems. Zimmer Biomet anchors its position through R&D intensity in battery-powered portable mixer platforms. Smith & Nephew competes on brand strength in European surgical centers with cement delivery system bundling.
Bone cement mixers are electromechanical or manually operated devices designed to blend polymethyl methacrylate powder with liquid monomer under controlled vacuum conditions to achieve homogeneous, porosity-reduced cement for implant fixation. These systems operate at rotational speeds between 1,500 and 3,000 RPM with vacuum levels typically maintained at 400–600 mmHg to eliminate air entrapment that compromises mechanical strength. Electric mixers dominate procurement budgets in high-volume orthopedic departments where throughput and consistency determine operating room efficiency. Portable mixers represent the fastest-growing category as ambulatory surgical centers prioritize space-constrained, battery-operated units for outpatient procedures. Manual mixers retain share in cost-sensitive clinics and emerging markets where capital equipment budgets remain restricted.
FDA 510(k) clearance pathways govern mixer safety and electromagnetic compatibility in the United States, while the EU MDR requires renewed clinical evidence and notified body certification for Class IIa devices sold in Europe. The FDA's updated software-as-medical-device guidance increasingly applies to mixers incorporating automated timing and viscosity sensing algorithms. Stakeholders must monitor how FDA premarket submission requirements and EU MDR transition deadlines reshape competitive access timelines for new mixer technologies.
Market Dynamics
Vacuum mixing systems are displacing manual preparation methods in orthopedic departments as cement porosity standards tighten and revision surgery costs pressure hospital procurement committees to prioritize consistency over capital savings.
Growth Catalysts
- EU MDR recertification timelines:The compressed renewal cycle for Class IIa devices accelerates hospital replacement of aging mixer inventories across German, French, and Italian surgical centers.
- Ambulatory surgical center expansion:Outpatient joint replacement volume in United States facilities drives demand for portable, battery-powered mixer platforms that fit space-constrained environments.
- Methyl methacrylate formulation advances:Improved cement viscosity control at lower mixing temperatures enables faster operating room turnover without compromising implant fixation strength.
Market Restraints
- Monomer supply concentration:Liquid methyl methacrylate production clusters among German and Chinese chemical suppliers, exposing mixer manufacturers to feedstock price volatility and allocation constraints.
- Vacuum pump component scarcity:Precision diaphragm pumps for medical-grade vacuum systems face extended lead times from specialized Japanese and German component vendors.
- Capital equipment budget rigidity:Public hospital systems in Southern Europe and Latin America prioritize essential surgical instruments over electromechanical mixers, extending manual method reliance.
Strategic Opportunities
- Indian orthopedic infrastructure buildout:Government medical device parks and import substitution policies create localized manufacturing incentives for mid-range mixer platforms.
- Integrated cement delivery systems:Convergence of mixing, injection, and pressurization functions into single-handpiece designs addresses surgeon workflow efficiency demands.
- United States ASC joint venture models:Device-as-a-service arrangements with orthopedic implant bundling unlock new revenue streams beyond equipment sales.
Industry Challenges
- Biomedical engineer staffing gaps:Operating room technicians trained in vacuum system maintenance and calibration remain scarce in high-volume arthroplasty centers.
- Software validation complexity:FDA 510(k) submissions for mixers incorporating automated viscosity sensing require extensive algorithm documentation and electromagnetic compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Cement Mixers Market |
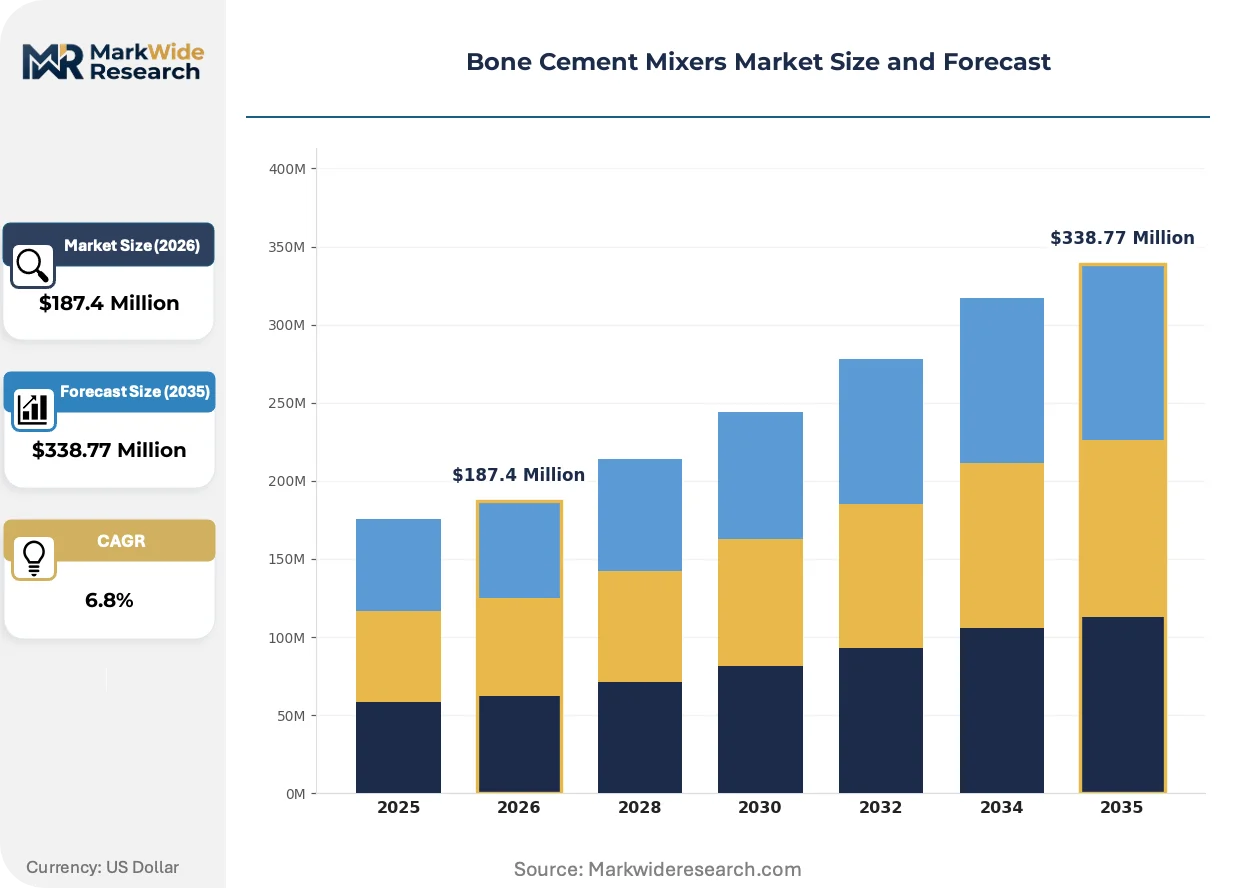
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Mixers, Manual Mixers, Portable Mixers, Industrial Mixers End User: Hospitals, Surgical Centers, Clinics, Research Laboratories Technology: Ultrasonic Mixing, Mechanical Mixing, Magnetic Mixing, Pneumatic Mixing Application: Orthopedic Surgery, Dental Surgery, Veterinary Surgery, Prosthetic Applications |
| Companies Covered | Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Exactech, Heraeus Medical, Tecres, Cardinal Health, MDM Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Cement Mixers Market Strategic Shifts
Battery-powered portable platforms are reshaping competitive positioning as surgical site migration accelerates, while regulatory software requirements and procurement model fragmentation force simultaneous technical and commercial adaptation.
Closed-cartridge mixing systems is expanding into ambulatory surgical centers and mobile surgical units where sterile field maintenance and waste reduction priorities outweigh capital cost considerations. These single-use systems eliminate cross-contamination risks and reduce technician training burdens. The technology is expanding into outpatient hip and knee replacement workflows, compressing equipment sterilization cycles and enabling same-day discharge protocols.
EU MDR technical documentation requirements for Class IIa electromechanical devices now mandate clinical performance data and post-market surveillance systems that many legacy mixer portfolios lack. Manufacturers face notified body bottlenecks and extended conformity assessment timelines. German and Swiss orthopedic device producers are accelerating portfolio rationalization to concentrate resources on MDR-compliant platform submissions.
Hospital purchasing consortia in the United States are consolidating mixer procurement into multi-year implant vendor agreements that bundle cement delivery equipment with joint replacement systems. Independent mixer manufacturers face channel access constraints as integrated suppliers capture preferred vendor status. This concentration is most visible in Southeast and Midwest health system networks where value-based care contracts align device selection with episode cost targets.
Bone Cement Mixers Market Segmentation
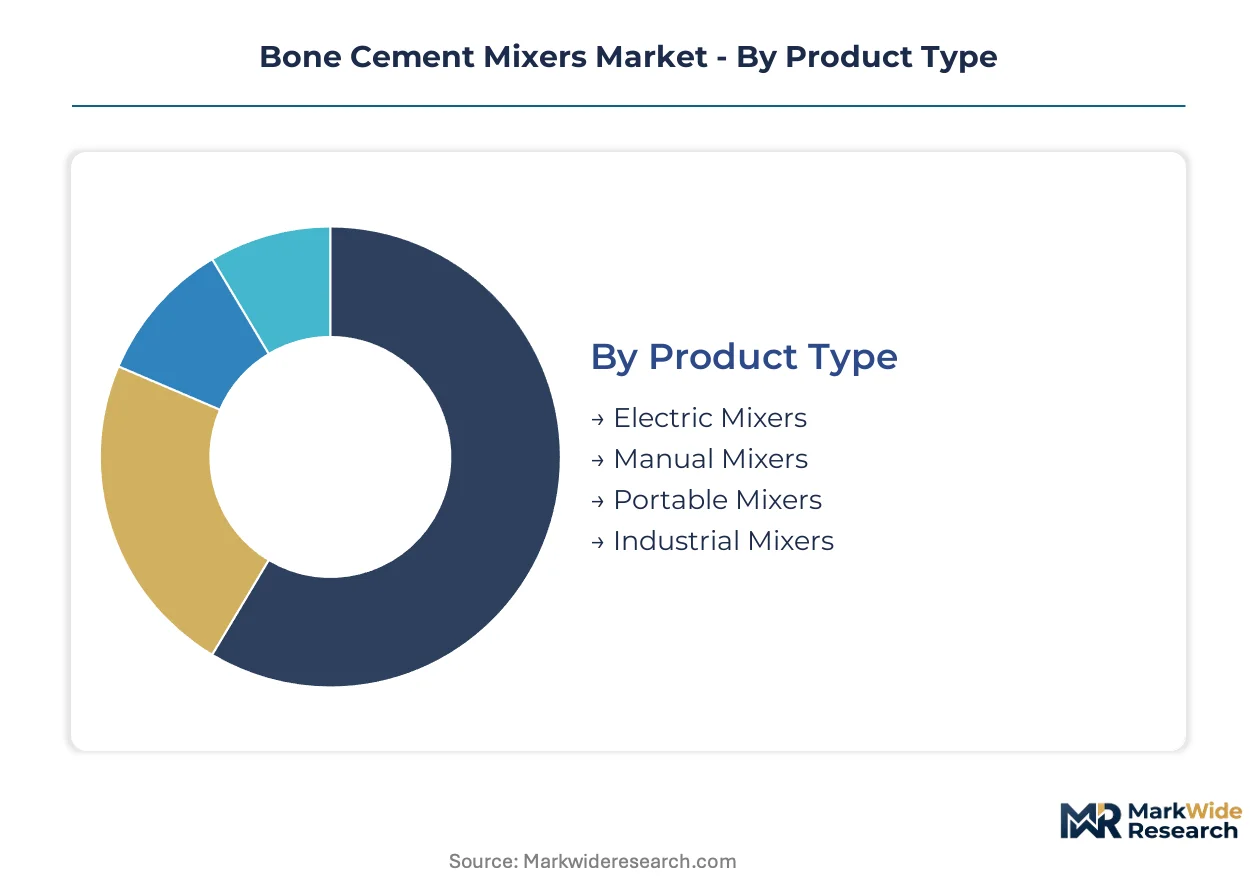
Mixer procurement patterns diverge sharply across clinical settings, with vacuum-mixing specifications, battery portability, and sterilization throughput driving distinct hardware requirements. Technology selection hinges on cement viscosity control precision and operating room turnover targets.
Product Type:
Supply concentration in precision vacuum pump manufacturing favors integrated electromechanical platforms over manual alternatives in high-volume orthopedic departments.
- Electric Mixers:Stationary electromechanical units operate at 1,500–3,000 RPM with integrated vacuum systems maintaining 400–600 mmHg. German hospital systems in Bavaria and North Rhine-Westphalia specify these for revision arthroplasty centers where cement porosity directly impacts implant survival rates.
- Portable Mixers:Battery-powered platforms prioritize space-constrained environments. United States ambulatory surgical centers in Florida and Texas favor these units for outpatient joint replacement workflows where same-day discharge protocols demand equipment mobility.
- Manual Mixers:Hand-cranked devices serve cost-sensitive clinics in Southern Europe and Latin America where capital budgets restrict electromechanical procurement.
- Industrial Mixers:High-capacity units support veterinary medical device manufacturers and research-scale cement formulation facilities.
Electric mixers absorb the bulk of installed capacity; portable mixers are expanding most quickly.
End User:
Procurement authority consolidation across health system networks is reshaping vendor access patterns by facility type.
- Hospitals:Academic medical centers and community hospitals with dedicated arthroplasty programs specify MDR-compliant vacuum mixing systems. French public hospital purchasing consortia centralize mixer procurement alongside implant contracts.
- Surgical Centers:Medicare-certified ASCs performing outpatient total joint arthroplasty drive demand for compact, battery-operated platforms. United States facilities in the Southeast and Midwest prioritize device-as-a-service arrangements over capital purchases.
- Clinics:Private orthopedic practices in Germany and Switzerland maintain manual mixer inventories for low-volume procedures.
- Research Laboratories:Biomechanical testing facilities and cement formulation R&D centers utilize precision mixing equipment for standardized specimen preparation.
Hospitals command the dominant share of equipment value; surgical centers show the steepest expansion trajectory.
Technology:
Mixing modality selection determines cement homogeneity, porosity levels, and regulatory classification complexity.
- Mechanical Mixing:Rotational blade systems dominate commercial installations. FDA 510(k) clearance pathways for these devices are well-established, accelerating market access for manufacturers with electromagnetic compatibility documentation.
- Ultrasonic Mixing:High-frequency vibration technology reduces cement porosity below mechanical alternatives. Japanese orthopedic device producers lead development, though EU MDR clinical evidence requirements delay European commercialization.
- Magnetic Mixing:Stir-bar systems serve laboratory-scale applications and small-batch veterinary cement preparation.
- Pneumatic Mixing:Compressed-air driven systems appear in industrial cement manufacturing and select high-volume hospital installations.
Mechanical mixing retains the largest installed base; ultrasonic systems face regulatory headwinds despite technical advantages.
Application:
Procedure volume and reimbursement structures create divergent equipment specifications across surgical specialties.
- Orthopedic Surgery:Hip and knee arthroplasty procedures generate the primary demand signal. Vacuum mixing systems with automated timing algorithms are becoming standard in German and United States hospital systems where revision surgery costs pressure consistency standards.
- Dental Surgery:Craniomaxillofacial implant fixation utilizes smaller-batch cement preparation. European dental surgical centers specify compact mixers with reduced monomer exposure protocols.
- Veterinary Surgery:Companion animal orthopedic procedures in North American specialty practices drive mid-range mixer demand.
- Prosthetic Applications:External limb prosthesis socket fabrication utilizes manual mixing methods in prosthetic clinics.
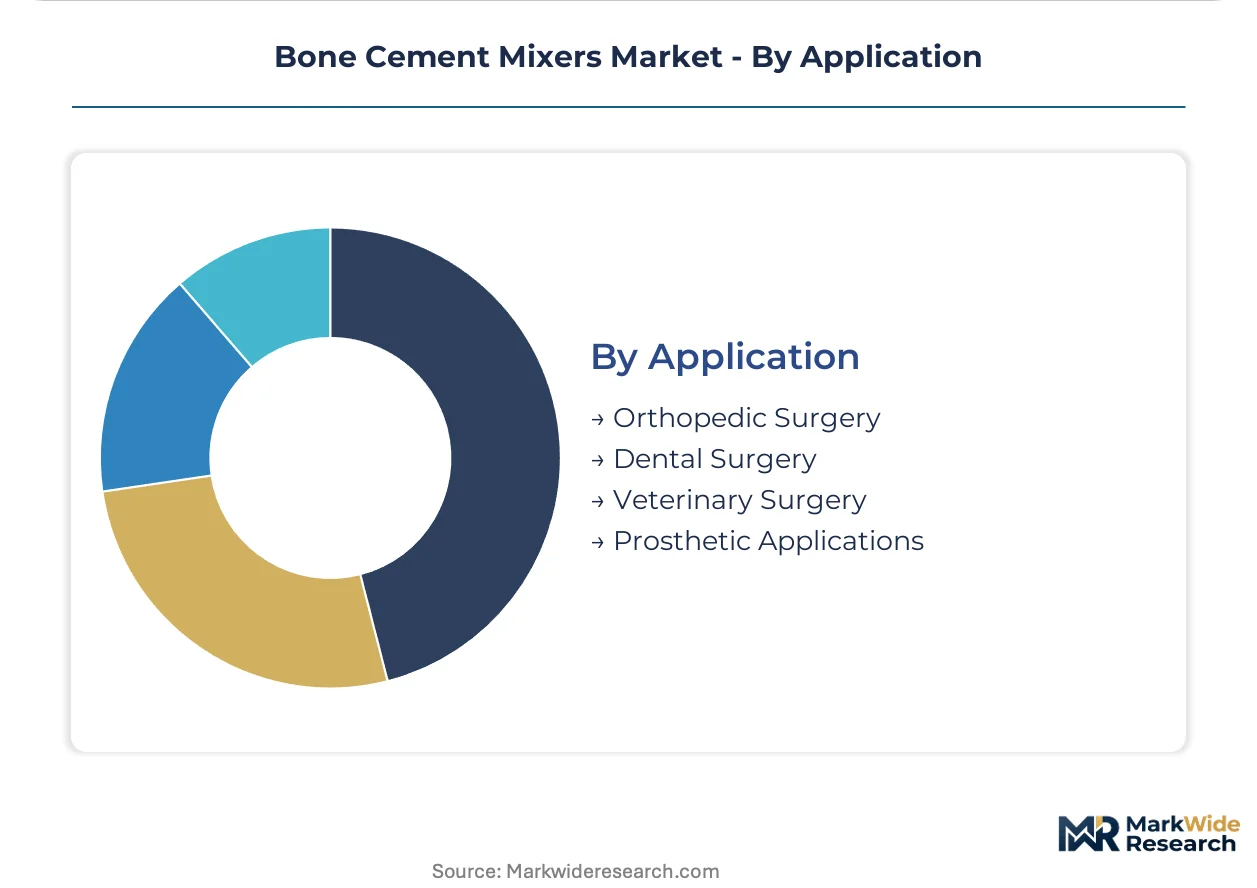
Orthopedic surgery consumes the majority of premium mixer shipments; dental applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methyl methacrylate production clusters in Germany and China anchor supply-side geography for bone cement mixer manufacturing. Hospital procurement patterns diverge sharply between established European arthroplasty centers and rapidly expanding United States ambulatory networks.
United States
Medicare-certified ambulatory surgical centers in Florida and Texas drive portable mixer demand for outpatient joint replacement workflows. FDA 510(k) clearance pathways govern electromagnetic compatibility requirements for battery-powered platforms. The Southeast and Midwest health system networks concentrate device-as-a-service procurement arrangements with orthopedic implant vendors.
Germany
Bavarian and North Rhine-Westphalian hospital systems specify vacuum mixing systems for revision arthroplasty centers where cement porosity standards are tightening. EU MDR recertification timelines compress procurement cycles for Class IIa electromechanical devices. The Frankfurt-Stuttgart medical device corridor hosts concentrated orthopedic manufacturing infrastructure.
China
Domestic methyl methacrylate feedstock availability supports localized mixer assembly for cost-sensitive hospital procurement. NMPA medical device registration requirements govern electromechanical safety standards for imported and domestically produced platforms. The Yangtze River Delta medical device manufacturing belt concentrates component sourcing for mid-range mixer platforms.
Japan
PMDA approval pathways for ultrasonic mixing technology delay commercialization despite technical advantages in porosity reduction. METI industrial standards influence precision vacuum pump specifications for medical-grade applications. The Osaka-Kobe orthopedic device cluster advances high-frequency vibration mixing research for next-generation cement preparation.
India
Government medical device parks under PLI scheme incentives attract mid-range mixer assembly for import substitution. CDSCO medical device rules classify electromechanical mixers under notified device categories requiring registration. The Gujarat and Maharashtra surgical instrument manufacturing corridors expand capacity for battery-powered portable platforms.
Bone Cement Mixers Market Competitive Environment
Global majors compete with regional champions across distribution channel control and implant bundling relationships. The vendor base concentrates around integrated orthopedic conglomerates with trauma and reconstruction portfolios, alongside specialized cement delivery equipment producers. Three archetypes dominate: implant-integrated conglomerates with captive mixer distribution, standalone electromechanical device specialists, and regional surgical instrument fabricators with localized cost positioning. Competitive moves center on multi-year hospital purchasing consortia agreements and R&D intensity in battery-powered portable platforms.
Among implant-integrated conglomerates, Stryker and Zimmer Biomet occupy positions shaped by distribution channel leverage across North American hospital systems. Smith & Nephew sits within the European surgical center tier where brand strength in cement delivery system bundling anchors market presence. These three exemplify how portfolio breadth and geographic footprint alignment determine competitive access to high-volume arthroplasty centers.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson |
| Exactech |
| Heraeus Medical |
| Tecres |
| Cardinal Health |
| MDM Medical |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between MDR-compliant vacuum systems and manual alternatives splits procurement budgets across European hospital systems, with after-sales service bundling and warranty coverage determining effective cost structures alongside component sourcing geography.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium electromechanical platforms from unbundled manual alternatives in hospital purchasing decisions. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR certification status, battery portability specifications, and vacuum pump precision grades. Cost compression in the mid-range portable segment is intensifying because ambulatory surgical centers prioritize capital efficiency over feature depth. Price-sensitive buyers cluster among Latin American public hospital systems, while German academic medical centers show lowest sensitivity due to revision-surgery cost accountability.
Supply Chain Analysis
Freight cost differentials between precision vacuum pump imports from Japan and regional assembly in China shape landed cost structures for mixer manufacturers. Production gravity centers on Germany for high-specification electromechanical units, China for mid-range battery-powered platforms, and Switzerland for precision diaphragm pump components. Liquid methyl methacrylate monomer and medical-grade polycarbonate housings constitute critical input dependencies. Single-source vulnerability concentrates in Japanese precision pump vendors, exposing manufacturers to allocation constraints. Distribution runs through orthopedic implant vendor bundling agreements in United States health system networks and direct hospital procurement in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR technical documentation requirements for Class IIa devices erect substantial barrier-to-entry moats favoring incumbents with notified body relationships and clinical evidence portfolios.
For Market Incumbents: Hedge against portable platform commoditization by deepening backward integration into precision vacuum pump production and securing multi-year GPO contracts with United States health system networks before MDR recertification deadlines compress replacement cycles. Battery chemistry supply agreements and electromagnetic compatibility pre-certification investments represent critical defensive levers against emerging Asian competitors. For New Entrants and Emerging Players: Ambulatory surgical center procurement managers in the United States Southeast and Midwest represent the most penetrable channel partner type given device-as-a-service model receptivity and implant bundling disruption opportunities. White-space targets include mid-range portable platforms for Indian government medical device parks and closed-cartridge mixing systems for mobile surgical units. A software-as-medical-device regulatory strategy accelerates FDA pathway access against hardware-incumbent timelines. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical device specialists possessing EU MDR-compliant portfolios and established notified body relationships given compressed recertification timelines and hospital replacement cycle acceleration. Long-term viability over the next decade hinges on software-enabled viscosity sensing capabilities and integrated cement delivery system convergence. The signal to watch is FDA 510(k) clearance velocity for algorithm-driven mixing platforms as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates notified body conformity assessment timelines for Class IIa electromechanical platforms. |
| Battery Chemistry Supply Agreement | Secures lithium-ion cell allocation for portable mixer production amid component scarcity. |
| Hospital System Partnership | Unlocks preferred vendor status in United States GPO bundling arrangements for joint replacement workflows. |
| Software Companion Development | Positions automated viscosity sensing algorithms under FDA software-as-medical-device guidance pathways. |
| Backward Integration into Vacuum Pumps | Reduces lead time exposure from Japanese and German precision diaphragm pump vendors. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body bottlenecks, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with biomedical engineers, orthopedic surgeons, GPO contracts managers, and cement delivery system product managers. Primary fieldwork combined with secondary validation against FDA premarket notification databases, EUDAMED device registration records, hospital procurement databases, and orthopedic implant vendor SEC filings. Bottom-up shipment modeling and top-down healthcare expenditure triangulation cross-verified volume and value estimates.
Segment-weighting across product type, end user facility category, mixing technology modality, and surgical application determined value distribution across the projection horizon. CAGRs derived from procedure volume elasticity to cement mixer penetration rates, ambulatory surgical center expansion trajectories, and MDR-driven replacement cycle compression. Industry-specific forecast inputs incorporated methyl methacrylate monomer price volatility indices and precision vacuum pump lead time surveys from Japanese component vendors.
Several conditions sit outside the modeled scope, including unforeseen regulatory delays in EU MDR implementation, acute monomer supply disruptions from German chemical producers, and technological substitution by alternative implant fixation methods. Forecasts reflect documented assumptions about hospital capital equipment budget trajectories and outpatient joint replacement reimbursement stability. Stakeholders should weight assumptions against their own operating context and procurement cycle exposure to notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Radiology Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Root Canal Irrigators Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Sterile Filtration Module Market