
 Data Buoy Market | 2026-2036
Data Buoy Market Size, Share, and Industry Trends Forecast 2026-2036
Data Buoy Market Insights
Marine telemetry engineering talent is collapsing across coastal manufacturing zones, forcing buoy makers to restructure production footprints. AXYS Technologies sustains its North American position through captive fabrication of harsh-environment hull systems. Develogic GmbH anchors European demand with deep-rated mooring solutions for Arctic deployments. Fugro N.V. competes on integrated survey-to-buoy service bundles that reduce client procurement complexity.
A data buoy is a moored or drifting floating platform engineered to house meteorological, oceanographic, or navigational sensors, typically rated for sustained operation in sea states up to 12 meters significant wave height with power budgets spanning solar, battery, and fuel-cell architectures. Its primary purpose is to transmit real-time environmental or positional data to shore stations or satellite networks for operational decision-making. Sensor-embedded buoys occupy the deepest margin pools where multi-parameter payloads command premium pricing against single-sensor alternatives. Autonomous buoys represent the fastest-expanding product category as navies and energy operators eliminate tether dependencies. Wireless communication technology underpins this shift by enabling mesh-networked swarms without surface radio infrastructure.
The International Maritime Organization's AIS carriage requirements shape navigation buoy specifications, while EPA water-quality monitoring mandates in the United States and the EU Marine Strategy Framework Directive drive environmental buoy procurement volumes. ISO 19848 compliance for sensor data interoperability increasingly gates market access for non-integrated suppliers. Stakeholders must weigh sovereign data-localization rules against cloud-architecture cost advantages when designing next-generation telemetry stacks.
Market Dynamics
Marine telemetry engineering scarcity is compressing production timelines and forcing buoy manufacturers toward captive fabrication models. The EU Marine Strategy Framework Directive mandates continuous ecosystem monitoring, tightening delivery windows for compliant platforms.
Growth Catalysts
- EU Marine Strategy Framework Directive:Member-state waters now require continuous data collection, mandating buoy deployments across the North Sea and Baltic approaches. Environmental compliance budgets are hardening into capital expenditure lines.
- Arctic energy exploration:Deep-rated mooring systems for ice-infested waters command premium positioning as Norway expands subsea corridor activity around Bergen and Trondheim.
- Wireless mesh networking:Autonomous swarms eliminate surface radio infrastructure dependencies, enabling navies and offshore operators to deploy untethered sensor arrays.
Market Restraints
- Marine-grade aluminum and titanium volatility:Hull material costs fluctuate with aerospace and defense procurement cycles, squeezing margin pools on fixed-price contracts.
- Norwegian subsea technology corridor concentration:Deep-rated mooring engineering talent clusters around Stavanger and Oslo, creating single-point vulnerability for Arctic-capable systems.
- ISO 19848 interoperability gates:Non-integrated sensor suppliers face market access barriers as procurement specifications harden around standardized data formats.
Strategic Opportunities
- India coastal monitoring expansion:The country's national maritime regulator is mandating port approach surveillance, opening procurement channels for wave and current monitoring platforms.
- Fuel-cell power architecture convergence:Solid oxide fuel cells paired with solar-battery hybrids extend deployment endurance beyond 24 months in high-latitude deployments.
- Cloud-architecture telemetry stacks:Sovereign data-localization rules in Germany and France are creating demand for edge-computing buoy designs that preprocess sensor streams before satellite uplink.
Industry Challenges
- Embedded systems firmware engineering scarcity:Real-time operating system expertise for harsh-environment sensor integration is collapsing across coastal manufacturing zones.
- CE marking and MDR compliance timelines:Certification bodies in the Netherlands and Germany are extending review periods for marine electronics, delaying revenue recognition on new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Buoy Market |
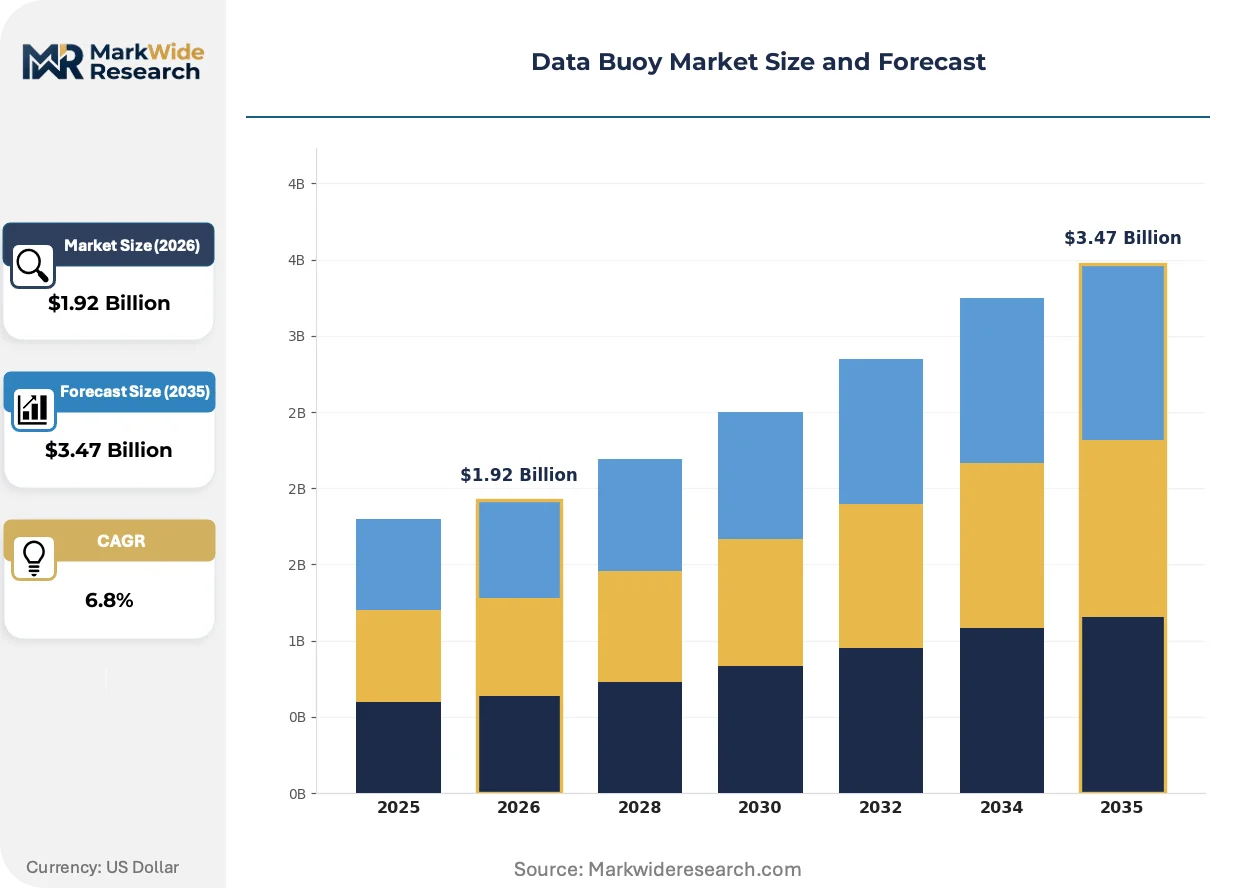
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Buoys, Research Buoys, Sensor-embedded Buoys, Navigation Buoys Technology: Remote Sensing, Wireless Communication, GPS Integration, Data Acquisition Application: Environmental Monitoring, Oceanographic Research, Marine Safety, Data Collection End User: Government Agencies, Research Institutions, Commercial Organizations, Environmental NGOs |
| Companies Covered | Aanderaa Data Instruments AS, AXYS Technologies, Inc., Develogic GmbH, Fugro N.V., JFC Manufacturing Co., Ltd., MetOcean Telematics, NexSens Technology, Inc., Smart Buoy Co., Planet Ocean Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Buoy Market Trends and Innovations
Power architecture and communication protocols are splitting the product map into endurance-optimized and bandwidth-optimized lineages. Platform differentiation now hinges on energy budgeting rather than sensor payload breadth.
Solid oxide fuel-cell systems are bifurcating the power architecture market. These platforms sustain multi-year deployments without solar exposure, attracting Arctic and sub-Arctic operators. High-latitude energy contractors are specifying fuel-cell hybrids as baseline requirements. The technology is compressing the addressable market for pure battery-solar configurations in ice-edge zones.
REACH substance restrictions on persistent organic pollutants are reshaping hull coating specifications. Anti-fouling formulations must now exclude legacy biocides, forcing reformulation of protective layers. Norwegian and Danish procurement offices are rejecting non-compliant platforms from tender pools. Manufacturers are accelerating fluoropolymer alternative qualification to maintain North Sea access.
Integrated survey-to-buoy service bundling is displacing component procurement patterns. Offshore energy operators now contract environmental monitoring as operational expenditure rather than capital projects. Norwegian state-controlled energy entities are leading this shift. The model is compressing standalone buoy sales cycles while extending vendor-client contract tenures.
Data Buoy Market Segmentation
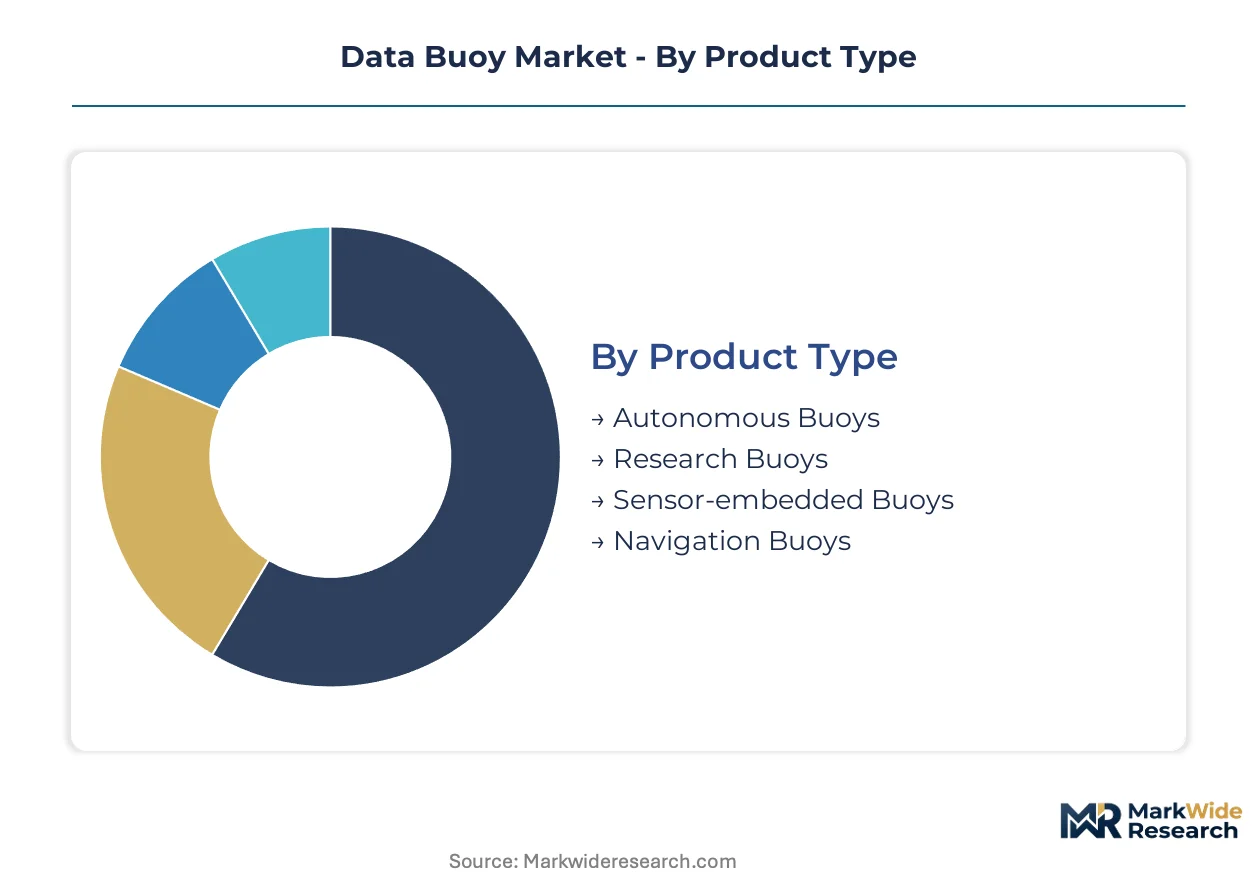
Segmentation in the Data Buoy Market reflects divergent certification requirements across deployment zones. Product architecture and telemetry specifications vary sharply between regulatory jurisdictions, creating distinct procurement pools.
Product Type:
CE marking and MDR compliance timelines in the Netherlands and Germany extend certification periods for marine electronics, compressing delivery windows for non-captive manufacturers.
- Autonomous Buoys:Untethered platforms deploy solid oxide fuel-cell hybrids for multi-year endurance in ice-edge zones without solar exposure. Norwegian energy contractors around Bergen specify these as baseline for Arctic corridor operations.
- Sensor-embedded Buoys:Multi-parameter payloads integrate meteorological, oceanographic, and water-quality sensors in ISO 19848-compliant data formats. EPA monitoring mandates in the United States and EU Marine Strategy Framework Directive requirements concentrate procurement in North Sea and Baltic approaches.
- Research Buoys:Configurable hull systems support academic and institutional field campaigns with modular sensor bays.
- Navigation Buoys:International Maritime Organization AIS carriage specifications govern transmitter power and visibility standards.
Sensor-embedded buoys handle the majority of throughput; autonomous buoys are climbing the fastest on share.
Technology:
Power budgeting rather than sensor breadth now determines platform selection, with communication protocols splitting procurement between endurance-optimized and bandwidth-optimized lineages.
- Wireless Communication:Mesh-networked swarms eliminate surface radio infrastructure dependencies for navies and offshore operators. Norwegian subsea technology corridors deploy these arrays for untethered environmental monitoring.
- Remote Sensing:Satellite-uplinked telemetry streams support sovereign data-localization requirements in Germany and France through edge-computing preprocessing.
- GPS Integration:Precise positional tracking enables drift-corrected current mapping and asset geofencing.
- Data Acquisition:Real-time operating system firmware manages harsh-environment sensor integration with compressed production timelines.
Wireless communication dominates capital deployment; remote sensing shows steepest expansion trajectory as edge-computing architectures mature.
Application:
Operational expenditure contracting is displacing capital procurement patterns, with integrated service bundling extending vendor-client tenures.
- Environmental Monitoring:Continuous ecosystem data collection mandated by EU Marine Strategy Framework Directive hardens compliance budgets into capital expenditure lines across member-state waters.
- Oceanographic Research:Academic institutions and government laboratories deploy configurable platforms for long-term climate and current studies.
- Marine Safety:Port approach surveillance requirements from India's national maritime regulator open procurement channels for wave and current monitoring platforms.
- Data Collection:Standardized sensor streams support operational decision-making for offshore energy and shipping logistics.
Environmental monitoring absorbs the largest procurement volume; marine safety is gaining share fastest from regulatory expansion in Asian waters.
End User:
Procurement authority concentration varies by funding source, with state-controlled energy entities leading the shift toward operational expenditure models.
- Government Agencies:Sovereign data-localization rules in Germany and France drive demand for edge-computing buoy designs that preprocess sensor streams before satellite uplink.
- Commercial Organizations:Offshore energy operators contract environmental monitoring as operational expenditure rather than capital projects, compressing standalone buoy sales cycles.
- Research Institutions:Academic procurement prioritizes modular payload flexibility over deployment endurance.
- Environmental NGOs:Non-governmental monitoring programs specify REACH-compliant hull coatings excluding legacy biocides.
Government agencies account for the dominant procurement volume; commercial organizations are expanding most quickly as service bundling displaces component sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deployment patterns diverge sharply by latitude: high-latitude operators prioritize ice-rated mooring endurance over sensor density, while equatorial procurement emphasizes bandwidth-optimized telemetry for real-time current mapping.
Norway
Arctic corridor expansion around Bergen and Trondheim drives demand for deep-rated autonomous platforms. The EU Marine Strategy Framework Directive mandates continuous ecosystem monitoring in Norwegian waters, hardening compliance budgets into capital expenditure lines. Stavanger anchors subsea technology engineering clusters where mooring system specialists concentrate.
United States
EPA water-quality monitoring mandates concentrate procurement in Great Lakes and Gulf Coast watersheds. The International Maritime Organization's AIS carriage requirements shape navigation buoy specifications for port approach surveillance. Pacific Northwest fabrication yards sustain captive hull production for harsh-environment deployments.
Germany
Sovereign data-localization rules under GDPR and national cybersecurity frameworks drive edge-computing buoy designs that preprocess sensor streams. CE marking and MDR compliance timelines extend certification periods for marine electronics. Hamburg and Bremerhaven harbor zones cluster telemetry systems integrators serving North Sea operators.
India
The country's national maritime regulator mandates port approach surveillance, opening procurement channels for wave and current monitoring platforms. Coastal infrastructure programs under the Sagarmala initiative fund harbor modernization. Gujarat and Maharashtra maritime zones concentrate domestic platform assembly capacity.
United Kingdom
North Sea decommissioning and offshore wind expansion sustain demand for integrated survey-to-buoy service bundles. The Marine Strategy Framework Directive implementation tightens delivery windows for compliant environmental monitoring platforms. Aberdeen maintains subsea engineering density despite talent migration pressures.
Data Buoy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding service-bundled contracts and the lower tier competing on component customization. The middle band fragments across regional fabrication yards and sensor-integrator boutiques. Two archetypes dominate: captive hull fabricators with in-house metalworking capacity, and mooring-system specialists with deep-rated engineering depth. Competitive moves concentrate on backward integration into power architecture production and geographic expansion through local certification partnerships.
Among North American fabricators, AXYS Technologies, Inc. exemplifies the captive-production archetype through sustained control over harsh-environment hull systems. Develogic GmbH anchors European positioning with deep-rated mooring solutions. Fugro N.V. occupies the integrated-service tier, representing the bundle-to-contract model that compresses standalone platform sales cycles.
| Leading Market Players |
|---|
| Aanderaa Data Instruments AS |
| AXYS Technologies, Inc. |
| Develogic GmbH |
| Fugro N.V. |
| JFC Manufacturing Co., Ltd. |
| MetOcean Telematics |
| NexSens Technology, Inc. |
| Smart Buoy Co. |
| Planet Ocean Ltd |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month delivery windows for ISO 19848-compliant platforms concentrate pricing power with captive hull fabricators in Norway and Germany, while spot buyers absorb premium markups from certification bottlenecks at Dutch and German notified bodies.
Pricing Analysis
Long-term offtake contracts dominate procurement between Norwegian energy operators and mooring-system specialists, compressing spot-market liquidity for autonomous platforms. Price differentiation rests on CE marking tier and Arctic endurance rating, with ice-rated configurations commanding substantial premiums over temperate-zone alternatives. Cost compression in sensor-embedded categories intensifies as EPA and EU environmental mandates harden compliance budgets into standardized procurement lines. Government agencies exhibit lowest price sensitivity due to sovereign data-localization requirements, while research institutions face acute budget constraints.
Supply Chain Analysis
Norway and Germany anchor deep-rated mooring engineering and hull fabrication respectively, with Pacific Northwest yards sustaining captive production for North American deployments. Marine-grade aluminum and titanium feed from aerospace and defense procurement cycles, while solid oxide fuel-cell stacks draw from specialized industrial gas suppliers. Single-source vulnerability clusters around Stavanger's subsea technology corridor for Arctic-capable systems. Distribution runs through integrated survey-to-buoy service bundles that displace component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Buoy Market is recovering from a cyclical trough as EU Marine Strategy Framework Directive mandates harden environmental compliance budgets into sustained capital expenditure lines across member-state waters.
For Market Incumbents: Fortify backward integration into power architecture production to capture margin pools eroding from fuel-cell and battery cost volatility. Deepen captive hull fabrication capacity in Bergen and Trondheim corridors to defend against emerging sensor-integrator boutiques gaining certification velocity through Dutch notified bodies. For New Entrants and Emerging Players: Post-deployment telemetry service gaps in India's Sagarmala-funded harbor modernization offer white-space entry with lower certification barriers than North Sea markets. Target marine safety applications for port approach surveillance, leveraging wireless mesh networking expertise to bypass incumbent mooring-system lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant marine telemetry divisions holding ISO 19848 compliance assets. Long-term viability hinges on fuel-cell hybrid architecture ownership and Arctic deployment track records. Watch for Norwegian state-controlled energy entities converting capital expenditure contracts to operational expenditure service bundles as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel-Cell Hybrid Power Architecture | Extends deployment endurance beyond solar-dependent limits in high-latitude zones. |
| Edge-Computing Telemetry Stack | Addresses German and French sovereign data-localization requirements before satellite uplink. |
| REACH-Compliant Hull Coating Qualification | Maintains North Sea access as Norwegian and Danish procurement offices reject legacy biocides. |
| Integrated Survey-to-Buoy Service Bundle | Captures operational expenditure contracting shift led by Norwegian state energy entities. |
| Wireless Mesh Network Deployment | Eliminates surface radio infrastructure dependencies for untethered autonomous swarms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with offshore energy procurement officers, marine telemetry systems integrators, subsea mooring engineers, and environmental compliance managers at regulatory agencies. Secondary validation drew from EPA water-quality monitoring mandates, EU Marine Strategy Framework Directive implementation documents, ISO 19848 interoperability standards, and customs records for marine-grade aluminum and titanium trade flows. Bottom-up platform deployment estimates were triangulated against top-down energy sector capital expenditure disclosures.
Across the projection horizon, the analytical framework modeled segmentation by product architecture, power system configuration, deployment latitude, and end-user procurement authority. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory mandate timelines and fuel-cell cost learning curves. Forecast inputs included Norwegian subsea corridor expansion rates and Indian port modernization funding allocations under Sagarmala.
Forecasts assume regulatory continuity in EU Marine Strategy Framework Directive implementation and EPA monitoring mandate enforcement; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in Arctic energy exploration licensing and sovereign data-localization rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Heat Stress Meter Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Mobile Lidar Scanner Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Digital Olfaction Products Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Connected Smart Thermostats Market
Sensors
Lidar in Construction Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Automated Weather Observation System Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Lidar in Mapping Market
Sensors
Handheld RFID Readers Market
Sensors
Global Weather Monitoring Solutions and Services Market