
 Global Positioning Systems Market | 2026-2036
Global Positioning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Positioning Systems Market Analytics
Semiconductor foundry capacity in Taiwan is decoupling from legacy GPS-only chipset production as multi-constellation demand surges. Trimble Inc. anchors its position through backward integration into correction service networks for surveying and agriculture. Qualcomm Technologies, Inc. dominates smartphone GNSS silicon by embedding L5-band support directly into mobile SoC platforms. Garmin Ltd. specializes in ruggedized outdoor navigation hardware that commands durable margins across recreational and professional segments.
Global Positioning Systems comprise satellite-based radio-navigation infrastructure and receiver terminals that calculate precise three-dimensional position, velocity, and timing (PVT) data through trilateration of signals from multiple orbital constellations. The technology enables geospatial coordination across transportation, telecommunications synchronization, and precision agriculture operations where sub-meter accuracy determines operational efficiency. Automotive Navigation applications lead value generation as OEMs integrate real-time kinematic positioning for lane-level guidance, while Location-based Services represent the fastest-expanding service type as retail and logistics operators deploy geofencing analytics. BeiDou technology is gaining structural share in Asia-Pacific industrial deployments where dual-frequency capability supports centimeter-level precision without foreign constellation dependency.
The Federal Communications Commission in the United States enforces GPS receiver standards that shape spectrum coexistence with adjacent wireless services, while Europe's Galileo program operates under ESA and GSA governance that mandates PRS-access security protocols for government users. China's MIIT administers BeiDou terminal certification through national encryption modules that restrict market access for non-domestic suppliers. Stakeholders must monitor constellation modernization timelines and spectrum reallocation proceedings to align R&D roadmaps with shifting regulatory access requirements.
Market Dynamics
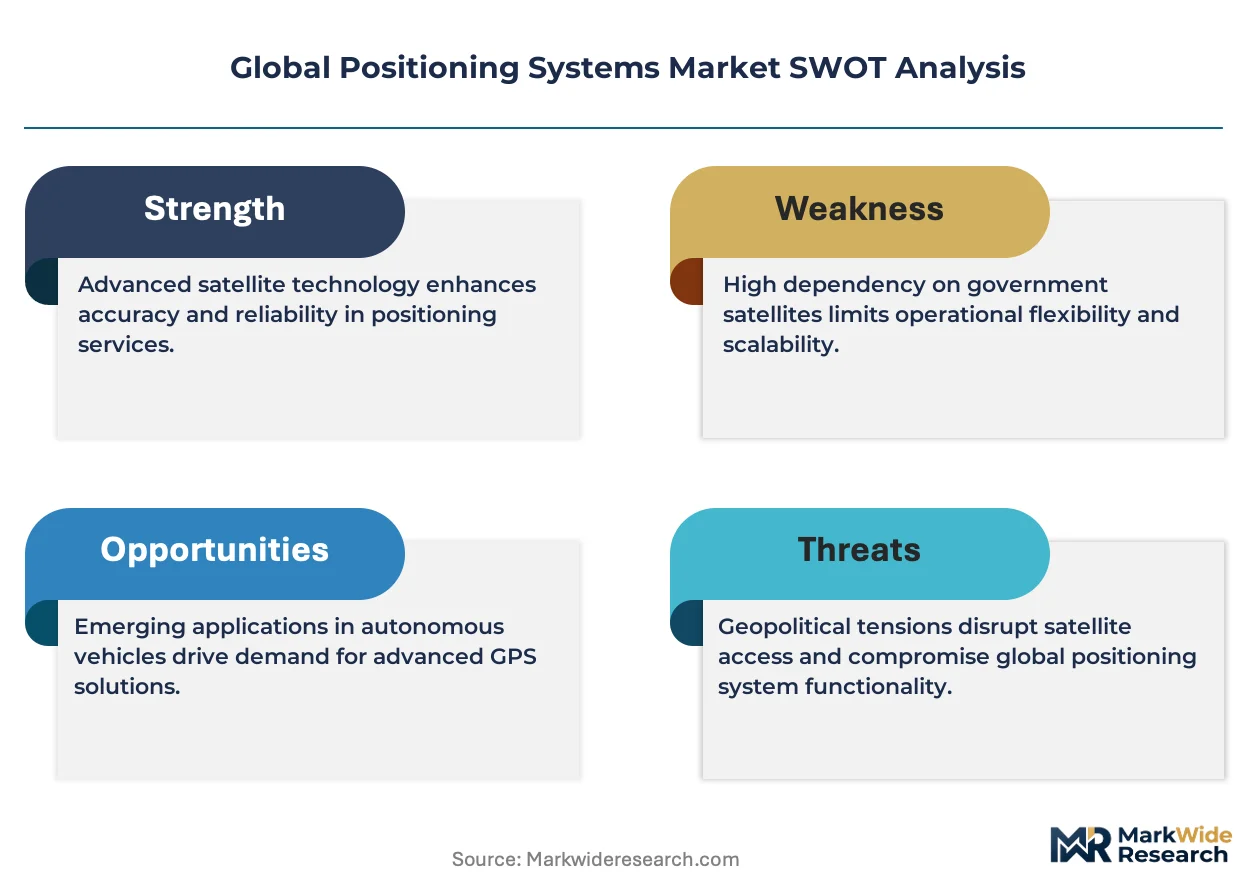
Multi-constellation receiver architectures are forcing a wholesale redesign of RF front-end silicon, as automotive and precision agriculture OEMs abandon single-system GPS modules for fused GNSS solutions that leverage BeiDou, Galileo, and GLONASS simultaneously.
Growth Catalysts
- Automotive RTK Mandates:Lane-level navigation requirements in connected vehicle platforms are pulling high-precision positioning into mass-market production lines.
- EASA Precision Approach Standards:Tightened certification thresholds for aviation-grade receivers are accelerating hardware refresh cycles across European commercial air transport.
- China's BeiDou Industrial Policy:Domestic terminal subsidies and encryption module mandates are displacing legacy GPS dependence in industrial IoT deployments.
Market Restraints
- Semiconductor Foundry Concentration:Advanced RF-CMOS capacity at Taiwan-based fabs creates supply vulnerability for multi-band receiver ASICs.
- Spectrum Adjacency Friction:FCC Part 15 enforcement actions against interference-generating devices constrain receiver sensitivity thresholds in dense urban RF environments.
- Lithium-Ion Battery Cost Volatility:Ruggedized portable terminals face margin pressure from cathode material price swings affecting power subsystem economics.
Strategic Opportunities
- Indian Precision Agriculture:Subsidy programs for farm mechanization are opening deployment channels for affordable RTK-enabled guidance systems.
- 5G Network Timing Convergence:Synchronization requirements for Open RAN infrastructure are creating demand for multi-GNSS disciplined oscillators in telecom base stations.
- Japan's Disaster Resilience Mandates:QZSS augmentation integration requirements for critical infrastructure are driving specialized receiver development.
Industry Challenges
- RF System Integration Complexity:Fading mitigation algorithms for multi-path urban environments require scarce expertise in adaptive filtering and signal processing.
- EASA Certification Timeline Compression:Aviation hardware validation cycles now extend 18-24 months, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Positioning Systems Market |
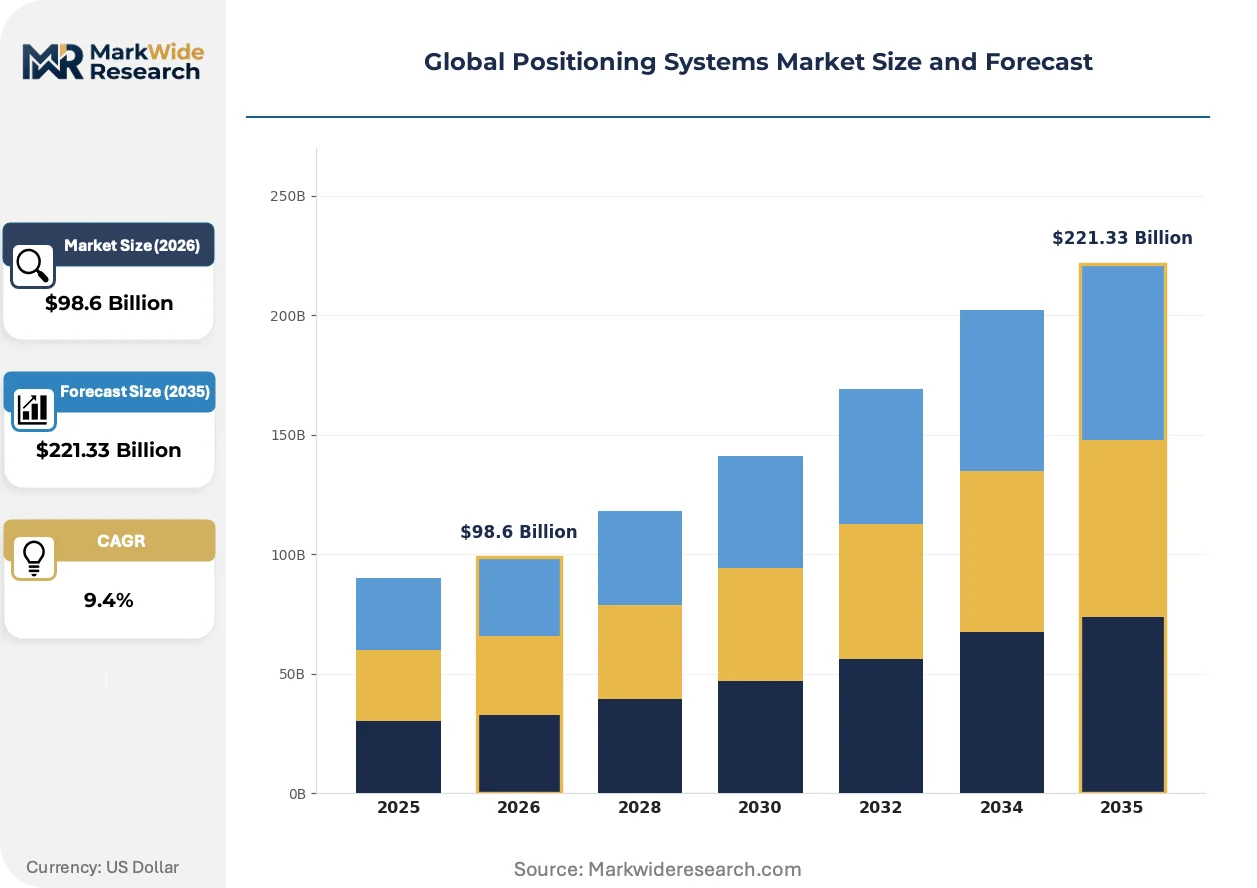
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive Navigation, Mobile Devices, Aviation, Marine Navigation Technology: GPS, GLONASS, BeiDou, Galileo End User: Government, Defense, Commercial, Consumer Service Type: Mapping, Tracking, Navigation, Location-based Services |
| Companies Covered | Garmin Ltd., Trimble Inc., Qualcomm Technologies, Inc., Broadcom Inc., Hexagon AB, TomTom International BV, Collins Aerospace, u-blox AG, Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Positioning Systems Market Evolving Landscape
Receiver architecture is converging toward software-defined positioning engines that decouple signal acquisition from baseband processing, enabling field-upgradable constellation support without hardware redesign.
Dual-frequency L1/L5 reception is consolidating as the baseline specification for automotive-grade modules, with silicon vendors embedding broadband RF chains directly into vehicle gateway SoCs. Tier-1 suppliers are adopting these platforms for 2027 model-year advanced driver-assistance systems. The technology is consolidating position-fix availability in urban canyon environments where single-frequency receivers experience frequent signal blockage.
Europe's CSRD sustainability disclosure requirements are mandating supply chain traceability for critical minerals in electronic components, affecting receiver manufacturers sourcing rare-earth elements for antenna substrates. Industrial customers now audit smelter documentation before qualifying new positioning hardware. Automotive OEMs with German manufacturing footprints are responding by qualifying alternative antenna ceramic formulations.
Buyer concentration among hyperscale logistics operators is compressing procurement cycles for fleet telematics hardware, with contract terms shifting from capital purchase to per-vehicle-month subscription models. Equipment lessors are capturing margin that previously accrued to hardware vendors. This pattern is most visible in North American long-haul trucking where three national carriers account for substantial annual receiver demand.
Global Positioning Systems Market Segmentation
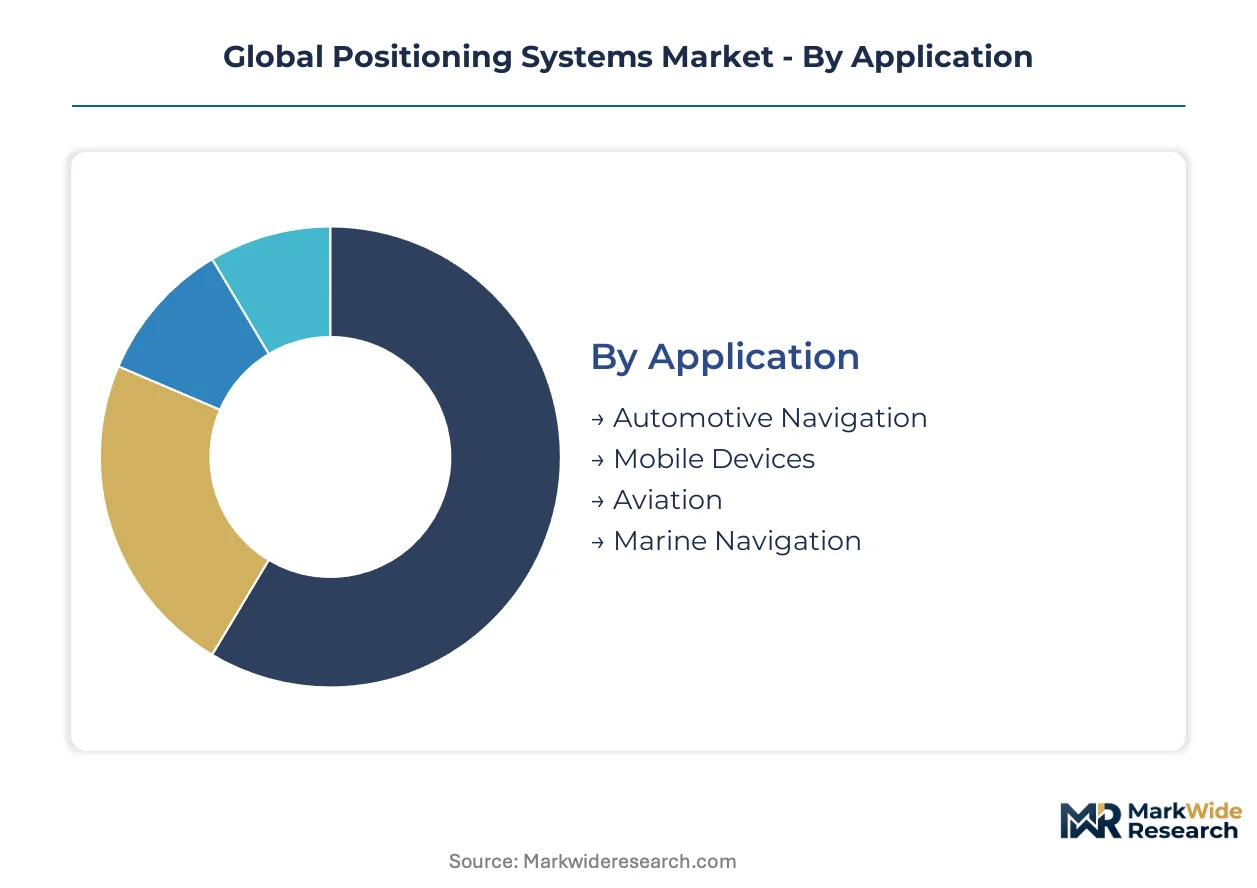
Positioning hardware and service procurement patterns diverge sharply across application contexts, with automotive OEMs demanding automotive-grade certification stacks while consumer electronics prioritize silicon integration density. End-user risk profiles and accuracy requirements reshape component sourcing strategies across each segment boundary.
Application:
Standardization dominates high-volume automotive contracts, whereas marine and aviation applications retain bespoke configuration requirements for certification compliance.
- Automotive Navigation:Multi-frequency receiver modules integrate directly into vehicle gateway SoCs, with L1/L5 dual-band reception now baseline for lane-level guidance. German and Japanese OEMs are pulling real-time kinematic positioning into mass-market production lines for advanced driver-assistance systems.
- Mobile Devices:GNSS silicon embeds into smartphone application processors with L5-band support for urban canyon performance. Qualcomm dominates this tier through direct integration into mobile SoC platforms, displacing discrete receiver modules.
- Aviation:EASA-certified precision approach hardware requires multi-constellation redundancy and aviation-specific interference rejection algorithms.
- Marine Navigation:Ruggedized terminals with differential correction service subscriptions support commercial fishing and offshore energy operations.
Most installed capacity flows through Automotive Navigation. Expansion is steepest in Mobile Devices.
Technology:
Cost tiers separate legacy single-constellation modules from multi-system fusion architectures now standard in precision applications.
- GPS:Legacy L1-only receivers retain presence in low-cost asset tracking, though module shipments are plateauing as customers migrate to multi-constellation alternatives. US-based fleet operators still specify GPS-first compatibility for backward integration with existing telematics infrastructure.
- BeiDou:Dual-frequency B1I/B2a capability supports centimeter-level precision without foreign constellation dependency. China's MIIT administers terminal certification through national encryption modules that restrict market access for non-domestic suppliers.
- GLONASS:Russian constellation provides high-latitude coverage advantages for Arctic shipping and northern aviation corridors.
- Galileo:European system mandates PRS-access security protocols for government users through ESA and GSA governance frameworks.
Receiver production concentrates on BeiDou-compatible architectures. Galileo adoption is climbing the fastest among European government and defense procurement channels.
End User:
Volume scales inversely with margin structure, with defense and government contracts commanding certification premiums while consumer shipments drive silicon foundry utilization.
- Commercial:Logistics operators and precision agriculture contractors purchase RTK-enabled guidance systems through equipment financing arrangements. North American long-haul trucking fleets are compressing procurement cycles with per-vehicle-month subscription terms.
- Consumer:Outdoor recreation and fitness wearable markets demand ruggedized hardware with durable margins. Garmin captures this tier through specialized navigation devices distinct from smartphone-integrated alternatives.
- Government:Critical infrastructure timing and surveying applications require encrypted signal authentication and domestic supply chain verification.
- Defense:Military receivers incorporate anti-jamming and anti-spoofing countermeasures with classified performance specifications.
Commercial deployments account for the largest installed base. Defense procurement is gaining share fastest through allied nation modernization programs.
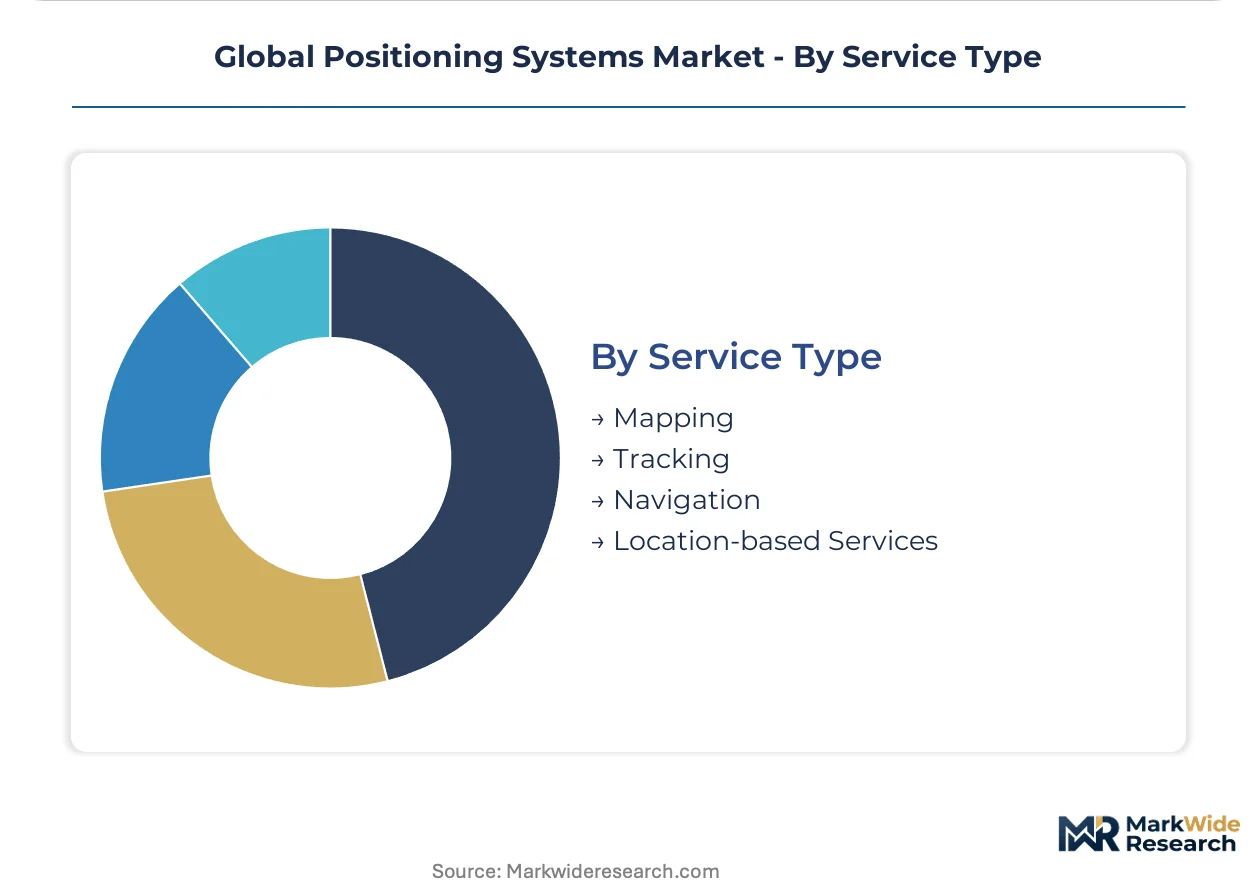
Service Type:
Customer type determines revenue model structure, with navigation and tracking services shifting toward recurring subscription frameworks while mapping retains project-based contracting.
- Navigation:Real-time route optimization and lane-level guidance services monetize through automotive OEM licensing and smartphone application integration.
- Location-based Services:Geofencing analytics and proximity marketing platforms serve retail and logistics operators. Retail chains in the United States and United Kingdom are deploying indoor-outdoor positioning fusion for customer journey mapping.
- Tracking:Fleet telematics and asset monitoring solutions combine cellular connectivity with periodic GNSS fixes for battery-constrained devices.
- Mapping:High-precision surveying and geographic information system data collection rely on correction service network subscriptions.
Navigation services carry the heaviest transaction volume. Location-based Services are expanding most quickly as retail operators deploy spatial analytics infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing multi-constellation receiver production toward jurisdictions with favorable certification cost structures. Taiwan's semiconductor foundry concentration attracts fabless GNSS designers seeking proximity to RF-CMOS capacity. China's domestic encryption mandates and terminal subsidies accelerate BeiDou ecosystem self-sufficiency.
United States
Autonomous vehicle fleet operators in California and Arizona deploy multi-constellation receivers for lane-level positioning. FCC Part 15 enforcement shapes receiver sensitivity thresholds in dense urban RF environments. The Dallas-Fort Worth metroplex hosts precision agriculture equipment distributors integrating RTK correction services.
Germany
Automotive OEMs in Stuttgart and Munich mandate dual-frequency L1/L5 modules for advanced driver-assistance systems launching 2027. EASA certification requirements for aviation-grade hardware tighten performance standards. Bavaria's automotive supplier cluster coordinates silicon qualification with Taiwan foundry partners.
China
Industrial IoT deployments displace legacy GPS modules through MIIT-administered BeiDou terminal certification. National encryption modules restrict market access for non-domestic suppliers. Shenzhen's electronics manufacturing hub concentrates domestic receiver assembly for Belt and Road export markets.
Japan
QZSS augmentation integration requirements drive specialized receiver development for disaster resilience mandates. METI coordinates critical infrastructure timing synchronization procurement. Nagoya's automotive electronics corridor supplies multi-GNSS modules to domestic and export vehicle programs.
India
Subsidy programs for farm mechanization open deployment channels for affordable RTK-enabled guidance systems. The national space regulator promotes NavIC constellation adoption in strategic applications. Bangalore's aerospace and defense electronics cluster develops indigenous multi-constellation receiver architectures.
Global Positioning Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined positioning engines and correction service networks. The vendor base stratifies across silicon designers, module integrators, and service operators. Three archetypes dominate: fabless semiconductor specialists with foundry partnerships, ruggedized hardware fabricators serving outdoor recreation and professional segments, and precision service operators bundling correction data with terminal subscriptions. Competitive moves concentrate on backward integration into correction networks and RF front-end silicon redesign for multi-constellation fusion.
Within the precision service tier, Trimble Inc. and Hexagon AB exemplify integrated positioning solution providers. Among silicon-centric designers, Qualcomm Technologies, Inc. and Broadcom Inc. occupy positions in mobile SoC and discrete receiver markets. Garmin Ltd. anchors the ruggedized hardware specialist archetype. These named entities represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Trimble Inc. |
| Qualcomm Technologies, Inc. |
| Broadcom Inc. |
| Hexagon AB |
| TomTom International BV |
| Collins Aerospace |
| u-blox AG |
| Topcon Corporation |
| Others |
Value Network & Pricing Analysis
Europe's CSRD sustainability disclosure requirements gate qualified supply for antenna ceramic substrates and premium-tier pricing access for automotive-grade receiver modules. German OEMs now audit smelter documentation before qualifying new positioning hardware, compressing margins for non-compliant suppliers while rewarding certified vendors with durable pricing power.
Pricing Analysis
Distributor margins in precision agriculture equipment run 12-18 points above direct-to-OEM automotive contracts. Three-tier pricing structure across aviation-certified, automotive-grade, and consumer-level receivers separates EASA-validated hardware from mass-market modules. Cost compression in consumer wearables is intensifying because Qualcomm's SoC integration displaces discrete module suppliers. Fleet telematics operators exhibit highest price sensitivity, while defense procurement tolerates 40-60 point premiums for anti-jam specifications.
Supply Chain Analysis
Advanced RF-CMOS wafer supply rests on Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation foundry capacity. Rare-earth elements for antenna substrates draw from Chinese separation facilities and Australian mining operations. Single-source vulnerability concentrates in Taiwan-based 28nm RF-CMOS lines. Distribution runs through Shenzhen electronics hubs for consumer modules and Stuttgart-Tokyo automotive supplier corridors for OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Positioning Systems Market functions as a stable compounder, with multi-constellation mandates across automotive and aviation end-uses ensuring replacement-cycle revenue visibility regardless of macroeconomic volatility.
For Market Incumbents: Acquire correction service network assets to anchor recurring revenue streams. Trimble's backward integration into RTK networks exemplifies this defensive posture against silicon commoditization. EASA certification timeline compression threatens hardware-only vendors; invest in pre-validation testing infrastructure to compress 18-month approval windows. Channel control through equipment financing arrangements defends margin position against hyperscale logistics buyer concentration. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass incumbent distributor lock-in across North American long-haul trucking. India's precision agriculture subsidy programs offer the most penetrable geography for affordable RTK guidance systems. Partner with domestic integrators in Shenzhen or Bangalore to satisfy local content requirements without captive manufacturing investment. For Investors and Strategic Acquirers: Roll-up economics work for precision service operators because correction network density creates local monopoly returns with minimal incremental capital. Five-to-ten year viability hinges on constellation diversification rather than GPS-only legacy exposure. Watch BeiDou terminal certification timelines as the inflection indicator for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Correction Service Network Expansion | Trimble and Hexagon capture recurring revenue through RTK infrastructure density in agricultural corridors. |
| Multi-Constellation RF Front-End Redesign | Automotive Tier-1 suppliers qualify Taiwan-foundry silicon for 2027 ADAS production lines. |
| EASA Pre-Certification Testing Investment | Aviation hardware vendors compress validation cycles to offset 18-month approval delays. |
| BeiDou Terminal Certification Compliance | Non-domestic suppliers secure MIIT encryption module partnerships for Chinese industrial IoT access. |
| Software-Defined Positioning Engine Development | Field-upgradable constellation support reduces hardware redesign costs for emerging constellations. |
Research Methodology
Multiple input streams — semiconductor foundry utilization data, EASA certification registry filings, and BeiDou terminal shipment records — were reconciled across primary interviews and secondary validation. Conversations with automotive platform engineers, precision agriculture equipment distributors, aviation hardware certification specialists, and telecom base station procurement officers informed demand-side assumptions. Secondary sources included FCC equipment authorization databases, MIIT terminal certification bulletins, EASA design approval registers, and customs trade data for receiver module flows. Bottom-up volume estimates triangulated against top-down constellation service revenue projections.
Historical shipment trajectories cross-referenced against panel input from GNSS silicon designers and module integrators shaped the analytical framework. Segmentation dimensions modeled encompass application context, constellation technology mix, end-user risk profile, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to replacement-cycle timing and new-installation penetration rates. Multi-constellation receiver architecture transition timing and EASA mandate implementation schedules served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for software-defined positioning engines would alter the outlook for hardware-centric vendor margins. Forecasts reflect assumptions regarding Taiwan foundry capacity allocation and lithium-ion battery cost trajectories. A small set of triggers — FCC spectrum reallocation proceedings, EASA certification timeline shifts, and MIIT encryption module policy changes — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Terrestrial Laser Scanning System Market
Sensors
Remote Sensing Technology Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Mobile Mapping Systems Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Underground Utility Mapping Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Telemetric Devices Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Drain Camera Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Bluetooth Beacons Market
Sensors
Asia Pacific RFID Market
Sensors
Gesture Recognition in Retail Market
Sensors
Asset Tracking Market