
 Asia-Pacific Tea Market | 2026-2036
Asia-Pacific Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tea Market Outlook
Indian smallholder cooperatives is broadening orthodox black tea output across Assam and Darjeeling. Tata Consumer Products anchors South Asian distribution through deep rural wholesale networks. Ito En Ltd leads Japan's ready-to-drink segment with precision-controlled extraction methods. Uni-President Enterprises Corp extends its reach across Taiwan and mainland China via convenience store exclusivity.
Asia-Pacific tea encompasses processed leaf from Camellia sinensis and botanical infusions, graded by oxidation level, polyphenol content, and liquor color against ISO 3720 standards. Black tea commands volume leadership through standardized CTC processing, while green tea captures premium margins via steaming and pan-firing techniques that preserve catechins. Specialty stores and online retail channels now outpace supermarket growth for loose-leaf and gift formats. Food service demand from high-end hotels concentrates on single-origin oolong and ceremonial-grade matcha with traceable provenance.
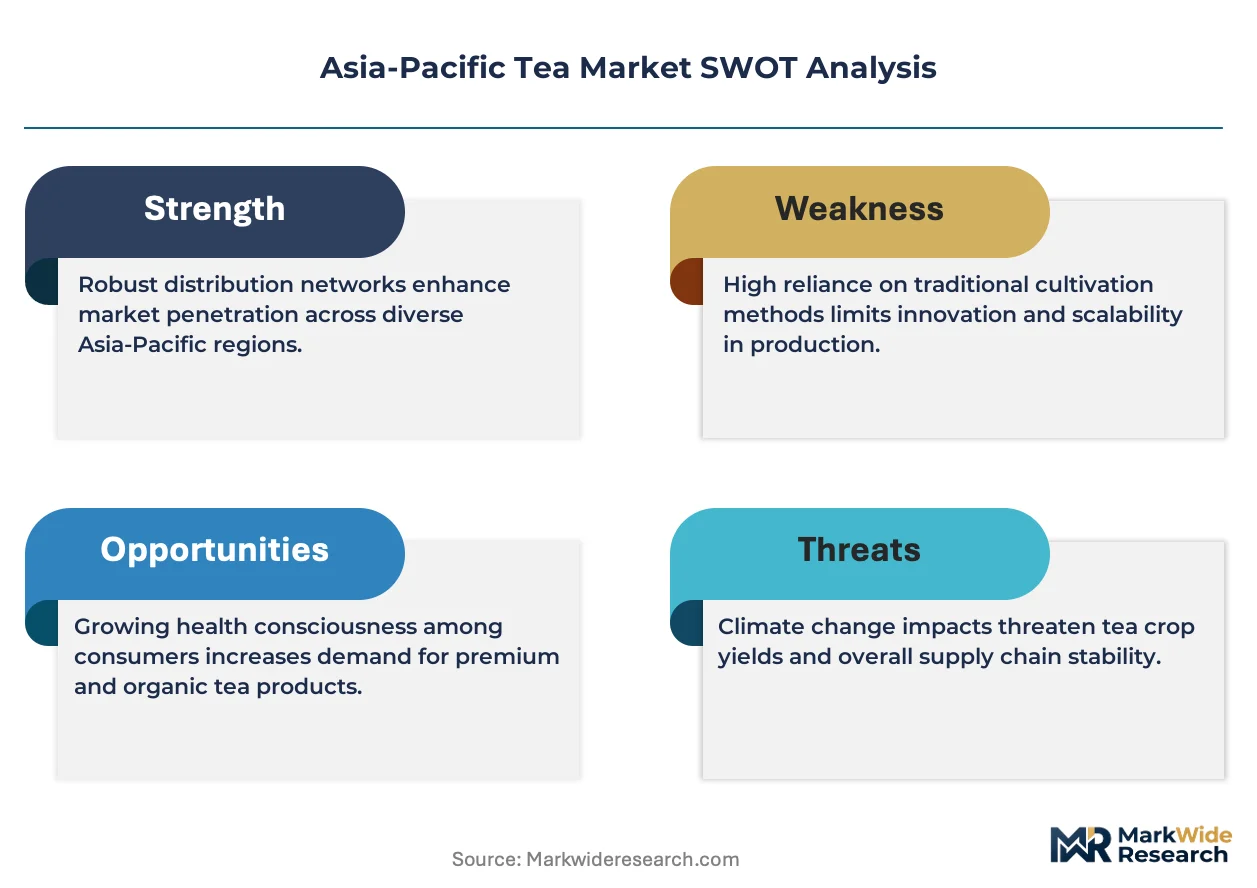
China's SAMR enforces GB standards for pesticide residues and labeling across domestic and imported tea. Japan's Ministry of Agriculture, Forestry and Fisheries operates JAS organic certification that governs export eligibility to premium European buyers. India's FSSAI mandates nutritional disclosure and quality marks for packaged blends sold through modern retail. Stakeholders must monitor how climate volatility in Sri Lanka and Kenya redirects blending sourcing strategies and origin premiums across the region.
Market Dynamics
India's FSSAI fortification mandates are compressing margins across mass-market packaged tea while simultaneously opening premium positioning for traceable orthodox grades. This regulatory pivot is forcing blenders to reconfigure sourcing networks and reformulate product hierarchies.
Growth Catalysts
- Cold-brew extraction technologies:Precision temperature control systems enable flavor preservation without thermal degradation. Specialty cafes in Shanghai and Seoul deploy these methods for bottled retail expansion.
- FSSAI nutritional disclosure mandates:India's packaged tea rules are accelerating premiumization as brands differentiate through fortification claims. Modern retail channels favor compliant suppliers with visible quality marks.
- Assam and Darjeeling cooperative expansion:Smallholder aggregation is broadening orthodox black tea availability. This geographic concentration strengthens origin-provenance narratives for export markets.
Market Restraints
- Climate volatility in Sri Lanka:Erratic monsoon patterns are disrupting Ceylon tea output consistency. Blenders face reformulation costs and origin premium volatility.
- CTC processing commoditization:Crush-tear-curl standardization has collapsed differentiation in black tea. Price competition intensifies across South Asian bulk markets.
- GB standard compliance costs:China's SAMR pesticide residue limits require extensive testing infrastructure. Smaller importers struggle with certification timelines and laboratory access.
Strategic Opportunities
- Vietnam's underdeveloped premium segment:Northern highland provinces lack branded orthodox infrastructure. Early movers can establish single-origin positioning before market saturation.
- Convenience store exclusivity models:Taiwan's 7-Eleven and FamilyMart networks demonstrate captive channel potential. Similar structures remain untapped in Indonesia and Philippines.
- JAS organic certification arbitrage:Japan's MAFF standard unlocks European premium buyer access. Investment in compliant estates yields export price premiums.
Industry Challenges
- Matcha grinding technician scarcity:Ceremonial-grade stone-milling expertise concentrates in Uji and Nishio. Training pipelines fail to match specialty cafe expansion rates.
- ISO 3720 testing backlog:Liquor color and polyphenol verification faces laboratory capacity constraints. Export shipments delay awaiting grade confirmation.
- Legacy wholesale credit systems:South Asian auction houses operate on extended payment terms incompatible with working capital requirements of direct-trade specialty buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tea Market |
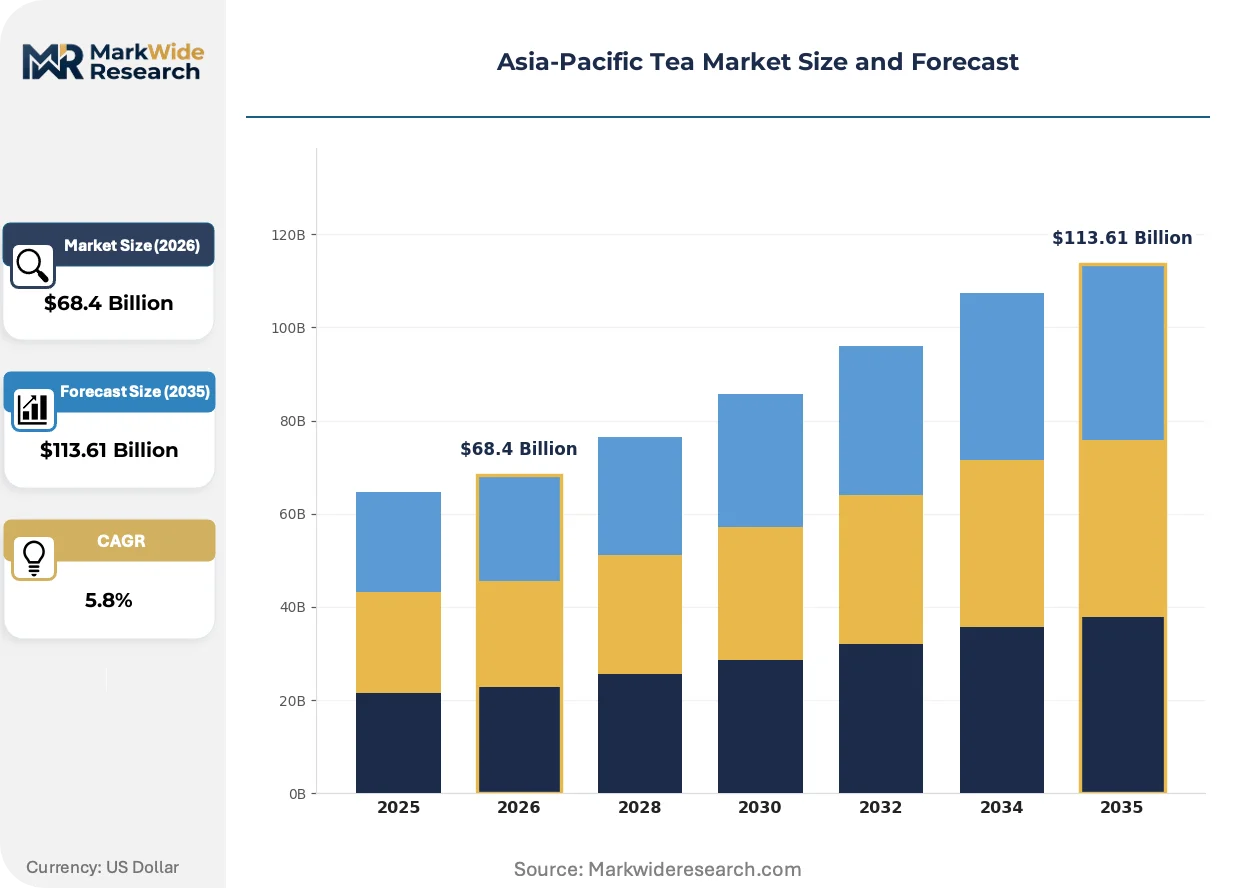
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Oolong Tea, Herbal Tea Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service End User: Households, Restaurants, Cafes, Hotels Packaging Type: Bags, Loose Leaf, Bottled, Tea Pods |
| Companies Covered | Nongfu Spring Co Ltd, The Hain Celestial Group, Unilever PLC, Uni-President Enterprises Corp, Suntory Holdings Ltd, Tata Consumer Products, Ito En Ltd, Tingyi Holding Corp, Dilmah Ceylon Tea Company PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tea Market Strategic Shifts
Processing precision and consumption format diversification are fragmenting traditional grade hierarchies. The market is splitting between convenience-driven ready-to-drink and ritual-driven ceremonial segments.
Precision-controlled extraction equipment is expanding into high-volume ready-to-drink manufacturing. Japanese bottlers deploy temperature-staged brewing to preserve catechins without astringency. This technology is expanding into Chinese and Taiwanese production lines, compressing the quality gap between artisan and industrial outputs.
India's FSSAI fortification mandates are reshaping packaged tea formulation requirements. Iron and vitamin premix integration now determines modern retail shelf access. South Asian blenders are responding by restructuring procurement toward estate-direct traceability to support premium positioning.
Specialty retail channels in China's tier-one cities are displacing supermarket dominance for loose-leaf and gift formats. Younger consumers in Beijing and Shenzhen favor single-origin oolong with blockchain-verified provenance. This behavioral shift is most visible in cold-brew and bottled segments where convenience intersects with authenticity signaling.
Asia-Pacific Tea Market Segmentation
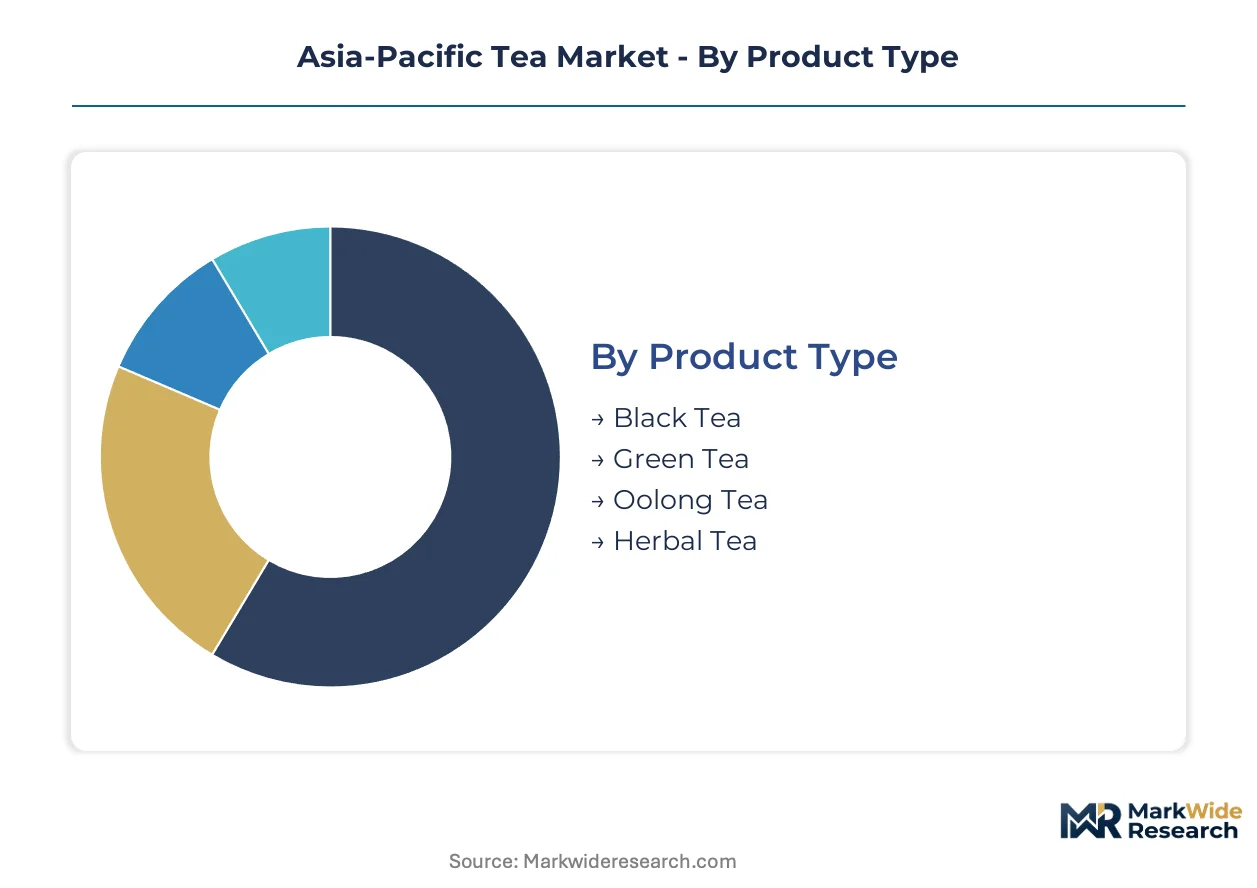
Asia-Pacific tea buyers navigate fragmented choice architectures where oxidation chemistry, ritual occasion, and channel accessibility intersect. Procurement patterns split between commodity-grade CTC for daily consumption and precision-processed orthodox grades for provenance signaling. Understanding segment boundaries clarifies where margin pools concentrate versus where volume scales.
Product Type:
Buyers prioritize oxidation level and polyphenol preservation as proxies for health claims and flavor complexity.
- Black Tea:Fully oxidized leaf processed through CTC or orthodox methods delivers standardized liquor color per ISO 3720. Demand concentrates in South Asian households and Middle Eastern export markets where Assam and Ceylon origin premiums command shelf positioning. FSSAI fortification mandates are compressing mass-market margins while elevating estate-direct traceability.
- Green Tea:Unoxidized leaf preserved through steaming (Japanese) or pan-firing (Chinese) techniques maximizes catechin retention. Procurement tilts toward China's tier-one cities and Japanese convenience networks where ceremonial-grade matcha and cold-brew formats gain traction among younger consumers. JAS organic certification unlocks European premium buyer access.
- Oolong Tea:Semi-oxidized leaf spanning 20-70% oxidation range.
- Herbal Tea:Botanical infusions outside Camellia sinensis including rooibos, chamomile, and regional adaptogens.
Volume sits with Black Tea; growth tilts toward Green Tea.
Distribution Channel:
Channel selection determines margin capture versus working capital intensity across the value chain.
- Supermarkets:Mass retail chains stock standardized CTC and bagged formats with extended payment terms. India's rural wholesale networks and China's county-level distributors dominate procurement here, though shelf space is compressing under private-label pressure.
- Online Retail:E-commerce platforms enable direct-to-consumer provenance storytelling with blockchain verification. China's tier-one cities and Taiwan's PChome network demonstrate fastest expansion for gift formats and subscription loose-leaf.
- Specialty Stores:Curated retail concentrating single-origin and ceremonial grades.
- Food Service:B2B supply to hotels, cafes, and restaurant chains.
Supermarkets retain volume dominance; Specialty Stores and Online Retail are expanding most quickly.
End User:
Consumption occasion shapes format preference from daily utility to ritual performance.
- Households:Residential consumption spans mass-market bagged tea for daily brewing and premium loose-leaf for hospitality occasions. India's urban middle-class and China's tier-two cities drive demand for FSSAI-compliant fortified blends and cold-brew concentrates.
- Hotels:Luxury hospitality procurement concentrates on ceremonial-grade matcha and single-origin oolong with traceable provenance for guest experience differentiation.
- Restaurants:Food service accounts requiring consistent brewing performance.
- Cafes:Third-wave coffee shops and tea houses driving cold-brew innovation.
Households anchor volume; Hotels command the steepest premium expansion trajectory.
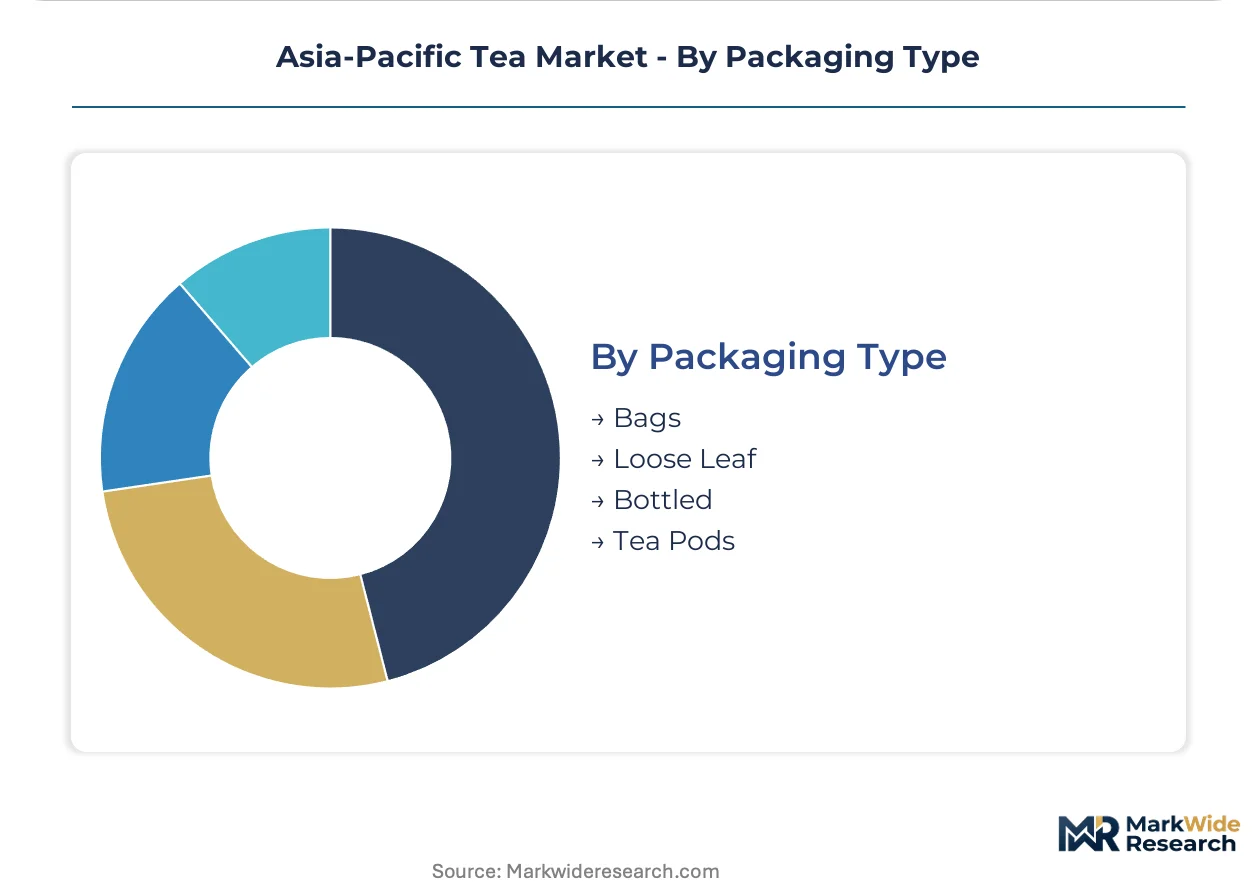
Packaging Type:
Format choice balances convenience, oxidation protection, and sustainability signaling.
- Bags:Filter paper and pyramid sachets dominate South Asian and Southeast Asian mass markets. India's FSSAI nutritional disclosure rules favor branded bagged blends with visible quality marks in modern retail.
- Loose Leaf:Bulk formats requiring brewing equipment preserve orthodox leaf integrity for specialty channels. China's tier-one cities and Taiwan demonstrate strongest demand for gift-boxed loose-leaf with blockchain verification.
- Bottled:Ready-to-drink formats including cold-brew and precision-extracted catechin preserves.
- Tea Pods:Single-serve capsules compatible with brewing systems.
Bags retain volume leadership; Loose Leaf and Bottled formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assam and Darjeeling plantations anchor South Asian orthodox output while Japanese precision-extraction methods set quality benchmarks across East Asian processing corridors.
China
Cold-brew and bottled formats gain traction among younger consumers in Beijing and Shenzhen where blockchain-verified single-origin oolong commands premium positioning. SAMR enforces GB standards for pesticide residues and labeling across domestic and imported tea. The Yangtze River Delta concentrates precision-extraction manufacturing for ready-to-drink lines.
India
Urban middle-class households in tier-two cities drive demand for FSSAI-compliant fortified blends and cold-brew concentrates. FSSAI mandates nutritional disclosure and quality marks for packaged blends sold through modern retail. Assam and Darjeeling cooperative expansion broadens orthodox black tea availability for export markets.
Japan
Ceremonial-grade matcha demand concentrates in Tokyo and Osaka specialty cafes where stone-milling expertise faces technician scarcity. MAFF operates JAS organic certification governing export eligibility to premium European buyers. Uji and Nishio retain concentrated ceremonial-grade grinding capability.
Vietnam
Northern highland provinces present underdeveloped premium orthodox infrastructure with single-origin positioning opportunities. The national agricultural regulator oversees phytosanitary compliance for export eligibility. Lam Dong and Thai Nguyen provinces concentrate bulk CTC output with limited branded value-add.
Taiwan
Convenience store exclusivity models through 7-Eleven and FamilyMart networks demonstrate captive channel potential for bottled formats. The national standards body enforces geographic indication protections for high-mountain oolong. Taichung and Nantou anchor specialty oolong processing clusters.
Asia-Pacific Tea Market Competitive Environment
Global majors compete with regional champions across extraction technology and distribution channel control. The market structures around three tiers: multinational beverage conglomerates with ready-to-drink scale, South Asian plantation-integrated blenders with rural wholesale dominance, and East Asian precision processors with convenience retail exclusivity. Dominant competitive moves include backward integration into estate sourcing and technology licensing for cold-brew extraction systems.
Within the multinational beverage tier, Unilever PLC and Suntory Holdings Ltd occupy positions defined by scale-driven ready-to-drink manufacturing and brand portfolio breadth. Among East Asian precision specialists, Ito En Ltd exemplifies temperature-controlled extraction methodology, while Uni-President Enterprises Corp anchors convenience channel exclusivity models. Tata Consumer Products represents the South Asian plantation-integrated archetype with deep rural wholesale network penetration.
| Leading Market Players |
|---|
| Nongfu Spring Co Ltd |
| The Hain Celestial Group |
| Unilever PLC |
| Uni-President Enterprises Corp |
| Suntory Holdings Ltd |
| Tata Consumer Products |
| Ito En Ltd |
| Tingyi Holding Corp |
| Dilmah Ceylon Tea Company PLC |
| Others |
Value Chain & Pricing Dynamics
FSSAI fortification mandates in India's packaged tea segment are forcing blenders to absorb premix integration costs or pivot toward estate-direct sourcing that commands premium positioning. This regulatory compression squeezes mass-market margins while rewarding traceable orthodox grades with pricing power.
Pricing Analysis
Certification-bundling separates JAS organic premiums from conventional export tiers, with laboratory testing and traceability documentation included in landed European pricing. Three-tier pricing structure across ceremonial-grade matcha, single-origin orthodox, and commodity CTC reflects oxidation method and origin provenance. Cost compression in South Asian bulk CTC is intensifying because standardized processing has collapsed differentiation. Household buyers in India's rural wholesale networks show highest price sensitivity; luxury hospitality procurement in Tokyo and Shanghai demonstrates lowest.
Supply Chain Analysis
Single-source vulnerability sits with Sri Lankan Ceylon tea output given erratic monsoon disruption to blending formulations. Raw material flows draw from Assam and Darjeeling orthodox leaf, Japanese Uji matcha grinding capacity, and Vietnamese northern highland CTC output. Tariff exposure runs through EU-JEPA trade framework negotiations affecting Japanese organic export eligibility. Distribution runs through Taiwan convenience store exclusivity, South Asian auction house networks, and China's tier-one city specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance costs and climate volatility are forcing weaker blenders toward exit or acquisition, consolidating procurement power among estate-integrated players with working capital depth.
For Market Incumbents: Anchor defensive positioning through backward integration into Assam and Darjeeling cooperative supply agreements that secure orthodox volume ahead of export demand expansion. Invest in JAS organic certification infrastructure to capture European premium buyer reallocation from Sri Lankan sources disrupted by climate volatility. Channel control through Taiwan-style convenience store exclusivity models offers margin protection against supermarket private-label encroachment. For New Entrants and Emerging Players: Boutique hospitality procurement in Vietnam's luxury resort corridor represents an underserved buyer archetype with limited incumbent presence. Northern highland provinces lack branded orthodox infrastructure, creating white-space for single-origin positioning before market saturation. Direct-trade relationships with Lam Dong smallholders bypass legacy auction house credit systems incompatible with specialty working capital cycles. For Investors and Strategic Acquirers: Re-rating potential sits with Japanese precision-extraction technology licensors given cold-brew format expansion across Chinese manufacturing lines. Acquisition targets include mid-cap blenders with FSSAI-compliant fortification infrastructure and established modern retail shelf access. Watch for SAMR enforcement actions on pesticide residue testing as signal of compliance cost inflection that advantages scaled laboratory networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Sourcing | Captures Assam and Darjeeling orthodox volume ahead of export demand expansion. |
| JAS Organic Certification Investment | Unlocks European premium buyer access as climate volatility disrupts Sri Lankan supply. |
| Cold-Brew Extraction Technology Licensing | Japanese precision methods transfer to Chinese manufacturing lines for catechin preservation. |
| Convenience Store Exclusivity Expansion | Taiwan's 7-Eleven and FamilyMart models replicate across Indonesia and Philippines captive channels. |
| Blockchain Provenance Verification Deployment | Chinese tier-one city consumers demand traceable single-origin oolong for authenticity signaling. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific tea market assessment. Primary interviews with estate managers, FSSAI compliance officers, specialty cafe procurement leads, and convenience store category buyers combined with India Tea Board export statistics, China SAMR pesticide residue disclosure databases, and Japan MAFF organic certification registries. Bottom-up volume modeling across oxidation grades and packaging formats triangulated against top-down trade flow analysis.
Granularity-level modeling deployed country-specific extraction technology adoption curves, regulatory compliance cost pass-through rates, and channel shift elasticity parameters across the projection horizon. Segmentation dimensions included oxidation level, distribution channel, end-user occasion, and packaging format with CAGRs derived from trend extrapolation moderated by structural constraint identification. Forecast inputs incorporated climate volatility impact coefficients on Sri Lankan output and FSSAI fortification mandate implementation timelines.
Revisions become necessary when SAMR enforcement intensity on GB standard compliance, JAS organic certification European market access negotiations, or Assam cooperative expansion rates materially diverge from baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Instant Tea Market
Tea
Rooibos Tea Market
Tea
Floral Tea Market
Tea
North America Tea Market
Tea
Smart Tea Set Market
Tea
Oolong Tea Market
Tea
Tea Pitchers Market
Tea
Asia-Pacific Green Tea Market
Tea
White Tea Extract Market
Tea
Bottled Milk Tea Market
Tea
Nitro Tea Market
Tea
Fermented Tea Market
Tea
Black Tea Market
Tea
Out of Home Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Natural Tea Extract Market