
 Plant Based New Tea Drink Market | 2026-2036
Plant Based New Tea Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based New Tea Drink Market Insights
Single-serve ready-to-drink formats with modular flavor pods is expanding consumer trial rates across convenience channels. Hey Tea leverages captive sourcing of botanical extracts to secure consistent flavor profiles across its retail footprint. Nayuki Holdings Limited anchors its premium positioning through controlled in-store brewing systems that emphasize freshness theater. Mixue Group competes on manufacturing scale, driving unit economics that undercut specialty competitors in China's lower-tier cities.
Plant based new tea drinks comprise brewed or extracted tea bases reformulated with plant-derived milks, fruit extracts, and botanical adjuncts, typically processed through cold-brew extraction or flash-pasteurization to preserve volatile aromatic compounds. The category serves both refreshment and functional wellness purposes, with adaptogen and probiotic fortification gaining traction among health-seeking consumers. Green and herbal variants capture the fastest growth trajectory as caffeine-conscious buyers migrate from traditional black tea formulations. Distribution through health stores and online retail channels concentrates margin pools, while supermarket placement remains volume-driven but price-compressed. Vegan consumers and athletes represent emerging demographic segments where botanical ingredient transparency commands premium positioning.
China's SAMR enforces plant-based labeling standards that restrict dairy mimicry claims, while the EU's EFSA novel food framework governs adaptogen and probiotic additive approvals. The US FDA exercises jurisdiction over bottled tea health claims through its food labeling regulations, creating compliance friction for functional positioning. China's dual carbon goals are accelerating cold-chain energy standards that reshape distribution infrastructure requirements. Stakeholders must monitor evolving botanical ingredient approval pathways across these jurisdictions to preempt formulation redesign costs and market access delays.
Market Dynamics
China's SAMR plant-based labeling standards are forcing reformulation across the ready-to-drink botanical infusion category, compressing product development cycles and reshaping competitive positioning around ingredient transparency rather than flavor novelty.
Growth Catalysts
- Cold-chain infrastructure expansion:China's dual carbon goals accelerate energy-efficient refrigeration deployment across tier-one cities, enabling flash-pasteurization distribution networks that preserve volatile aromatic compounds in botanical extracts.
- EFSA novel food framework:The EU's streamlined adaptogen approval pathways reduce time-to-market for functional fortification, stimulating probiotic and botanical additive innovation among European formulators.
- Athlete demographic penetration:Sports nutrition channels in Germany and the United States are absorbing caffeine-free green tea variants as recovery beverages, creating premium positioning for electrolyte-fortified botanical infusions.
Market Restraints
- Botanical extract supply concentration:Camellia sinensis and adaptogen sourcing clusters in Yunnan and Sichuan provinces create geographic vulnerability to climate-induced harvest volatility.
- SAMR dairy mimicry restrictions:China's labeling standards prohibit visual and textual cues suggesting traditional milk equivalence, forcing costly packaging redesigns and consumer education investments.
- Flash-pasteurization capex barriers:Cold-fill aseptic lines require specialized stainless-steel equipment that excludes smaller co-packers from functional RTD production.
Strategic Opportunities
- Lower-tier Chinese city penetration:Mixue Group's manufacturing scale demonstrates viable unit economics for plant-based new tea drinks in markets underserved by premium specialty operators.
- Modular flavor pod systems:Single-serve formats with interchangeable botanical cartridges create trial acceleration through convenience channel placement without full-size commitment.
- US FDA health claim pathway:The agency's food labeling regulations permit structure-function positioning for adaptogen-fortified variants, opening functional wellness positioning in American retail.
Industry Challenges
- Volatile compound stabilization expertise:Cold-brew extraction chemistry requires specialized food science talent scarce outside established beverage R&D clusters in Shanghai and Shenzhen.
- Multi-jurisdiction compliance synchronization:Simultaneous navigation of SAMR's plant-based standards, EFSA novel food approvals, and FDA health claim frameworks fragments regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based New Tea Drink Market |
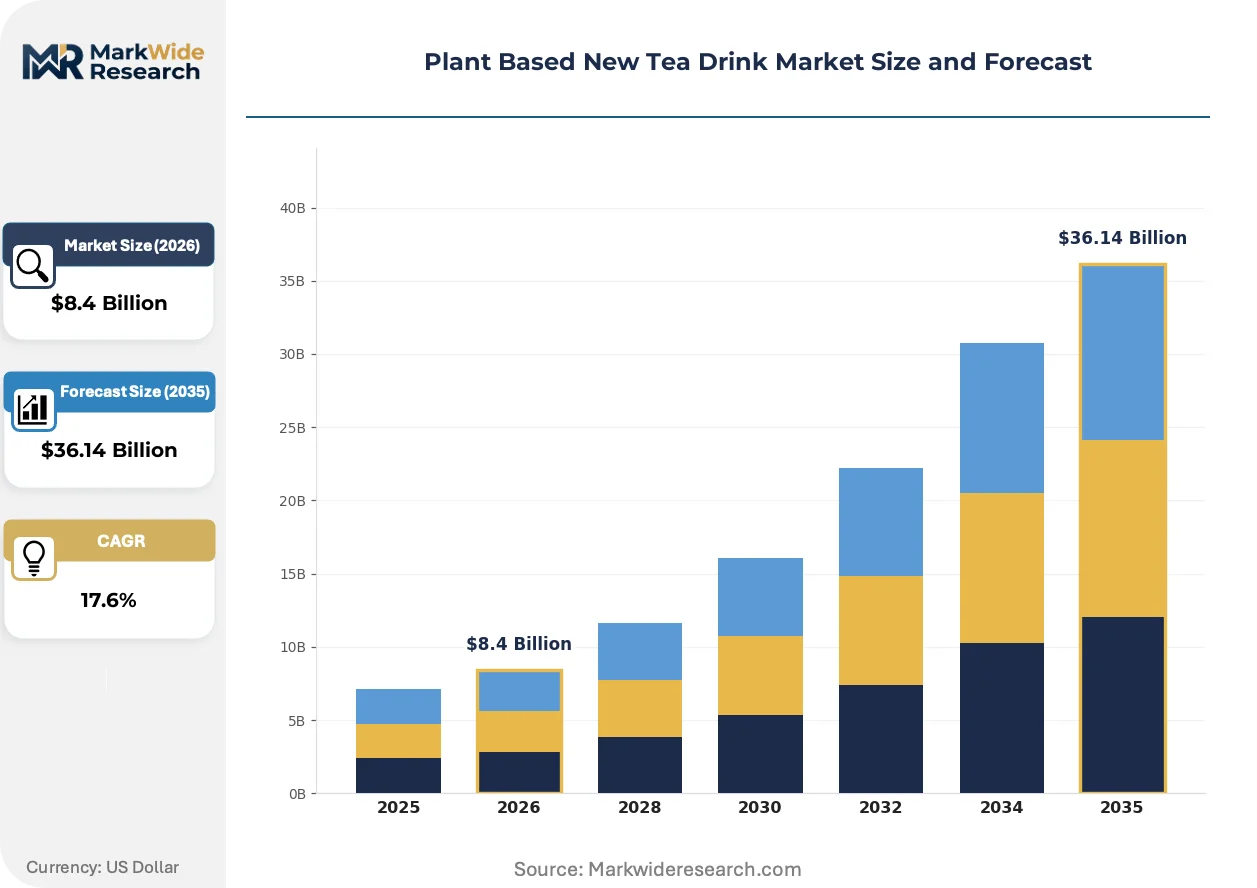
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Green, Black, White Ingredient Type: Fruit Extracts, Spices, Botanicals, Sweeteners Distribution Channel: Supermarkets, Online Retail, Health Stores, Cafes Consumer Demographic: Health-Conscious, Millennials, Athletes, Vegan Consumers |
| Companies Covered | Hey Tea, Nayuki Holdings Limited, CHAGEE, CoCo Fresh Tea & Juice, Mixue Group, Sexy Tea, Goodme, Chabaidao, Sichuan Shuyi Catering Management Co.,Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based New Tea Drink Market Trends and Innovations
Formulation technology and distribution infrastructure are converging to compress product development timelines while fragmenting consumer access points across convenience, specialty, and direct channels.
Flash-pasteurization with nitrogen dosing is unifying shelf-stability and sensory freshness in ambient-distributed botanical infusions. Mid-market beverage brands in China's tier-one cities are adopting this hybrid thermal treatment at accelerating rates. The technology is unifying previously separate cold-chain and ambient distribution networks, collapsing the premium-mass market boundary that historically segmented plant-based new tea drinks.
REACH-compliant botanical extract certification is reshaping European supply base qualification requirements. The ECHA framework mandates full supply chain disclosure for adaptogen and herbal additive sourcing, elevating documentation costs for Asian ingredient suppliers. German and Dutch formulators are responding by consolidating procurement around pre-certified extract houses with established European analytical laboratories.
Caffeine-conscious migration is compressing the traditional black tea dominance in ready-to-drink portfolios. Health stores and online retail channels in the United States are displacing supermarket velocity with green and herbal variant concentration, reorienting margin capture toward transparency-premium positioning. This pattern is most visible among vegan consumer segments and endurance athlete demographics where ingredient provenance commands price tolerance.
Plant Based New Tea Drink Market Segmentation
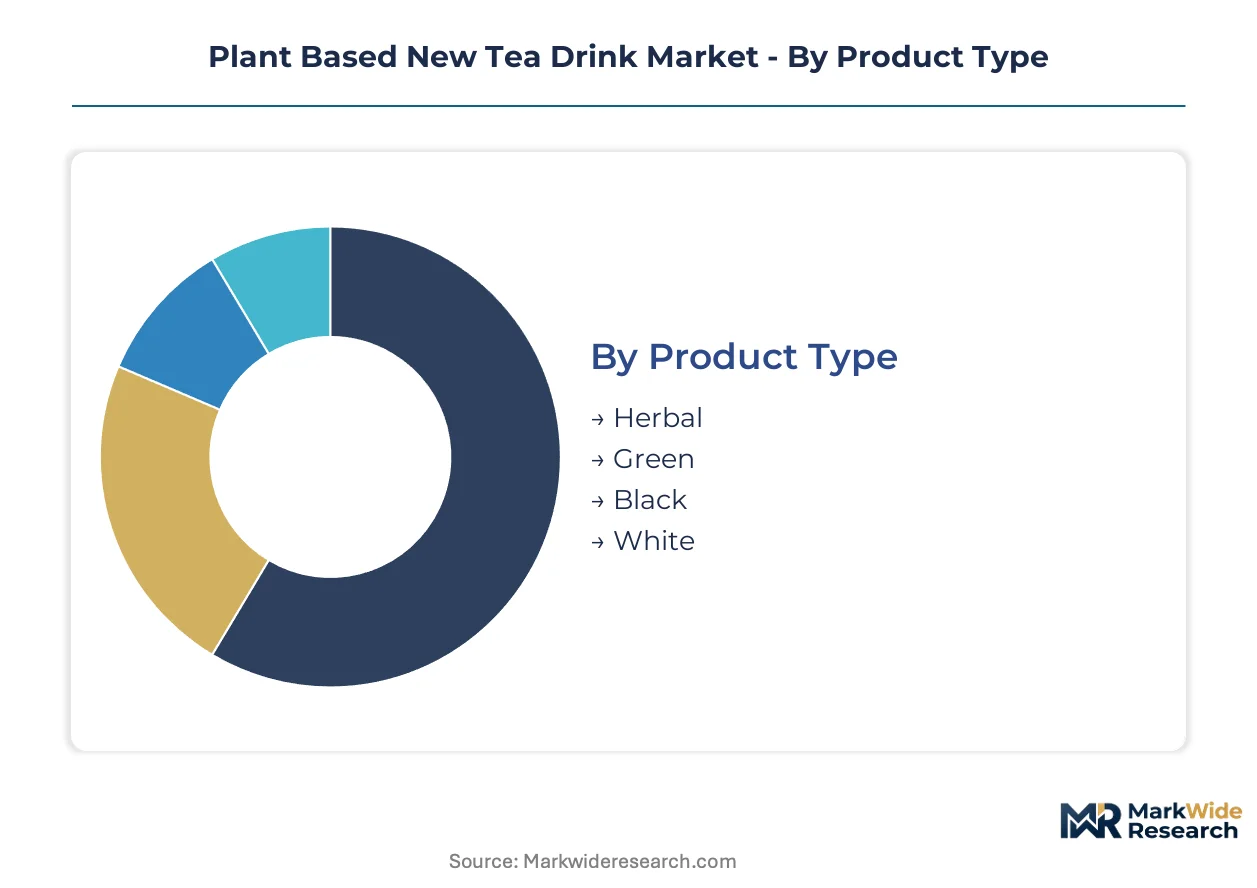
Segmentation in plant-based new tea drinks exposes where margin pools concentrate versus where volume scales. Category boundaries are blurring as flash-pasteurization unifies cold-chain and ambient distribution, forcing brands to choose between transparency-premium positioning or manufacturing-scale economics.
Product Type:
Supply concentration around Camellia sinensis cultivars in Yunnan and Sichuan provinces shapes which variants achieve consistent flavor profiling at scale.
- Herbal:Caffeine-free formulations blending rooibos, chamomile, and hibiscus with botanical adjuncts. Demand concentrates in German health stores and US online retail channels where adaptogen fortification commands price premiums.
- Green:Cold-brew extracted Camellia sinensis with preserved catechin content. China's tier-one cities and US athlete demographics are absorbing the fastest volume as caffeine-conscious buyers migrate from black tea bases.
- Black:Traditional fully-oxidized tea bases reformulated with oat and almond milk derivatives. Standardization costs are compressing margins in supermarket placement.
- White:Minimally processed silver needle and white peony extracts with delicate aromatic profiles. Premium positioning in Japanese and South Korean specialty channels offsets limited harvest volumes.
Green tea absorbs the bulk of installed capacity; herbal variants are expanding most quickly.
Ingredient Type:
Cost tier stratification separates commodity inputs from certified organic extracts with full supply chain documentation.
- Fruit Extracts:Cold-pressed citrus, berry, and tropical fruit concentrates providing natural sweetness and acidity balance. China's Hey Tea and Nayuki Holdings Limited leverage captive sourcing of Yunnan-grown botanicals to secure consistent flavor profiles.
- Botanicals:Adaptogen roots, floral essences, and functional herb extracts requiring EFSA novel food approval in Europe. German formulators are consolidating procurement around REACH-compliant extract houses with established European analytical laboratories.
- Spices:Cinnamon, ginger, and cardamom infusions with warming flavor profiles. Limited to seasonal and regional variants with narrow distribution.
- Sweeteners:Monk fruit, stevia, and erythritol blends replacing cane sugar in reduced-calorie positioning. SAMR labeling standards restrict health claim associations.
Botanicals capture the steepest expansion trajectory; fruit extracts anchor current formulation volumes.
Distribution Channel:
Margin structure diverges sharply between transparency-premium health channels and price-compressed supermarket placement.
- Health Stores:Curated assortments emphasizing organic certification and ingredient provenance. US and German channels are displacing supermarket velocity with green and herbal variant concentration.
- Online Retail:Direct-to-consumer subscriptions and marketplace listings enabling trial-size formats. China's tier-one cities show highest conversion rates for modular flavor pod systems.
- Supermarkets:Mass-market shelf placement with ambient distribution requirements. Flash-pasteurization capex barriers exclude smaller co-packers from functional RTD production.
- Cafes:Controlled in-store brewing systems emphasizing freshness theater. Nayuki Holdings Limited anchors premium positioning through this channel in China's dense urban networks.
Online retail is gaining share fastest; supermarkets still absorb the bulk of unit volume.
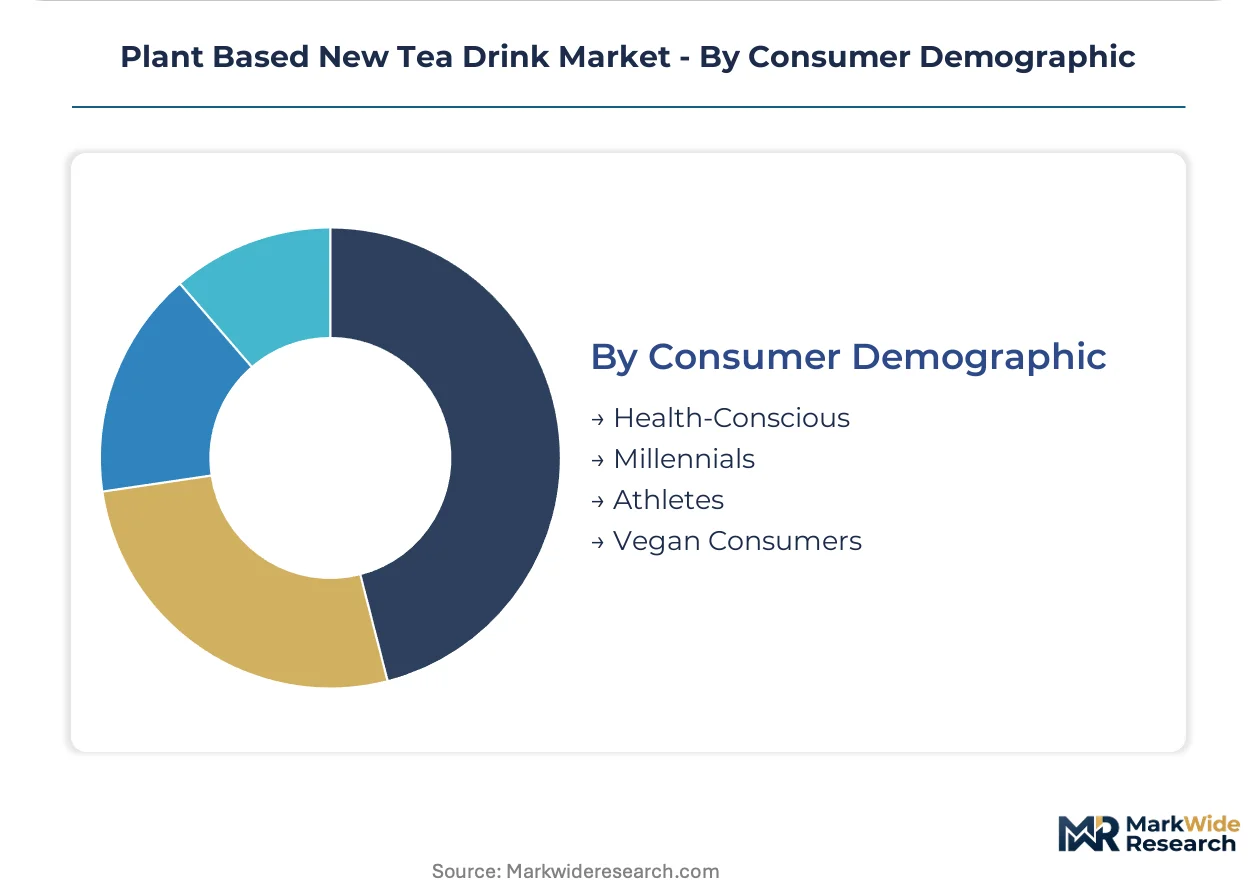
Consumer Demographic:
Application-specific need states determine willingness to pay for botanical ingredient transparency versus convenience-oriented price sensitivity.
- Health-Conscious:Buyers prioritizing clean label positioning and functional wellness claims. China's SAMR plant-based labeling standards and FDA health claim frameworks create compliance friction for this segment.
- Millennials:Urban professionals in China, the United States, and Germany accelerating uptake of ready-to-drink botanical infusions. Convenience channel penetration drives trial rates.
- Athletes:Endurance sports participants seeking caffeine-free recovery beverages with electrolyte fortification. German and US sports nutrition channels show strongest absorption.
- Vegan Consumers:Strict plant-based dietary adherents demanding dairy-free certification and supply chain verification. Premium positioning in European health stores and US specialty retail.
Millennials represent the largest addressable base; athletes are climbing the fastest in per-capita spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates production through Yunnan and Sichuan tea cultivar clusters, while consumption concentrates in tier-one cities and spreads through Germany's health channels and US athlete demographics. This production-consumption divide shapes regulatory friction and supply chain investments across three continents.
China
Health-conscious millennials in Shanghai, Beijing, and Shenzhen drive ready-to-drink botanical infusion uptake through dense Hey Tea and Nayuki Holdings Limited store networks. SAMR plant-based labeling standards restrict dairy mimicry claims, forcing packaging redesigns and consumer education investments. The Yangtze River Delta anchors captive sourcing of botanical extracts that secure consistent flavor profiles across retail footprints.
Germany
Sports nutrition channels absorb caffeine-free green tea variants as recovery beverages, creating premium positioning for electrolyte-fortified botanical infusions. EFSA novel food guidelines govern adaptogen and probiotic additive approvals, streamlining functional fortification pathways. REACH-compliant extract certification from Dutch and German analytical laboratories consolidates procurement around pre-certified supply houses.
United States
Endurance athletes and vegan consumers in health stores and online retail channels displace supermarket velocity with green and herbal variant concentration. FDA food labeling regulations permit structure-function positioning for adaptogen-fortified variants, opening functional wellness positioning. The Pacific Northwest and Northeast Corridor show strongest absorption of modular flavor pod systems through convenience channel placement.
Japan
White tea extracts with delicate aromatic profiles command premium positioning in Tokyo and Osaka specialty channels, offsetting limited harvest volumes. METI energy standards intersect with cold-chain infrastructure requirements as dual carbon goals reshape distribution investments. The Kanto region concentrates flash-pasteurization expertise for nitrogen-dosed ambient distribution networks.
United Kingdom
Millennial professionals in London accelerate trial rates through convenience channel penetration of single-serve formats. The EU Green Deal's carbon border adjustments intersect with post-Brexit regulatory divergence, complicating multi-jurisdiction compliance for brands operating across both markets. Southeast England clusters online retail fulfillment infrastructure for direct-to-consumer botanical subscriptions.
Plant Based New Tea Drink Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where manufacturing scale, captive sourcing, and freshness theater define competitive vectors. The vendor base spans three strategic archetypes: specialty operators emphasizing controlled in-store brewing, scale-driven manufacturers optimizing unit economics in lower-tier cities, and captive sourcing integrators securing botanical extract consistency. Dominant competitive moves include backward integration into Yunnan tea cultivar regions and strategic deployment of modular flavor pod systems through convenience channels.
Within the specialty operator tier, Hey Tea and Nayuki Holdings Limited exemplify divergent approaches to premium positioning, while Mixue Group anchors the scale-driven manufacturing archetype. These three Chinese entities occupy distinct competitive positions based on store network density, captive sourcing arrangements, and geographic focus across tier-one versus lower-tier urban markets. Hey Tea represents the botanical extract integration model; Nayuki Holdings Limited exemplifies freshness theater through controlled brewing systems; Mixue Group demonstrates viable unit economics in underserved markets through manufacturing scale advantages.
| Leading Market Players |
|---|
| Hey Tea |
| Nayuki Holdings Limited |
| CHAGEE |
| CoCo Fresh Tea & Juice |
| Mixue Group |
| Sexy Tea |
| Goodme |
| Chabaidao |
| Sichuan Shuyi Catering Management Co.,Ltd. |
| Others |
Pricing and Supply Chain Analysis
Yunnan tea cultivar auction indices cascade through three pricing tiers as captive sourcing arrangements separate premium botanical extract users from commodity spot buyers facing volatile harvest yields.
Pricing Analysis
Margin tightening in supermarket placement reflects flash-pasteurization capex barriers that exclude smaller co-packers from functional RTD production. A three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Cost compression in mass-market channels accelerates because Mixue Group's manufacturing scale undercuts specialty competitors. Health-conscious millennials in China's tier-one cities show least price sensitivity; lower-tier urban consumers absorb highest price elasticity.
Supply Chain Analysis
Dual-sourcing mandates from German formulators require REACH-compliant extract houses alongside Asian botanical suppliers to preempt ECHA documentation failures. Geographic supply concentration centers on China, India, and Sri Lanka for Camellia sinensis cultivars. Raw material dependencies rest on Yunnan-grown adaptogen roots, Sichuan floral essences, and cold-pressed tropical fruit concentrates. Single-source vulnerability from climate-induced harvest volatility in Yunnan and Sichuan provinces threatens consistent flavor profiling. Distribution runs through cold-chain networks in tier-one Chinese cities and ambient flash-pasteurized channels in European health stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over Yunnan tea cultivar regions has become the decisive lever as brands race to lock in consistent botanical extract supply before SAMR labeling enforcement tightens further.
For Market Incumbents: Deepen captive sourcing arrangements in Yunnan and Sichuan provinces to defend against climate-induced harvest volatility threatening flavor consistency. Expand controlled in-store brewing systems across dense urban networks to reinforce freshness theater differentiation from manufacturing-scale competitors. Prioritize EFSA novel food pre-approval investments before adaptogen fortification claims face tightened European scrutiny.
For New Entrants and Emerging Players: Modular flavor pod technology offers a technology-first wedge into China's convenience channel penetration without requiring full-scale flash-pasteurization infrastructure. Target lower-tier Chinese cities where Mixue Group's unit economics demonstrate viable addressable white space underserved by premium specialty operators. Pursue direct-to-consumer subscription models through online retail channels to bypass supermarket price compression.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale extract houses with established European analytical laboratory partnerships in Germany and the Netherlands. Long-term viability over a multi-year horizon rests on consolidation around REACH-compliant certification capabilities as ECHA documentation costs escalate. Monitor EFSA adaptogen approval velocity as the critical inflection signal for functional fortification market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sourcing Integration | Hey Tea's Yunnan botanical extract control secures consistent flavor profiles across retail footprints. |
| Flash-Pasteurization Deployment | Nitrogen-dosed ambient distribution unifies previously separate cold-chain networks in Chinese tier-one cities. |
| EFSA Novel Food Pre-Approval | Streamlined adaptogen pathways reduce time-to-market for German and Dutch functional fortification formulators. |
| Modular Flavor Pod Systems | Single-serve formats accelerate consumer trial rates through convenience channel placement without commitment. |
| REACH-Compliant Certification | Full supply chain disclosure mandates elevate procurement consolidation around pre-certified European extract houses. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and retail audit panels underwrites the qualitative findings in this study. Primary interviews with beverage R&D directors, supply chain managers at extract houses, regulatory affairs leads navigating SAMR and EFSA frameworks, and category buyers at health stores and supermarkets informed demand-side and compliance assessments. Secondary validation drew from SAMR labeling standard disclosures, EFSA novel food approval registers, FDA food labeling guidance documents, and Yangtze River Delta cold-chain infrastructure investment filings. Bottom-up volume modeling and top-down value reconciliation triangulated market size estimates.
Comparable-period anchoring to historical flash-pasteurization adoption curves and adaptogen fortification penetration patterns structured the projection horizon. Segmentation dimensions modeled include product type, ingredient certification tier, distribution channel margin structure, and consumer demographic need states. CAGRs were derived from trend extrapolation adjusted for regulatory friction coefficients and supply concentration risk premiums across the analysis window. Forecast inputs incorporated SAMR enforcement intensity scenarios and EFSA approval velocity assumptions for botanical additive categories.
Several conditions sit outside the modeled scope, including black swan climate events disrupting Yunnan harvest cycles and abrupt SAMR dairy mimicry restriction expansions beyond current labeling standards. Forecasts reflect documented assumptions about cold-chain infrastructure buildout pacing and EFSA novel food backlog clearance rates. Deviation in dual carbon goal enforcement intensity or ECHA documentation requirement tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Out of Home Tea Market
Tea
Slimming Tea Market
Tea
Light-Fermented Tea Market
Tea
Europe Tea Market
Tea
Tea Packaging Market
Tea
Pyramid Tea Bags Market
Tea
Tea Polyphenols Market
Tea
Smart Tea Maker Market
Tea
APAC RTD Tea Market
Tea
North America Tea Market
Tea
Floral Tea Market
Tea
US Ready to Drink Tea Market
Tea
US RTD Organic Tea Market
Tea
Herbal Tea Market
Tea
Natural Tea Extract Market
Tea
Fermented Tea Market