
 North America Ready-To-Drink Tea Market | 2026-2036
North America Ready-To-Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ready-To-Drink Tea Market Analytics
Mexico is reshaping regional production capacity through expanded bottling infrastructure serving cross-border distribution. The Coca-Cola Company leverages its fountain-equipment network to secure cold-chain placement in convenience channels. PepsiCo anchors shelf-stable tea manufacturing through its Quaker Foods North America division. Arizona Beverage Company competes on price-point consistency across its iconic tall-can format.
Ready-to-drink tea comprises brewed, extracted, or infused tea formulations packaged for immediate consumption without preparation, typically processed through hot-fill or aseptic bottling to preserve polyphenol stability and achieve shelf lives of 6-18 months. The category serves commercial purposes spanning refreshment, functional wellness positioning, and sugar-reduced hydration alternatives to carbonated soft drinks. Green tea formulations lead product type margins due to antioxidant marketing claims and premium positioning, while herbal tea segments attract Gen Z buyers through caffeine-free and adaptogenic ingredient stories. Supermarkets dominate distribution channel volume, though online retailers represent the fastest-growing access point for subscription-based wellness tea programs.
FDA enforces nutrition facts panel requirements and added-sugar disclosure rules that compel reformulation across U.S. portfolios, while Health Canada sets caffeine limits and natural health product standards affecting cross-border SKU rationalization. The USDA organic certification framework creates tiered price architecture separating conventional from certified organic ready-to-drink tea placements. Stakeholders must monitor evolving sugar-tax proposals in multiple U.S. states and Canadian provinces to anticipate channel-mix disruptions.
Market Dynamics
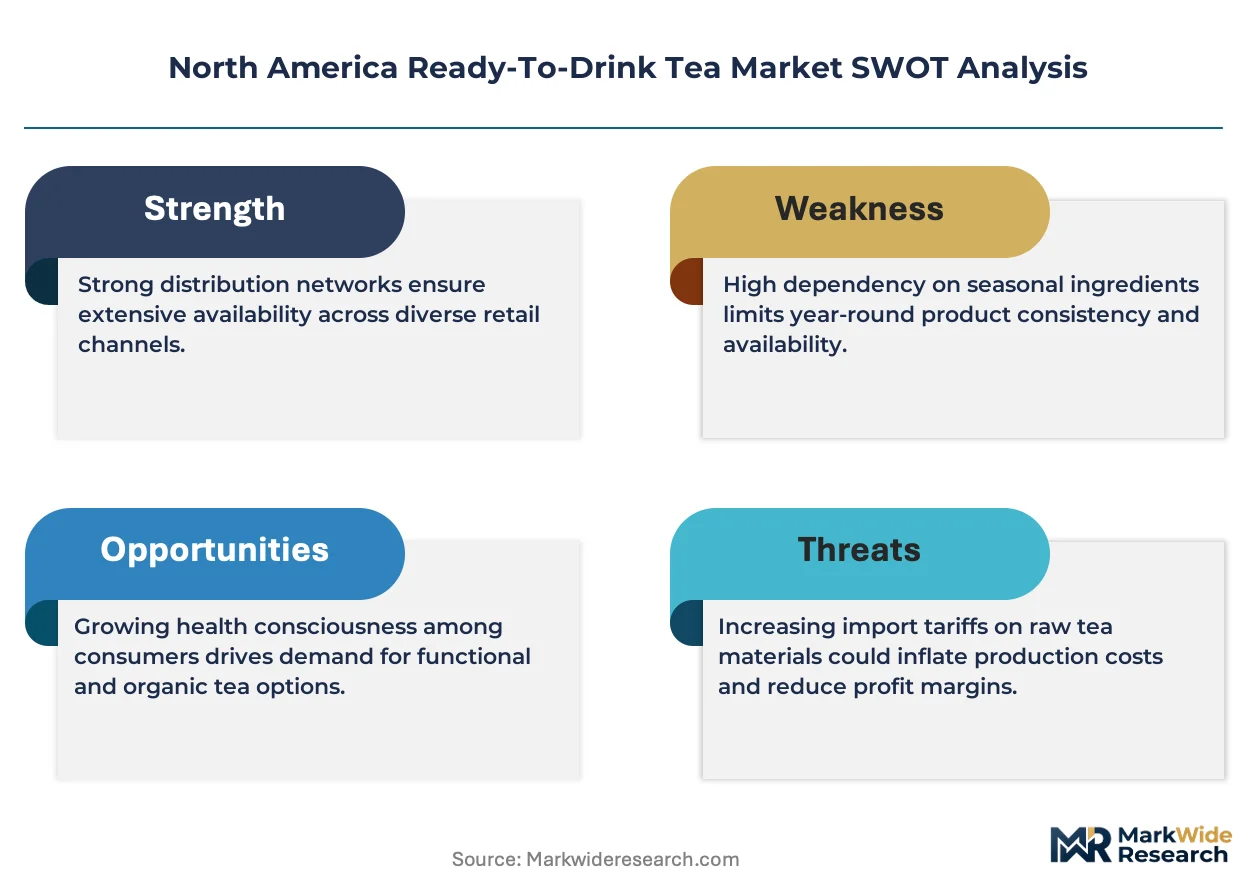
FDA added-sugar disclosure mandates and Health Canada caffeine limits are compressing formulation cycles across North American portfolios, forcing manufacturers to rebuild recipes around natural sweeteners and polyphenol preservation without sacrificing shelf stability.
Growth Catalysts
- Clean-label preference intensification:Health-conscious consumers in U.S. Northeast and West Coast metropolitan corridors prioritize ingredient transparency, expanding demand for USDA-certified organic and minimal-processing claims.
- Functional wellness positioning:Green tea formulations leverage antioxidant marketing narratives to capture premium shelf placements in supermarket beverage aisles.
- Cross-border bottling infrastructure:Mexico's expanded production capacity reduces landed costs for U.S. distribution, enabling price-point competitiveness in convenience channels.
Market Restraints
- Input cost volatility:Tea leaf and natural sweetener prices fluctuate with climate-driven harvest variability in key sourcing regions, compressing gross margins on conventional formulations.
- Regulatory friction:Divergent FDA and Health Canada labeling requirements create SKU rationalization costs for brands attempting unified North American portfolios.
- Substitution threat:Flavored sparkling waters and functional beverages capture overlapping refreshment occasions, particularly among sugar-avoidant demographics.
Strategic Opportunities
- Subscription channel expansion:Online retailers represent underpenetrated access points for wellness-focused tea programs with recurring revenue models.
- Adaptogenic ingredient stories:Herbal tea segments attract Gen Z buyers through caffeine-free formulations incorporating ashwagandha and functional mushrooms.
- Aseptic cold-fill technology:Advanced bottling methods enable extended shelf life without thermal degradation of heat-sensitive bioactive compounds.
Industry Challenges
- Reformulation timeline compression:FDA nutrition facts panel updates and pending state-level sugar-tax proposals demand rapid recipe redevelopment with limited consumer testing windows.
- Cold-chain placement competition:Securing refrigerated retail space against entrenched fountain-equipment networks requires sustained trade investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ready-To-Drink Tea Market |
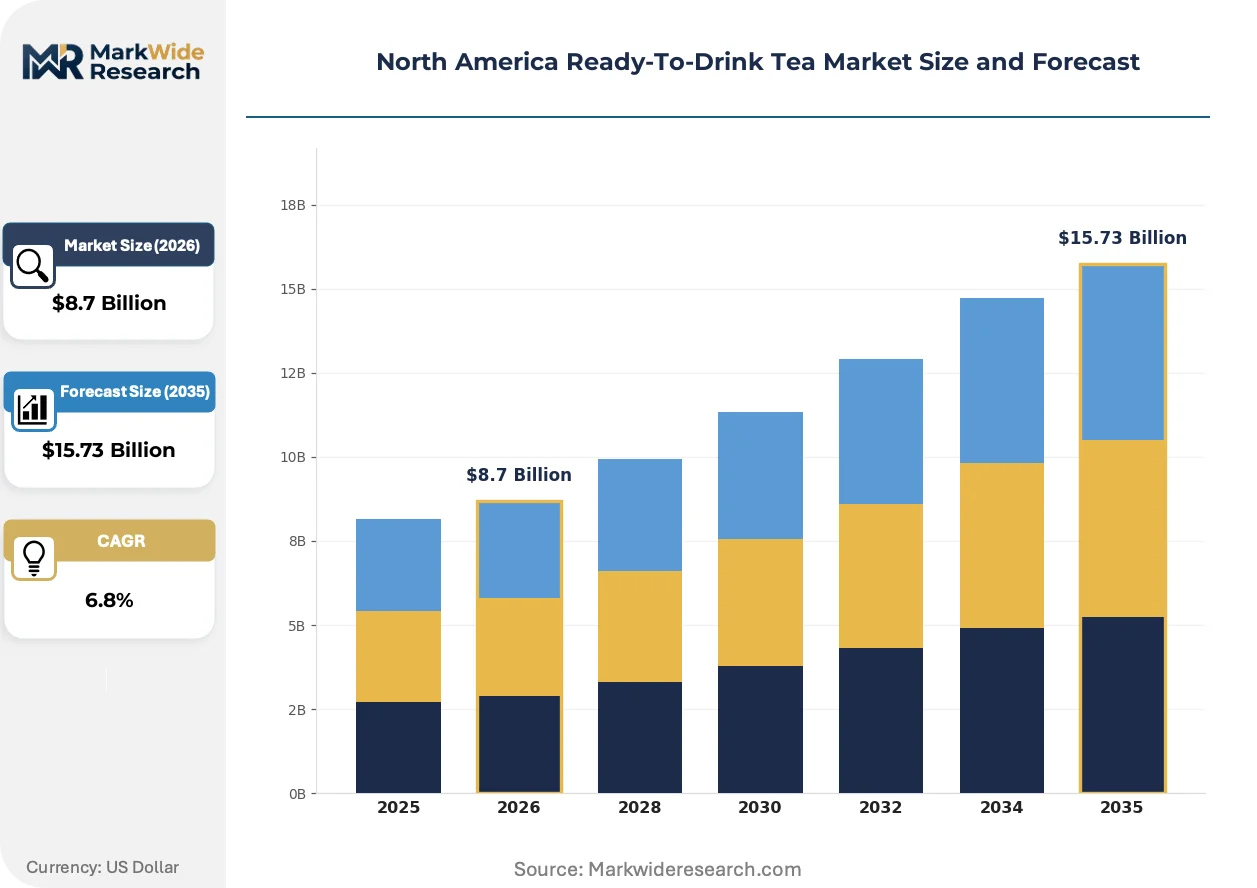
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Flavored Tea Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Stores End User: Millennials, Gen Z, Health Conscious Consumers, Busy Professionals Flavor Profile: Citrus, Mint, Berry, Peach |
| Companies Covered | The Coca-Cola Company, PepsiCo, Inc., Nestlé S.A., Arizona Beverage Company, Keurig Dr Pepper Inc., Unilever PLC, Ito En, Ltd., Starbucks Corporation, R.C. Bigelow, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ready-To-Drink Tea Market Evolving Landscape
Cold-chain infrastructure investments and aseptic processing advances are reconfiguring how ready-to-drink tea reaches consumers, collapsing traditional barriers between shelf-stable and refrigerated positioning.
Aseptic cold-fill technology is collapsing the distinction between premium refrigerated and ambient-stable tea segments. Mid-tier brands in the U.S. Southeast are adopting this equipment to deliver extended shelf life without hot-fill polyphenol degradation. The structural consequence compresses price premiums previously commanded by exclusively refrigerated products.
FDA added-sugar disclosure rules compel front-of-package reformulation across U.S. portfolios. Manufacturers are rebuilding recipes around monk fruit and stevia blends to maintain sweetness perception while complying with new labeling thresholds. Sugar-reduced green tea SKUs in the Northeast corridor show the most aggressive adaptation timelines.
Subscription-based wellness programs are displacing single-serve impulse purchases in coastal metropolitan markets. Direct-to-consumer platforms capture recurring revenue through curated adaptogenic and herbal assortments. This shift concentrates most visibly in West Coast urban centers where Gen Z buyers prioritize caffeine-free functional positioning over traditional refreshment occasions.
North America Ready-To-Drink Tea Market Segmentation
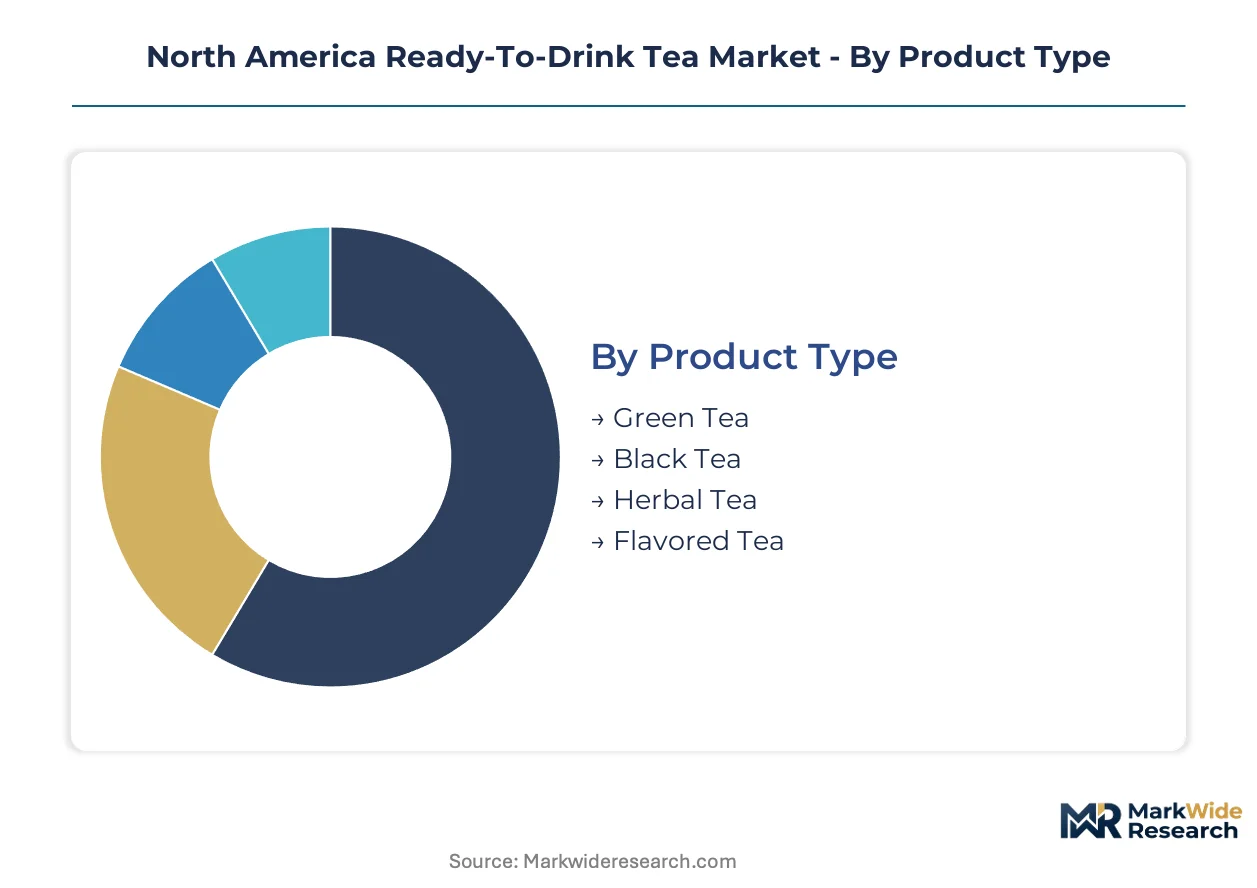
Segmentation in the North America ready-to-drink tea market reveals how formulation choices, channel access, and generational preferences create distinct commercial battlegrounds. Manufacturers must align product architecture with specific consumption occasions rather than pursuing undifferentiated mass-market positioning.
Product Type:
Cost tier differentiation separates commodity formulations from premium antioxidant-positioned SKUs with significant margin implications.
- Green Tea:Brewed from unoxidized Camellia sinensis leaves, these formulations deliver elevated catechin content that supports antioxidant marketing claims. U.S. Northeast and West Coast metropolitan corridors concentrate demand as health-conscious buyers prioritize polyphenol density over price sensitivity. FDA nutrition labeling requirements compel precise caffeine disclosure that constrains formulation flexibility.
- Herbal Tea:Caffeine-free infusions derived from rooibos, chamomile, and adaptogenic botanicals target wellness-positioned consumption occasions. Gen Z buyers in coastal urban centers drive adoption through subscription-based direct-to-consumer platforms. Health Canada natural health product standards create cross-border SKU complexity for brands with unified North American portfolios.
- Black Tea:Fully oxidized leaf formulations offering robust flavor profiles and higher caffeine content than green alternatives.
- Flavored Tea:Blended formulations incorporating fruit, botanical, or spice extracts to mask bitterness and broaden palatability.
Green tea commands the established base. The steepest expansion runs through herbal tea.
Distribution Channel:
Channel selection determines temperature requirements, shelf-life specifications, and trade investment intensity for portfolio deployment.
- Supermarkets:Mass-merchandise beverage aisles accommodate both ambient-stable and refrigerated SKUs with extended facing allocations. U.S. suburban corridors concentrate volume as household stock-up trips dominate purchase patterns. Cold-chain placement competition against entrenched fountain-equipment networks demands sustained slotting allowance investment.
- Online Retailers:Direct-to-consumer platforms enable subscription-based wellness programs with recurring revenue models. West Coast metropolitan markets show the most concentrated adoption as Gen Z buyers prioritize curated adaptogenic assortments over impulse convenience. Health Canada cross-border shipping regulations create fulfillment complexity for unified North American fulfillment operations.
- Convenience Stores:Grab-and-go channels favor single-serve ambient-stable formats with immediate consumption positioning.
- Health Food Stores:Specialty retail emphasizes USDA organic certification and clean-label ingredient transparency at premium price points.
Supermarkets anchor volume throughput. The fastest channel expansion is occurring through online retailers.
End User:
Customer type segmentation aligns functional positioning with distinct life-stage priorities and consumption occasion patterns.
- Gen Z:Digital-native consumers aged 18-27 prioritize caffeine-free adaptogenic formulations and sustainability credentials in purchase decisions. Subscription-based wellness programs in coastal metropolitan markets capture this cohort through curated herbal assortments. Social media discovery drives trial conversion more than traditional advertising channels.
- Health Conscious Consumers:Demographic-spanning buyers prioritize USDA organic certification, minimal processing claims, and sugar-reduced formulations. U.S. Northeast and West Coast corridors concentrate this segment as clean-label preference intensifies across age cohorts. FDA added-sugar disclosure mandates accelerate reformulation timelines to maintain purchase eligibility.
- Millennials:Convenience-seeking professionals aged 28-43 balance functional wellness positioning with on-the-go consumption requirements.
- Busy Professionals:Time-constrained buyers prioritize grab-and-go accessibility and sustained energy positioning over ingredient exploration.
Health conscious consumers represent the core revenue base. Gen Z is gaining share fastest among generational cohorts.
Flavor Profile:
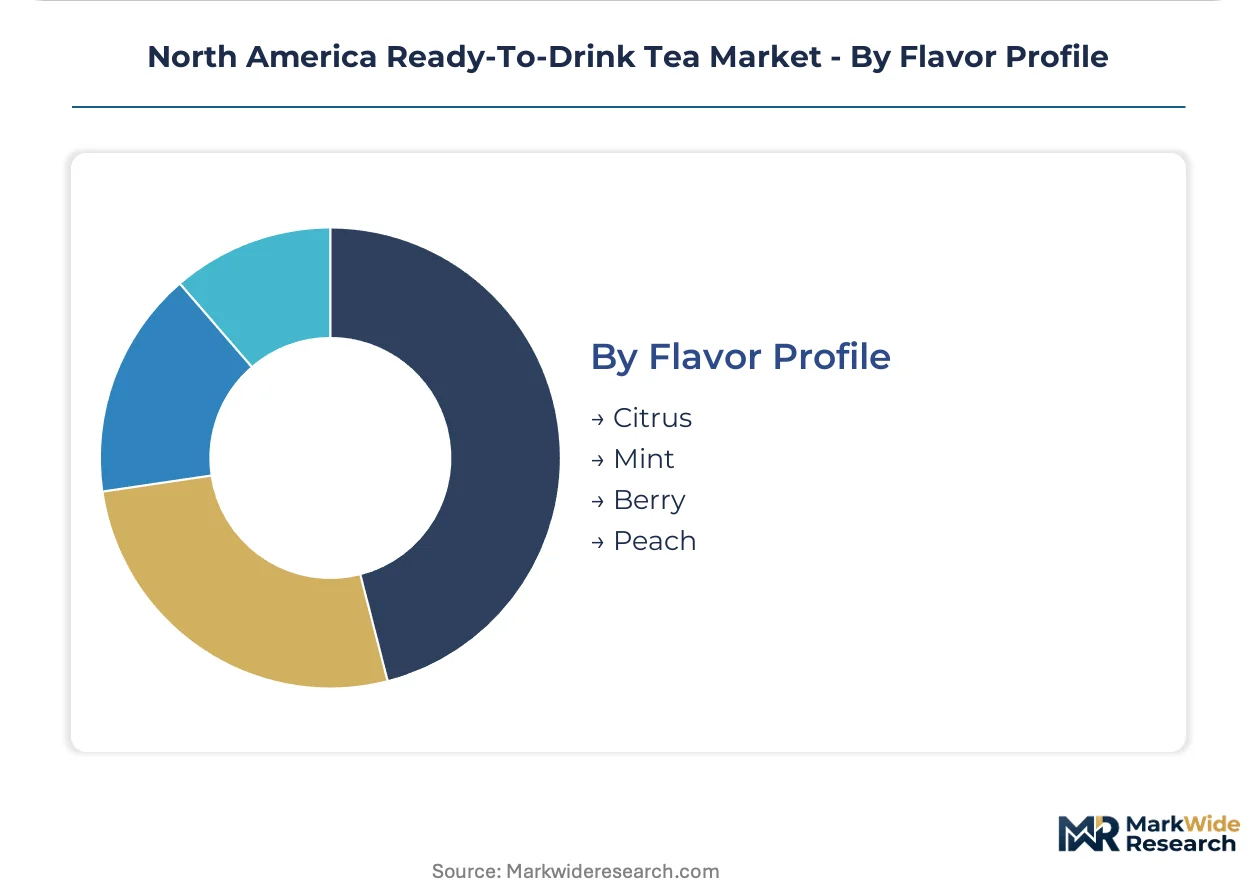
Flavor architecture determines palatability masking effectiveness and seasonal rotation flexibility across regional preferences.
- Citrus:Lemon, lime, and grapefruit extracts provide acidity balance that masks tannin astringency in green tea bases. U.S. Sun Belt markets concentrate demand as refreshment positioning dominates consumption occasions. Natural flavor sourcing from Florida and California agricultural regions faces climate-driven harvest variability.
- Mint:Peppermint and spearmint botanicals deliver cooling sensory profiles that differentiate from commodity cola and citrus alternatives. Health food store channels emphasize mint-herbal combinations for digestive wellness positioning. Mint oil price volatility from Pacific Northwest sourcing regions compresses formulation cost predictability.
- Berry:Strawberry, raspberry, and blueberry extracts target younger demographic palatability preferences in flavored black tea formulations.
- Peach:Stone-fruit positioning dominates Southern U.S. regional preferences with seasonal summer consumption concentration.
Citrus maintains the volume foundation. Berry formulations are expanding most quickly through flavored tea innovation pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border bottling capacity expansion in Mexico is reshaping supply-side economics for North American distribution networks. FDA and Health Canada regulatory divergence creates compliance complexity for unified portfolios. Demand clusters concentrate in coastal metropolitan corridors with pronounced generational preference splits.
United States
Northeast and West Coast metropolitan corridors drive clean-label demand as health-conscious buyers prioritize USDA organic certification. FDA added-sugar disclosure mandates compress reformulation timelines for national brands. Cold-chain placement competition intensifies in convenience channels across urban centers.
Canada
Health Canada caffeine limits and natural health product standards constrain SKU architecture for cross-border portfolios. Health-conscious consumers in Toronto and Vancouver metropolitan areas accelerate organic and minimal-processing claims. Quebec's beverage distribution networks favor bilingual labeling requirements.
Mexico
Expanded bottling infrastructure in Nuevo León and Jalisco reduces landed costs for U.S. distribution. Mexican regulatory frameworks align with U.S. FDA standards while maintaining distinct front-of-package labeling requirements. Northern border states concentrate production capacity serving cross-border logistics corridors.
North America Ready-To-Drink Tea Market Competitive Landscape
Beverage conglomerates and specialty tea specialists split the market into distinct competitive spheres. The structure consolidates around scale-driven distribution networks and niche wellness positioning. Three archetypes dominate: multinational soft-drink conglomerates with fountain-equipment advantages, dedicated tea specialists with heritage brand equity, and coffee-chain retailers extending beverage portfolios. Capacity expansion in Mexican bottling facilities and subscription-channel platform development represent the dominant competitive moves.
Among multinational conglomerates, The Coca-Cola Company and PepsiCo, Inc. exemplify scale-driven distribution archetypes leveraging existing cold-chain infrastructure. Arizona Beverage Company occupies a position within the heritage specialist tier, anchoring price-point consistency through iconic format recognition. These three entities represent the competitive spectrum from mass-market penetration to differentiated positioning.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Nestlé S.A. |
| Arizona Beverage Company |
| Keurig Dr Pepper Inc. |
| Unilever PLC |
| Ito En, Ltd. |
| Starbucks Corporation |
| R.C. Bigelow, Inc. |
| Others |
Value Network & Pricing Analysis
Camellia sinensis leaf sourcing from India, Kenya, and Sri Lanka concentrates cost volatility in the premium green tea tier, where polyphenol density requirements tether margin pools to harvest quality differentials rather than brand equity alone. This upstream geographic concentration cascades downstream through formulation decisions, as manufacturers absorb commodity swings or pass them through subscription pricing models.
Pricing Analysis
FDA added-sugar disclosure mandates dictate the pricing tier structure across North American portfolios. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic SKUs with adaptogenic positioning from conventional formulations and private-label alternatives. Price differentiation hinges on certification grade and cold-chain placement investment. Cost compression in the economy tier is intensifying because Mexican cross-border bottling capacity expands supply elasticity. Health-conscious consumers in coastal metropolitan corridors show least price sensitivity, while convenience-channel impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for tea extract and natural sweetener procurement. Raw material sourcing draws from India, Kenya, and Sri Lanka for leaf inputs, with monk fruit and stevia extracts anchored in Chinese agricultural processing regions. Single-source vulnerability in aseptic cold-fill equipment manufacturing creates bottleneck exposure for mid-tier brands upgrading bottling infrastructure. Distribution runs through refrigerated trucking networks serving supermarket beverage aisles and direct-to-consumer fulfillment centers for subscription wellness programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription platform economics are displacing single-serve impulse purchasing as the dominant revenue architecture, with interoperability between direct-to-consumer wellness apps and retailer loyalty programs creating new ecosystem lock-in opportunities.
For Market Incumbents: Build cold-chain placement moats through exclusive fountain-equipment partnerships with convenience channel operators. Anchor shelf-stable manufacturing capacity in Mexican border states to capture cross-border logistics efficiencies. Defend against adaptogenic specialist entrants by accelerating USDA organic certification timelines for core green tea portfolios. Prioritize aseptic cold-fill technology investment to collapse price premiums between refrigerated and ambient-stable positioning. For New Entrants and Emerging Players: Subscription-based wellness programs targeting Gen Z buyers in West Coast metropolitan corridors represent the most penetrable entry point. Caffeine-free herbal formulations with ashwagandha and functional mushroom positioning offer white-space differentiation from incumbent green tea dominance. Direct-to-consumer platform launch with curated assortments bypasses slotting allowance barriers in supermarket beverage aisles. Social media discovery-driven trial conversion replaces traditional trade marketing investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed adaptogenic beverage specialists possessing subscription platform infrastructure but limited manufacturing scale. Five-to-ten year viability framing favors brands with dual-channel capability spanning direct-to-consumer recurring revenue and retail distribution access. Acquisition target archetype: regional herbal tea specialists with Health Canada natural health product approvals enabling cross-border portfolio rationalization. Monitor FDA sugar-tax proposal advancement in Northeast corridor states as inflection indicator for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Technology Deployment | Enables extended shelf life without polyphenol degradation, collapsing refrigerated-ambient price distinctions. |
| Subscription Platform Integration | Captures recurring revenue through curated adaptogenic assortments targeting Gen Z wellness priorities. |
| Cross-Border Bottling Capacity Expansion | Mexican infrastructure reduces landed costs for U.S. distribution, enhancing convenience channel competitiveness. |
| USDA Organic Certification Acceleration | Separates premium tier from conventional formulations as clean-label preference intensifies in coastal corridors. |
| Adaptogenic Ingredient Pipeline Development | Positions herbal tea segments for Gen Z adoption through caffeine-free functional wellness narratives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers, category buyers at supermarket chains, cold-chain logistics coordinators, and beverage formulation scientists. Secondary validation drew from FDA nutrition labeling guidance documents, Health Canada natural health product standards, USDA organic certification databases, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, generational cohort, and flavor profile, with formulation technology tier as an industry-specific dimension. CAGRs were derived from slope-consistent growth pattern analysis. Forecast inputs incorporated climate-driven harvest variability indices and pending state-level sugar-tax proposal tracking.
Practitioners should monitor FDA added-sugar enforcement escalation and Health Canada caffeine limit revisions for early signals of reformulation cost acceleration. Forecasts reflect assumptions about subscription platform adoption rates and cross-border bottling capacity utilization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Instant Tea Premix Consumption Market
Tea
Slimming Tea Market
Tea
Global Fruit Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Floral Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Africa Ready to Drink Tea Market
Tea
Tea Subscription Market
Tea
Black Tea Base Bubble Tea Market
Tea
Nitro Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Edible Tea Market
Tea
Global Catechin Market
Tea
Single Origin Tea Market
Tea
Tea Packaging Market
Tea
Fermented Tea Market