
 Herbal Tea Market | 2026-2036
Herbal Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Tea Market Intelligence
The European Union's stringent regulations on novel foods and botanical health claims are hardening the cost-of-entry calculus for new market entrants. Established players like Unilever leverage extensive global supply chains to manage ingredient sourcing and compliance costs effectively. Associated British Foods, via its Twinings brand, sustains a premium position through its long-standing brand heritage and quality assurance. Meanwhile, The Hain Celestial Group competes by specializing in certified organic and non-GMO product lines that appeal to health-conscious consumers.
Herbal tea, technically a tisane, is an infusion or decoction of herbs, spices, flowers, or other plant material in hot water. Unlike true teas, it contains no leaves from the Camellia sinensis plant. Its primary commercial purpose is to provide flavor and perceived wellness benefits without the caffeine found in traditional teas. Chamomile and Peppermint blends continue to lead in volume, driven by their established use for relaxation and as a digestion aid. Formulations with ingredients like ginger and hibiscus are gaining share, aligning with consumer demand for products supporting immunity and detoxification.
Regulatory frameworks from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern permissible health claims and ingredient safety. In parallel, national standards, such as those set by India's FSSAI, dictate labeling and purity requirements, shaping market access. Producers must now decide whether to pursue costly clinical validation for specific functional benefits or to build lifestyle brands centered on general wellness and flavor exploration.
Market Dynamics
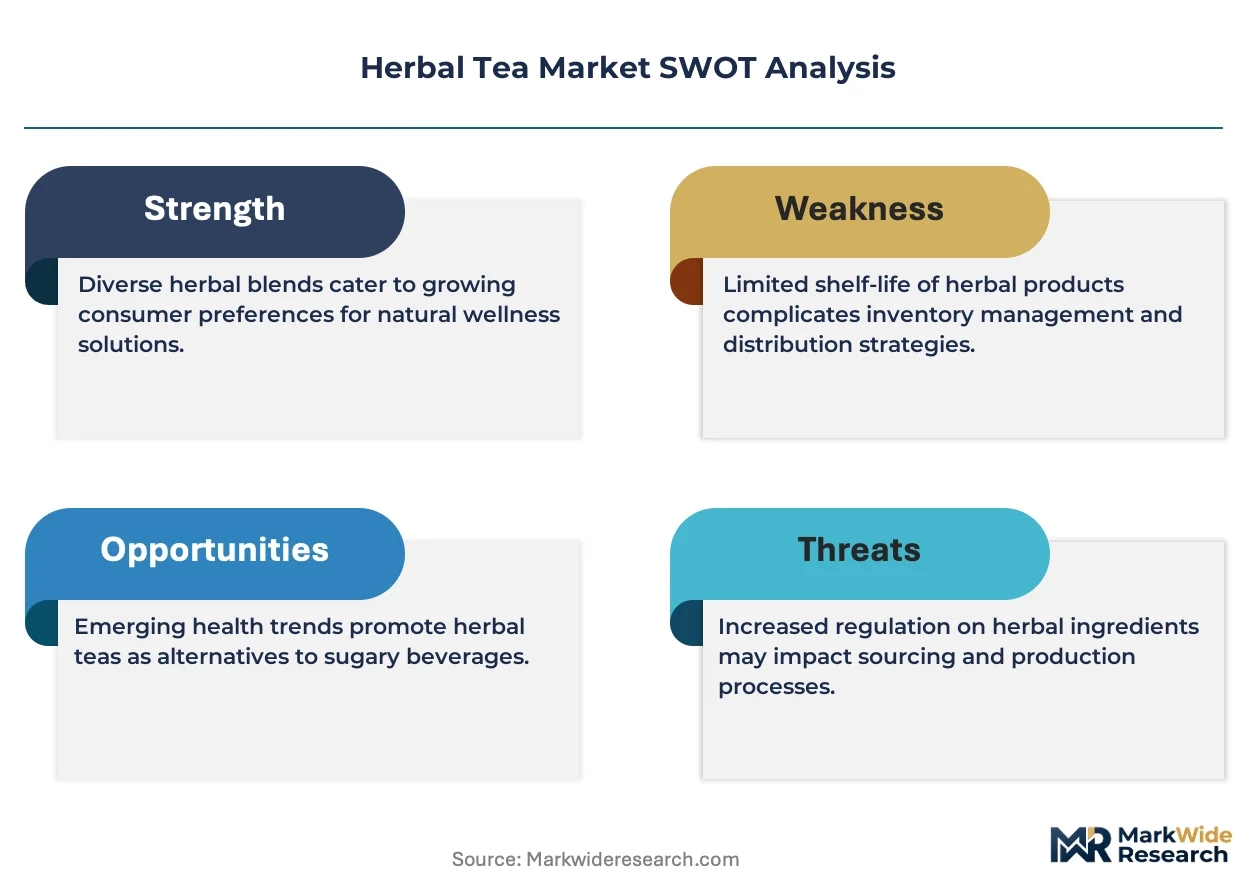
The central structural force shaping the herbal tea market is the collision between traditional ethnobotanical wellness narratives and the rigorous, evidence-based demands of modern food safety and health claim regulations from bodies like the FDA and EFSA.
Growth Catalysts
- Functional Wellness Integration:The incorporation of specific herbal teas, such as ginger for immunity or chamomile for stress, into corporate wellness programs and preventative health plans is creating a sustained, institutional demand channel beyond retail.
- Organic Certification Trust:Stricter enforcement and consumer recognition of organic standards, including the USDA Organic seal and the EU organic logo, are driving purchasing decisions and allowing certified products to command a price premium.
- Modernized Traditional Medicine:In China, the fusion of Traditional Chinese Medicine (TCM) principles with contemporary consumer preferences for convenient, well-packaged goods is creating a massive, concentrated market for functional herbal infusions.
Market Restraints
- Regulatory Friction on Claims:The European Food Safety Authority's (EFSA) stringent requirements for scientific substantiation of botanical health claims make it costly and difficult for brands to market products based on specific functional benefits in the EU.
- Input Cost Volatility:Climate-induced disruptions to agricultural yields for key botanicals like peppermint and chamomile in primary growing regions are creating significant raw material price instability and supply chain risks for manufacturers.
- Functional Beverage Substitution:The market faces intense competition from a widening array of functional beverages, including kombucha, fortified seltzers, and mushroom-based drinks, that target the same health-conscious consumer base.
Strategic Opportunities
- Ready-to-Drink (RTD) Formats:Developing and marketing cold-brew and RTD herbal infusions offers a significant opportunity to capture the convenience-driven consumer segment and expand presence in channels like grab-and-go coolers and cafes.
- Botanical Exploration in New Geographies:Markets in Latin America, particularly Brazil, possess a rich biodiversity of native plants that remain commercially untapped, offering white space for new flavor profiles and functional ingredients pending regulatory approval from bodies like ANVISA.
- Personalized Subscription Models:Leveraging e-commerce platforms to offer personalized herbal tea subscriptions based on consumer wellness goals, as identified through online quizzes, can build brand loyalty and generate recurring revenue streams.
Industry Challenges
- Fragmented Regulatory Compliance:Manufacturers face significant operational complexity in aligning product formulations and labeling to meet disparate and often conflicting purity and claims standards set by national bodies like the US FDA and India's FSSAI.
- Clinical Validation Expense:The high cost and long timelines associated with conducting robust clinical trials to validate specific health benefits pose a substantial barrier to entry, particularly for smaller brands aiming to compete on functional claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Tea Market |
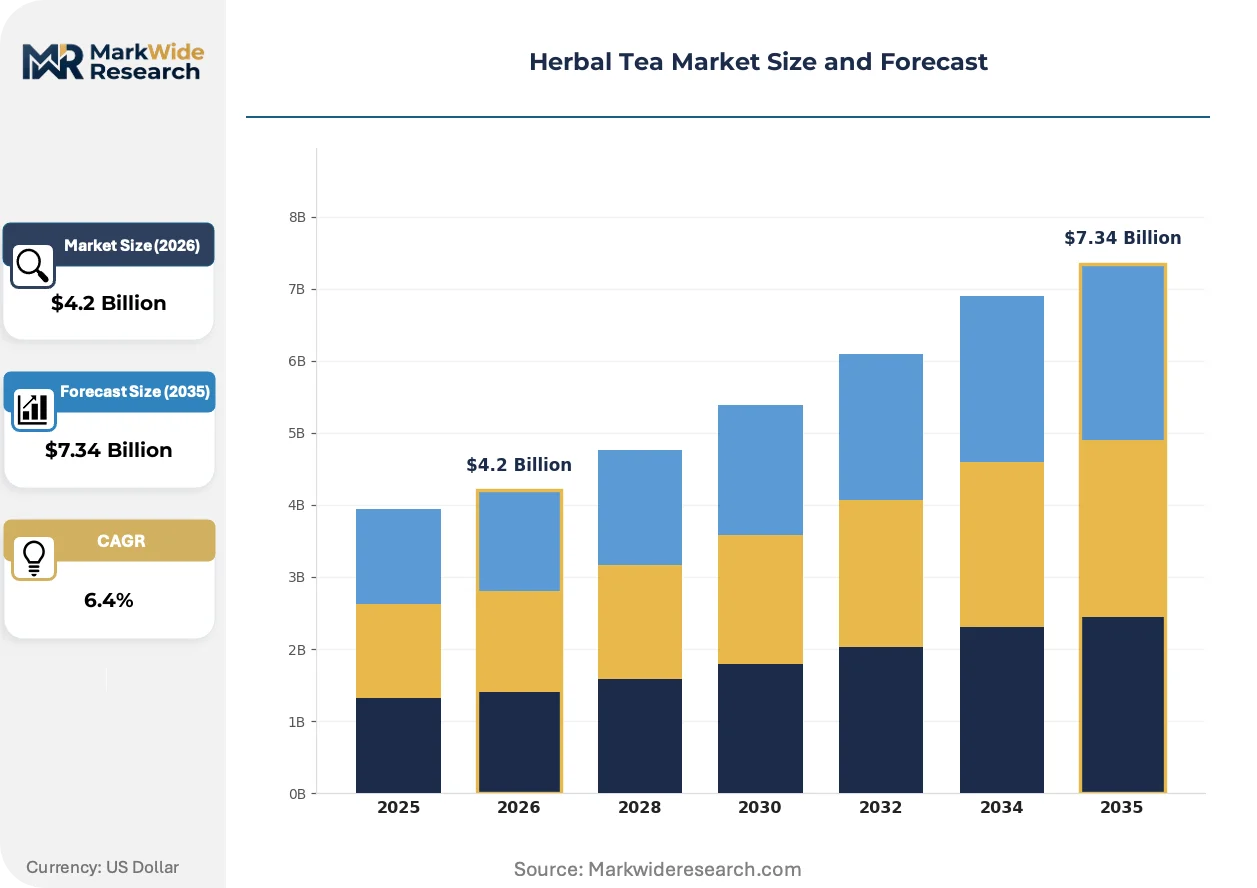
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chamomile, Peppermint, Rooibos, Hibiscus, Lemongrass, Ginger Packaging Type: Tea Bags, Loose Leaf, Sachets, Pyramid Bags, Tin Cans, Glass Jars Application: Relaxation, Digestion Aid, Immunity Boost, Detoxification, Sleep Enhancement, Stress Relief End User: Wellness Centers, Organic Stores, Specialty Cafés, Spas, Tea Retailers, E-commerce Platforms |
| Companies Covered | Associated British Foods, Bigelow Tea Company, Hain Celestial Group, Twinings, Pukka Herbs, Tata Consumer Products, Organic India, Dilmah Ceylon Tea Company, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Tea Market Strategic Shifts & Innovations
The herbal tea market's evolution is defined by a pivot from generic wellness and flavor toward verifiable product authenticity and personalized functional benefits. This shift is driven by technological advancements in supply chain transparency and new models for consumer engagement.
Traceability technologies like blockchain provide immutable, farm-to-cup verification for botanical ingredients. Premium brands and ethically-minded consumer segments are adopting this to guarantee product origin, purity, and organic certification status. This level of transparency is electrifying consumer trust in high-value categories, such as single-origin rooibos or Manuka-infused blends, validating their premium positioning.
The European Union’s Novel Foods Regulation mandates stringent pre-market safety assessments for botanicals lacking a significant history of consumption within the EU prior to 1997. This rule slows the introduction of innovative ingredients from biodiverse regions in Africa and South America. The functional ingredients segment is most impacted, compelling formulators to either fund expensive EFSA safety dossiers or utilize a more limited palette of established herbs.
A significant behavioral change is the consumer shift toward subscription-based, direct-to-consumer (DTC) purchasing for curated herbal tea assortments. This model bypasses traditional retail gatekeepers, enabling brands to foster direct relationships and gather valuable data on flavor preferences and wellness interests. This trend is most advanced in North American and Western European markets, where digital-native brands are gaining traction.
Herbal Tea Market Segmentation
Understanding the herbal tea market's segmentation is critical for tailoring product development, marketing, and distribution. This granular view reveals where consumer preferences consolidate and which attributes drive premium pricing or volume sales. Analyzing these segments helps stakeholders identify niches and emerging growth vectors.
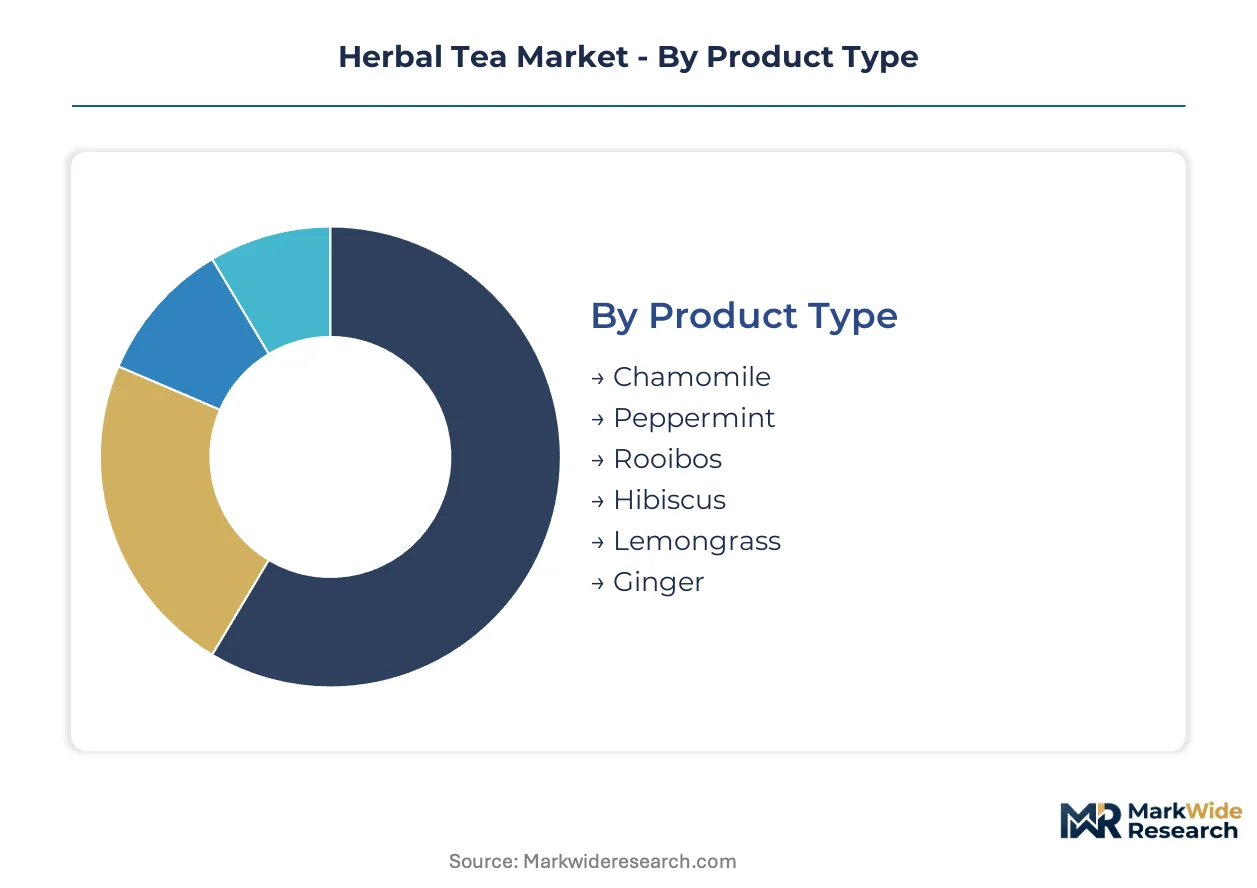
Product Type:
The herbal tea market balances between standardized, widely recognized blends and specialized, custom botanical formulations catering to diverse wellness needs.
- Chamomile:Derived from dried chamomile flowers, this infusion is valued for its mild flavor and calming properties. Demand concentrates in Western Europe for natural sleep aids and stress reduction.
- Peppermint:Prepared from peppermint leaves, this tea offers a refreshing taste with recognized digestive benefits. Its established use drives consistent volume sales across North American and European retail channels.
- Rooibos:Caffeine-free tea from the South African red bush, known for earthy flavor and antioxidants.
- Hibiscus:Tart, cranberry-like flavor and vibrant red color, often consumed for potential cardiovascular benefits.
- Lemongrass:Aromatic grass infusion with a refreshing, citrusy flavor, utilized for purported detoxifying qualities.
- Ginger:Pungent, spicy root infusion recognized for anti-inflammatory properties and immune function support.
Most installed capacity flows through Chamomile. Expansion is steepest in Ginger.
Packaging Type:
Consumer preferences for herbal tea packaging are highly influenced by convenience, perceived quality, and environmental considerations, segmenting the market by customer type.
- Tea Bags:Convenient, pre-portioned sachets with finely cut ingredients, offering ease of preparation and portability. Demand remains high in fast-paced urban environments.
- Loose Leaf:Whole or coarsely cut botanicals, allowing greater flavor complexity and perceived quality by tea enthusiasts. Strongest among discerning consumers prioritizing ritualistic brewing.
- Sachets:Porous paper or biodegradable materials form individual servings, balancing convenience with a premium feel.
- Pyramid Bags:Three-dimensional bags allowing botanicals to unfurl fully, enhancing flavor extraction and visual appeal for premium segments.
- Tin Cans:Durable, decorative, and protective against light and air, preserving freshness for bulk or specialty loose leaf teas.
- Glass Jars:Transparent and reusable, showcasing botanical ingredients, appealing to consumers prioritizing aesthetic presentation and sustainability.
The largest volume sales are attributable to Tea Bags. The fastest expansion is observed in Pyramid Bags, driven by a premium positioning.
Application:
The market for herbal teas is increasingly defined by specific health outcomes, with consumers seeking targeted functional benefits beyond general wellness.
- Immunity Boost:Formulations supporting the body's natural defenses, often incorporating ginger, echinacea, or elderberry. Significant demand in regions with heightened health consciousness.
- Detoxification:Teas aiding the body's natural cleansing processes, typically featuring dandelion, nettle, or milk thistle. Urban consumers frequently seek these for perceived internal purification.
- Relaxation:Herbal blends like chamomile and lavender, consumed for calming effects, supporting mental tranquility.
- Digestion Aid:Teas such as peppermint and fennel, traditionally used to soothe digestive discomfort and promote gut health.
- Sleep Enhancement:Specific blends, including valerian root or passionflower, marketed to improve sleep quality.
- Stress Relief:Herbal infusions targeting anxiety reduction, frequently featuring lemon balm or ashwagandha.
Immunity Boost applications command substantial consumer interest. Detoxification applications are demonstrating accelerating adoption rates.
End User:
The distribution landscape for herbal tea varies significantly, reflecting diverse consumer access points and the maturity of different retail and service channels.
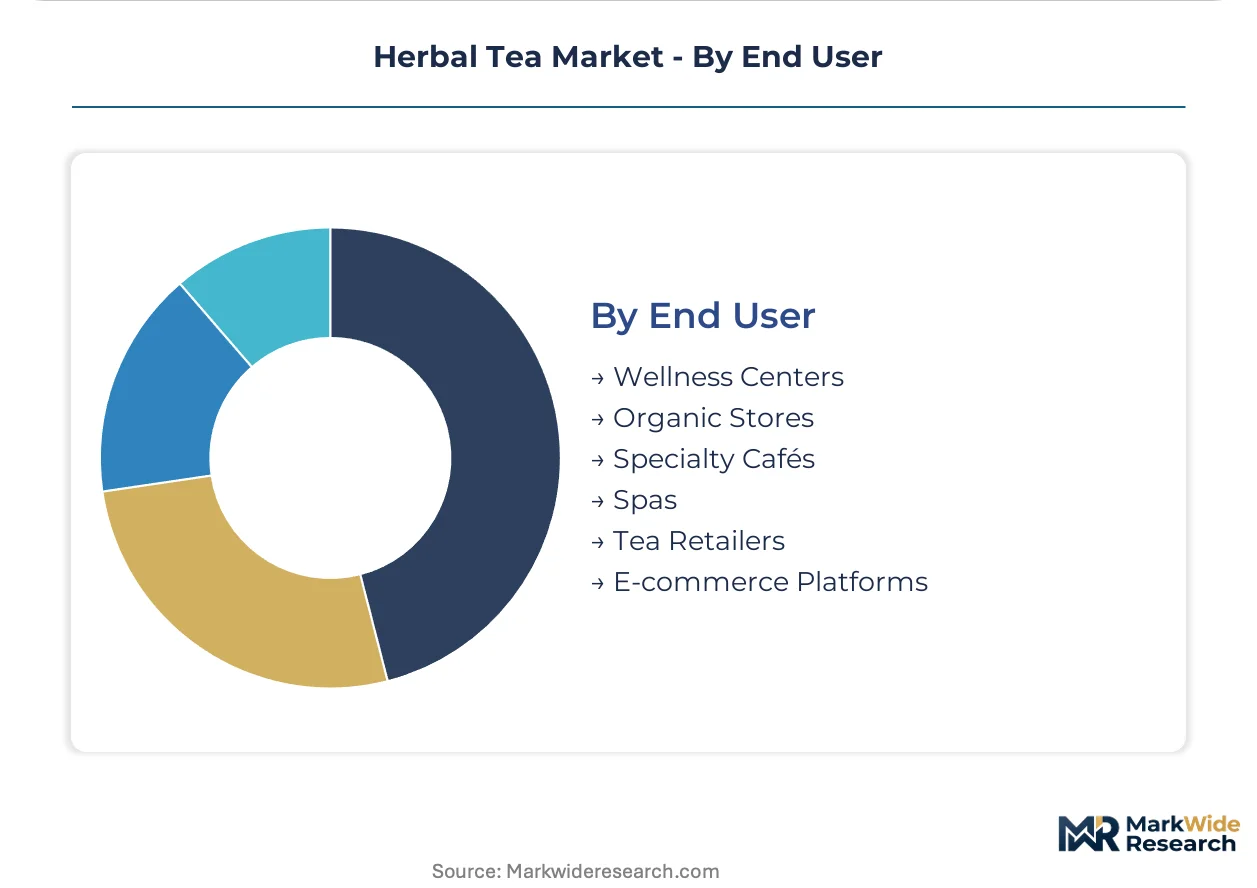
- Wellness Centers:These establishments integrate functional herbal teas into holistic health programs, offering curated blends for specific outcomes. This segment represents a significant institutional demand channel.
- E-commerce Platforms:Online marketplaces and direct-to-consumer websites facilitate personalized subscriptions and broader access to niche brands. This channel drives growth in North America and Western Europe.
- Organic Stores:Retail outlets specializing in organic and natural products, where certified herbal teas align with core consumer values.
- Specialty Cafés:Establishments focusing on high-quality beverages, often featuring premium herbal tea selections to complement their menu.
- Spas:Luxury wellness facilities incorporating herbal teas as part of their relaxation and detoxification treatments.
- Tea Retailers:Dedicated stores offering a wide assortment of teas, providing expert advice and a specialized shopping experience.
Wellness Centers represent a foundational end-user segment. E-commerce Platforms are experiencing the most dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Herbal tea consumption originated in ancient civilizations, evolving from traditional remedies to a global wellness market. China and India historically cultivated diverse botanicals for medicinal infusions. This deep cultural heritage now underpins significant modern market expansion.
China
Demand for functional herbal infusions is massive, integrating Traditional Chinese Medicine (TCM) principles with modern consumer preferences. China's NMPA oversees the safety and efficacy of traditional herbal products, influencing market access. Major cities like Shanghai and Beijing drive innovation in convenient, well-packaged functional teas.
United States
Health-conscious consumers drive demand for certified organic and non-GMO herbal teas, focusing on specific wellness benefits. The USDA Organic seal provides critical consumer trust and commands a price premium for products. Silicon Valley and other tech hubs show high adoption of personalized subscription models for curated wellness blends.
Germany
Wellness centers integrate functional teas into health programs, while consumers prioritize organic certification for perceived purity. Germany's national food safety authority enforces stringent standards for botanical ingredients and health claims. Munich and Berlin demonstrate strong consumer interest in premium loose-leaf teas and sustainable packaging.
India
Traditional Ayurvedic practices fuel demand for herbal infusions supporting immunity and detoxification, aligning with national health priorities. India's FSSAI dictates stringent purity and labeling requirements for herbal tea products, shaping market entry. Bengaluru and Delhi are emerging as innovation centers for modern Ayurvedic tea formulations.
Brazil
Untapped biodiversity offers significant potential for new flavor profiles and functional ingredients, appealing to a growing health-aware population. Brazil's ANVISA closely regulates novel foods and botanical health claims, influencing product development. The Amazon region presents a rich source of native plants for future commercialization, pending regulatory approvals.
Herbal Tea Market Key Industry Players
The competitive structure tilts toward established food and beverage conglomerates leveraging extensive global supply chains. Several strategic archetypes exist, including diversified global players, organic specialization brands, and niche functional tea providers. These archetypes compete across various price points and distribution channels. Companies pursue portfolio diversification and geographic expansion to capture new consumer segments, often through strategic partnerships.
Among the larger, diversified players, Associated British Foods, via its Twinings brand, occupies a position of extensive global reach, leveraging established brand heritage and quality assurance. Unilever similarly anchors a broad market presence through its widespread distribution networks and diverse product offerings. The Hain Celestial Group exemplifies brands specializing in certified organic and non-GMO product lines, appealing directly to health-conscious consumer segments. These companies represent distinct strategies within the herbal tea market, from premium traditional blends to specialized health-oriented formulations.
| Leading Market Players |
|---|
| Associated British Foods |
| Bigelow Tea Company |
| Hain Celestial Group |
| Twinings |
| Pukka Herbs |
| Tata Consumer Products |
| Organic India |
| Dilmah Ceylon Tea Company |
| Unilever |
| Others |
Cost & Logistics Intelligence
Skilled agricultural labor in primary botanical growing regions like China and India underpins the cost structure of herbal teas, influencing the pricing tiers across premium and volume segments. This dynamic interaction defines market accessibility and profitability.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels characterizes the herbal tea market. Certification levels like the USDA Organic seal and established brand heritage drive significant price differentiation. Pricing softness reflects intense competition from other functional beverages like kombucha. Health-conscious consumers exhibit lower price sensitivity for certified organic blends, while general retail buyers prioritize affordability.
Supply Chain Analysis
Reverse logistics for herbal tea packaging, though minimal, focuses on recycling initiatives for tin cans and glass jars. Raw botanical material supply concentrates heavily in China and India, with specific botanicals like rooibos sourced from South Africa. Key dependencies include chamomile, peppermint, and ginger, making climate-induced disruptions to agricultural yields a significant structural risk. Distribution runs through a fragmented network of e-commerce platforms, organic stores, and wellness centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The herbal tea market functions as a late-cycle quality story, shifting from basic wellness claims to verifiable product authenticity. Consumer demand increasingly favors premium specifications like blockchain-traceable ingredients and organic certifications.
For Market Incumbents:Extend existing global supply chain advantages to manage ingredient sourcing and compliance costs effectively. Invest in costly clinical validation for specific functional benefits to differentiate against generic offerings. This mitigates the threat of stringent EFSA regulations on botanical health claims. Reinforce brand loyalty through consistent quality assurance and certification investment.
For New Entrants and Emerging Players:Begin with developing ready-to-drink (RTD) herbal infusions to capture convenience-driven consumer segments. Target personalized subscription models via e-commerce platforms, leveraging online quizzes for curated assortments. This approach bypasses traditional retail gatekeepers, offering a penetrable segment for digital-native brands. Focus on novel flavor profiles from under-explored botanicals in new geographies.
For Investors and Strategic Acquirers:Valuations sit cheapest among fragmented regional players lacking scale or robust certification. Long-term viability remains strong for brands demonstrating verifiable functional claims and sustainable sourcing practices. Target acquisition candidates include niche functional tea providers specializing in certified organic and non-GMO product lines. Monitor consumer adoption rates of blockchain-traceable ingredients as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension | Introduce new functional blends with immunity or detoxification benefits to capture evolving consumer needs. |
| Direct-to-Consumer Launch | Establish e-commerce platforms for personalized subscription services to foster direct customer relationships. |
| Premium Tier Introduction | Market single-origin botanicals with blockchain traceability to validate product origin and purity for discerning buyers. |
| Distribution Channel Expansion | Partner with corporate wellness programs and specialty cafes to access institutional demand channels. |
| Sustainability Repositioning | Obtain stricter organic certifications and eco-friendly packaging to align with consumer environmental values. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market view. Primary interviews engaged brand managers, regulatory affairs leads, wellness center operators, and e-commerce platform managers. Secondary validation utilized USDA Organic certification databases, EFSA regulatory filings, and trade association reports. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
The forecast window was anchored to comparable historical periods, establishing baseline growth rates for herbal tea consumption. This analytical framework modeled segmentation across product type, packaging type, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Key inputs included consumer wellness spending and the pace of novel food approvals.
Several conditions sit outside the modeled scope, including unforeseen geopolitical instability or rapid shifts in agricultural policy. Forecasts reflect assumptions regarding current regulatory frameworks and consumer behavior. Practitioners should monitor extreme weather events impacting botanical yields for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Single Origin Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
New Style Tea Drink Market
Tea
Tea Concentrate Market
Tea
Probiotic Tea Market
Tea
Matcha Tea Market
Tea
North America Tea Market
Tea
Kombucha Tea Market
Tea
Green Tea Bag Market
Tea
Tea Pitchers Market
Tea
Nitro Tea Market
Tea
Moringa Tea Market
Tea
Bottled Milk Tea Market
Tea
Oolong Tea Market
Tea
Matcha Products Market
Tea
White Tea Extract Market